
 Classic Car Restoration and Restomod Services Market | 2026-2036
Classic Car Restoration and Restomod Services Market Size, Share, and Industry Trends Forecast 2026-2036
Classic Car Restoration and Restomod Services Market Insights
Buyer concentration among ultra-high-net-worth collectors is repositioning service priorities across the restoration sector. Singer Vehicle Design leverages obsessive manufacturing scale in bespoke Porsche commissions to sustain pricing power at the apex tier. Velocity Restorations anchors its competitive position through geographic dominance in Florida-based classic truck restorations. Ringbrothers differentiates via technology leadership in carbon-fiber body fabrication for American muscle platforms.
Classic car restoration and restomod services encompass the comprehensive rebuild, modernization, and aesthetic reengineering of vehicles typically manufactured twenty-five or more years prior, integrating contemporary powertrains, suspension geometries, and infotainment architectures while preserving period-correct exterior proportions. Full restoration commands the largest absolute revenue pool due to labor intensity and parts scarcity premiums, though custom fabrication represents the fastest-expanding margin segment as clients demand one-off chassis modifications and coachbuilt body panels. Vintage European models attract disproportionate investment flow from established collector networks, while exotic collectibles occupy the highest per-unit service value tier.
EPA emissions certification requirements for engine-swapped vehicles and NHTSA safety equipment standards govern domestic restomod legality, compelling workshops to maintain regulatory compliance expertise as a core competency. ISO 9001 quality management protocols increasingly influence supplier qualification for specialist parts manufacturers serving the restoration ecosystem. Stakeholders must monitor evolving electrification compliance pathways as battery-electric powertrain conversions attract both regulatory scrutiny and collector capital allocation.
Market Dynamics
Ultra-high-net-worth collector concentration is restructuring service priorities across the restoration sector, compressing project timelines and elevating bespoke fabrication demands while workshop capacity constraints intensify pricing power at the apex tier.
Growth Catalysts
- EPA Emissions Pathways:The EPA's evolving compliance frameworks for modified vehicles are creating regulatory clarity that accelerates restomod project approvals and expands addressable vehicle pools for engine-swapped builds.
- Carbon-Fiber Fabrication:Advanced composite manufacturing techniques are reducing coachbuilt body panel costs and enabling structural weight reductions that enhance performance metrics for collector-grade commissions.
- Southern California Cluster Effects:Critical mass in specialist workshop density, parts sourcing infrastructure, and fabrication expertise in Los Angeles and Orange County counties is attracting cross-border project flows from international collectors.
Market Restraints
- Period-Correct Parts Scarcity:Discontinuation of OEM tooling for pre-1990 European and American drivetrain components is inflating input costs and extending project timelines for concours-grade restorations.
- Specialist Labor Concentration:Master metalworkers, coachbuilding artisans, and period-correct upholstery specialists cluster in Germany, Italy, and the United Kingdom, creating geographic supply bottlenecks for North American workshops.
- NHTSA Safety Equipment Mandates:Federal Motor Vehicle Safety Standards compliance requirements for modified braking and lighting systems impose certification friction that limits restomod eligibility for road-legal registration in certain states.
Strategic Opportunities
- Battery-Electric Powertrain Conversions:Electrification compliance pathways under development by CARB and EPA staff are opening regulatory space for zero-emission restomods that preserve vintage aesthetics while eliminating emissions liability.
- ISO 9001 Supplier Qualification:Quality management certification adoption by specialist parts manufacturers is creating tiered supply base differentiation that rewards workshops with documented procurement protocols.
- Concours Event Circuit Expansion:Pebble Beach, Villa d'Este, and Goodwood Revival are amplifying trophy value for commissioned builds, driving demand for show-quality finishes and documented provenance restoration.
Industry Challenges
- Master Craftsman Succession:Knowledge transfer from aging coachbuilding and metal-forming specialists to apprentice cohorts faces generational friction, compressing available labor hours for hand-formed aluminum bodywork.
- Multi-Jurisdictional Compliance Documentation:Engine-swap projects require simultaneous satisfaction of EPA emissions certification, state DMV registration protocols, and insurance underwriting requirements, extending administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Classic Car Restoration and Restomod Services Market |
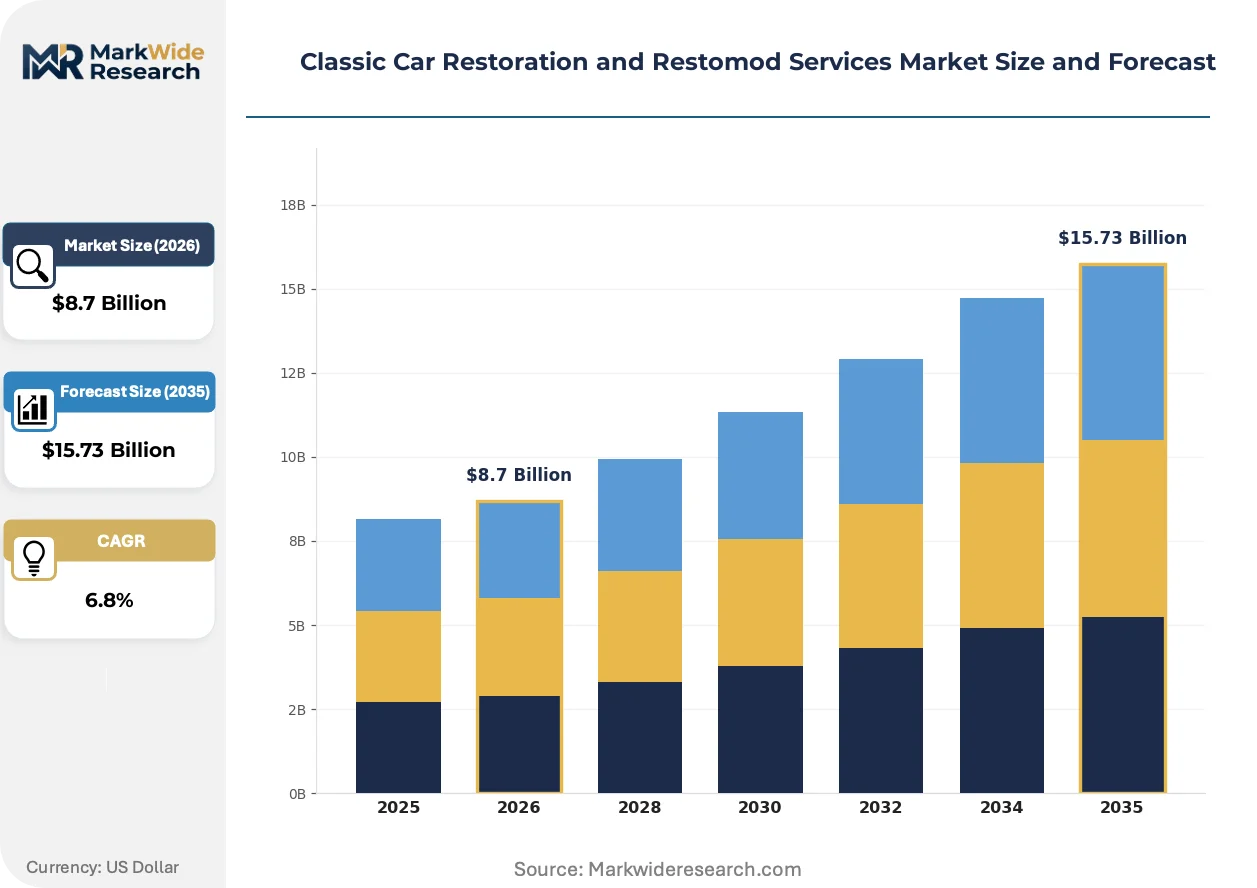
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
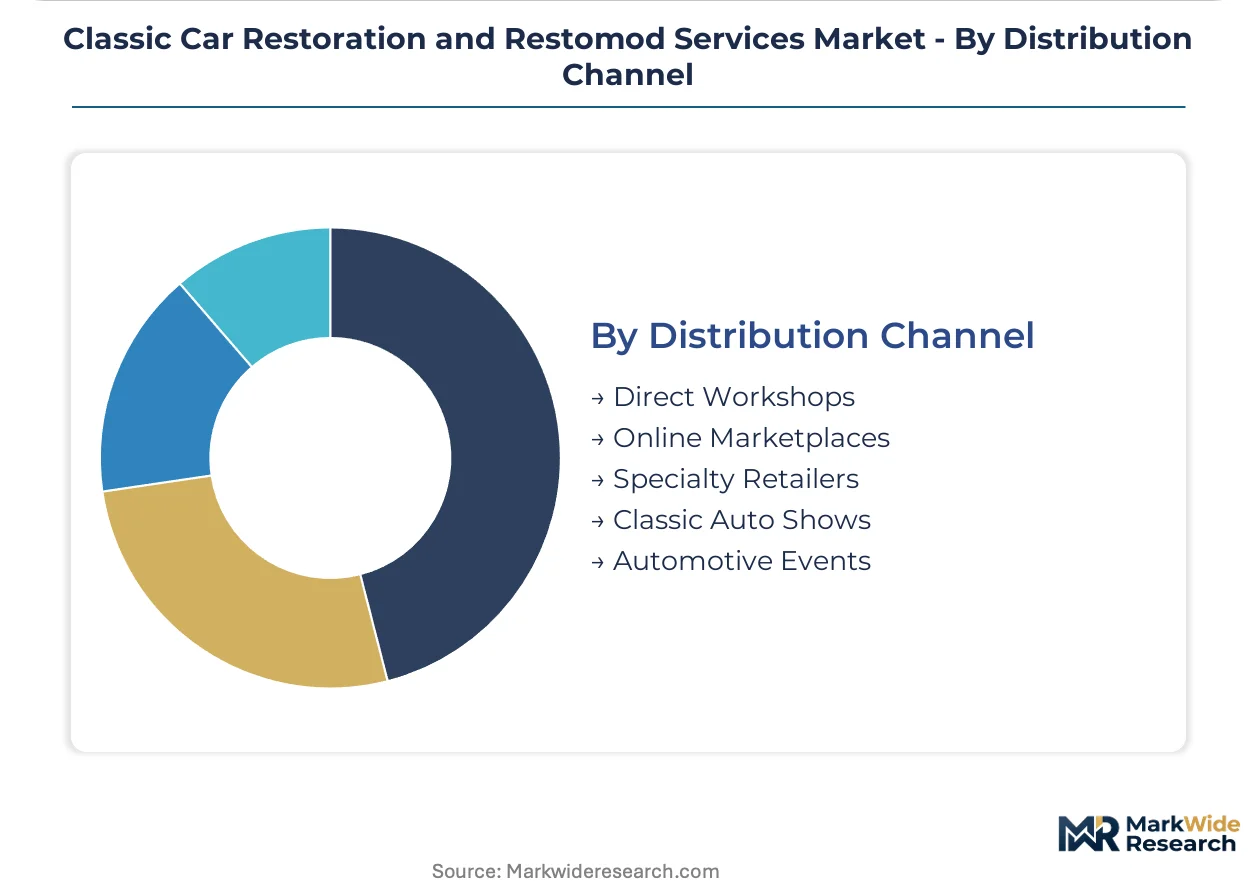
| Segmentation | Service Type: Full Restoration, Mechanical Repair, Custom Fabrication, Paint & Bodywork, Upholstery Refurbishment Vehicle Category: Classic Muscle Cars, Vintage European Models, Antique Trucks, Custom Hot Rods, Exotic Collectibles Customer Profile: Private Collectors, Specialty Garages, Restoration Enthusiasts, Classic Auto Dealers, Specialty Clubs Distribution Channel: Direct Workshops, Online Marketplaces, Specialty Retailers, Classic Auto Shows, Automotive Events |
| Companies Covered | Singer Vehicle Design, Velocity Restorations, Everrati Automotive, Ringbrothers, Gateway Bronco, Revology Cars, Kindig-it Design, ECD Automotive Design, Canepa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Classic Car Restoration and Restomod Services Market Trends and Innovations
Digital design-to-fabrication pipelines are compressing development cycles for one-off coachbuilt components while regulatory pressure on powertrain emissions accelerates technology substitution across the restoration value chain.
Additive manufacturing is converging with traditional coachbuilding techniques as titanium and inconel 3D-printed intake manifolds, exhaust headers, and suspension uprights enter bespoke Porsche and Ferrari restomod specifications. Collector clients commissioning seven-figure builds now expect generative-design components that reduce weight while maintaining period-correct exterior proportions. This technology convergence is compressing the fabrication timeline for one-off chassis modifications from eighteen months to under eight months in leading Southern California workshops.
California Air Resources Board executive orders for aftermarket powertrain conversions are establishing template compliance pathways that other state regulators are adopting, reducing regulatory fragmentation for engine-swapped builds. The industrial consequence is standardized emissions testing protocols that lower certification costs for workshops serving multi-state client bases. Muscle car and American truck restomod segments are most affected, with Florida and Texas workshops rapidly building CARB-compliance capabilities to capture cross-border demand.
Collector procurement preferences are migrating from transaction-based restoration contracts toward milestone-gated engagements with embedded post-delivery service commitments. High-net-worth clients now demand two-year mechanical warranties and concours-prep retainers as standard inclusions, displacing traditional fixed-bid project structures. This behavioral shift is most visible in the European exotic collectible segment, where Swiss and Monaco-based collectors are negotiating multi-year service attachments before commissioning seven-figure builds.
Classic Car Restoration and Restomod Services Market Segmentation

Service differentiation in classic car restoration hinges on labor intensity, parts scarcity premiums, and regulatory compliance complexity. Collector investment patterns and workshop capacity constraints reshape which segments capture margin expansion versus volume concentration.
Service Type:
Project scope and labor specialization determine buyer willingness to pay premium rates and tolerate extended timelines.
- Full Restoration:Comprehensive ground-up rebuilds integrating period-correct components with concours-grade finishes command the largest absolute revenue pool. Demand concentrates among ultra-high-net-worth collectors commissioning seven-figure European exotic builds where documented provenance restoration amplifies trophy value at Pebble Beach and Villa d'Este.
- Custom Fabrication:One-off chassis modifications, coachbuilt body panels, and carbon-fiber structural components represent the steepest expansion trajectory. Southern California workshops leverage digital design-to-fabrication pipelines to compress development cycles from eighteen months to under eight months for bespoke Porsche and Ferrari commissions.
- Mechanical Repair:Drivetrain rebuilds and suspension geometry corrections address functional restoration needs without full aesthetic reengineering.
- Paint & Bodywork:Show-quality finishes and rust remediation services support both standalone projects and full restoration phases.
- Upholstery Refurbishment:Period-correct leatherwork and interior trim restoration require master artisans clustered in Germany, Italy, and the United Kingdom.
Volume sits with Full Restoration; growth tilts toward Custom Fabrication.
Vehicle Category:
Collector capital allocation and regulatory treatment differentiate addressable vehicle pools across restomod eligibility and parts availability.
- Vintage European Models:Porsche, Ferrari, and Jaguar platforms attract disproportionate investment flow from established collector networks in Switzerland and Monaco. EPA emissions certification requirements for engine-swapped vehicles create compliance friction that favors workshops with documented regulatory expertise.
- Classic Muscle Cars:Ford Mustang, Chevrolet Camaro, and Dodge Challenger restomods dominate American workshop capacity. CARB executive orders for aftermarket powertrain conversions are establishing template compliance pathways that Florida and Texas workshops rapidly adopt to capture cross-border demand.
- Exotic Collectibles:Limited-production marques occupy the highest per-unit service value tier with multi-year project horizons.
- Antique Trucks:Ford F-Series and Chevrolet C/K platform restorations anchor Velocity Restorations' geographic dominance in Florida-based classic truck specialization.
- Custom Hot Rods:Post-war American street rod builds emphasize aesthetic personalization over period-correct authenticity.
Revenue concentrates in Vintage European Models; margin expansion favors Exotic Collectibles.
Customer Profile:
Procurement sophistication and post-delivery service expectations separate transaction-based engagements from milestone-gated relationships with embedded warranties.
- Private Collectors:High-net-worth individuals diversifying tangible asset portfolios now demand two-year mechanical warranties and concours-prep retainers as standard inclusions. Swiss and Monaco-based collectors negotiate multi-year service attachments before commissioning builds.
- Specialty Garages:Workshop-to-workshop subcontracting relationships concentrate in Southern California's specialist cluster where fabrication expertise and parts sourcing infrastructure achieve critical mass.
- Restoration Enthusiasts:Owner-involved projects prioritize cost management over concierge service levels.
- Classic Auto Dealers:Inventory preparation and consignment restoration services support resale value optimization.
- Specialty Clubs:Marque-specific member networks aggregate demand for group-purchased restoration services and parts sourcing.
Absolute spending power resides with Private Collectors; contract innovation originates with Specialty Garages.
Distribution Channel:
Project discovery and workshop selection increasingly migrate from geographic proximity to digital curation of portfolio credentials.
- Direct Workshops:Established relationships with master craftsmen in Germany, Italy, and the United Kingdom command premium positioning. Los Angeles and Orange County counties attract cross-border project flows from international collectors through critical mass in specialist workshop density.
- Online Marketplaces:Digital platforms for parts sourcing and workshop discovery reduce search friction for restoration enthusiasts seeking specialty components.
- Specialty Retailers:Bricks-and-mortar parts suppliers maintain relevance for urgent component needs and technical consultation.
- Classic Auto Shows:Pebble Beach, Goodwood Revival, and Amelia Island concours events serve as commissioning venues where trophy value drives show-quality finish demand.
- Automotive Events:Auctions and track days facilitate collector networking and workshop relationship initiation.
Project origination still flows through Direct Workshops; digital discovery is gaining share fastest through Online Marketplaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist aluminum stockpiles in Birmingham and Solihull anchor European restoration capacity. Southern California's titanium and carbon-fiber supply chains feed North American bespoke fabrication. Japanese steel alloy distributors in Aichi Prefecture service the Nagoya coachbuilding cluster.
United States
Ultra-high-net-worth collectors in Florida and California commission seven-figure restomod builds. EPA emissions certification requirements for engine-swapped vehicles create compliance friction that favors workshops with documented regulatory expertise. Los Angeles and Orange County counties attract cross-border project flows from international collectors through critical mass in specialist workshop density.
Germany
Master metalworkers and coachbuilding artisans cluster in Stuttgart and Munich serving Porsche and Mercedes-Benz heritage divisions. KBA type-approval standards for modified vehicles govern road-legal registration of engine-swapped classics. Bavaria's restoration workshops leverage proximity to OEM parts archives and factory-trained technician networks.
United Kingdom
Period-correct upholstery specialists in London and the Midlands command premium positioning for concours-grade interior refurbishment. DVLA registration protocols for substantially altered vehicles impose documentation requirements that extend project timelines. Buckinghamshire and Oxfordshire workshop concentrations service Goodwood Revival and Salon Privé commissioning cycles.
Italy
Ferrari and Lamborghini heritage restoration concentrates in Modena and Maranello where factory-authorized technicians maintain proprietary tooling. ANFIA technical standards for modified vehicles influence insurer underwriting requirements for collector-grade builds. Emilia-Romagna's coachbuilding tradition sustains hand-formed aluminum bodywork capabilities for limited-production commissions.
Japan
JIS-certified restoration workshops in Aichi and Kanagawa prefectures specialize in domestic vintage sports car preservation. METI guidelines for classic vehicle emissions exemptions provide regulatory clarity for Showa-era engine retention. Nagoya's titanium fabrication suppliers support lightweight chassis modifications for circuit-prepared restomods.
Classic Car Restoration and Restomod Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification conversion and carbon-fiber fabrication as differentiation vectors. The restoration sector exhibits tiered concentration with boutique ateliers commanding premium pricing for bespoke commissions while regional specialists capture volume-driven mechanical rebuilds. Three archetypes dominate: heritage-certified workshops with OEM affiliations, technology-forward fabricators integrating additive manufacturing, and geographic specialists leveraging cluster effects for parts sourcing efficiency. Competitive moves center on regulatory compliance capability building and multi-year service contract attachments that displace fixed-bid project structures.
Within the bespoke commission tier, Singer Vehicle Design and Ringbrothers exemplify divergent specialization strategies. Velocity Restorations anchors geographic concentration in Florida-based classic truck restoration. Everrati Automotive occupies a position representing the electrification conversion archetype. These three entities collectively illustrate how workshop differentiation vectors—manufacturing scale, regional dominance, and technology substitution—structure competitive positioning across the restoration value chain.
| Leading Market Players |
|---|
| Singer Vehicle Design |
| Velocity Restorations |
| Everrati Automotive |
| Ringbrothers |
| Gateway Bronco |
| Revology Cars |
| Kindig-it Design |
| ECD Automotive Design |
| Canepa |
| Others |
Pricing and Supply Chain Analysis
Coachbuilding-grade aluminum stockpiles in Birmingham and Solihull flow through three-tier pricing structures across premium, standard, and economy levels, with master metalworker labor hours in Stuttgart and Modena anchoring cost escalation at the apex tier while carbon-fiber composite inputs from Southern California workshops compress fabrication timelines for mid-market restomods.
Pricing Analysis
Warranty and service-bundling inclusions now separate premium from standard tiers, with Swiss and Monaco-based collectors demanding two-year mechanical warranties and concours-prep retainers as standard inclusions before commissioning seven-figure builds. Project-based pricing dominates, with price differentiation hinging on ISO 9001 supplier qualification status and geographic delivery cost to collector hubs. Pricing pressure stems from period-correct parts scarcity inflating input costs for concours-grade European restorations. Restoration enthusiasts exhibit highest price sensitivity, while ultra-high-net-worth private collectors demonstrate inelastic demand for documented provenance restoration.
Supply Chain Analysis
Domestic-content mandates under EPA emissions certification requirements are reshaping powertrain sourcing toward CARB-compliant California suppliers for engine-swapped builds. Supply concentrates in Germany, Italy, and the United Kingdom for master artisans, with titanium and carbon-fiber composite inputs drawn from Southern California fabrication clusters. Single-source vulnerability runs through discontinued OEM tooling for pre-1990 European drivetrain components. Distribution runs through direct workshop relationships anchored by geographic proximity to collector hubs and concours event circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master craftsman succession gaps prop pricing power for heritage-certified workshops, with available labor hours for hand-formed aluminum bodywork compressing as generational knowledge transfer faces friction.
For Market Incumbents: To counter battery-electric conversion entrants like Everrati Automotive, heritage-certified workshops should deepen regulatory compliance expertise as a defensive moat and anchor capacity addition in Southern California's titanium supply chain cluster to capture cross-border project flows from international collectors.
For New Entrants and Emerging Players: Capture white-space in antique truck electrification conversions and carbon-fiber structural fabrication for American muscle platforms, with Florida and Texas offering the most penetrable geography given rapid CARB-compliance capability building among regional specialists. A go-to-market angle targeting specialty garage subcontracting relationships in the Southern California cluster reduces customer acquisition cost.
For Investors and Strategic Acquirers: EPA electrification compliance pathway finalization is the leading indicator that battery-electric restomod legitimacy will accelerate capital allocation toward technology-forward fabricators. Over a multi-year horizon, vertically integrated workshops with in-house additive manufacturing capabilities and documented ISO 9001 procurement protocols represent the preferred acquisition archetype.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Certification Investment | EPA emissions pathway expertise unlocks multi-state addressable market for engine-swapped builds. |
| Carbon-Fiber Fabrication Capacity Expansion | Advanced composite manufacturing reduces coachbuilt body panel costs and structural weight for collector commissions. |
| Master Craftsman Apprenticeship Programs | Knowledge transfer pipelines secure labor hours for hand-formed aluminum bodywork succession. |
| Multi-Year Service Contract Attachments | Concours-prep retainers displace fixed-bid structures and deepen collector wallet capture. |
| Battery-Electric Powertrain Conversion Development | Zero-emission restomods eliminate emissions liability while preserving vintage aesthetic provenance. |
Research Methodology
Independent corroboration across restoration workshop proprietors, marque heritage division executives, specialist parts manufacturers, and collector network intermediaries underwrites the qualitative findings, with secondary validation from EPA regulatory filings, CARB executive order databases, concours event commissioning records, and customs trade data for aluminum and titanium alloy imports. Bottom-up project pipeline analysis triangulates against top-down collector capital allocation estimates.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by service type, vehicle category, customer profile, and geographic workshop cluster. CAGRs derive from regression against collector demographic expansion, regulatory compliance cost curves, and fabrication technology adoption rates. Forecast inputs incorporate master craftsman labor hour availability and carbon-fiber composite cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA electrification pathway finalization and generational succession in European coachbuilding traditions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market