
 Engine Mounting Brackets Market | 2026-2036
Engine Mounting Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Mounting Brackets Market Analysis
The performance gap between premium hydraulic assemblies and commodity rubber mounts is broadening as OEMs specify multi-chamber fluid-filled designs for electric vehicle platforms while budget segments retain conventional elastomeric solutions. Vibracoustic leverages its acoustic engineering heritage to supply tuned damping systems for luxury passenger car programs. ContiTech anchors its position through captive rubber compounding and metal-rubber bonding expertise. Sumitomo Riko differentiates via integrated sensor-ready mount designs that support vehicle health monitoring architectures.
Engine mounting brackets are structural chassis components that secure powertrain assemblies to vehicle subframes while isolating cabin noise and absorbing drivetrain torque reactions, typically fabricated from stamped steel or cast aluminum with bonded elastomeric or fluid-filled damping elements. Hydraulic mounts command premium positioning due to their complex internal valving and tuned frequency response, whereas solid steel variants serve cost-sensitive commercial vehicle applications where durability outweighs refinement. Aluminum material grades are gaining share in passenger car platforms seeking mass reduction, while polyurethane compounds occupy niche aftermarket upgrade segments targeting track-day enthusiasts.
FCC vehicle noise regulations in the United States, ECE R51 noise emission standards across European type-approval regimes, and China's GB 1495 noise limits collectively mandate stricter vibration control, directly elevating specification thresholds for mount damping performance and material longevity. NHTSA crashworthiness requirements further influence bracket fracture behavior and retention integrity under severe impact loading. Stakeholders must monitor how electrification shifts torque pulse characteristics and thermal envelope demands, as these powertrain changes will redefine mount architecture priorities faster than legacy test protocols adapt.
Market Dynamics
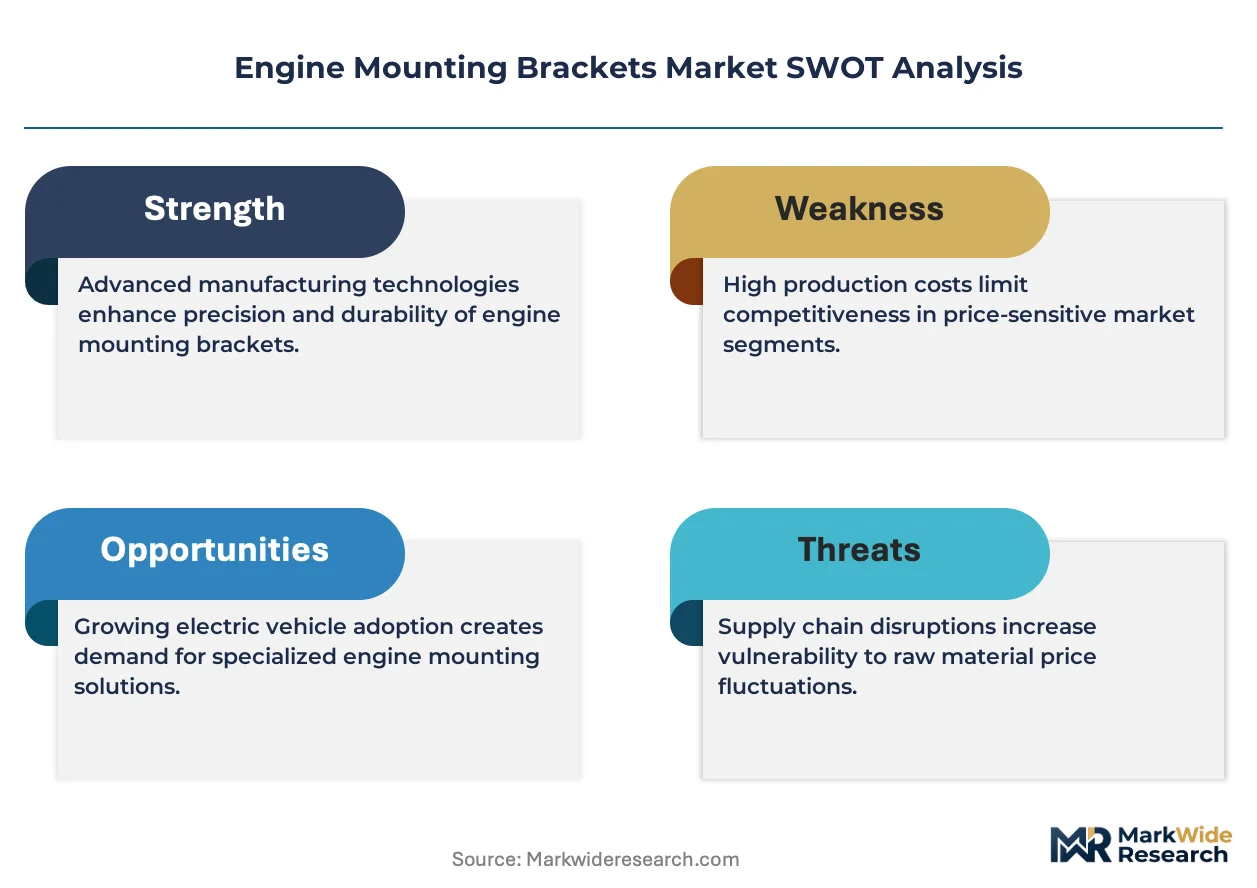
Powertrain electrification is redefining torque pulse characteristics and thermal envelope demands faster than legacy mount test protocols adapt, forcing suppliers to retune damping architectures for electric vehicle platforms while maintaining hybrid compatibility.
Growth Catalysts
- Commercial fleet vibration specifications:Fleet operators specify multi-chamber hydraulic mounts to extend powertrain service life and reduce unscheduled downtime in high-mileage applications.
- GB 1495 noise emission tightening:China's evolving national standards for vehicle noise are elevating material and performance requirements for chassis-mounted vibration control components.
- Aluminum alloy corrosion resistance:Passenger car OEMs specify corrosion-resistant aluminum grades to achieve mass reduction targets without sacrificing bracket longevity in salt-spray environments.
Market Restraints
- Raw material volatility in rubber compounding:Natural rubber and synthetic elastomer price swings compress margin predictability for bonded mount producers without captive polymer supply.
- Supplier concentration in precision valving:Complex hydraulic mount internal valving depends on a concentrated base of specialized fluid dynamics engineering houses in Germany and Japan.
- Legacy test protocol lag:SAE and ISO vibration test standards have not kept pace with electric motor torque ripple frequencies, creating certification uncertainty for next-generation designs.
Strategic Opportunities
- Sensor-integrated mount architectures:Integrated load cell and accelerometer designs enable real-time powertrain health monitoring for predictive maintenance platforms.
- Mexico automotive manufacturing clusters:OEM sourcing decisions are concentrating in Guanajuato and Nuevo León production corridors, creating localized supply opportunities.
- IRA domestic content incentives:US electric vehicle assembly tax credits are pulling mount production toward North American stamping and casting operations.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled fluid-structure-acoustic modeling for hydraulic mount tuning requires specialized CAE expertise that outpaces university pipeline output.
- Weld qualification timelines:NHTSA crashworthiness retention requirements demand extensive fracture testing and documentation, extending new bracket program approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Mounting Brackets Market |
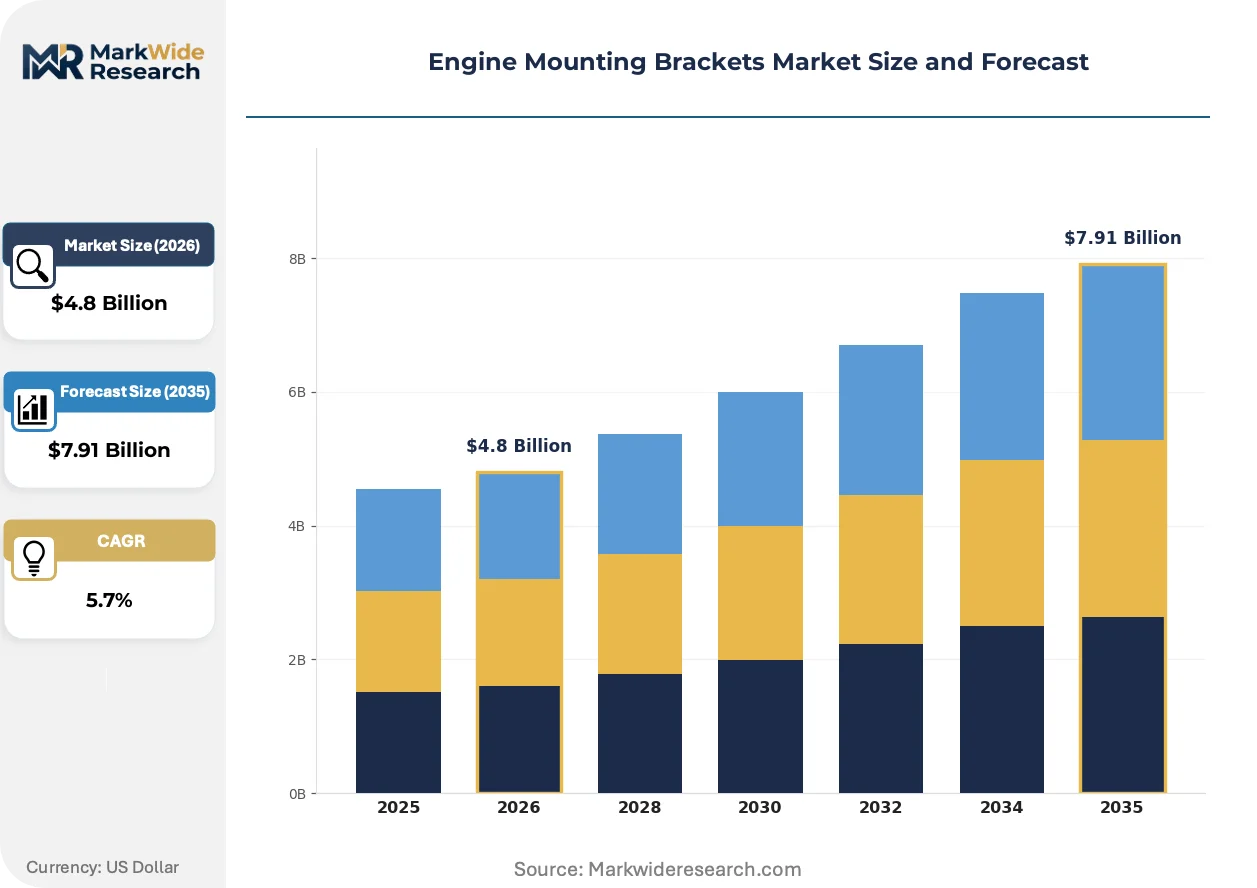
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Mounts, Rubber Mounts, Solid Mounts, Pneumatic Mounts End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Material: Aluminum, Steel, Polyurethane, Composite Application: Passenger Cars, Commercial Vehicles, Heavy Machinery, Motorcycles |
| Companies Covered | TOYO TIRES, Hasport Performance, ContiTech, Vibracoustic, Lord Corporation, Hutchinson, Hedman Performance Group, Trelleborg, Sumitomo Riko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Mounting Brackets Market Emerging Trajectories
Mount architecture is converging around tunable damping systems that adapt to powertrain mode transitions, with fluid-filled designs displacing passive elastomeric solutions in premium platforms while stamped steel retains commercial vehicle cost floors.
Active hydraulic engine mounts with electronically controlled valving are modularizing across luxury and near-luxury vehicle programs. BMW and Mercedes-Benz specification teams are adopting these systems for hybrid powertrains that switch between combustion torque pulses and electric motor smoothness. The technology is modularizing supplier development roadmaps by separating electronic control unit firmware from mechanical cartridge design, enabling tiered sourcing strategies.
ECE R51 noise emission standards across European type-approval regimes are mandating stricter vibration control at specific frequency bands. The regulation is compressing the performance gap acceptable between OEM and aftermarket replacement mounts. Passenger car segments in Germany and France are responding with accelerated validation of multi-chamber hydraulic designs that target 20-80 Hz isolation.
Aftermarket channel consolidation is compressing distributor margins and shifting volume toward direct OEM service part programs. Independent jobbers in North America are losing share to dealer captive parts operations as vehicle health monitoring systems flag mount degradation codes earlier. The behavior is most visible in US domestic light truck segments where telematics-enabled warranty extensions bundle mount replacement into powertrain service contracts.
Engine Mounting Brackets Market Segmentation
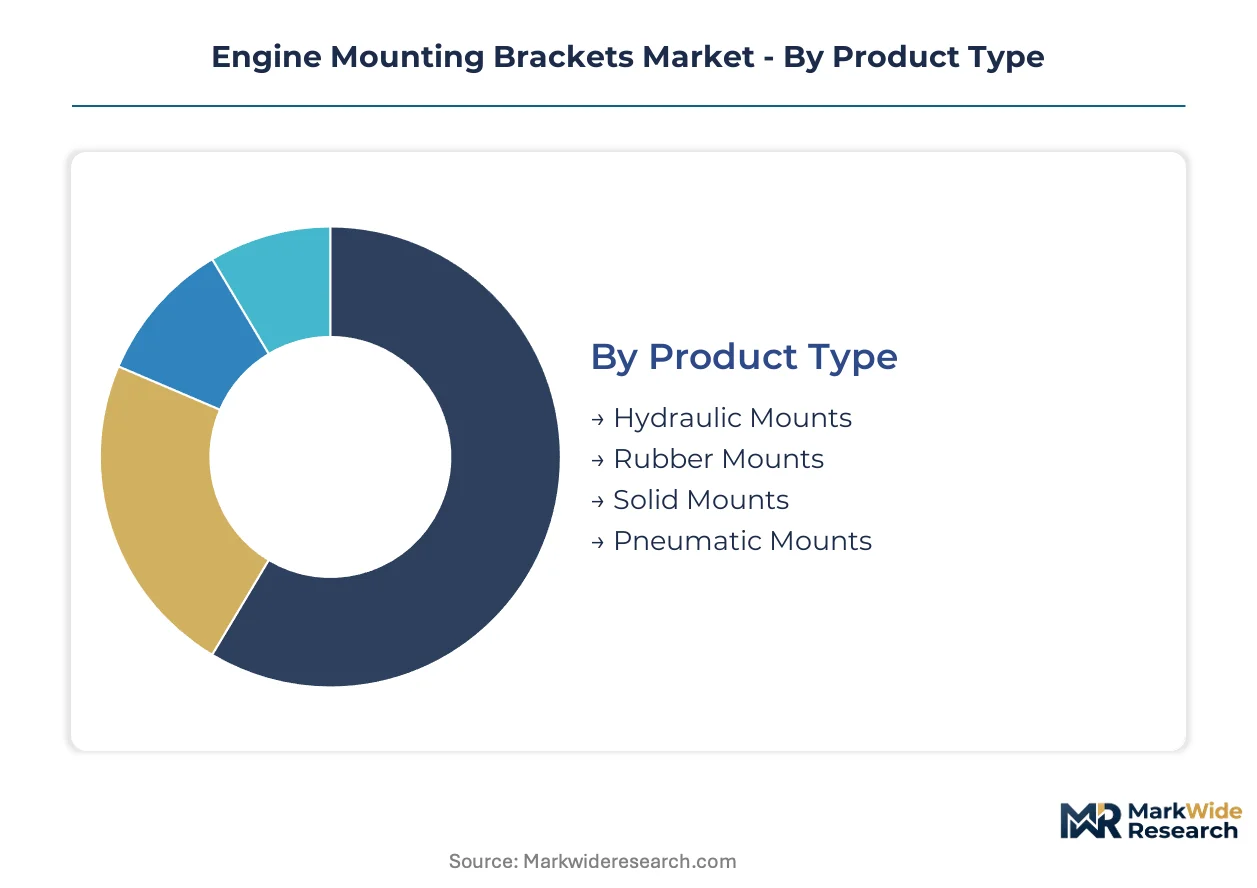
Engine mounting bracket segmentation reveals how material science, damping architecture, and supply chain configuration intersect to define competitive positioning. Each dimension carries distinct margin profiles and qualification barriers that shape supplier strategy across vehicle platforms.
Product Type:
Supply concentration in precision valving and tuned fluid dynamics engineering creates tiered competitive moats around hydraulic architectures.
- Hydraulic Mounts:Multi-chamber fluid-filled designs incorporate internal valving systems tuned to specific frequency response curves. BMW and Mercedes-Benz specification teams prioritize these for hybrid powertrains in Germany and US luxury assembly plants. OEMs source these through specialized engineering houses concentrated in Germany and Japan.
- Rubber Mounts:Bonded elastomeric assemblies dominate cost-sensitive volume production through simpler metal-rubber bonding processes. China's expanding commercial vehicle fleets in Shandong and Hebei provinces specify these for durability over refinement in high-mileage truck applications.
- Solid Mounts:Stamped steel variants serve commercial vehicle cost floors where mechanical retention outweighs cabin isolation.
- Pneumatic Mounts:Air-spring assisted designs occupy niche heavy-duty segments requiring adjustable load compensation.
Today's leader: Hydraulic Mounts. Tomorrow's challenger: Pneumatic Mounts.
End User:
Procurement authority concentrates with OEM specification teams, though aftermarket channel consolidation is redistributing volume toward captive service operations.
- OEMs:Vehicle manufacturer engineering teams define bracket architecture during platform development, locking in suppliers through multi-year program contracts. NHTSA crashworthiness requirements and ECE R51 noise standards shape their technical specifications.
- Aftermarket Providers:Distributor networks face margin compression as telematics-enabled warranty extensions bundle mount replacement into powertrain service contracts. US domestic light truck segments show this shift most visibly.
- Vehicle Assemblers:Contract manufacturing operations in Mexico's Guanajuato corridor execute OEM designs with localized sourcing mandates.
- Repair Shops:Independent jobbers lose share to dealer captive parts operations as vehicle health monitoring systems flag degradation codes earlier.
Volume concentrates with OEMs. Value capture is shifting toward Aftermarket Providers with diagnostic integration capabilities.
Material:
Mass reduction imperatives and salt-spray durability requirements are elevating aluminum specification rates in passenger car platforms.
- Aluminum:Corrosion-resistant grades achieve mass reduction targets without sacrificing bracket longevity. Passenger car OEMs in Japan and Germany specify these for electric vehicle platforms where thermal envelope demands differ from combustion architectures.
- Steel:Stamped and cast grades retain dominance in commercial vehicle applications where fracture toughness under impact loading outweighs weight considerations. NHTSA retention requirements favor steel's predictable failure modes.
- Polyurethane:Aftermarket upgrade compounds target track-day enthusiasts seeking stiffer powertrain response.
- Composite:Fiber-reinforced polymers remain developmental for specific electric vehicle thermal management applications.
Steel retains volume leadership. Aluminum is climbing the fastest on electrification-driven mass reduction mandates.
Application:
Torque pulse characteristics and duty cycle severity create divergent specification thresholds across vehicle categories.
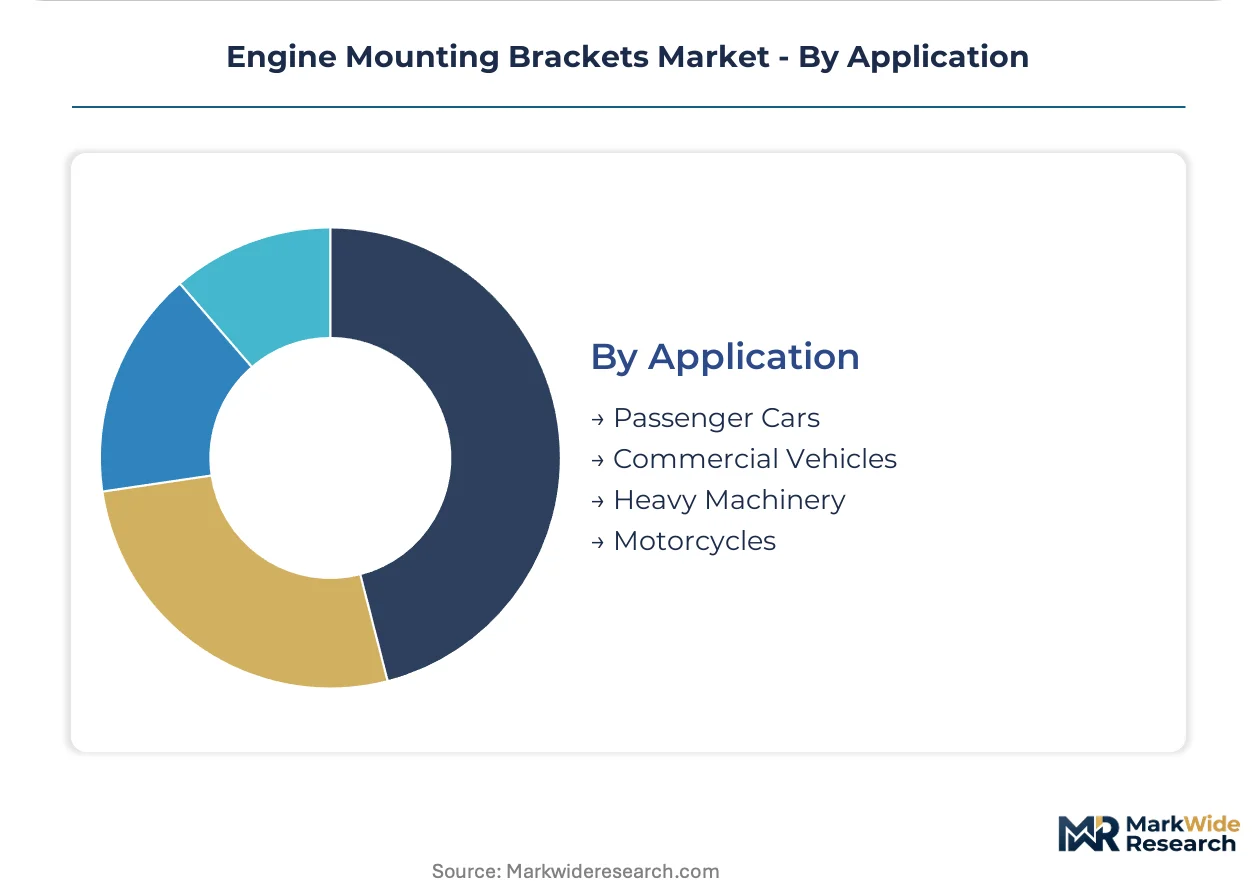
- Passenger Cars:Premium platforms specify multi-chamber hydraulic designs targeting 20-80 Hz isolation bands mandated by ECE R51. Electric motor torque ripple frequencies are forcing retuning of legacy damping architectures faster than SAE test protocols adapt.
- Commercial Vehicles:Fleet operators prioritize service life extension through vibration-dampening assemblies. China's GB 1495 noise emission tightening elevates material requirements for chassis-mounted components in heavy-duty segments.
- Heavy Machinery:Construction and mining equipment demands fracture-resistant retention under severe impact and continuous vibration loading.
- Motorcycles:Compact packaging constraints favor integrated bracket-damping solutions with minimal envelope requirements.
Passenger Cars anchor premium technology adoption. Commercial Vehicles represent the steepest expansion trajectory on fleet electrification and durability specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision valving engineering houses command premium hydraulic mount sourcing, while China's commercial vehicle fleets drive volume demand for stamped steel variants under tightening noise emission mandates.
Germany
BMW and Mercedes-Benz specification teams prioritize multi-chamber fluid-filled designs for hybrid powertrains. ECE R51 noise emission standards mandate stricter vibration control at 20-80 Hz isolation bands. Stuttgart and Munich engineering corridors concentrate specialized fluid dynamics expertise for tuned damping architectures.
China
Expanding commercial vehicle fleets in Shandong and Hebei provinces specify vibration-dampening assemblies for high-mileage durability. NMPA vehicle safety standards and evolving GB 1495 noise limits tighten material requirements. Yangtze River Delta automotive clusters localize aluminum casting operations for electric vehicle platforms.
United States
NHTSA crashworthiness requirements influence bracket fracture behavior and retention integrity under severe impact loading. IRA domestic content incentives pull mount production toward North American stamping operations. Michigan and Ohio manufacturing corridors execute OEM designs with localized sourcing mandates for electric vehicle assembly.
Japan
Passenger car OEMs specify corrosion-resistant aluminum grades for mass reduction without sacrificing longevity. METI industrial standards shape material qualification protocols for chassis components. Nagoya and Osaka production clusters integrate sensor-ready mount designs supporting vehicle health monitoring architectures.
Mexico
OEM sourcing decisions concentrate in Guanajuato and Nuevo León production corridors creating localized supply opportunities. Vehicle assembler contract manufacturing operations execute designs with regional content requirements. Bajío Region automotive clusters attract bracket stamping and casting investments serving North American electric vehicle programs.
Engine Mounting Brackets Market Vendor Landscape
Top-tier vendors anchor premium hydraulic assembly supply, while mid-tier fabricators compete on stamped steel commercial vehicle contracts. The vendor base stratifies across acoustic engineering specialists, captive rubber compounders, and integrated sensor-ready designers. Two strategic archetypes dominate: precision valving houses with tuned frequency expertise, and diversified chassis suppliers leveraging metal-rubber bonding scale. Competitive moves center on sensor integration partnerships and regional casting capacity expansion near OEM assembly plants.
Within the precision valving tier, Vibracoustic and ContiTech exemplify divergent sourcing strategies—Vibracoustic representing acoustic engineering heritage positioning, ContiTech anchoring captive polymer supply control. Sumitomo Riko occupies a position bridging mechanical design with electronics integration, reflecting the sensor-architecture convergence reshaping procurement criteria. These three entities illustrate how tier-one positioning now requires either deep fluid dynamics specialization or backward integration into rubber compounding, with hybrid-electric platform retuning demands favoring those with multi-physics simulation capabilities.
| Leading Market Players |
|---|
| TOYO TIRES |
| Hasport Performance |
| ContiTech |
| Vibracoustic |
| Lord Corporation |
| Hutchinson |
| Hedman Performance Group |
| Trelleborg |
| Sumitomo Riko |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Germany's Stuttgart engineering corridor anchor premium hydraulic mount production, their patient capital enabling multi-year R&D cycles that sustain pricing discipline against volatile rubber compounders in Asia. This ownership structure insulates tier-one suppliers from quarterly margin pressure while concentrating supply leverage around tuned valving expertise.
Pricing Analysis
Bundled engineering services separate premium hydraulic mount suppliers from commodity rubber producers. Three-tier pricing structure across active hydraulic, passive fluid-filled, and solid elastomeric levels reflects certification complexity and damping performance tiers. Pricing pressure stems from raw material volatility in natural rubber and synthetic elastomer markets, compressing margin predictability for non-captive compounders. Commercial vehicle fleet operators exhibit highest price sensitivity, prioritizing durability over refinement, while luxury OEM specification teams accept premium positioning for multi-chamber designs.
Supply Chain Analysis
Reverse-logistics flows for remanufactured hydraulic cartridges are emerging as OEMs extend powertrain warranty programs through predictive maintenance platforms. Supply concentrates in Germany, Japan, and China's Yangtze River Delta, with precision valving engineering anchored in Stuttgart and Nagoya corridors. Production draws from specialized aluminum casting operations, captive rubber compounding facilities, and precision machining centers. Single-source vulnerability in fluid dynamics simulation talent creates qualification bottlenecks. Distribution runs through tiered OEM supply contracts with localized stamping and casting investments serving North American electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electrification-driven retuning demands favor suppliers with multi-physics simulation capabilities and backward-integrated polymer control. Fleet procurement is shifting toward vibration-dampening specifications that extend powertrain service life.
For Market Incumbents: Deepen captive rubber compounding investments to insulate margin predictability from elastomer price volatility. Expand sensor-ready mount architectures supporting vehicle health monitoring platforms to defend against electronics-integrated entrants. Prioritize weld qualification documentation acceleration to compress NHTSA crashworthiness approval cycles for new bracket programs. For New Entrants and Emerging Players: Capture aftermarket diagnostic integration opportunities as telematics-enabled warranty extensions bundle mount replacement into powertrain service contracts. Target Mexico's Guanajuato and Nuevo León production corridors where IRA domestic content incentives are pulling assembly operations. Pursue white-label sensor integration partnerships with predictive maintenance platform providers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier stamped steel fabricators lacking hydraulic valving expertise or aluminum casting scale. Long-term viability favors precision engineering houses with demonstrated electric vehicle platform retuning capabilities. Watch NMPA and GB standard evolution in China as the signal indicating regulatory-driven specification upgrades that compress commodity margin tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Mount Development | Enables real-time powertrain health monitoring for predictive maintenance platforms serving commercial fleets. |
| Aluminum Casting Capacity Expansion | Addresses mass reduction mandates for electric vehicle platforms in Germany and Japan manufacturing clusters. |
| Multi-Physics Simulation Talent Acquisition | Resolves coupled fluid-structure-acoustic modeling scarcity constraining hydraulic mount tuning cycles. |
| Regional Stamping Localization | Captures IRA domestic content incentives pulling production toward Michigan and Ohio manufacturing corridors. |
| Captive Rubber Compounding Integration | Insulates margin predictability from natural rubber and synthetic elastomer price volatility in Asian supply markets. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier-one supplier procurement teams, aftermarket distributor operations managers, and commercial fleet maintenance directors grounded this analysis in operational reality. Secondary validation drew from NHTSA crashworthiness filings, ECE R51 type-approval documentation, vehicle production databases, and customs trade records. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level projections incorporated product type, material grade, vehicle application, and regional production cluster dimensions throughout the forecast period. CAGRs derived from elasticity modeling against powertrain electrification penetration curves and fleet replacement cycles. Electric motor torque ripple frequency characteristics and thermal envelope demands served as primary forecast inputs.
Raw material volatility, regulatory protocol lag, and multi-physics simulation talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding electrification adoption trajectories and noise emission standard evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
EV Connectors Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Snowplows Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Sideloaders Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Garbage Collection Vehicle Market