
 Asia Pacific Automotive Aftermarket Market | 2026-2036
Asia Pacific Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Aftermarket Market Analysis
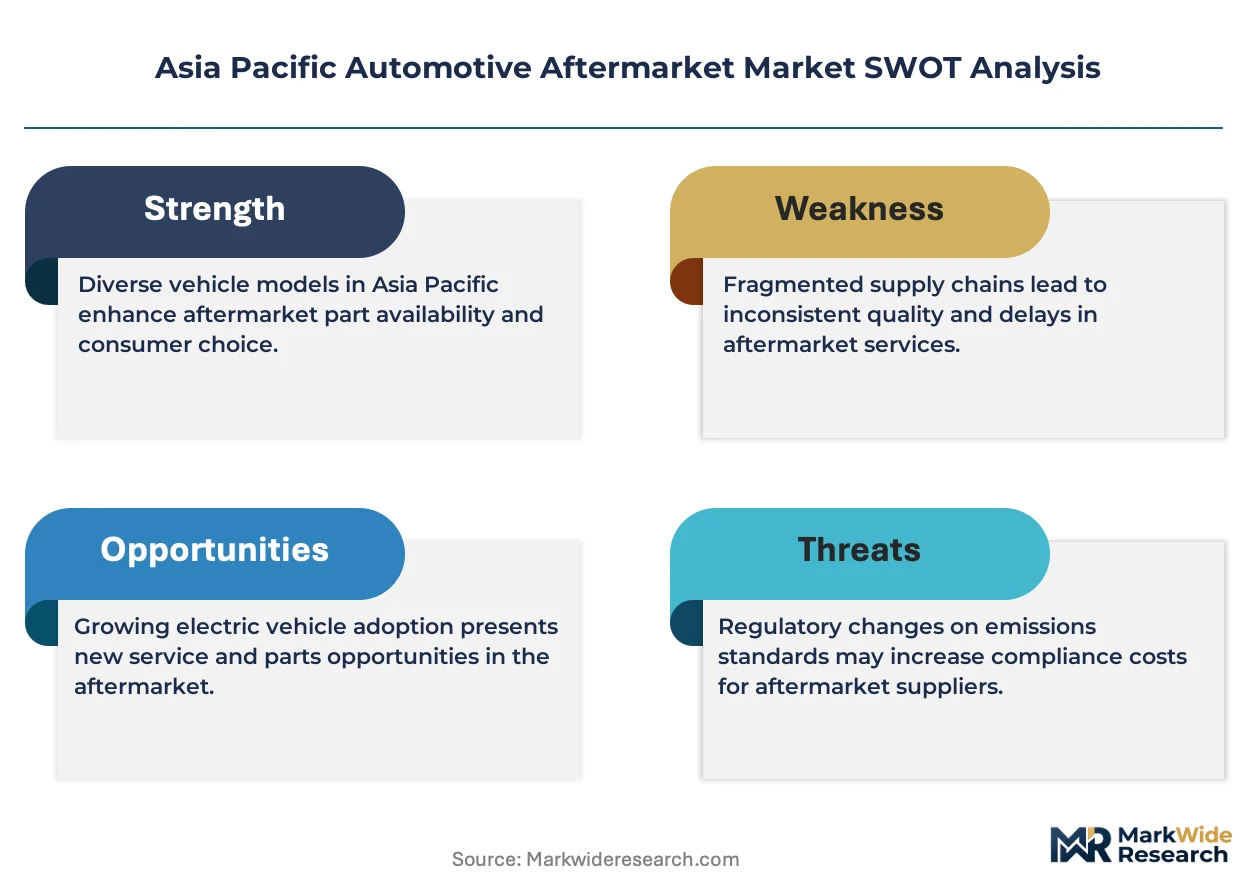
The widening gap between OEM-certified parts and unbranded commodity alternatives is repositioning competitive dynamics across the Asia Pacific Automotive Aftermarket. Robert Bosch GmbH leverages its diagnostic equipment ecosystem to anchor premium service networks in Japan and South Korea. Denso Corporation sustains dominance in thermal and powertrain components through captive manufacturing scale. Mando Corporation differentiates in chassis and brake systems by controlling OEM supply relationships that cascade into aftermarket channels.
The Asia Pacific Automotive Aftermarket comprises the trade of replacement parts, accessories, tools, and services for vehicles after their original sale, encompassing everything from brake pads and filters engineered to OEM tolerances to performance chips reprogramming engine control units. Its primary commercial purpose is maintaining vehicle operability, safety compliance, and owner customization across a region where average vehicle age now exceeds seven years in multiple markets. Aftermarket Parts command the largest revenue pool due to recurring replacement cycles, while Online Platforms represent the fastest-growing end-user channel as smartphone penetration enables direct-to-workshop procurement. Repair Services generate stable cash flows, though Performance Services extract premium pricing from enthusiast segments in Australia and Thailand.
Japan's METI enforces JIS standards for aftermarket component interoperability, while China's SAMR administers GB standards that foreign suppliers must meet for market access. India's BIS mandates certification for critical safety components, creating compliance barriers that favor established multinationals over gray-market imports. Stakeholders must monitor how Australia's TGA-equivalent automotive safety frameworks and evolving ASEAN mutual recognition agreements reshape cross-border parts eligibility. The decisive variable ahead is whether national regulators harmonize certification regimes or fragment them further.
Market Dynamics
The Asia Pacific Automotive Aftermarket is being restructured by the collision between aging vehicle parc expansion and tightening national certification regimes. Workshop networks in Southeast Asia are scaling capacity to absorb rising repair volumes while BIS mandates in India and METI standards in Japan erect compliance barriers that favor capitalized suppliers over fragmented importers.
Growth Catalysts
- Vehicle Parc Aging:Southeast Asian markets now average seven-plus years of vehicle age, compressing replacement cycles for brake components, filters, and thermal systems across Indonesia, Thailand, and Vietnam.
- BIS Certification Mandates:India's Bureau of Indian Standards now requires pre-market approval for brake linings and headlamp assemblies, eliminating gray-market competition and formalizing demand channels for certified suppliers.
- Smartphone-Enabled Procurement:Mobile platform penetration is rewiring parts distribution, allowing independent workshops in tier-two Indian cities to bypass traditional distributor tiers and source directly from certified manufacturers.
Market Restraints
- Steel and Aluminum Input Volatility:Foundry-grade aluminum and cold-rolled steel price swings compress margin predictability for chassis and brake component producers serving price-sensitive replacement markets.
- OEM Supply Lock-In:Tier-one chassis and powertrain suppliers leverage captive OEM relationships to restrict aftermarket parts flow, concentrating control over technical documentation and calibration protocols in South Korea and Japan.
- Counterfeit Component Infiltration:Unbranded commodity alternatives lacking JIS or GB certification continue capturing volume in price-driven segments, eroding trust in formal channels across secondary Chinese and Indonesian cities.
Strategic Opportunities
- Tier-Two Indian City Expansion:Passenger car ownership acceleration in Pune, Jaipur, and Lucknow is outpacing service infrastructure, creating whitespace for standardized workshop networks and parts distribution hubs.
- Diagnostic-Tools-as-a-Service:Subscription-based diagnostic equipment models are penetrating independent workshop segments, converting capital expenditure into recurring revenue while locking in parts purchasing commitments.
- ASEAN Mutual Recognition Trajectory:Emerging cross-border certification reciprocity between Thailand, Malaysia, and Vietnam is streamlining parts eligibility, enabling regional scale for compliance-invested suppliers.
Industry Challenges
- EV Powertrain Skill Deficit:High-voltage battery system repair and motor controller diagnostics require technician retraining that current vocational pipelines in India and Indonesia cannot supply at scale.
- Multi-Standard Certification Burden:Suppliers serving Japan, China, and India simultaneously must maintain parallel testing protocols for JIS, GB, and BIS standards, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Aftermarket Market |
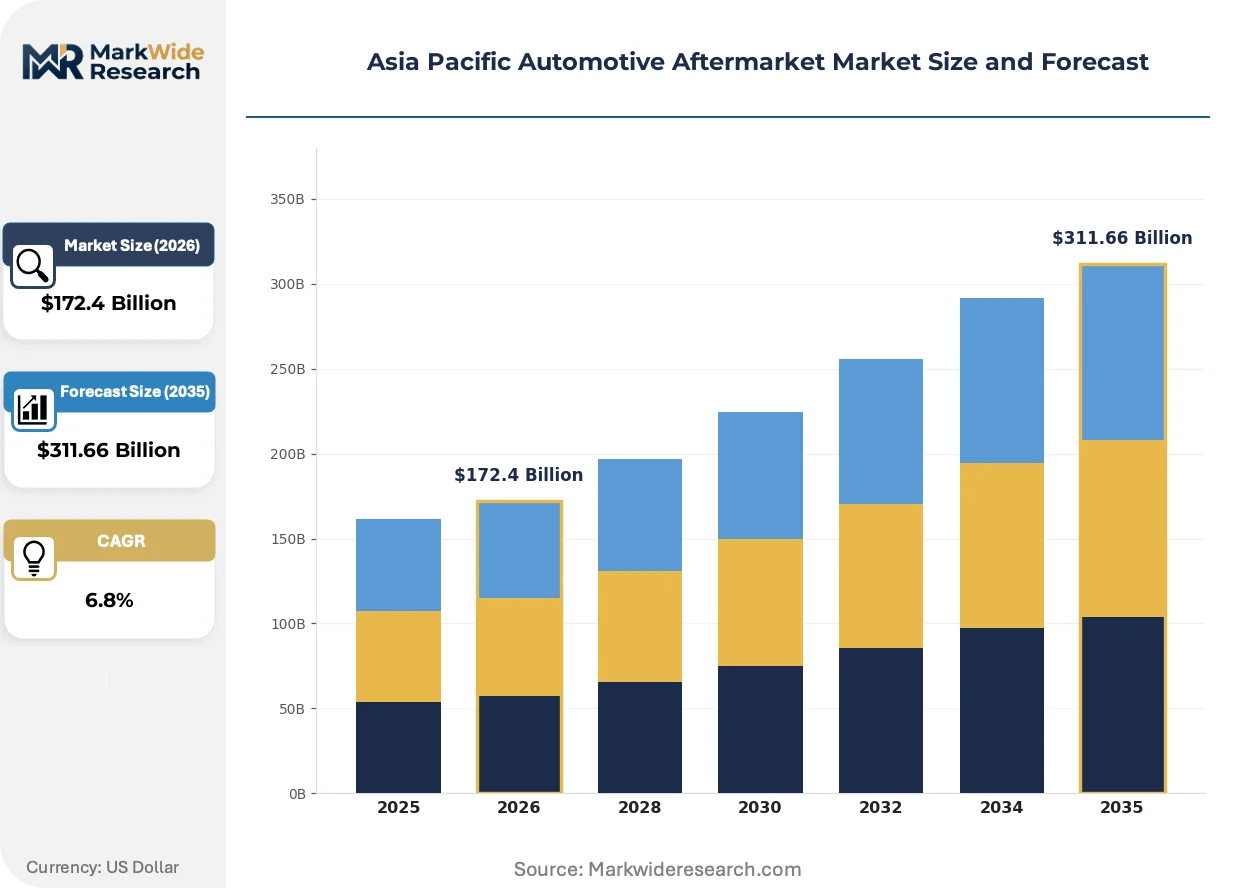
| Market Size in 2026 | $172.4 Billion |
| Market Size in 2035 | $311.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Parts, Aftermarket Parts, Accessories, Tools End User: Independent Workshops, Franchise Workshops, Retail Stores, Online Platforms Distribution Channel: Online Sales, Retail Outlets, Wholesale Distributors, Service Stations Service Type: Repair Services, Maintenance Services, Cosmetic Services, Performance Services |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, ZF Friedrichshafen AG, Hyundai Mobis Co, Aisin Seiki Co., Ltd., Delphi Automotive PLC, 3M, Mando Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Aftermarket Market Emerging Trajectories
Digital procurement infrastructure and predictive maintenance algorithms are rewiring how replacement parts reach end-users across the Asia Pacific. Three convergent developments are compressing traditional distribution hierarchies while elevating technical service content.
Telematics-integrated predictive maintenance systems are overtaking scheduled interval servicing as the dominant aftermarket revenue trigger. Fleet operators in Australia and Thailand now receive real-time component degradation alerts, converting unscheduled repairs into pre-positioned parts shipments. This compression of the failure-to-repair cycle is reducing inventory carrying costs for workshops while elevating data analytics capabilities among parts suppliers.
China's SAMR has accelerated enforcement of GB standards for aftermarket brake and lighting components, requiring foreign suppliers to submit domestic test data rather than accepting international certifications. Japanese and Korean component manufacturers are responding by establishing captive testing facilities in Shanghai and Tianjin, localizing compliance infrastructure to preserve market access. The policy is most disruptive for mid-tier European suppliers lacking regional laboratory partnerships.
Workshop procurement patterns are fragmenting across channel types as independent repairers in Vietnam and the Philippines adopt mobile marketplace applications for same-day parts fulfillment. Traditional three-tier distribution through national distributors and regional sub-distributors is losing volume to platform-direct models that aggregate demand and consolidate logistics. This behavioral shift is most pronounced among digitally native workshop owners under age forty operating in Ho Chi Minh City and Manila suburbs.
Asia Pacific Automotive Aftermarket Market Segmentation
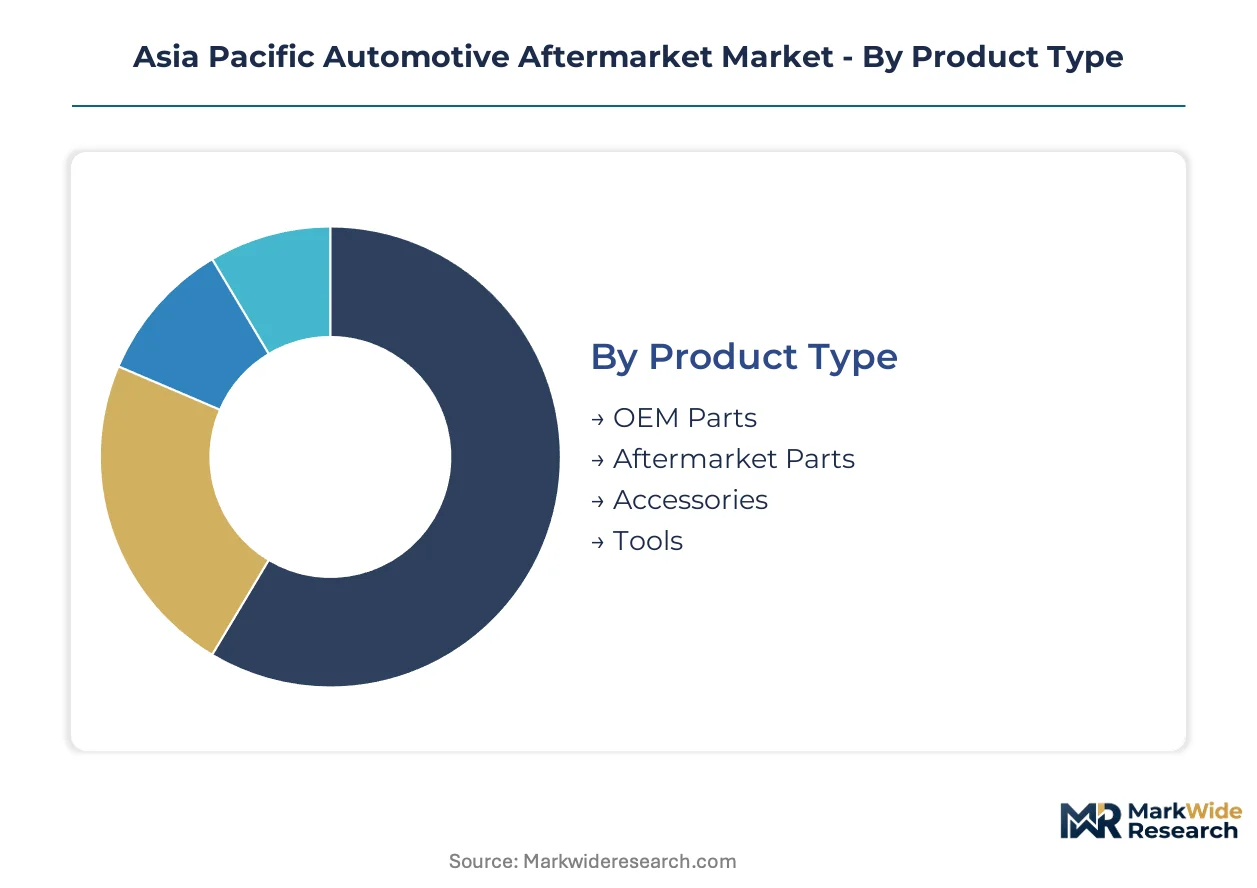
Segmentation in the Asia Pacific Automotive Aftermarket reveals how procurement behavior fragments across buyer sophistication levels. Workshop operators in Jakarta and Chennai select parts through fundamentally different channels than fleet managers in Sydney or enthusiast garages in Bangkok.
Product Type:
Certification grade determines price tolerance and supplier loyalty across replacement part categories.
- OEM Parts:Components manufactured to original equipment specifications with full technical documentation and calibration data. Demand clusters in Japan and South Korea where METI enforcement of JIS standards and captive OEM supply relationships preserve premium positioning for verified suppliers.
- Aftermarket Parts:Replacement components engineered to equivalent performance standards without original branding, spanning brake pads, filters, and thermal systems. Volume concentrates in India's tier-two cities where BIS mandates are compressing gray-market alternatives and formalizing demand for certified aftermarket suppliers.
- Accessories:Non-essential add-ons including infotainment upgrades, lighting modifications, and interior customization products. Pune and Lucknow workshops report rising attach rates for smartphone integration kits.
- Tools:Diagnostic equipment, specialized service tools, and calibration devices required for modern vehicle servicing. Ho Chi Minh City distributors note accelerating procurement of OBD-II scanners among independent repairers.
Volume sits with Aftermarket Parts; growth tilts toward OEM Parts as certification barriers harden.
End User:
Workshop scale and technical capability shape channel selection and parts sourcing patterns.
- Independent Workshops:Small-to-mid-size repair facilities operating outside franchise networks, typically serving localized vehicle populations. Thailand and Vietnam lead expansion as smartphone-enabled procurement allows direct manufacturer sourcing bypassing traditional distributor tiers.
- Franchise Workshops:Branded service networks with standardized equipment, technician training, and parts supply agreements. Australia's franchise penetration remains highest in the region due to consumer warranty preservation preferences.
- Retail Stores:Counter-sales outlets serving DIY enthusiasts and small fleet operators with immediate parts availability. Jaipur and Lucknow retail footprints are widening fastest among Indian tier-two cities.
- Online Platforms:Digital marketplaces aggregating parts demand and consolidating logistics for workshop and consumer buyers. Platform-direct procurement is gaining share fastest in Manila and Ho Chi Minh City suburbs among digitally native workshop owners.
Revenue concentrates with Independent Workshops; platform adoption is climbing the fastest among end-user channels.
Distribution Channel:
Channel selection reflects urgency requirements, technical support needs, and price sensitivity trade-offs.
- Online Sales:E-commerce and mobile marketplace transactions enabling direct manufacturer-to-workshop fulfillment. Same-day delivery capabilities are penetrating Vietnam and Philippines urban corridors.
- Retail Outlets:Physical counter locations providing immediate parts availability and basic technical consultation. Tier-two Indian cities show retail network expansion outpacing service infrastructure growth.
- Wholesale Distributors:Regional and national distributors maintaining inventory buffers and credit terms for workshop accounts. Traditional three-tier distribution retains dominance in Indonesian secondary cities.
- Service Stations:Integrated repair facilities combining parts supply with installation services. Australia's service station network maintains highest diagnostic equipment penetration in the region.
Transaction volume flows through Wholesale Distributors; Online Sales channels are expanding most quickly as logistics networks mature.
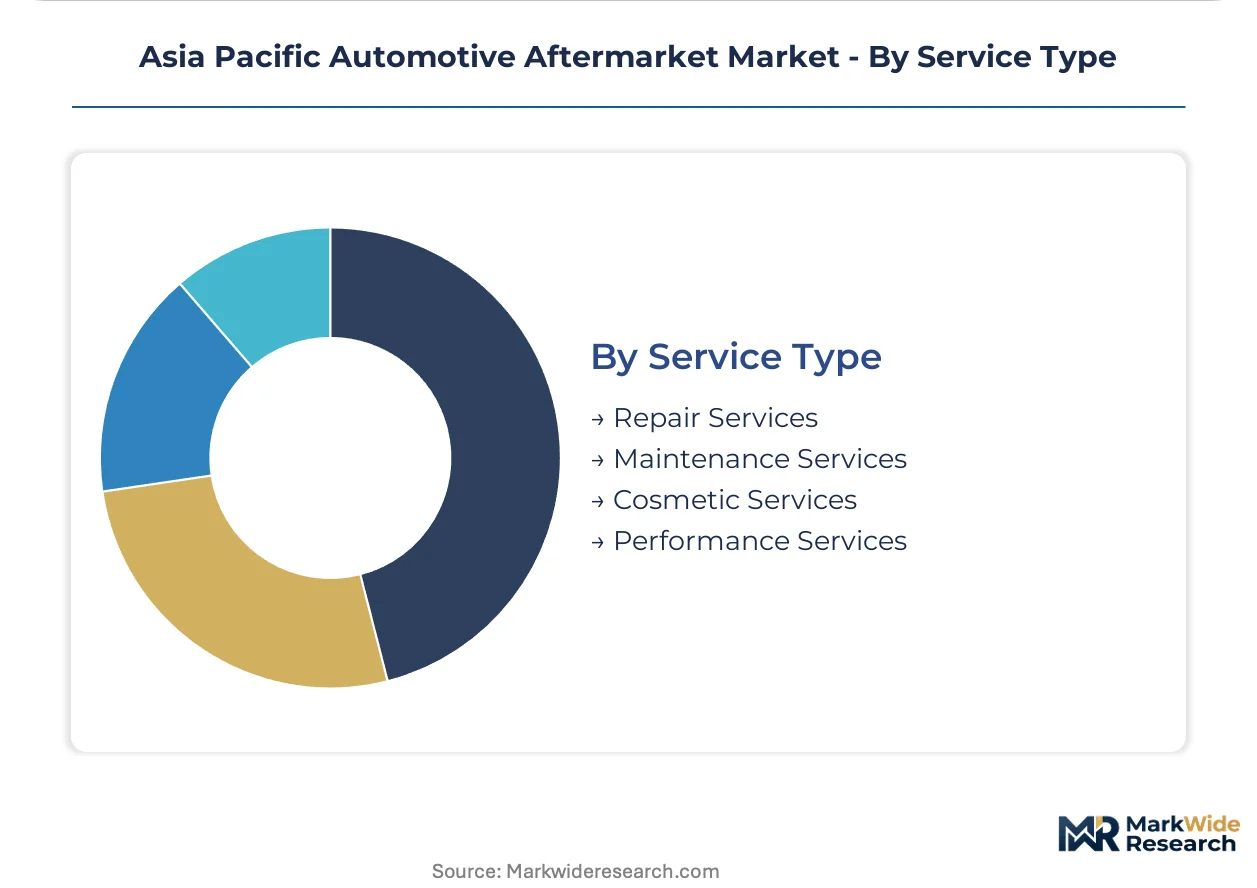
Service Type:
Service category selection correlates with vehicle age, ownership tenure, and regional income levels.
- Repair Services:Unscheduled component replacement addressing failures and damage events. Demand intensifies across Southeast Asia as regional vehicle parc exceeds seven years average age.
- Maintenance Services:Scheduled interval servicing including fluid changes, filter replacement, and inspection protocols. India's BIS certification mandates are elevating maintenance service formalization in tier-two cities.
- Cosmetic Services:Appearance restoration and enhancement including paint, trim, and interior refurbishment. Australia's enthusiast segment sustains premium cosmetic service pricing.
- Performance Services:Powertrain modifications, suspension upgrades, and track-oriented enhancements. Thailand's motorsport culture anchors regional performance service revenue concentration.
Revenue stability characterizes Maintenance Services; Performance Services show steepest expansion trajectory among enthusiast demographics in Australia and Thailand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors aftermarket sophistication across the Asia Pacific, where Japan's seven-plus-year vehicle parc sustains premium parts demand while emerging Southeast Asian markets absorb capacity expansion from aging fleets.
Japan
Japan's aftermarket concentrates in brake components and thermal systems replacement as vehicle age exceeds eight years nationally. METI enforces JIS standards for component interoperability, creating compliance barriers for non-certified imports. Nagoya's industrial corridor houses captive OEM supply relationships that cascade certified parts into aftermarket channels.
India
India's aftermarket accelerates in tier-two cities where passenger car ownership outpaces service infrastructure growth. BIS mandates pre-market certification for brake linings and headlamp assemblies, eliminating gray-market competition. Pune and Jaipur workshop networks expand standardized service capacity to capture rising maintenance demand.
China
China's aftermarket faces restructuring as SAMR accelerates GB standards enforcement for brake and lighting components. Foreign suppliers now submit domestic test data rather than international certifications. Shanghai and Tianjin host localized compliance laboratories established by Japanese and Korean manufacturers preserving market access.
Thailand
Thailand's aftermarket benefits from ASEAN mutual recognition trajectory streamlining cross-border parts eligibility. Bangkok's workshop density supports motorsport-oriented performance services extracting premium pricing. Ho Chi Minh City and Manila distributors replicate Thai platform-direct procurement models among digitally native repairers.
Australia
Australia's aftermarket sustains highest franchise workshop penetration regionally due to warranty preservation preferences. TGA-equivalent automotive safety frameworks elevate diagnostic equipment standards. Sydney and Melbourne fleet operators deploy telematics-integrated predictive maintenance compressing failure-to-repair cycles.
Asia Pacific Automotive Aftermarket Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade tiers, with JIS-certified and BIS-approved suppliers commanding price premiums over unbranded alternatives. The vendor base stratifies between integrated OEM-captive manufacturers, independent aftermarket specialists, and platform-aggregated distributors. Three archetypes dominate: diagnostic equipment ecosystem providers anchoring service networks, thermal and powertrain component scale manufacturers, and chassis system suppliers leveraging OEM supply relationships. Competitive moves concentrate on compliance infrastructure localization and subscription-based diagnostic tool penetration.
Within the integrated OEM-captive tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes where diagnostic equipment ecosystems and thermal component scale create aftermarket anchoring positions. Mando Corporation occupies a distinct position among chassis and brake system specialists. Zhengzhou-based fabricators and other regional Co., Ltd. structures represent commodity-margin competition facing certification barrier compression.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co |
| Aisin Seiki Co., Ltd. |
| Delphi Automotive PLC |
| 3M |
| Mando Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap distributors across Thailand and Vietnam anchor procurement liquidity in tier-two cities, compressing payment terms for upstream foundries while extracting volume rebates that cascade into workshop-level price competition. Their concentrated ownership structures enable rapid inventory rebalancing when aluminum and steel input costs fluctuate, tightening pricing discipline across brake component and thermal system categories.
Pricing Analysis
Value-based pricing anchored to vehicle uptime guarantees dominates fleet service contracts in Australia and Thailand, where telematics integration allows suppliers to capture premiums tied to predictive failure avoidance. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified OEM-grade components from BIS-approved aftermarket alternatives and unbranded commodity imports. Pricing pressure stems from smartphone-enabled direct sourcing that collapses traditional distributor markups in Ho Chi Minh City and Manila. Independent workshops in Jakarta show highest price sensitivity, while franchise networks in Sydney preserve premium tolerance through warranty-linked service bundling.
Supply Chain Analysis
Regional distribution centers in Shanghai, Bangkok, and Mumbai orchestrate hub-and-spoke patterns that consolidate fragmented workshop demand into manufacturer-direct fulfillment lanes. Supply concentrates in China for foundry-grade aluminum and electronics, Japan for precision brake components, and South Korea for powertrain modules. Raw material dependencies on Indonesian nickel, Australian bauxite, and Chinese rare earth processing create tariff exposure at multiple conversion stages. Distribution runs through platform-aggregated logistics networks that bypass traditional three-tier wholesaler hierarchies in Vietnam and Philippines urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive testing laboratories and diagnostic equipment production represents the decisive upstream lever as certification barriers harden across Japan, India, and China. Players securing in-house compliance infrastructure compress product launch timelines while locking in premium pricing tiers.
For Market Incumbents: Acquire diagnostic equipment ecosystems and calibration protocol libraries to anchor workshop network loyalty against emerging platform-aggregated distributors. Fortify BIS and JIS certification pipelines in India and Japan to eliminate gray-market substitution threats. Build regional testing facilities in Shanghai and Tianjin to preserve China market access under SAMR's domestic data requirements.
For New Entrants and Emerging Players: Enter via tier-two Indian city service infrastructure gaps where passenger car ownership outpaces standardized workshop penetration. Target Pune, Jaipur, and Lucknow for parts distribution hub deployment with same-day fulfillment capabilities. Leverage mobile marketplace applications to aggregate fragmented independent workshop demand and bypass entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier chassis and brake specialists in Southeast Asia facing working capital pressure from input cost volatility. Long-term viability hinges on certification-grade positioning that survives regulatory harmonization or fragmentation scenarios. Monitor ASEAN mutual recognition implementation velocity as the critical inflection signal for regional scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Localization | Captive testing laboratories in Shanghai and Tianjin preserve SAMR market access for Japanese suppliers. |
| Diagnostic-Tools-as-a-Service Launch | Subscription models convert workshop capital expenditure into recurring parts-purchase-locked revenue streams. |
| Tier-Two City Distribution Expansion | Hub deployment in Pune and Jaipur captures passenger car ownership growth outpacing service infrastructure. |
| ASEAN Cross-Border Certification Alignment | Mutual recognition between Thailand, Malaysia, and Vietnam streamlines parts eligibility for regional scale. |
| Telematics-Integrated Predictive Maintenance | Real-time degradation alerts compress failure-to-repair cycles for Australian and Thai fleet operators. |
Methodological Framework
Document review covered regulatory filings from METI, SAMR, and BIS, customs and trade flow databases, and vehicle registration records, complemented by interviews with aftermarket distributor procurement heads, independent workshop operators in tier-two Indian cities, Tier 1 supplier platform engineers, and diagnostic equipment technical specialists. Secondary validation drew from ASEAN automotive industry association reports, IHS Markit vehicle parc data, and national standards body certification registries. Bottom-up demand modeling triangulated against top-down macroeconomic and vehicle ownership projections.
Cross-referencing historical replacement cycle patterns with expert panel input on certification timeline impacts shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product certification grade, end-user workshop type, distribution channel tier, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation adjusted for policy inflection points. Industry-specific forecast inputs encompassed vehicle age distribution shifts and smartphone procurement penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of ASEAN regulatory fragmentation or accelerated EV powertrain displacement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Global Road Maintenance Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market