
 Europe E-Commerce Automotive Aftermarket Market | 2026-2036
Europe E-Commerce Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Commerce Automotive Aftermarket Market Analysis
Multi-source parts procurement is expanding across European garage networks as independent workshops abandon single-brand distributor relationships. Bosch leverages its captive manufacturing base to control quality certification across digital channels. Continental AG anchors its platform strategy on VIN-accurate fitment databases that reduce return rates. Autodoc GmbH competes through centralized warehousing in Germany with radiating last-mile coverage.
The Europe E-Commerce Automotive Aftermarket encompasses digitally transacted replacement components, accessories, maintenance tools, and consumable fluids for post-warranty vehicles, typically specified by OEM part numbers or equivalent quality certifications such as E-mark or CAPA compliance, with platforms integrating VIN decoding to ensure dimensional and performance compatibility. Its primary commercial purpose is to disintermediate traditional brick-and-mortar parts distribution, compressing delivery timelines from days to hours while expanding SKU availability beyond local inventory constraints. Parts dominate transaction value given high-frequency demand for brake, filtration, and powertrain components, yet Accessories generates disproportionate margin through lower price transparency and stronger brand loyalty effects. Professional Mechanics represent the fastest-growing customer type as fleet-scale garages consolidate purchasing through B2B portals with negotiated terms, while DIY Enthusiasts sustain higher per-basket values despite lower order frequency.
REACH and RoHS frameworks restrict hazardous substance content in aftermarket components, compelling platforms to verify supplier material declarations before listing eligibility. The EU Green Deal's right-to-repair provisions and ECHA substance restrictions are reshaping product assortments toward remanufactured and sustainably sourced alternatives. GDPR compliance adds operational cost to customer data handling across cross-border transactions. Stakeholders must monitor evolving CSRD disclosure requirements that will soon mandate supply chain emissions transparency from marketplace operators.
Market Dynamics
Professional mechanics across European garage networks are consolidating purchasing through B2B portals, compressing traditional distributor margins while demanding same-day fulfillment and VIN-accurate fitment guarantees that reshape platform infrastructure investments.
Growth Catalysts
- EU Green Deal repairability mandates:Vehicle longevity requirements accelerate platform investments in remanufactured parts catalogs, expanding addressable SKU pools beyond new OEM equivalents.
- Germany's logistics infrastructure:Dense automotive ownership and mature last-mile networks enable sub-24-hour delivery models that neighboring markets struggle to replicate.
- VIN-decoding technology:Automated fitment verification reduces return rates and builds mechanic trust, converting single-transaction buyers into recurring portal users.
Market Restraints
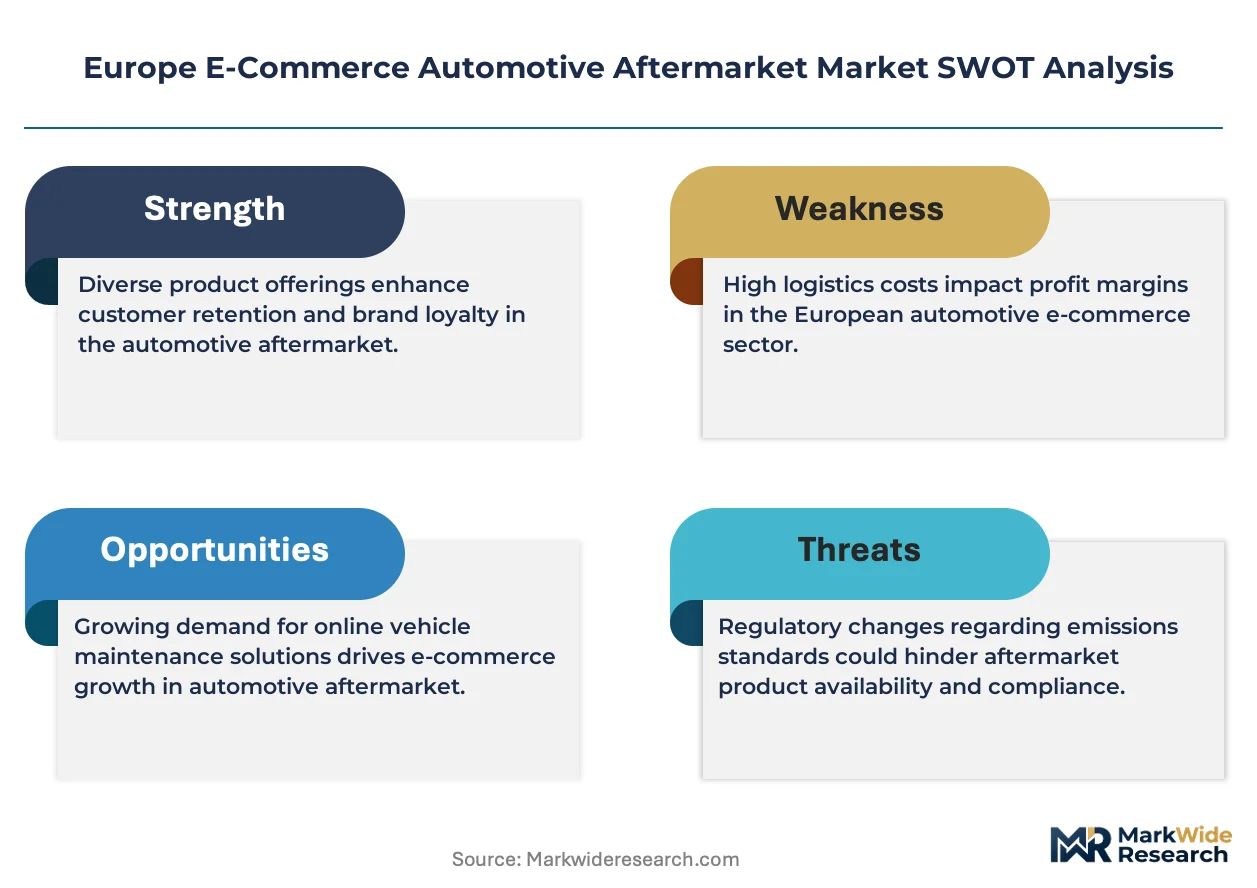
- REACH substance compliance costs:Material declaration verification for hazardous content restricts supplier onboarding velocity and elevates platform operational overhead.
- GDPR cross-border friction:Customer data handling requirements add procedural cost to transactions spanning multiple EU member states with divergent national implementations.
- Aluminum and rare earth input volatility:Brake component and powertrain part pricing fluctuates with commodity markets, compressing margin predictability for high-volume SKUs.
Strategic Opportunities
- Eastern European garage digitization:Poland and Romania present underpenetrated professional mechanic segments where centralized warehousing from German hubs could radiate cost-efficient coverage.
- CSRD supply chain transparency:Upcoming emissions disclosure mandates create first-mover advantage for platforms with verified carbon footprint data on remanufactured alternatives.
- AI-powered predictive inventory:Machine learning convergence with telematics data enables platforms to pre-position parts based on vehicle-age-driven failure probability models.
Industry Challenges
- E-mark certification timelines:Third-party quality verification for brake and filtration components delays supplier onboarding by 8-14 weeks, constraining platform SKU expansion velocity.
- Legacy garage management system integration:Independent workshops operate fragmented software environments, forcing platforms to maintain multiple API configurations for order ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Commerce Automotive Aftermarket Market |
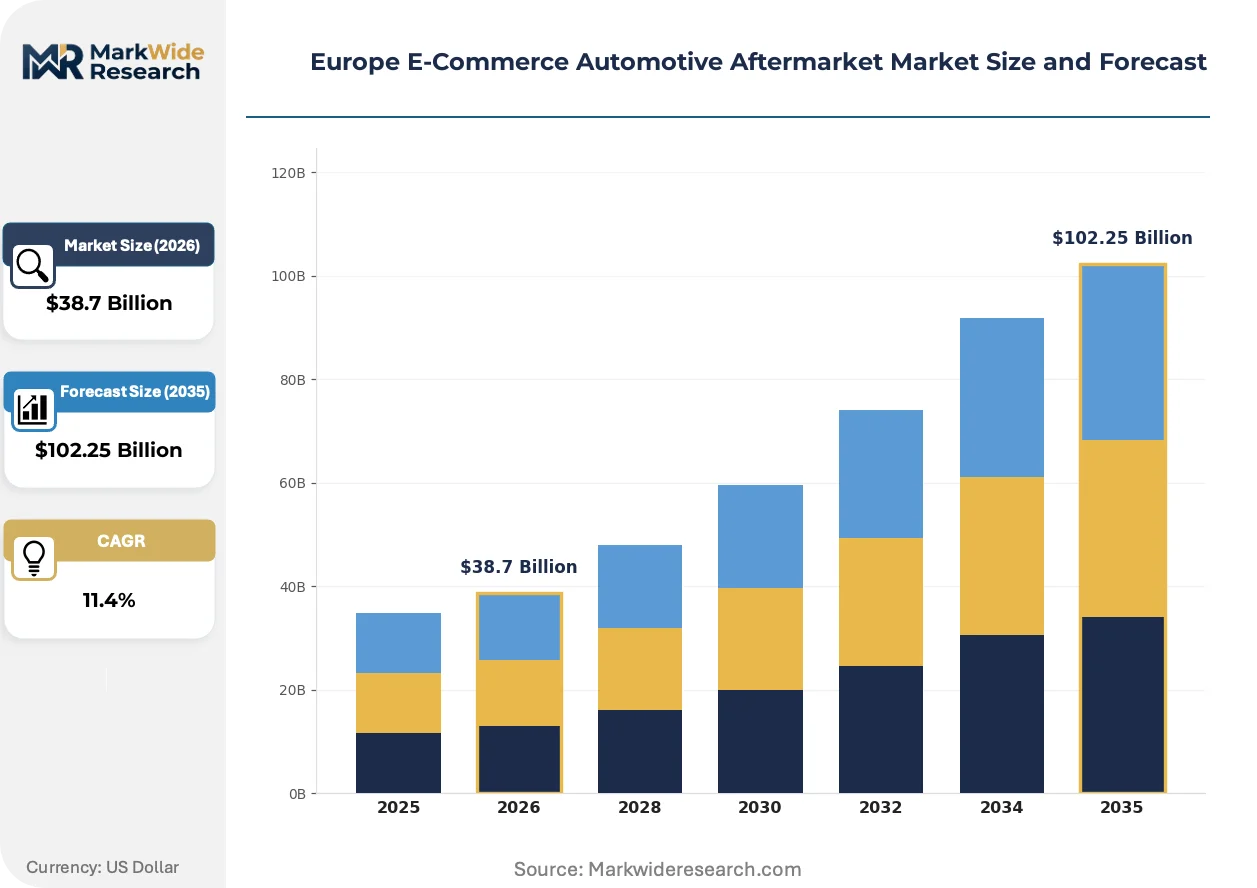
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parts, Accessories, Tools, Fluids Sales Channel: Online Retailers, Marketplaces, Brand Websites, Service Providers Customer Type: DIY Enthusiasts, Professional Mechanics, Fleet Operators, Retail Customers Delivery Mode: Direct Shipping, In-Store Pickup, Local Delivery, Subscription Services |
| Companies Covered | Bosch, Continental AG, ZF Friedrichshafen AG, Valeo SA, DENSO Corporation, Autodoc GmbH, Amazon, Euro Car Parts Limited, Mekonomen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Commerce Automotive Aftermarket Market Emerging Trajectories
Digital procurement infrastructure is rewriting competitive advantage in European automotive aftermarket distribution, with three converging forces reshaping how parts flow from manufacturer to bay.
AI-driven VIN-to-part matching engines are overtaking traditional catalog search methods in professional garage adoption. These systems parse 17-digit vehicle identifiers against real-time inventory databases, returning dimensional-compatible alternatives within seconds. German fleet-scale garages now mandate such capability in supplier selection criteria, compressing the competitive relevance of manual lookup interfaces.
REACH substance restrictions and RoHS hazardous material frameworks are tightening allowable content in friction materials and electronic components. Platform operators must now verify supplier material declarations before listing eligibility, with ECHA enforcement actions creating liability exposure for non-compliant intermediaries. Remanufactured brake and powertrain segments face disproportionate scrutiny as recycled content triggers heightened documentation requirements.
Consolidated purchasing through negotiated B2B portals is displacing ad-hoc transaction behavior among mid-size garage networks. Fleet-scale operators now demand volume-tiered pricing, dedicated account management, and integrated invoice reconciliation that standalone distributors cannot provision. This concentration is most visible in Benelux and northern Germany, where multi-site garage groups represent 40% of professional segment order flow.
Europe E-Commerce Automotive Aftermarket Market Segmentation
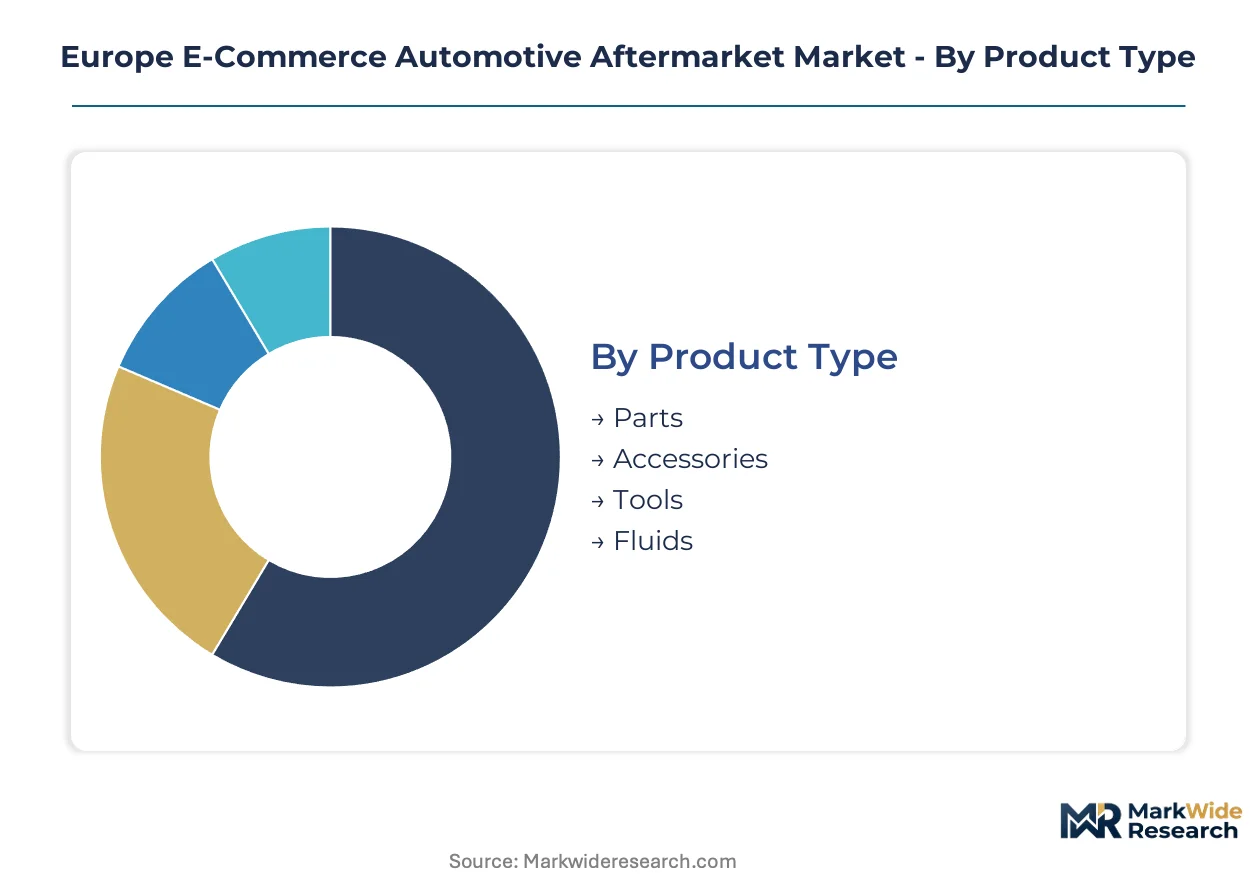
Segmentation in the Europe E-Commerce Automotive Aftermarket Market reveals how procurement behavior splits between mission-critical replacement cycles and discretionary upgrade purchases. Platform operators configure inventory depth, pricing algorithms, and fulfillment infrastructure differently for each segment cluster.
Product Type:
Standalone consumables dominate transaction frequency while embedded system components require VIN-verified fitment depth.
- Parts:Brake pads, filtration elements, and powertrain components constitute the revenue core, with German fleet garages driving bulk procurement through negotiated B2B portals. REACH substance compliance and E-mark certification constrain supplier onboarding velocity for friction materials.
- Accessories:Infotainment upgrades, exterior styling kits, and interior customization products generate disproportionate margin through weaker price transparency. Demand concentrates among DIY enthusiasts in Benelux markets where vehicle personalization carries cultural weight.
- Tools:Diagnostic equipment and specialized servicing implements support professional mechanic segments.
- Fluids:Engine oils, coolants, and brake fluids represent high-velocity replenishment cycles with standardized specifications.
Parts leads volumes today; Accessories is gaining share fastest.
Sales Channel:
Channel selection reflects buyer sophistication tiers, with integrated service bundles displacing pure product transactions among professional segments.
- Online Retailers:Specialized automotive platforms aggregate multi-brand catalogs with VIN-decoding infrastructure, capturing professional mechanic loyalty through same-day fulfillment guarantees. German logistics density enables sub-24-hour delivery models that anchor retention.
- Marketplaces:Third-party platforms expand SKU availability beyond captive inventory but introduce quality verification burdens. ECHA enforcement exposure for non-compliant intermediaries elevates operational risk in brake and powertrain categories.
- Brand Websites:Captive manufacturer channels control certification messaging and warranty integration.
- Service Providers:Garage-integrated procurement portals consolidate fleet-scale purchasing with invoice reconciliation automation.
Online Retailers command the largest transaction share; Service Providers show the steepest expansion trajectory.
Customer Type:
Procurement scale and technical specification depth separate commercial buyers from discretionary purchasers.
- DIY Enthusiasts:Individual vehicle owners sustain higher per-basket values despite lower order frequency, concentrating in northern European markets with strong repair culture. Price sensitivity elevates during economic compression cycles.
- Professional Mechanics:Garage network consolidation drives B2B portal adoption with volume-tiered pricing demands. GDPR cross-border data handling adds procedural cost to multi-national fleet operator transactions spanning German, French, and Polish jurisdictions.
- Fleet Operators:Commercial vehicle managers prioritize predictive maintenance integration and telematics-driven parts pre-positioning.
- Retail Customers:Occasional purchasers respond to promotional intensity and delivery speed guarantees.
Professional Mechanics anchor current revenue; Fleet Operators are expanding most quickly.
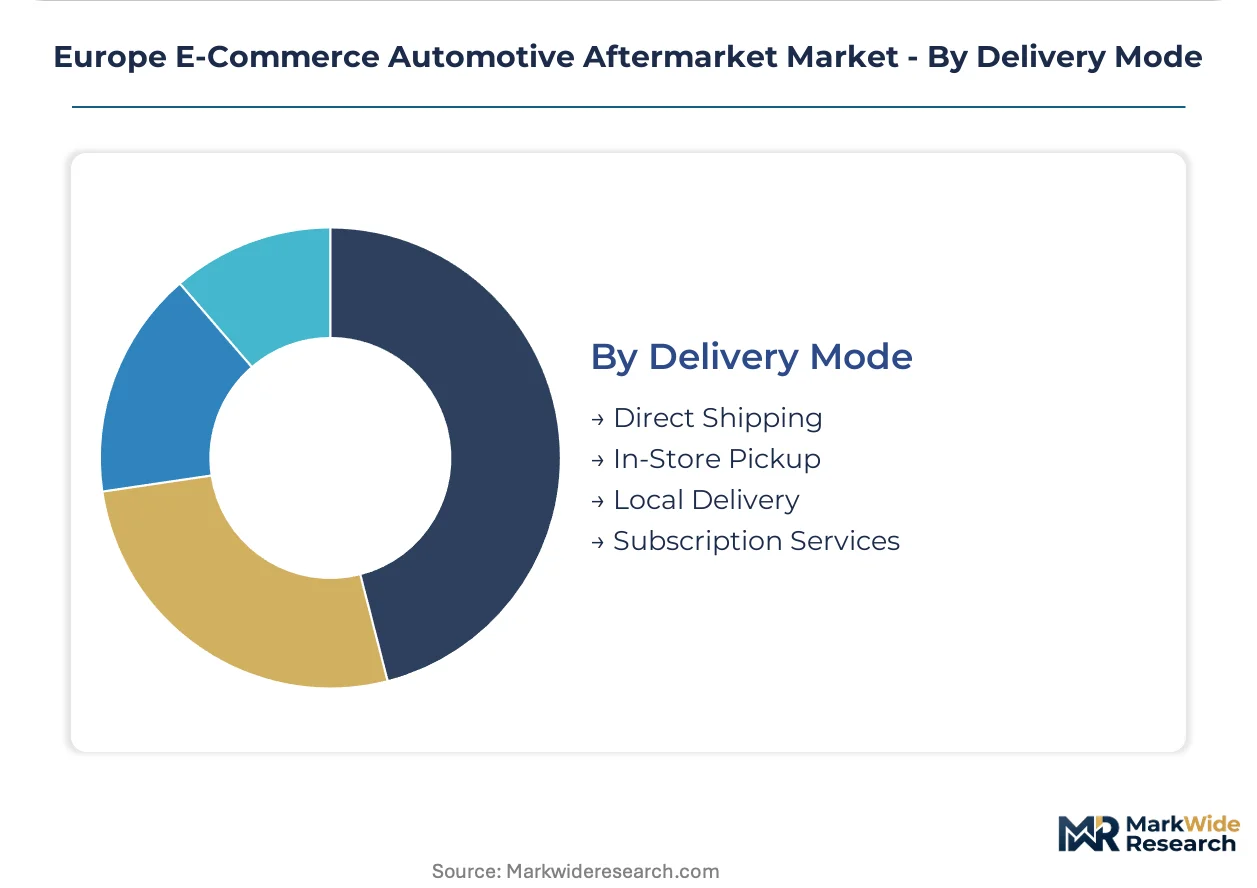
Delivery Mode:
Fulfillment configuration determines competitive viability in time-sensitive replacement scenarios.
- Direct Shipping:Centralized German warehousing radiates across European markets with varying last-mile efficiency. Poland and Romania present coverage gaps that elevate delivery timelines beyond professional mechanic tolerance thresholds.
- In-Store Pickup:Click-and-collect infrastructure leverages existing garage networks for immediate availability without inventory duplication.
- Local Delivery:Urban density in German and Benelux metropolitan clusters supports courier-based same-day models.
- Subscription Services:Predictable consumption patterns for fluids and filtration enable automated replenishment with locked pricing terms.
Direct Shipping carries the highest volume; Subscription Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance compliance costs diverge sharply across EU member states, pushing supplier verification operations toward jurisdictions with established chemical safety infrastructure. German and Dutch regulatory clarity attracts platform headquarters investment, while Eastern European markets absorb fulfillment expansion seeking lower last-mile density thresholds.
Germany
Dense automotive ownership and mature logistics networks enable sub-24-hour delivery models that professional mechanics now mandate. KBA vehicle registration databases integrate directly with platform VIN-decoding systems, accelerating fitment verification. The Stuttgart-Munich corridor hosts concentrated warehouse operations radiating across Central Europe.
United Kingdom
Post-Brexit customs friction elevates domestic fulfillment center investment against continental sourcing delays. Euro Car Parts Limited anchors national coverage from regional distribution nodes. The Midlands logistics cluster absorbs cross-channel inventory repositioning as operators seek regulatory alignment with EU safety standards.
France
Right-to-repair enforcement through ANSM creates demand pull for remanufactured brake and powertrain components. Paris-region garage networks digitize procurement through integrated B2B portals. The Lyon automotive supplier belt feeds platform inventory with E-mark certified friction materials.
Poland
Underpenetrated professional mechanic segments present expansion targets for German-hub radiating coverage models. Lower warehouse operating costs attract fulfillment infrastructure investment despite sparser last-mile networks. Warsaw-Krakow corridor development concentrates platform marketing spend on fleet-scale garage consolidation.
Netherlands
Rotterdam port access and Benelux distribution density position the country as cross-border inventory staging ground. GDPR implementation clarity reduces data handling friction for multi-national fleet operators. The Randstad metropolitan cluster supports same-day courier models for premium brake and filtration SKUs.
Europe E-Commerce Automotive Aftermarket Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue platform-native fulfillment architectures that bypass traditional distributor relationships. The market structures around three distinct competitive layers: captive manufacturers with certified production bases, pure-play digital aggregators with centralized warehousing, and marketplace intermediaries with expanded SKU reach. Consolidation pressures concentrate among mid-scale distributors lacking VIN-decoding infrastructure or same-day delivery guarantees. Dominant competitive moves include backward integration into captive manufacturing and strategic partnerships with fleet-scale garage networks.
Among Germany-based industrial conglomerates, Bosch and Continental AG exemplify the captive-manufacturer archetype, leveraging in-house production to control quality certification across digital channels. Autodoc GmbH occupies a position within the pure-play aggregator tier, anchoring competitive positioning on centralized warehousing with radiating last-mile coverage. These three entities represent divergent strategic paths: manufacturing control versus fulfillment velocity versus platform scale.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo SA |
| DENSO Corporation |
| Autodoc GmbH |
| Amazon |
| Euro Car Parts Limited |
| Mekonomen |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between E-mark verified friction materials and uncertified alternatives splits procurement economics across European garage networks, with premium tiers commanding supplier exclusivity through captive manufacturing while commodity SKUs face margin compression from aluminum and rare earth input volatility.
Pricing Analysis
Distributor margin layers collapse as B2B portals disintermediate traditional wholesale relationships, compressing markups from 35-40% toward 15-20% for high-volume brake and filtration SKUs. Price differentiation hinges on REACH compliance documentation density and VIN-decoding integration depth. Cost compression in remanufactured powertrain components intensifies as platforms compete for EU Green Deal procurement mandates. DIY enthusiasts exhibit highest price sensitivity, while fleet-scale garage networks prioritize same-day fulfillment guarantees over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in Czech and Polish manufacturing zones elevate labor costs for precision-machined brake components, pushing production gravity toward German and Romanian automotive supplier belts. Raw material dependencies center on aluminum alloys, copper wiring, and rare earth magnets for electronic control modules. Single-source vulnerability concentrates in Chinese-sourced friction material substrates. Distribution runs through centralized German warehousing with radiating last-mile coverage, though Poland and Romania present coverage gaps that elevate delivery timelines beyond professional mechanic tolerance thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe E-Commerce Automotive Aftermarket operates as a stable compounder, with vehicle fleet aging and right-to-repair enforcement generating predictable replacement part demand across economic cycles.
For Market Incumbents: Anchor competitive position through backward integration into remanufactured brake and powertrain production, securing EU Green Deal procurement eligibility ahead of CSRD disclosure mandates. Consolidate garage network relationships through dedicated B2B portal development with integrated invoice reconciliation, countering pure-play digital aggregators threatening distributor margins. For New Entrants and Emerging Players: Mid-size garage networks in Poland and Romania represent the most penetrable buyer archetype, with fragmented procurement habits and limited VIN-decoding infrastructure creating white-space opportunity. Target fleet-scale operators in Warsaw-Krakow corridor with German-hub fulfillment guarantees and volume-tiered pricing, bypassing incumbent distributor relationships through direct platform engagement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale distributors lack same-day delivery infrastructure or E-mark certification capabilities. Long-term viability favors platforms with verified carbon footprint data on remanufactured alternatives and established GDPR-compliant cross-border data handling. Monitor ECHA enforcement action intensity as inflection indicator for platform liability exposure and supplier onboarding velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Remanufacturing | Captive production of EU Green Deal-compliant brake components secures platform eligibility ahead of CSRD mandates. |
| VIN-Decoding Infrastructure Investment | Automated fitment verification reduces return rates and converts single-transaction mechanics into recurring portal users. |
| Centralized Warehousing Expansion | German-hub radiating coverage models compress delivery timelines to sub-24-hour guarantees for Benelux and northern France. |
| GDPR-Compliant Data Architecture | Cross-border transaction handling infrastructure reduces procedural cost for multi-national fleet operator procurement. |
| AI-Powered Predictive Inventory | Machine learning convergence with telematics data enables pre-positioning based on vehicle-age-driven failure probability models. |
Methodological Framework
Multiple input streams — structured interviews with platform procurement directors, garage network operations managers, and Tier 1 supplier sales executives; trade data from German KBA registration databases and IHS Markit vehicle production statistics; and regulatory filings from ECHA and national REACH implementation bodies — were reconciled through bottom-up SKU-level aggregation and top-down market sizing triangulation.
Historical transaction velocity patterns were cross-referenced against panel input from fleet-scale garage operators to model adoption curves across the projection horizon. Segmentation dimensions included product type, customer archetype, sales channel, and delivery mode, with CAGRs derived from logistic curve fitting to professional mechanic digitization rates and remanufactured part catalog expansion trajectories. Forecast inputs incorporated REACH substance restriction enforcement timelines and EU Green Deal procurement mandate rollout patterns.
Underlying measurement precision varies by segment; Parts and Professional Mechanics carry tighter precision than Accessories and DIY Enthusiasts due to consolidated B2B reporting transparency. Forecasts reflect assumptions regarding garage network consolidation velocity and E-mark certification timeline stability. Material deviation in ECHA enforcement intensity or aluminum commodity pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market