
 Global Road Maintenance Market | 2026-2036
Global Road Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Road Maintenance Market Outlook
Performance-based road maintenance contracts is hardening as the dominant service layer, shifting risk from public agencies to private operators and bundling decades of upkeep into single procurement vehicles. Ferrovial Services leverages its concession expertise across European toll networks to capture long-dated revenue streams. Skanska AB anchors its Nordic base while competing for complex rehabilitation tenders in North America.
Road maintenance encompasses the periodic inspection, repair, resurfacing, and structural renewal of paved and unpaved thoroughfares to preserve load-bearing capacity, ride quality, and safety performance; asphalt overlay applications typically deploy hot-mix binder courses 40-75 mm thick to restore surface integrity without full-depth reconstruction. Pavement repair commands the largest share of current spending due to backlog accumulation on aging networks, while smart road technologies represent the fastest-expanding segment as embedded sensors enable predictive intervention models. Eco-friendly materials occupy a niche but growing margin pool where polymer-modified binders and warm-mix formulations meet tightening carbon thresholds.
FHWA standards in the United States, the EU Green Deal framework, and ISO 9001 quality management protocols collectively shape material specifications, contractor eligibility, and environmental compliance across jurisdictions. The EPA's stormwater runoff rules and REACH chemical restrictions in Europe further constrain binder formulations and disposal practices. Stakeholders must monitor how evolving carbon accounting requirements will reshape competitive positioning between traditional asphalt suppliers and emerging bio-based material developers.
Market Dynamics
Performance-based contracting is consolidating decades of fragmented road upkeep into single-source agreements that transfer operational risk from municipal agencies to specialized contractors, fundamentally restructuring how public infrastructure budgets convert into executed work.
Growth Catalysts
- EU Green Deal carbon mandates:Binding low-carbon material requirements across member states are accelerating substitution of conventional hot-mix asphalt with warm-mix and bio-based binder formulations in resurfacing contracts.
- India's highway expansion pipeline:National highway development programs are generating sustained maintenance investment as newly constructed corridors mature into rehabilitation cycles.
- Embedded sensor networks:Predictive pavement management systems using IoT-enabled structural monitoring are reducing emergency repair frequency and optimizing overlay timing for network operators.
Market Restraints
- Bitumen price volatility:Crude oil-linked input costs create margin compression for asphalt suppliers unable to pass through fluctuations on fixed-price municipal contracts.
- Specialized contractor concentration:Long-dated concession expertise resides with a limited pool of European operators, constraining competitive entry in emerging markets.
- Warm-mix performance gaps:Reduced production temperatures can compromise binder adhesion in high-stress applications, limiting deployment on heavy freight corridors.
Strategic Opportunities
- Secondary Indian cities:State-level urban road programs outside national highway networks remain undersupplied by performance-based maintenance specialists.
- Reclaimed asphalt pavement integration:Circular material mandates in European public procurement are creating premium positioning for contractors with advanced RAP processing capabilities.
- Digital twin convergence:Integration of LiDAR survey data with structural modeling software enables condition-based intervention scheduling that reduces lifecycle costs for asset managers.
Industry Challenges
- Pavement engineering specialization:Shortage of professionals trained in mechanistic-empirical design methods limits contractor capacity to execute complex rehabilitation tenders.
- Multi-decade contract execution:Performance agreements spanning 20-30 years expose operators to climate adaptation costs and traffic load uncertainties that strain financial modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Road Maintenance Market |
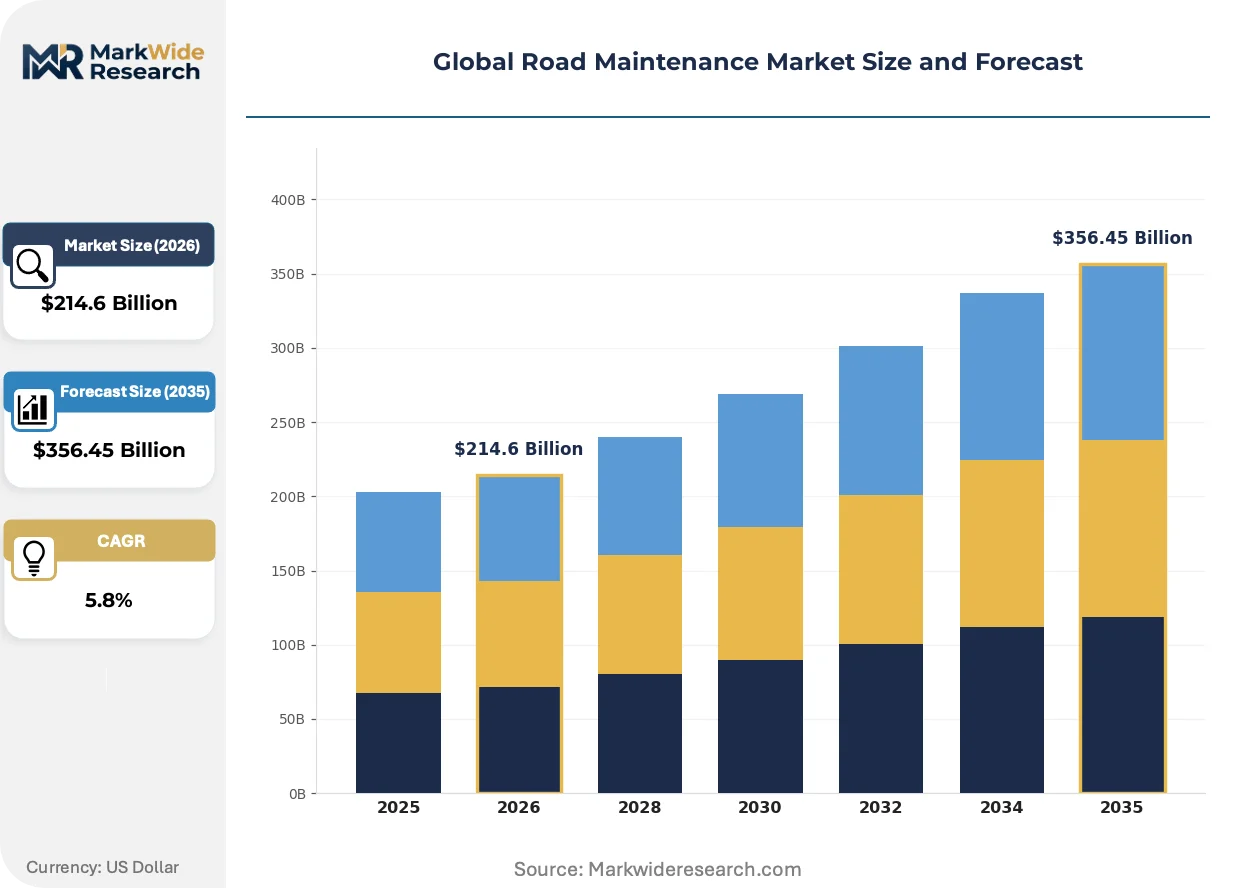
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pavement Repair, Surface Treatment, Road Rehabilitation, Asphalt Overlay End User: Government Agencies, Construction Firms, Private Contractors, Municipalities Material: Asphalt, Concrete, Bitumen, Eco-Friendly Materials Technology: Traditional Methods, Smart Road Technologies, Recycled Material Use, Automated Solutions |
| Companies Covered | Balfour Beatty, Ferrovial Services, Vinci SA, Jacobs Engineering Group Inc., Skanska AB, AECOM, Eurovia, Kier Group, Colas Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Road Maintenance Market Strategic Shifts
Digital infrastructure is penetrating road networks at the material layer, with sensing technologies and low-carbon binders converging to transform how agencies predict failure modes and procure intervention services.
Warm-mix asphalt formulations incorporating chemical additives and foaming processes are absorbing market share from conventional hot-mix production across European and North American resurfacing programs. State departments of transportation in the United States are specifying reduced-temperature binders on federally aided projects to meet EPA emissions thresholds. The technology is absorbing capital allocation previously directed toward plant emissions control equipment, compressing the cost structure of compliant production.
REACH chemical restrictions in Europe are tightening permissible thresholds for polycyclic aromatic hydrocarbons in paving binders, forcing reformulation of traditional penetration-grade bitumens. Refiners are investing in hydrotreating capacity to produce cleaner base stocks that maintain rheological performance. Pavement contractors in Germany and France are experiencing accelerated qualification timelines as agencies verify compliance with evolving hazard classifications.
Municipal procurement offices are consolidating fragmented annual maintenance budgets into multi-year performance contracts that bundle inspection, routine repair, and structural renewal. This aggregation is displacing spot-market asphalt purchases and small-scale resurfacing awards that dominated prior decades. The shift is most visible in Nordic countries where transport agencies have transferred network condition risk to concession operators on arterial road systems.
Global Road Maintenance Market Segmentation
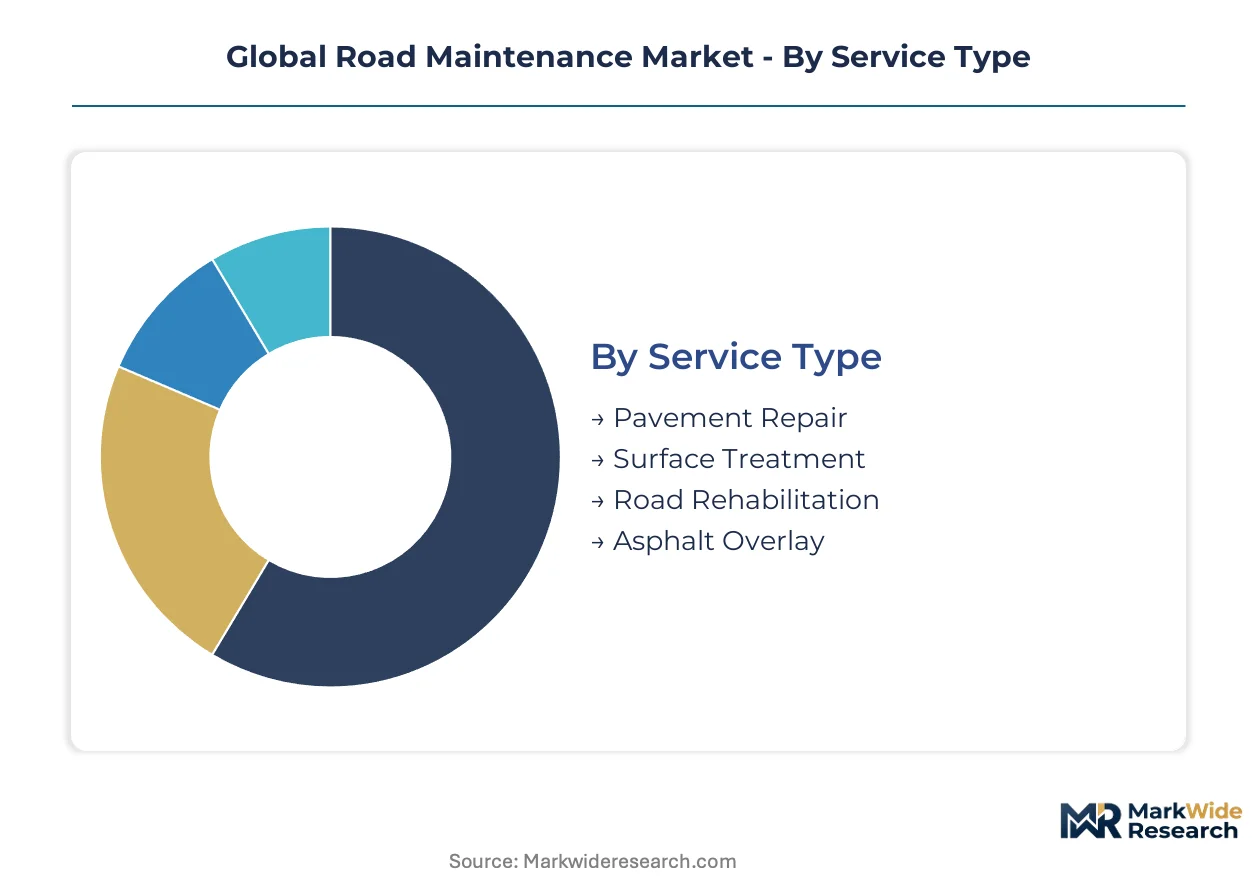
Road maintenance procurement fragments across service delivery models, material specifications, and technology maturity levels. Understanding these divides reveals where contract value concentrates and which capability investments yield competitive position.
Service Type:
Standardized spot repairs contrast with multi-decade bundled agreements that transfer network condition risk to operators.
- Pavement Repair:Crack sealing, pothole patching, and localized structural fixes address surface distress without full reconstruction. Municipal agencies in the United States concentrate spending here as FHWA-mandated condition ratings trigger emergency interventions on interstate corridors.
- Road Rehabilitation:Full-depth reconstruction, base stabilization, and drainage renewal restore load-bearing capacity on failed sections. India's national highway development programs are driving sustained investment as newly constructed corridors mature into heavy rehabilitation cycles.
- Surface Treatment:Chip seals, slurry seals, and micro-surfacing extend pavement life through preventive applications.
- Asphalt Overlay:Hot-mix or warm-mix binder courses restore ride quality without structural reconstruction.
Most installed capacity flows through Pavement Repair. Expansion is steepest in Road Rehabilitation.
End User:
Procurement scale ranges from fragmented municipal spot contracts to consolidated national framework agreements.
- Government Agencies:Federal and state transport departments specify performance standards, material certifications, and environmental compliance thresholds. The EU Green Deal is accelerating low-carbon material mandates across member state procurement frameworks.
- Private Contractors:Specialized operators assume network condition risk through long-dated concession arrangements. Nordic countries have transferred arterial road maintenance risk to concession operators under 20-30 year performance contracts.
- Construction Firms:General contractors execute discrete rehabilitation projects within capital improvement programs.
- Municipalities:Local governments manage neighborhood and collector road networks through annual maintenance budgets.
Government Agencies command the largest contract volume. Private Contractors are gaining share fastest through performance-based models.
Material:
Carbon intensity now differentiates material selection as procurement rules harden around lifecycle emissions accounting.
- Asphalt:Hot-mix and warm-mix formulations dominate resurfacing applications with established supply chains and contractor familiarity. REACH chemical restrictions in Europe are forcing reformulation of traditional penetration-grade bitumens to reduce polycyclic aromatic hydrocarbon content.
- Eco-Friendly Materials:Bio-based binders, warm-mix additives, and polymer-modified formulations meet tightening carbon thresholds. State departments of transportation in the United States are specifying reduced-temperature binders on federally aided projects to satisfy EPA emissions requirements.
- Concrete:Portland cement concrete provides structural durability on high-load freight corridors and bridge decks.
- Bitumen:Unmodified penetration-grade binders serve low-traffic applications with minimal specification requirements.
Asphalt retains the largest installed base. Eco-Friendly Materials are climbing the fastest as carbon accounting reshapes procurement.
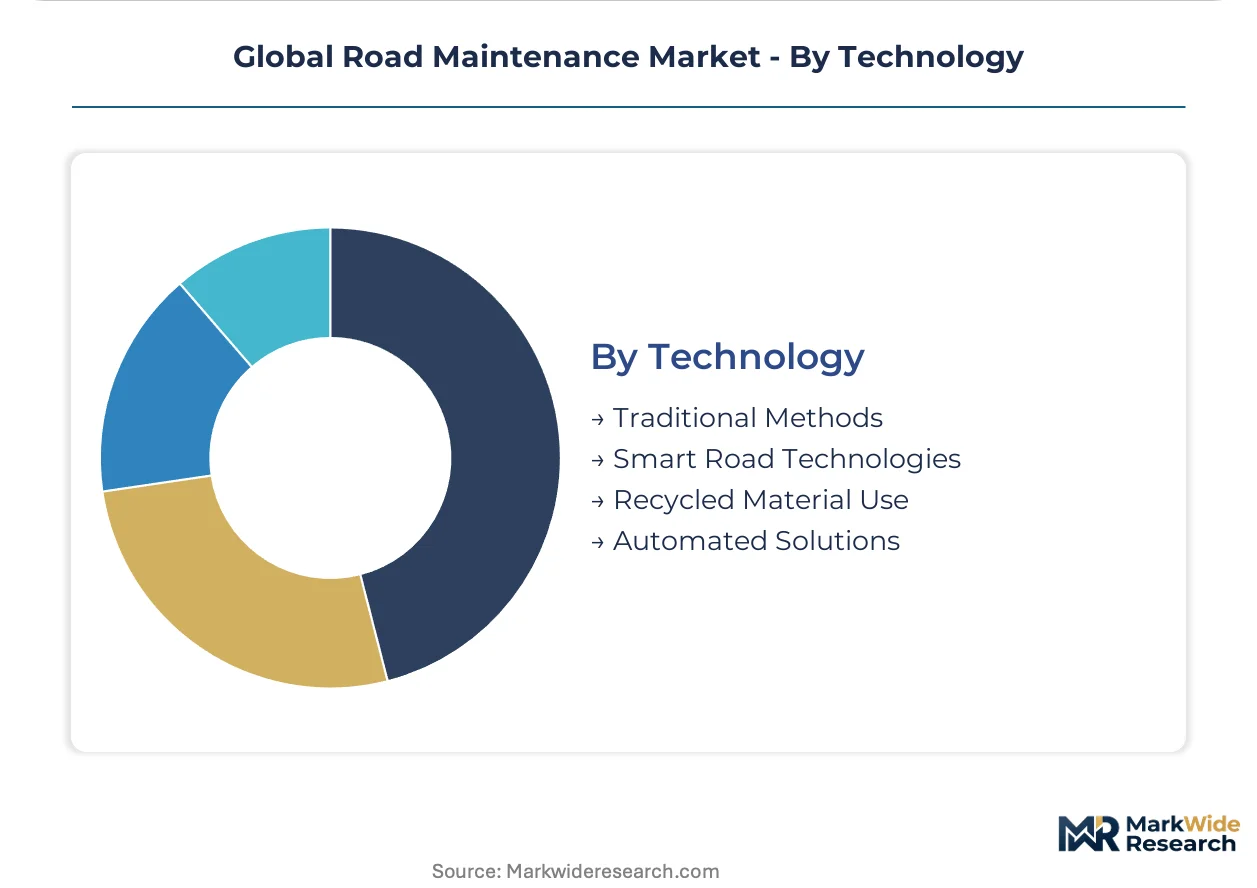
Technology:
Digital infrastructure investment separates predictive maintenance operators from reactive repair contractors.
- Smart Road Technologies:Embedded strain gauges, temperature sensors, and accelerometers enable real-time structural monitoring. IoT-enabled pavement management systems are reducing emergency repair frequency for network operators by optimizing overlay timing based on actual condition data.
- Recycled Material Use:Reclaimed asphalt pavement processing and warm-mix production reduce virgin material consumption. Circular material mandates in European public procurement are creating premium positioning for contractors with advanced RAP capabilities.
- Traditional Methods:Visual inspection and scheduled maintenance cycles persist where sensor infrastructure investment lacks budget justification.
- Automated Solutions:Robotic crack sealing and autonomous milling equipment address labor scarcity in high-cost markets.
Traditional Methods still dominate execution volume. Smart Road Technologies are gaining share fastest as asset managers adopt predictive intervention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is driving contractor migration toward jurisdictions with lower compliance costs for warm-mix asphalt production. The EU Green Deal's carbon accounting rules have widened the cost-of-compliance gap between member states and emerging markets. India and the United States now attract investment from European operators seeking to escape REACH chemical restrictions and extended producer responsibility frameworks.
United States
FHWA-mandated condition ratings on interstate corridors trigger emergency pavement interventions that concentrate contractor activity around state DOT procurement offices. EPA stormwater runoff rules constrain binder formulations and disposal practices for resurfacing contracts. Texas and California anchor the heaviest maintenance spending, with Houston's Gulf Coast freight corridors generating sustained overlay demand.
Germany
REACH chemical restrictions on polycyclic aromatic hydrocarbons force rapid reformulation of penetration-grade bitumens across federal highway networks. The KBA enforces construction quality standards that extend contractor qualification timelines for public tenders. Bavaria's autobahn maintenance clusters around Munich and Nuremberg concentrate specialized rehabilitation capacity.
India
National highway development programs mature into heavy rehabilitation cycles that sustain contractor deployment across state border corridors. BIS material certification requirements govern asphalt specifications for NHAI-funded projects. Maharashtra's Mumbai-Pune Expressway and Gujarat's freight corridors generate concentrated demand for performance-based maintenance specialists.
France
EU Green Deal low-carbon mandates accelerate warm-mix and bio-based binder substitution in resurfacing contracts awarded by regional transport authorities. ANSM oversight of construction chemical safety shapes additive approval timelines for pavement formulations. The Lyon-Grenoble corridor and Paris peripheral networks concentrate advanced rehabilitation contractor presence.
United Kingdom
Highways England framework agreements consolidate fragmented municipal maintenance into multi-year performance contracts that transfer network condition risk. HSE workplace safety rules govern hot-work permitting for asphalt production facilities. The Midlands and Northern Powerhouse road networks attract concession operators seeking long-dated revenue streams.
Global Road Maintenance Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with concession operators capturing extended revenue streams while construction firms compete for discrete project awards. The market structure tiers around scale: integrated infrastructure groups with decades of concession expertise occupy the premium layer, regional contractors execute spot maintenance, and material suppliers feed both tiers. Three archetypes dominate: performance-based concession specialists, rehabilitation-focused construction firms, and integrated asphalt producers with downstream contracting arms. Competitive moves concentrate on M&A to acquire concession portfolios and strategic partnerships to secure RAP processing capabilities for circular material mandates.
Among European-based infrastructure specialists, Ferrovial Services, Skanska AB, and Vinci SA exemplify the concession-driven archetype. Ferrovial Services leverages its toll network expertise across Iberian and Latin American markets. Skanska AB anchors its Nordic base while extending into North American rehabilitation tenders. Vinci SA occupies a position spanning French domestic networks and international framework agreements. These operators sit within a tier where long-dated contract execution capability separates viable bidders from spot-market competitors.
| Leading Market Players |
|---|
| Balfour Beatty |
| Ferrovial Services |
| Vinci SA |
| Jacobs Engineering Group Inc. |
| Skanska AB |
| AECOM |
| Eurovia |
| Kier Group |
| Colas Group |
| Others |
Value Chain & Pricing Dynamics
Municipal procurement offices in Nordic countries and Germany anchor contract aggregation, concentrating buyer power into multi-year performance agreements that compress spot-market pricing and favor operators with concession execution capability.
Pricing Analysis
Capacity additions in India are reshaping price floors for asphalt overlay services as state-level urban road programs expand contractor pools beyond established European operators. Project-based long-term contracting dominates, with price differentiation resting on RAP processing certification and warm-mix technology qualification. Cost compression in standard pavement repair is intensifying because crude-linked bitumen volatility strains fixed-price municipal agreements. State transport departments exhibit highest price sensitivity, while toll network concessionaires prioritize lifecycle cost predictability over unit rates.
Supply Chain Analysis
Domestic-content mandates in India's NHAI-funded projects are reshaping sourcing patterns, forcing international contractors to establish local asphalt production partnerships. Supply concentration centers on Germany, the United States, and India for specialized rehabilitation equipment and polymer-modified binder formulations. Raw material dependencies include crude-derived bitumen, limestone aggregate, and chemical warm-mix additives. Single-source vulnerability runs through European hydrotreating capacity for low-PAH base stocks. Distribution feeds through regional asphalt plant networks serving 50-100 kilometer radius catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Road Maintenance Market functions as a stable compounder, with urbanization-driven infrastructure budgets providing predictable demand visibility across economic cycles.
For Market Incumbents: Acquire concession portfolios in maturing Indian highway corridors before state-level tender consolidation accelerates. Defensive positioning requires securing advanced RAP processing certification under EU circular material mandates, while expanding warm-mix production capacity to offset margin pressure from REACH chemical compliance costs. Threat substitution from bio-based binder developers demands backward integration into additive formulation expertise. For New Entrants and Emerging Players: The price-point gap between premium performance-based operators and economy spot-repair contractors creates entry opportunity in secondary Indian cities where state urban road programs lack specialized maintenance capacity. White-space targets include Maharashtra and Gujarat state road networks outside NHAI corridors, plus digital twin integration services for mid-sized municipal agencies. Go-to-market positioning should anchor on IoT-enabled predictive maintenance as a lower-cost alternative to full concession risk transfer. For Investors and Strategic Acquirers: Infrastructure funds with toll road expertise are the most active acquirer in this space, seeking concession operators with 15-plus year contract backlogs. Long-term viability frames around climate adaptation cost absorption capabilities and traffic load forecasting accuracy. Acquisition target archetype: mid-cap European contractors with underexploited RAP processing assets. The signal to watch is BIS certification timeline compression in India, which would accelerate competitive entry by qualified international operators.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contract Expansion | Transfers network condition risk from NHAI to specialized operators under 20-30 year terms. |
| Warm-Mix Technology Certification | Meets EPA emissions thresholds and EU Green Deal carbon mandates for federal aid eligibility. |
| Reclaimed Asphalt Pavement Integration | Positions contractors for circular material mandates in European public procurement frameworks. |
| Digital Twin Platform Deployment | Reduces lifecycle costs for asset managers through LiDAR-integrated condition monitoring. |
| Secondary City Market Entry | Captures undersupplied state urban road programs outside national highway networks in India. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pavement engineering directors, municipal procurement officers, concession operators, and asphalt plant managers with secondary validation against FHWA condition rating databases, EU transport expenditure reports, NHAI project disclosures, and BIS material certification records. Bottom-up project pipeline analysis and top-down infrastructure budget triangulation anchored market sizing.
Historical maintenance spending patterns across comparable contract maturity cycles informed the projection horizon, with segmentation modeling across service type, material specification, technology maturity, and end-user procurement scale. CAGRs derived from network age distribution analysis, urbanization trajectory correlation, and carbon mandate implementation timelines. Forecast inputs incorporated bitumen price volatility assumptions and embedded sensor adoption curves for predictive intervention systems.
Caveats apply where bitumen price spikes, REACH chemical restriction acceleration, or Indian state-level procurement fragmentation could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market