
 Car and Truck Wash Market | 2026-2036
Car and Truck Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Car and Truck Wash Market Analysis
Asset-light subscription and lease-based equipment financing is fragmenting capital requirements across the Car and Truck Wash landscape. Mister Car Wash leverages its scale to dominate express tunnel rollouts in Sun Belt metros. Alfred Kärcher SE and Co. KG anchors European supply through manufacturing pressure systems and water recovery hardware. Spotless Brands competes via multi-brand rollup strategies that consolidate fragmented regional operators.
Car and truck wash services comprise mechanized, semi-automated, or manual cleaning systems utilizing high-pressure water jets, biodegradable detergents, and reclaim systems to remove road film, salt, and contaminants from vehicle exteriors and undercarriages. Automatic service formats lead volume throughput in suburban retail zones, while mobile units capture fleet contracts at logistics yards and construction sites. Waterless technology segments attract regulatory scrutiny in drought-prone jurisdictions, pressuring operators to validate chemical runoff profiles. Subscription services through online booking channels now sustain recurring revenue pools that outperform single-visit vending formats.
EPA effluent guidelines and state-level water board regulations in California, Texas, and Florida mandate reclaim rates and restrict discharge chemistry, elevating compliance costs for independent operators. OSHA workplace safety standards govern chemical handling and enclosed-bay ventilation, shaping equipment specifications and facility design. Stakeholders must monitor evolving state water budgets and reclaim technology maturation to calibrate capital deployment between express tunnels and mobile fleet services.
Market Dynamics
Water reclamation mandates from the EPA and state-level environmental agencies are forcing capital reallocation toward closed-loop filtration systems, compressing margins for independent operators while advantaging scaled tunnel networks.
Growth Catalysts
- California Water Board regulations:Mandated reclaim rates above 80% for new facilities drive equipment upgrade cycles and create captive demand for filtration hardware suppliers.
- Fleet outsourcing contracts:Logistics firms operating class-8 trucks and last-mile delivery vans are consolidating maintenance spend with national wash networks rather than maintaining in-house bays.
- Biodegradable surfactant chemistry:Advanced enzymatic detergents enable compliance with discharge restrictions while reducing water consumption per vehicle.
Market Restraints
- Stainless steel and polymer input volatility:Tunnel equipment fabrication depends on commodity metals and specialized resins subject to tariff and energy cost swings.
- Concentrated equipment supply:High-pressure pump and reclaim system manufacturing clusters in Germany and Italy create geographic supply risk for North American operators.
- Waterless chemical substitution limits:Drought-prone jurisdictions scrutinize runoff profiles of spray-on cleaners, constraining adoption despite scarcity pressures.
Strategic Opportunities
- Texas municipal water budgets:State infrastructure funding for reclaimed water distribution creates co-location opportunities for tunnel operators near utility trunk lines.
- Subscription booking platforms:Mobile app-based membership models convert single-visit customers into recurring revenue pools with predictable utilization rates.
- IoT sensor convergence with reclaim systems:Real-time turbidity and flow monitoring enables predictive maintenance and automated compliance reporting.
Industry Challenges
- Certified wastewater technician scarcity:EPA-mandated operator training for closed-loop systems creates hiring bottlenecks in secondary metros.
- Legacy bay retrofit complexity:Self-service sites built before 2010 require structural reinforcement and electrical upgrades to accommodate modern reclaim equipment.
- Integration friction with fleet telematics:Enterprise customers demand API connectivity between wash scheduling and vehicle tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car and Truck Wash Market |
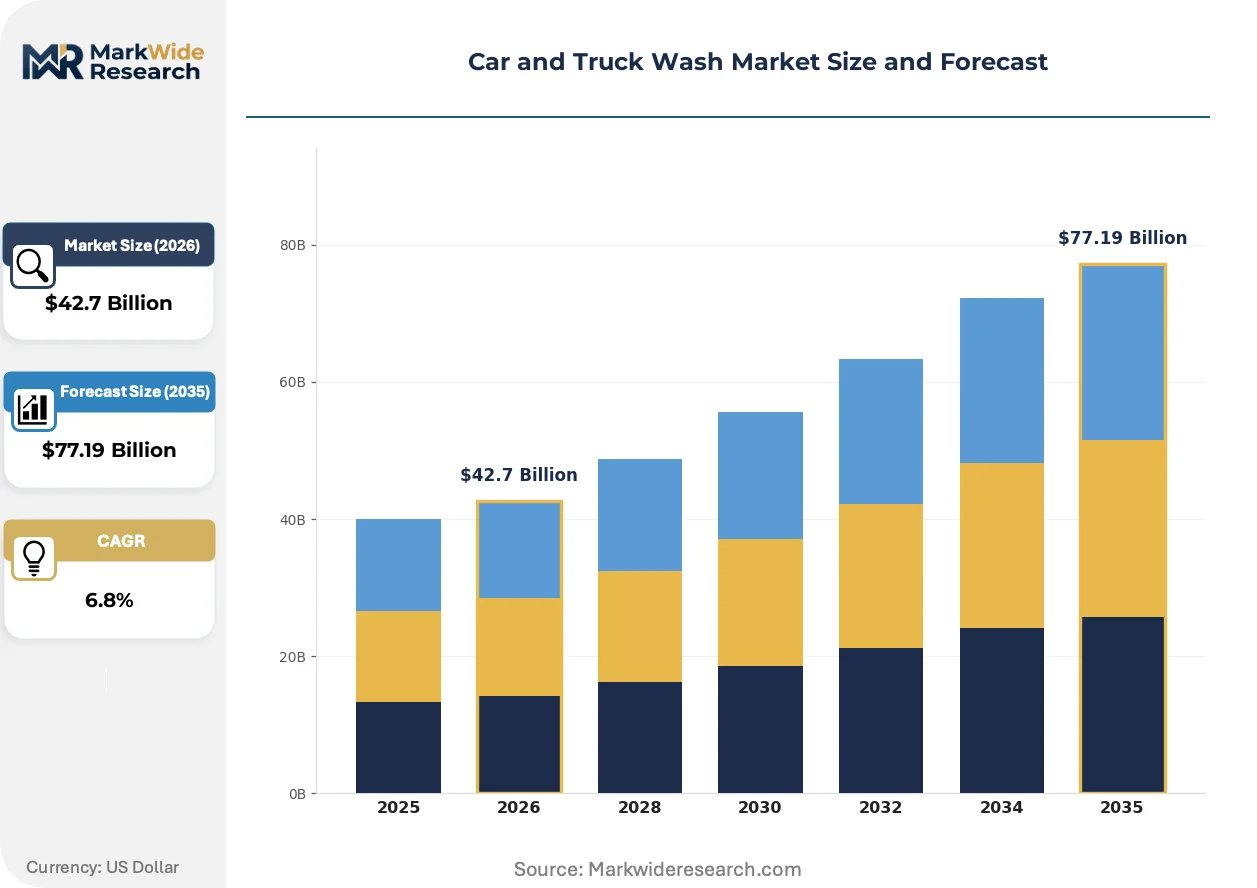
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service, Full-Service, Automatic, Mobile Customer Type: Individual Owners, Fleet Operators, Rental Companies, Commercial Vehicles Technology: Waterless, Pressure Washing, Foam, Steam Cleaning Sale Channel: Direct Sales, Online Booking, Subscription Services, Vending Machines |
| Companies Covered | Whistle Express Car Wash, WetGo Car Wash, Mister Car Wash, Crew Carwash, Delta Sonic, Tidal Wave Auto Spa, Spotless Brands, Alfred Kärcher SE and Co. KG, Quick Quack Express Car Wash, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car and Truck Wash Market Emerging Trajectories
Digital infrastructure and sensor networks are transforming vehicle wash operations from mechanical vending into data-driven service platforms that optimize throughput and compliance simultaneously.
License plate recognition and automated entry systems are digitizing customer identification and payment processing. Express tunnel operators deploy these tools to eliminate friction at entry gates, compressing transaction time from 45 seconds to under 10 seconds. Fleet accounts benefit from automated billing reconciliation tied to vehicle registration databases.
EPA effluent guidelines under the Clean Water Act are tightening discharge limits for commercial wash operations. Operators in Florida and Texas face new reporting requirements for total suspended solids and chemical oxygen demand. Scaled networks respond by deploying centralized water quality monitoring dashboards that aggregate data across multiple sites.
Fleet procurement teams now bundle wash services with fuel card and maintenance contracts through integrated vendor platforms. Third-party logistics firms negotiate enterprise rates that undercut single-visit retail pricing by 30-40%. This consolidation concentrates buying power among national accounts and pressures regional operators to join branded networks or exit fleet segments entirely.
Car and Truck Wash Market Segmentation
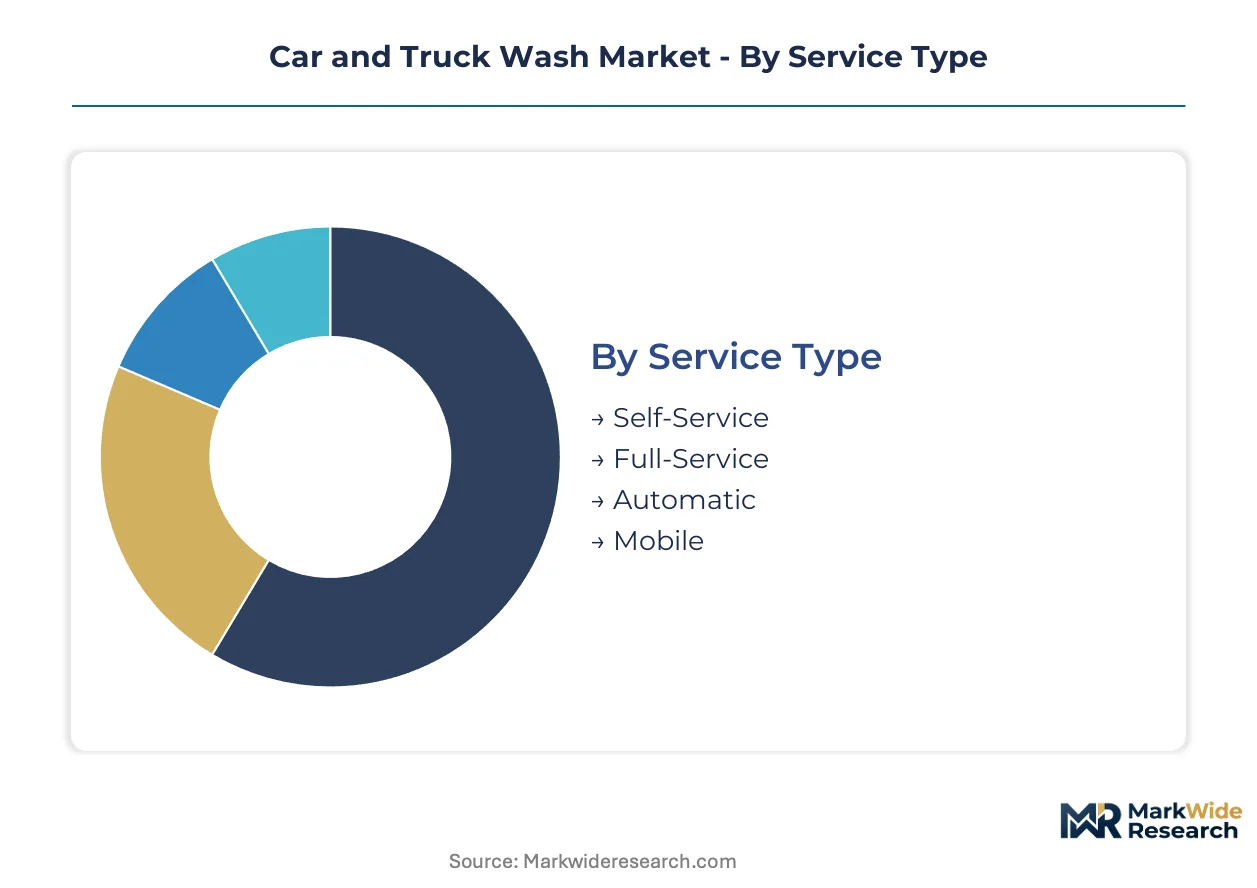
Segmentation in the car and truck wash market exposes divergent capital intensity and regulatory exposure across service formats. Each dimension reveals distinct margin structures and customer lifetime value profiles that shape operator strategy.
Service Type:
Cost tier determines equipment depreciation schedules and labor requirements across facility formats.
- Self-Service:Coin- or card-activated bay systems where customers apply high-pressure wands and foaming brushes. Demand concentrates in secondary metros and rural corridors where land costs support lower throughput economics. EPA reclaim mandates in California and Texas force retrofits that raise per-bay capital requirements.
- Full-Service:Attendant-managed interior and exterior cleaning with detailing add-ons. Fleet accounts in Florida logistics corridors sustain volume during retail troughs. Labor scheduling complexity and OSHA ventilation standards compress margins relative to automated alternatives.
- Automatic:Tunnel or in-bay rollover systems processing vehicles through fixed wash cycles. Express tunnel configurations dominate suburban retail zones in Sun Belt states.
- Mobile:Truck-mounted or trailer-based units delivering on-site service to fleet yards and construction sites. Waterless chemistry variants face discharge scrutiny in drought-prone jurisdictions.
Automatic holds installed capacity. Mobile is rotating up the share rankings.
Customer Type:
Application focus separates recurring fleet contracts from discretionary retail visits.
- Individual Owners:Retail consumers purchasing single washes or monthly subscriptions through mobile apps. Subscription models in Texas and California convert these accounts into predictable revenue pools with 40-60% higher annual spend than pay-per-visit customers.
- Fleet Operators:Logistics firms, delivery services, and utility fleets outsourcing vehicle maintenance to national wash networks. Class-8 truck and last-mile van segments in Florida consolidate spend with branded operators offering telematics integration.
- Rental Companies:Vehicle return preparation and fleet turnover cleaning with standardized turnaround time requirements.
- Commercial Vehicles:Construction equipment, agricultural machinery, and municipal truck cleaning with heavy soil loads and undercarriage corrosion management needs.
Fleet Operators anchor contract value. Individual Owners deliver volume density.
Technology:
Water consumption profiles differentiate regulatory risk and operating cost structures.
- Waterless:Spray-on, wipe-off chemical formulations using surfactant-lubricant blends. California water board and Texas drought restrictions constrain adoption pending runoff validation.
- Pressure Washing:High-pressure pumps delivering 1,200-3,000 PSI for road film and salt removal. Equipment supply concentrates in German and Italian manufacturing clusters.
- Foam:Pre-soak and conditioning agents reducing mechanical friction during tunnel cycles. Biodegradable enzymatic chemistry enables EPA discharge compliance in Florida facilities.
- Steam Cleaning:Heated vapor systems for interior sanitization and engine bay degreasing with minimal water discharge.
Pressure Washing commands equipment spend. Foam is climbing the fastest.
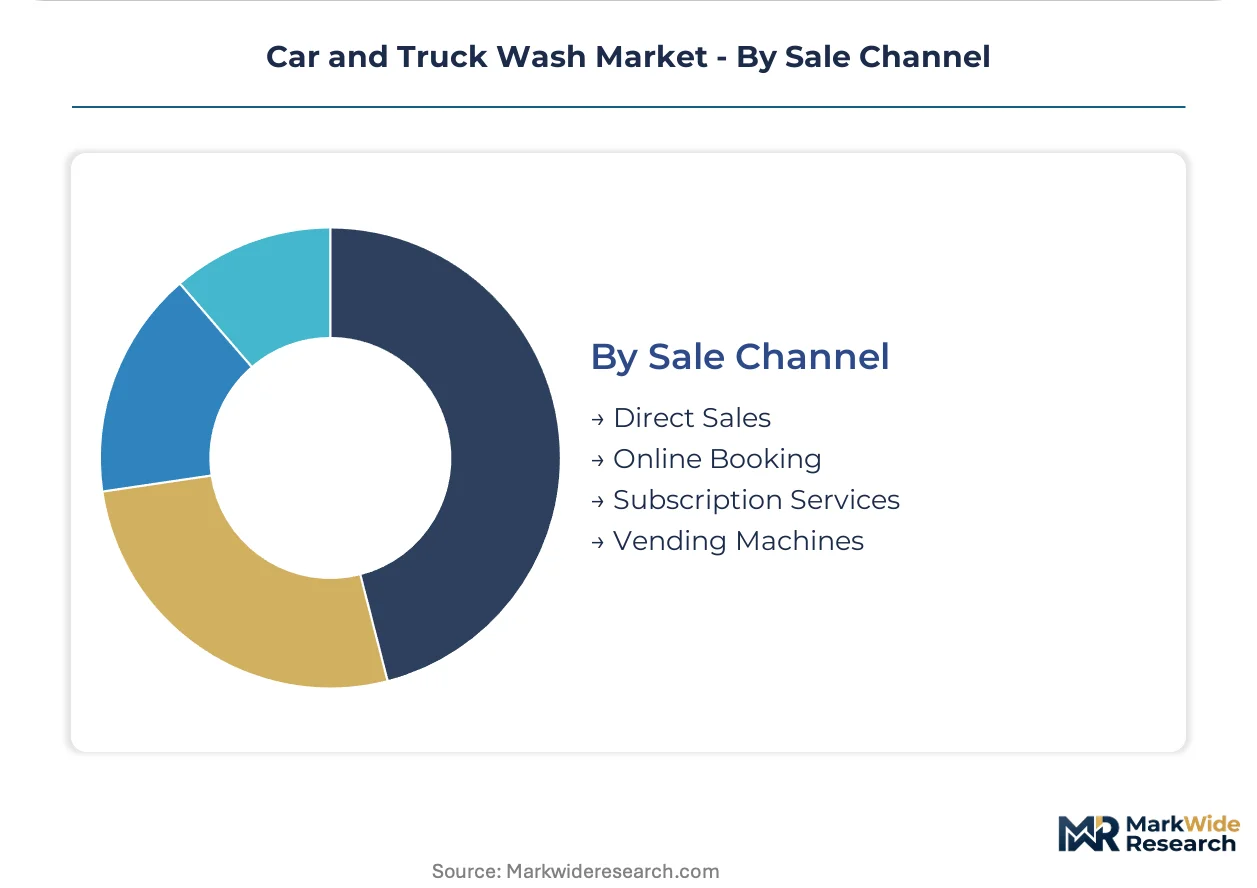
Sale Channel:
Customer acquisition cost and retention mechanics vary sharply across booking modalities.
- Direct Sales:On-site transactions at facility entry points with cash, card, or fleet account billing. License plate recognition systems in Texas and California tunnel networks compress entry friction from 45 seconds to under 10 seconds.
- Online Booking:Mobile and web platforms scheduling appointments with dynamic pricing. Fleet procurement teams in Florida leverage these channels for enterprise rate negotiation.
- Subscription Services:Recurring membership models with unlimited or tiered wash allowances. Monthly billing sustains utilization rates 30-40% above single-visit economics.
- Vending Machines:Self-service equipment sales of cleaning supplies, air fresheners, and detailing products at bay exits.
Subscription Services capture lifetime value. Online Booking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water reclamation mandates and fleet outsourcing contracts are concentrating car and truck wash investment in jurisdictions with stringent discharge regulations and dense logistics corridors.
United States
Express tunnel networks dominate suburban retail zones across Texas, Florida, and California. The EPA enforces effluent guidelines under the Clean Water Act that mandate reclaim rates above 80% for new facilities. Dallas-Fort Worth anchors the Sun Belt expansion where Mister Car Wash scales subscription-based membership models.
Germany
Pressure system manufacturing clusters in Stuttgart and Munich supply high-pressure pump hardware to North American operators. The EU Water Framework Directive and REACH chemical regulations govern surfactant discharge profiles. Alfred Kärcher SE and Co. KG anchors European equipment supply through Baden-Württemberg production facilities.
Canada
Fleet maintenance outsourcing by Alberta oilfield services and Ontario logistics firms sustains mobile wash unit demand. Health Canada and provincial environment ministries regulate chemical runoff from commercial wash operations. Calgary and Edmonton corridor operators deploy truck-mounted units to remote construction and energy sites.
Australia
Drought-prone jurisdictions in New South Wales and Queensland scrutinize waterless chemical formulations pending runoff validation. The country's national water regulator imposes consumption limits on commercial wash facilities during scarcity declarations. Sydney and Melbourne tunnel operators invest in closed-loop filtration to secure operating permits.
Brazil
São Paulo and Rio de Janeiro logistics corridors generate fleet wash contract volume for last-mile delivery and long-haul trucking segments. ANVISA regulates cleaning chemical composition while state environmental agencies monitor discharge into watersheds. Regional operators consolidate through multi-brand rollup strategies to capture enterprise accounts.
Car and Truck Wash Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven tunnel networks face pressure from mobile fleet specialists and equipment fabricators. The market fragments between subscription-based retail operators, fleet-service mobile units, and manufacturing-centric hardware suppliers. Three archetypes dominate: national wash networks with recurring revenue platforms, regional multi-brand consolidators, and European equipment specialists with reclaim technology portfolios. Competitive moves concentrate on geographic rollup acquisitions and technology licensing partnerships that transfer filtration system IP across regional boundaries.
Among US-based wash network operators, Mister Car Wash and Spotless Brands occupy positions at opposite ends of the consolidation spectrum. Alfred Kärcher SE and Co. KG anchors the equipment-specialist tier with German manufacturing heritage. These three entities exemplify how scale, rollup strategy, and hardware supply each carve defensible positions within a market pressured by water reclamation capital requirements and fleet procurement consolidation.
| Leading Market Players |
|---|
| Whistle Express Car Wash |
| WetGo Car Wash |
| Mister Car Wash |
| Crew Carwash |
| Delta Sonic |
| Tidal Wave Auto Spa |
| Spotless Brands |
| Alfred Kärcher SE and Co. KG |
| Quick Quack Express Car Wash |
| Others |
Supply Flow & Price Mechanics
Stuttgart's pressure pump manufacturing cluster anchors European equipment supply, translating German engineering premiums into North American operator cost structures while tariff exposure on stainless steel inputs compresses margin buffers for independent tunnel networks.
Pricing Analysis
Water reclaim certification tiers create the primary spread between premium tunnel networks and legacy self-service bays, with EPA-mandated closed-loop systems commanding 25-40% equipment surcharges over basic wash configurations. Fleet procurement teams negotiate enterprise rates through bundled fuel and maintenance contracts, driving price erosion in commercial segments while subscription retail models sustain pricing power. Independent operators face acute price sensitivity as scaled networks leverage volume purchasing on biodegradable surfactant chemistry.
Supply Chain Analysis
High-pressure pump hardware draws from German and Italian manufacturing clusters, with reclaim system electronics sourcing from South Korean and Taiwanese component suppliers. Stainless steel fabrication and specialized polymer resins for tunnel equipment rest on commodity markets subject to energy cost swings and tariff uncertainty. Single-source vulnerability concentrates in Baden-Württemberg production facilities for Kärcher-class pressure systems. Distribution runs through OEM-direct channels for major tunnel builds and regional equipment distributors for retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water reclamation mandates are accelerating capital intensity thresholds, creating structural separation between scaled reclaim-compliant networks and legacy operators facing equipment obsolescence.
For Market Incumbents: Entrench subscription-based membership models to lock recurring revenue pools before fleet procurement consolidation advances further. Prioritize backward integration into reclaim system maintenance capabilities to capture service revenue from EPA-mandated operator training requirements. Defend against mobile fleet specialists by co-locating express tunnels near Texas municipal water trunk lines where infrastructure subsidies reduce reclaim capital costs.
For New Entrants and Emerging Players: Secondary metros in Florida and Texas with certified wastewater technician scarcity represent the most penetrable entry point for mobile fleet units targeting construction and logistics yards. IoT-enabled reclaim monitoring systems offer a technology wedge to differentiate against legacy tunnel operators. Target fleet accounts through API-first scheduling platforms that integrate with enterprise telematics systems.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because water board mandates create captive demand for filtration hardware and compliance-linked service contracts. Acquisition targets should cluster around regional operators with grandfathered water rights or existing reclaim permits in drought-prone jurisdictions. Monitor state water budget appropriations as the signal for co-location opportunity windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Reclaim System Retrofit Program | EPA compliance mandates in California and Texas create captive upgrade demand for filtration hardware suppliers. |
| Fleet Telematics Integration | API connectivity with logistics tracking systems secures enterprise contract renewals against mobile competitors. |
| Subscription Platform Rollout | Mobile app billing converts single-visit retail into recurring revenue pools with 30-40% utilization premiums. |
| Municipal Water Co-location | Texas infrastructure funding for reclaimed water distribution reduces per-site capital requirements for tunnel operators. |
| Biodegradable Chemistry Licensing | Enzymatic surfactant IP transfer enables Florida and California operators to meet discharge restrictions without waterless substitution. |
Methodological Framework
Operator-level perspectives from tunnel network executives, fleet procurement managers, reclaim system technicians, and municipal water board regulators anchored the qualitative base for this study. Primary interviews with equipment fabricators in Germany and Italy supplemented secondary validation through EPA effluent guideline documents, state water board permit databases, and SEC filings from publicly traded wash networks. Customs data on high-pressure pump imports and regional water consumption statistics completed the triangulation between bottom-up facility economics and top-down market sizing.
Scenario-bracketing around reclaim mandate enforcement timelines and fleet outsourcing adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service format, customer type, water consumption technology, and booking channel, with additional granularity on state-level regulatory cluster exposure. CAGRs derived from equipment installation run rates and subscription conversion metrics, cross-referenced against logistics fleet growth and commercial vehicle registration patterns.
Practitioners should monitor EPA effluent guideline revision schedules and state water budget appropriations for early signals of regulatory intensity shifts. Cross-checking against municipal water authority capital improvement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market