
 Peru Road Freight Transport Market | 2026-2036
Peru Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Road Freight Transport Market Analytics
Peru's coastal highway corridors is restructuring capacity allocation between Pacific port gateways and interior mining provinces. DHL leverages its international network density to dominate pharmaceutical and electronics lanes from Callao. SAVAR Corporación Logística anchors domestic distribution through its warehousing footprint across Arequipa and Trujillo. Peru Logistic SAC specializes in project cargo for energy infrastructure serving the southern copper belt.
Road freight transport encompasses the movement of goods via motor vehicles over paved and unpaved road networks, utilizing trucks rated by gross vehicle weight, axle configuration, and cargo containment systems designed for payloads from 3.5 tonnes to heavy-haul configurations exceeding 50 tonnes. The sector functions as the dominant surface logistics mode for Peru's export commodity flows and domestic consumption supply chains. Full Truck Load services capture the highest volume share through mineral concentrate and agricultural bulk movements from the sierra to port terminals. Refrigerated Transport exhibits the fastest structural expansion, driven by asparagus and avocado cold-chain requirements to maintain temperature integrity below 4 degrees Celsius across 1,000-kilometer transits. E-commerce end users are reshaping delivery mode preferences, forcing fleet operators to integrate same-day and next-day capabilities into traditionally scheduled networks.
Peru's Ministry of Transport and Communications (MTC) enforces maximum axle-load limits and vehicle dimension standards that directly constrain trailer specifications and fleet renewal cycles. The Superintendence of Land Transport (SUTRAN) monitors driver hours-of-service compliance and carrier safety ratings, creating differentiated market access for certified operators versus informal competitors. Stakeholders must weigh electrification timelines against Andean altitude performance degradation and the sparse charging infrastructure along the Pan-American Highway corridor.
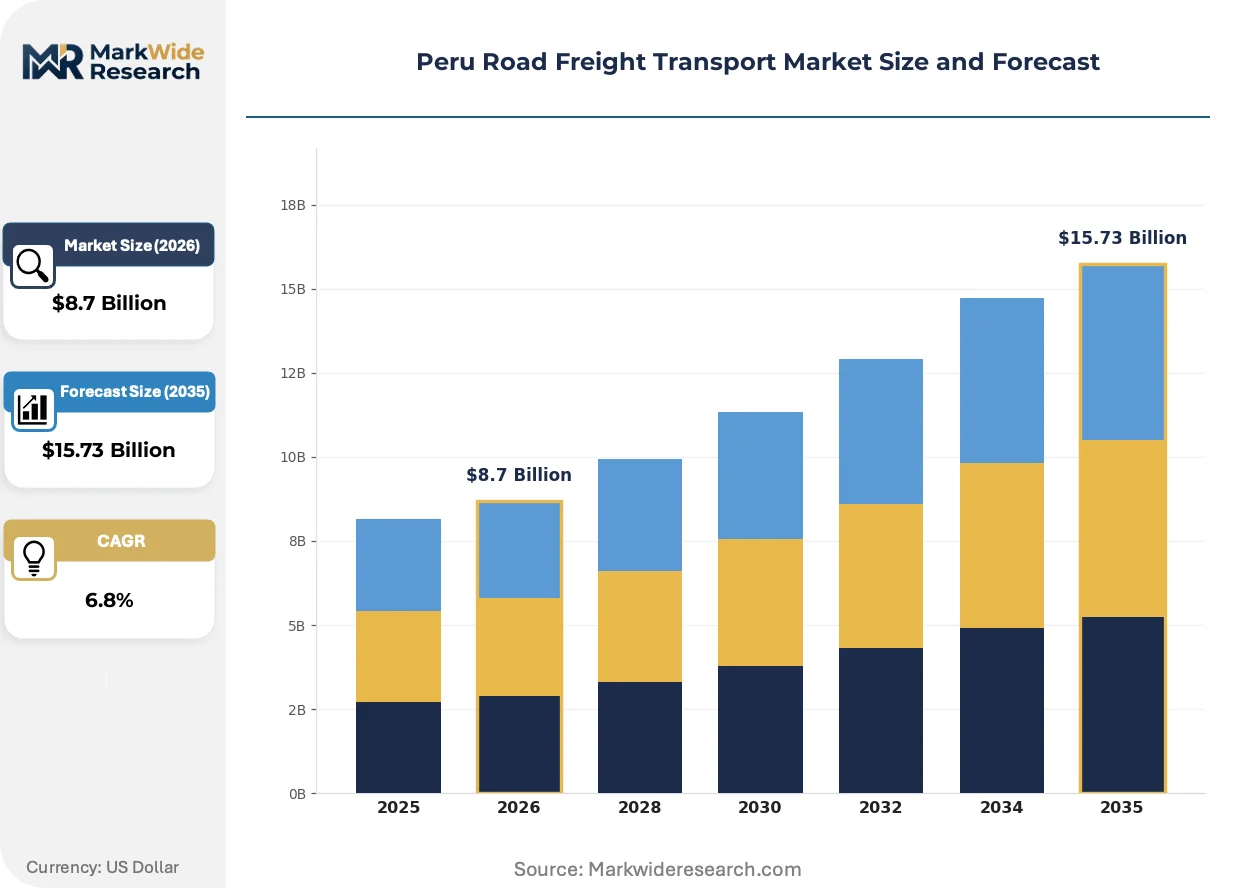
Market Dynamics
Axle-load enforcement by Peru's Ministry of Transport and Communications is forcing fleet-wide trailer replacements and compressing carrier margins across the Andean corridor. Mining export volumes continue expanding while compliance costs reshape competitive viability between formal operators and informal competitors.
Growth Catalysts
- Copper concentrate volumes:Southern Peru's mining belt generates heavy-haul demand along the Lima-Callao corridor. Mineral processors require dedicated fleets for 50-tonne payload configurations.
- Cold-chain infrastructure:Asparagus and avocado exporters drive refrigerated transport expansion. Temperature integrity below 4 degrees Celsius across 1,000-kilometer transits mandates fleet renewal.
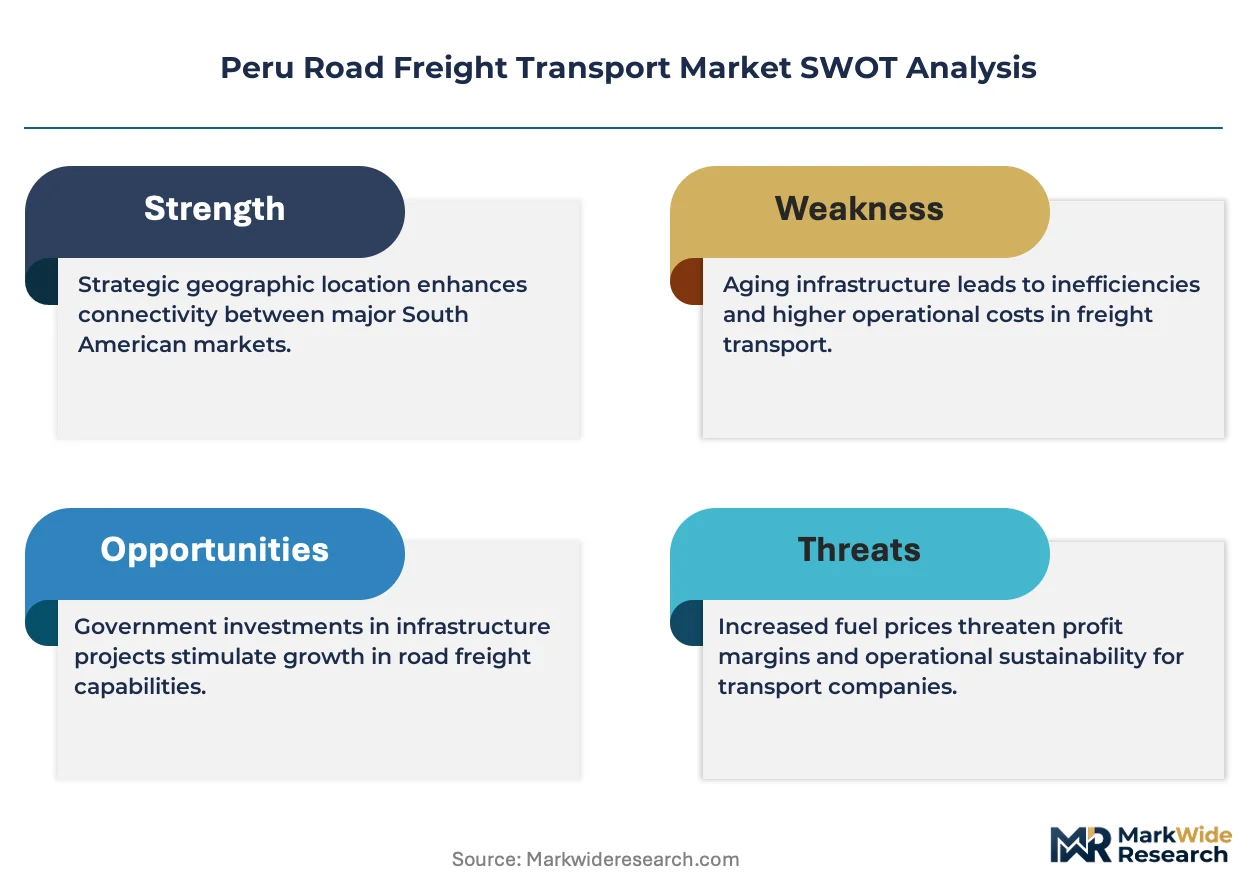
- Pan-American Highway modernization:Paved corridor improvements reduce transit times between Pacific ports and interior provinces. Logistics operators capture efficiency gains on north-south freight lanes.
Market Restraints
- Diesel price volatility:Fuel constitutes the largest operating cost component for Andean fleet operators. Price fluctuations compress margins on fixed-rate mining contracts.
- Charging infrastructure gaps:Sparse electric vehicle stations along mountain corridors limit electrification timelines. Altitude performance degradation compounds battery range constraints.
- SUTRAN enforcement variance:Inconsistent hours-of-service monitoring across regional offices creates compliance cost asymmetry. Formal carriers face audit burdens informal competitors evade.
Strategic Opportunities
- Arequipa logistics cluster:Underdeveloped warehousing capacity in southern Peru offers greenfield development potential. Mining suppliers require bonded storage near copper processing facilities.
- Last-mile e-commerce integration:Same-day delivery capabilities remain nascent outside Lima-Callao. Regional distributors can capture consumer electronics and pharmaceutical flows.
- Axle-load compliance services:Fleet weighing and certification demand exceeds certified provider supply. Technical audit services command premium pricing from formal operators.
Industry Challenges
- Qualified driver scarcity:Heavy-haul certification programs produce insufficient graduates for mining corridor demand. Fleet operators poach trained personnel from competitors.
- Multi-generational fleet complexity:Compliance deadlines force simultaneous operation of pre-regulation and post-regulation trailer specifications. Maintenance protocols fragment across incompatible axle configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Road Freight Transport Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Refrigerated Transport, Bulk Transport Vehicle Type: Flatbed Trucks, Box Trucks, Cargo Vans, Tank Trucks End User: Retailers, Manufacturers, Distributors, E-commerce Delivery Mode: Scheduled Deliveries, Same Day Delivery, Next Day Delivery, Expedited Shipping |
| Companies Covered | Kuehne+Nagel, Peru Logistic SAC, DHL, Transaltisa, JAS Worldwide, DSV, SAVAR Corporación Logística, GEODIS, CEVA Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Road Freight Transport Market Evolving Landscape
Telematics integration is redefining how Peruvian carriers manage asset utilization across dispersed mining and agricultural supply chains. Real-time tracking capabilities now separate certified operators from informal competitors in contract bidding.
GPS-enabled fleet management systems is converging with predictive maintenance algorithms to compress downtime on Andean mountain routes. Mining logistics coordinators now mandate telematics visibility for heavy-haul tenders. Equipment manufacturers are bundling sensor packages with new tractor configurations to capture aftermarket service revenue.
Peru's Ministry of Transport and Communications maximum axle-load regulations are accelerating trailer retirement cycles and reshaping manufacturer order books. Compliance deadlines force carriers to scrap pre-2018 configurations regardless of mechanical condition. Domestic trailer assemblers face capacity constraints as fleet replacement demand concentrates in 18-month windows.
E-commerce fulfillment expectations are compressing delivery windows from scheduled routes to same-day availability. Consumer electronics distributors in Lima now require 4-hour response capabilities previously reserved for pharmaceutical cold-chain. Regional carriers without urban micro-fulfillment partnerships are losing retail contract renewals to integrated logistics providers.
Peru Road Freight Transport Market Segmentation
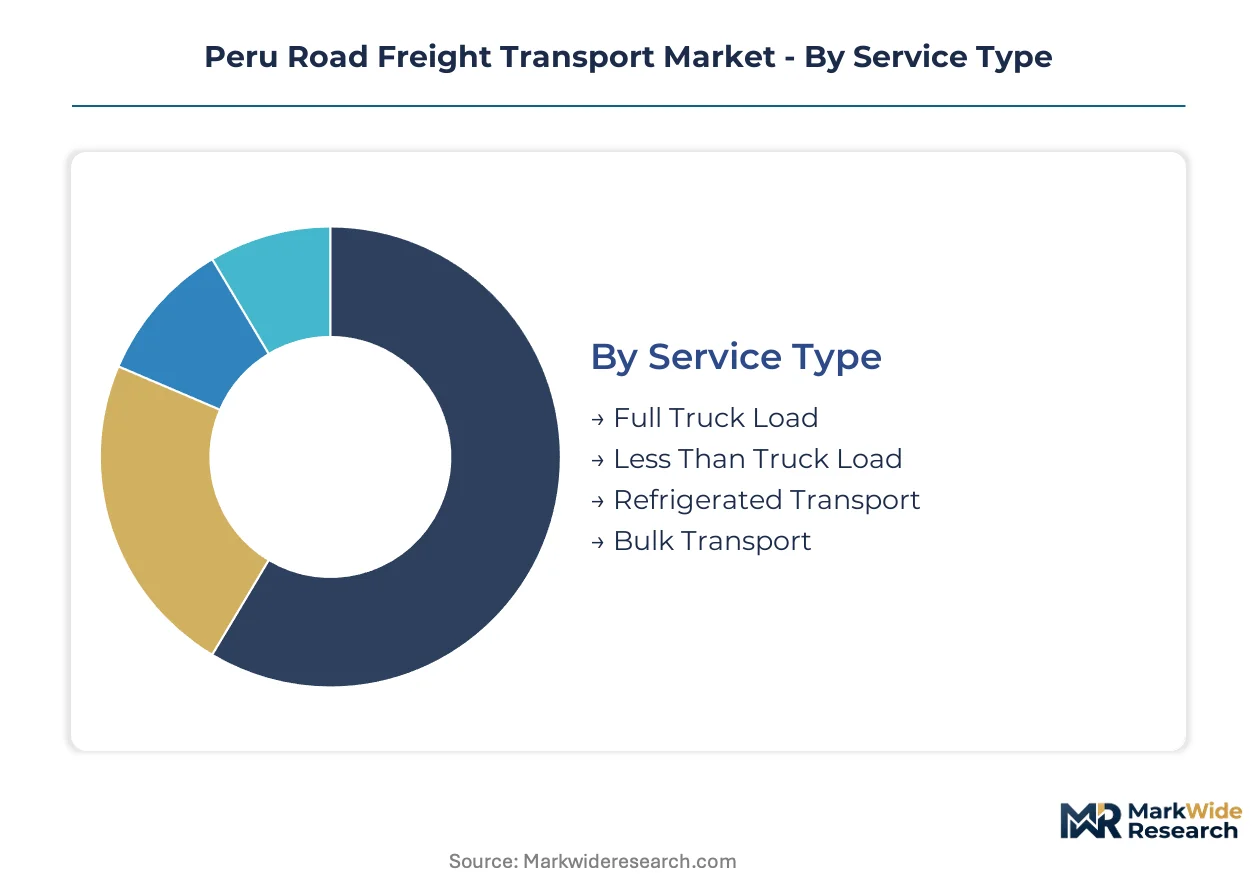
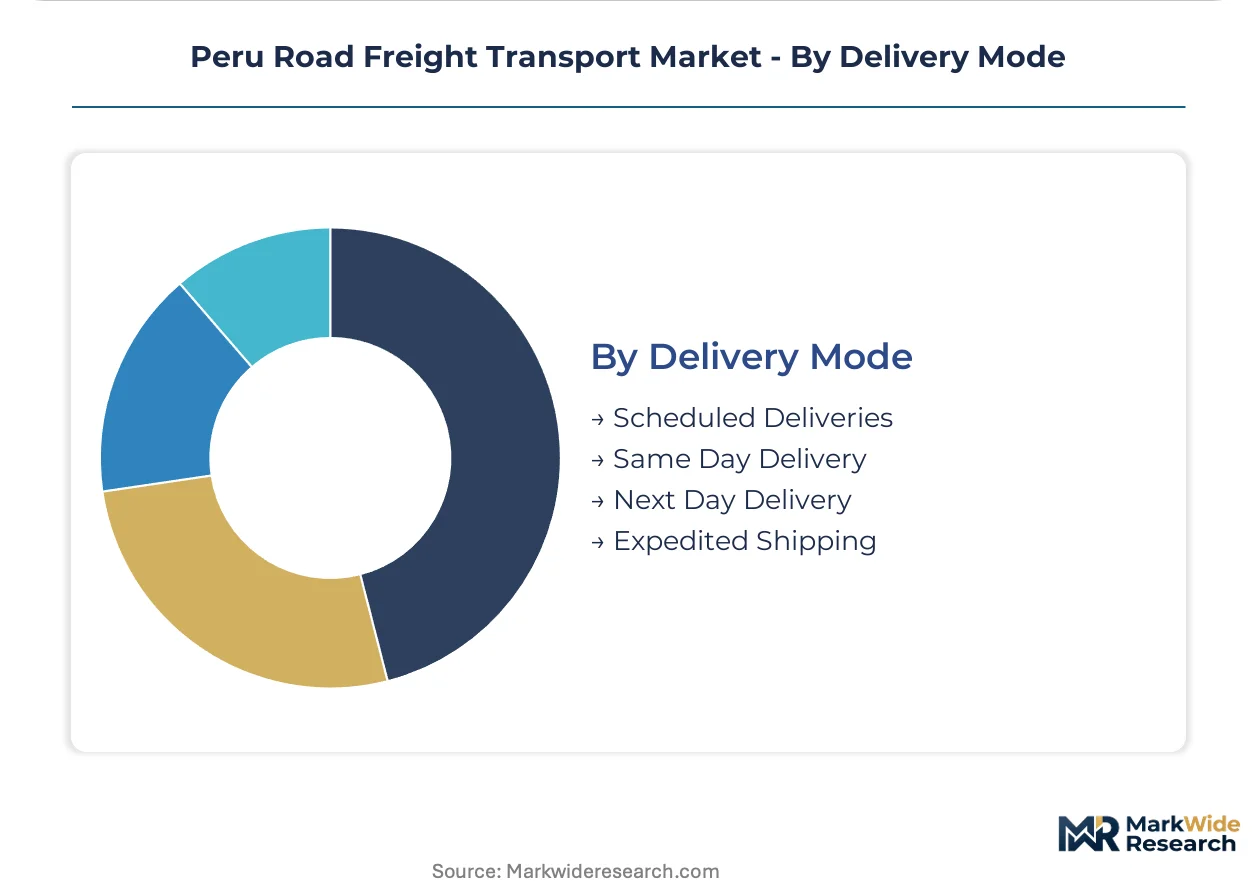
Peru's road freight market segments reflect the tension between mining-driven bulk logistics and emerging consumer delivery expectations. Service configurations diverge sharply between Andean heavy-haul corridors and Lima-Callao last-mile networks.
Service Type:
Supply concentration among copper exporters and agro-industrial processors shapes how carriers allocate fleet capacity across service tiers.
- Full Truck Load:Dedicated 50-tonne configurations dominate mineral concentrate movements from southern mining provinces to Callao port terminals. Mining contracts absorb the highest-capacity trailers under long-term fixed-rate agreements.
- Refrigerated Transport:Temperature-controlled units maintain sub-4°C integrity across 1,000-kilometer asparagus and avocado transits from Ica and La Libertad. Cold-chain compliance mandates fleet renewal cycles shorter than dry-cargo equivalents.
- Less Than Truck Load:Consolidated shipments serve fragmented manufacturing bases in Arequipa and Trujillo where individual consignments lack FTL scale.
- Bulk Transport:Open-hopper configurations handle agricultural commodities and construction aggregates on unpaved feeder roads.
Today's leader: Full Truck Load. Tomorrow's challenger: Refrigerated Transport.
Vehicle Type:
Axle-load enforcement by Peru's Ministry of Transport and Communications is compressing replacement cycles and reshaping manufacturer order books across body configurations.
- Flatbed Trucks:Open-deck configurations accommodate oversized mining equipment and containerized mineral concentrates. Southern copper belt logistics coordinators specify flatbeds for 80% of heavy-haul tenders.
- Box Trucks:Enclosed van bodies protect consumer electronics and pharmaceuticals from Andean dust and humidity on the Lima-Callao corridor. DHL's pharmaceutical network relies exclusively on box configurations for controlled-temperature lanes.
- Cargo Vans:Light-duty units below 3.5 tonnes penetrate urban micro-fulfillment for e-commerce same-day commitments.
- Tank Trucks:Liquid bulk configurations serve fuel distribution and chemical transport for mining processing facilities.
Flatbeds command the heaviest investment; box trucks gain share fastest as consumer logistics expands.
End User:
Customer procurement patterns separate commodity-driven volume contracts from service-sensitive retail relationships.
- Manufacturers:Mining processors and agro-industrial packers dominate tender volumes with multi-year logistics agreements spanning the Pan-American Highway corridor.
- E-commerce:Digital retail platforms are compressing delivery windows to same-day availability, forcing fleet operators to reconfigure scheduled networks around urban micro-fulfillment nodes.
- Retailers:Traditional distribution channels in Arequipa and Trujillo maintain scheduled delivery relationships with domestic carriers.
- Distributors:Intermediate wholesalers aggregate fragmented demand across secondary cities lacking direct manufacturer logistics.
Manufacturers anchor current revenue; e-commerce platforms are climbing the fastest.
Delivery Mode:
Speed-tier differentiation separates mining logistics coordinators from consumer-facing distributors in contract negotiations.
- Scheduled Deliveries:Fixed-route rotations dominate mining concentrate and agricultural bulk movements where transit predictability outweighs velocity. Carriers optimize asset utilization through confirmed loading windows at port terminals.
- Same Day Delivery:Four-hour response capabilities now penetrate Lima-Callao consumer electronics and pharmaceutical flows. Regional carriers without urban micro-fulfillment partnerships are losing retail renewals to integrated providers.
- Next Day Delivery:Intermediate tier serves provincial retail replenishment outside immediate Lima metropolitan coverage.
- Expedited Shipping:Premium positioning for project cargo and emergency mining spare parts on Andean mountain routes.
Scheduled deliveries retain volume dominance; same-day capabilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Peru's formal operators and informal competitors are redistributing freight flows toward compliance-heavy corridors where certified carriers command premium rates. The Ministry of Transport and Communications enforces axle-load standards that compress margins in highland mining routes while opening arbitrage opportunities on modernized Pacific highways.
Lima-Callao Corridor
Peru's dominant logistics axis concentrates pharmaceutical and electronics flows through Callao port terminals. The Ministry of Transport and Communications enforces vehicle dimension standards that constrain trailer configurations entering the metropolitan freight zone. DHL anchors pharmaceutical distribution from bonded warehouses in Callao, while SAVAR Corporación Logística operates cross-docking facilities linking coastal imports to interior provinces.
Southern Mining Belt
Arequipa and Tacna provinces generate heavy-haul demand for copper concentrate movements exceeding 50-tonne payloads. SUTRAN monitors driver hours-of-service compliance across mountain routes, creating audit burdens that informal competitors evade. Peru Logistic SAC specializes in project cargo for energy infrastructure serving copper processing facilities clustered near the Chilean border.
Central Highlands
Huancayo and Cerro de Pasco anchor agricultural bulk movements from sierra farming cooperatives to Pacific port terminals. Axle-load enforcement by the Ministry of Transport and Communications forces fleet-wide trailer replacements on unpaved feeder roads. Cold-chain operators maintain temperature integrity below 4 degrees Celsius for asparagus transits originating in Ica province valleys.
Northern Agro-Industrial Zone
La Libertad and Lambayeque provinces drive refrigerated transport expansion for avocado exports through Salaverry port. The Pan-American Highway modernization reduces transit times between Trujillo logistics clusters and Lima distribution centers. SAVAR Corporación Logística anchors domestic distribution through warehousing footprints across Trujillo that consolidate fragmented agricultural consignments.
Amazonian Frontier
Loreto and Ucayali provinces present greenfield opportunities for bulk transport on unpaved corridors linking riverine ports to Andean highway networks. Sparse enforcement capacity across regional SUTRAN offices creates compliance cost asymmetry between formal and informal operators. Project cargo specialists target hydrocarbon exploration logistics where infrastructure gaps exceed standard fleet capabilities.
Peru Road Freight Transport Market Competitive Landscape
Lima-based integrated logistics providers anchor one tier; regional specialists concentrated in Arequipa and Trujillo hold contract manufacturing and agricultural distribution relationships. The market structure fragments across three operational tiers: international forwarders with bonded warehousing, domestic heavy-haul operators serving mining corridors, and last-mile distributors penetrating e-commerce fulfillment. Strategic archetypes include compliance-certified fleet operators, cold-chain specialists, and project cargo coordinators. Dominant competitive moves encompass fleet renewal cycles compressed by axle-load deadlines and micro-fulfillment partnerships capturing urban same-day delivery contracts.
Among international forwarders operating Peruvian subsidiaries, Kuehne+Nagel, DHL, and GEODIS exemplify the premium-tier archetype through integrated ocean-air-road networks. These entities occupy positions defined by customs brokerage capabilities and pharmaceutical cold-chain certifications rather than asset-heavy fleet ownership. Domestic operators including Peru Logistic SAC and SAVAR Corporación Logística represent the specialized heavy-haul and warehousing tier, anchoring relationships with mining processors and agro-industrial exporters through region-specific infrastructure investments. The competitive dynamic pits international network density against local corridor expertise, with formal certification status increasingly separating contract-eligible operators from informal price competitors.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| Peru Logistic SAC |
| DHL |
| Transaltisa |
| JAS Worldwide |
| DSV |
| SAVAR Corporación Logística |
| GEODIS |
| CEVA Logistics |
| Others |
Value Network & Pricing Analysis
Telematics-enabled fleet management systems are compressing operating cost differentials between certified and informal carriers while concentrating contract eligibility among technology-invested operators. Peru's Ministry of Transport and Communications axle-load enforcement simultaneously raises compliance investment thresholds and rewards formal operators with premium-rate access to mining corridor tenders.
Pricing Analysis
Distributor margins on heavy-haul mining contracts absorb the steepest compression as fuel volatility erodes fixed-rate agreements. Three-tier pricing structure across certified, transitional, and informal fleet tiers separates contract-eligible operators from price-competitive shadow carriers. Pricing pressure stems from diesel cost pass-through limitations in multi-year mining offtakes. Small agricultural shippers exhibit highest price sensitivity; pharmaceutical distributors show least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese axle and suspension component suppliers serving domestic trailer assemblers. Manufacturing concentration in China, Brazil, and Mexico feeds Peru's fleet renewal cycles. Steel and tire inputs face commodity volatility exposure. Distribution runs through Lima-based bonded warehouses before interior province deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's road freight market functions as a stable compounder anchored by mining export volumes that generate predictable heavy-haul demand regardless of consumer cycle fluctuations.
For Market Incumbents: Deepen backward integration into trailer maintenance and axle-certification services to capture compliance-driven aftermarket revenue. Formal operators should expand warehousing footprints in Arequipa before greenfield competitors secure mining supplier relationships. SUTRAN audit intensity represents the primary margin threat. For New Entrants and Emerging Players: E-commerce platform partnerships offer the lowest barrier to contracted revenue for asset-light regional distributors. Last-mile micro-fulfillment in Trujillo and Chiclayo remains penetrable before integrated logistics providers consolidate urban nodes. Lead with same-day capability demonstrations to consumer electronics retailers. For Investors and Strategic Acquirers: Valuations sit cheapest among second-tier regional carriers with underutilized fleet capacity and pending axle-load compliance deadlines. Long-term viability favors operators with demonstrated SUTRAN certification and mining contract renewal rates. Watch copper concentrate export volume trends as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Deployment | Real-time tracking separates certified operators from informal competitors in mining tenders. |
| Refrigerated Capacity Expansion | Cold-chain compliance mandates shorter replacement cycles than dry-cargo equivalents. |
| Arequipa Warehousing Development | Bonded storage near copper processing facilities captures mining supplier logistics spend. |
| Axle-Load Certification Services | Technical audit demand exceeds certified provider supply across the Andean corridor. |
| E-Commerce Last-Mile Partnerships | Urban micro-fulfillment nodes secure retail contract renewals from integrated providers. |
Research Methodology
Direct dialogue with fleet operations managers, mining logistics coordinators, SUTRAN compliance officers, and trailer manufacturer sales directors grounded qualitative findings. Secondary validation drew from Peru's Ministry of Transport and Communications regulatory filings, SUTRAN enforcement statistics, copper export customs records, and agricultural cold-chain operator disclosures. Bottom-up carrier capacity estimates and top-down commodity flow analysis were triangulated against Ministry freight volume surveys.
Market size outputs reflect segment-level modeling across service type, vehicle configuration, end-user industry, and delivery speed tier throughout the projection horizon. CAGRs were derived from mineral export volume trajectories, fleet replacement cycle compression, and e-commerce penetration curves. Refrigerated transport growth rates incorporate asparagus and avocado export expansion assumptions.
Copper price volatility, SUTRAN enforcement intensity variance, and charging infrastructure deployment pace are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory compliance deadlines and mining investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market