
 Asia-Pacific Car Wash Market | 2026-2036
Asia-Pacific Car Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Car Wash Market Insights
Asset-light franchise leasing is reshaping competitive entry across the Asia-Pacific Car Wash Market, lowering capital barriers for regional operators. WashUp leverages captive supply of recycled-water modules to anchor its position in water-stressed Australian corridors. CleenBee sustains brand strength through hyperlocal fleet contracts in Indonesian logistics hubs. EcoWash differentiates via biodegradable chemistry integration aligned with emerging environmental compliance timelines.
Asia-Pacific car wash services encompass automated, self-service, mobile, and hand-wash modalities that remove contaminants from vehicle exteriors and interiors using pressurized water, chemical agents, or mechanical friction systems operating at 60–150 bar pressure ratings. These services preserve automotive finishes, ensure regulatory roadworthiness for commercial fleets, and support resale value retention across passenger and light-commercial vehicle categories. Automatic tunnel systems dominate throughput economics for high-volume urban locations, while mobile wash units represent the fastest-expanding segment as on-demand platforms penetrate dense metropolitan zones with limited fixed infrastructure. Waterless technology commands premium positioning where municipal supply restrictions or drought contingency protocols constrain conventional high-pressure operations.
India's Central Pollution Control Board enforces wastewater discharge standards for commercial wash facilities, while Australia's state-level environmental protection agencies mandate water recycling thresholds in drought-declared regions. Japan's METI promotes resource-efficiency labeling that incentivizes low-flow equipment adoption among service providers. Stakeholders must monitor evolving sub-national water pricing regimes and building-code adaptations that will determine viable site economics and technology selection across the region's heterogeneous regulatory landscape.
Market Dynamics
India's BIS water-efficiency mandates and Australia's drought-response infrastructure codes are compressing capital deployment timelines for conventional high-pressure wash systems across the region. Fleet operators now prioritize touchless and waterless modalities to secure operating permits in water-stressed corridors.
Growth Catalysts
- Indonesian logistics fleet expansion:Commercial vehicle pools in Jakarta and Surabaya are instituting scheduled wash programs to maintain roadworthiness certifications and preserve resale values for heavy-duty trucks.
- India's tier-2 motorization surge:Rapid passenger vehicle ownership growth in cities like Lucknow and Indore outpaces fixed-bay infrastructure, creating demand for mobile and automated tunnel systems.
- Waterless chemistry advancement:Biodegradable surfactant formulations now enable compliant cleaning without pressurized water discharge, unlocking operations in Australian drought-declared zones.
Market Restraints
- Recycled-water module supply concentration:Captive supply of closed-loop filtration systems concentrates among Australian specialist manufacturers, constraining deployment scale across Southeast Asia.
- Site certification timelines:India's Central Pollution Control Board wastewater discharge permitting creates 8-14 month approval windows for new commercial facilities in metropolitan jurisdictions.
- Touchless equipment capex thresholds:Automated tunnel systems with 60–150 bar pressure ratings require substantial upfront investment relative to hand-wash labor economics in lower-wage Vietnamese and Indonesian markets.
Strategic Opportunities
- Vietnamese commercial vehicle underpenetration:Fleet wash contracts for logistics hubs around Ho Chi Minh City and Hai Phong remain fragmented, offering first-mover consolidation potential for platform operators.
- Japan's METI resource-efficiency labeling:Low-flow equipment certification creates preference pull among Japanese service providers seeking differentiated positioning in premium passenger segments.
- Mobile-on-demand channel emergence:App-based scheduling platforms are penetrating dense Indian and Australian metropolitan zones with limited fixed infrastructure, compressing customer acquisition costs versus traditional site-based models.
Industry Challenges
- Technician training pipelines:Waterless chemistry application and high-pressure system maintenance require specialized competencies that outpace vocational program output in Indonesian and Vietnamese labor markets.
- Legacy equipment integration friction:Retrofitting existing fixed-bay sites with closed-loop water recycling modules demands structural modifications that disrupt revenue continuity during construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Car Wash Market |
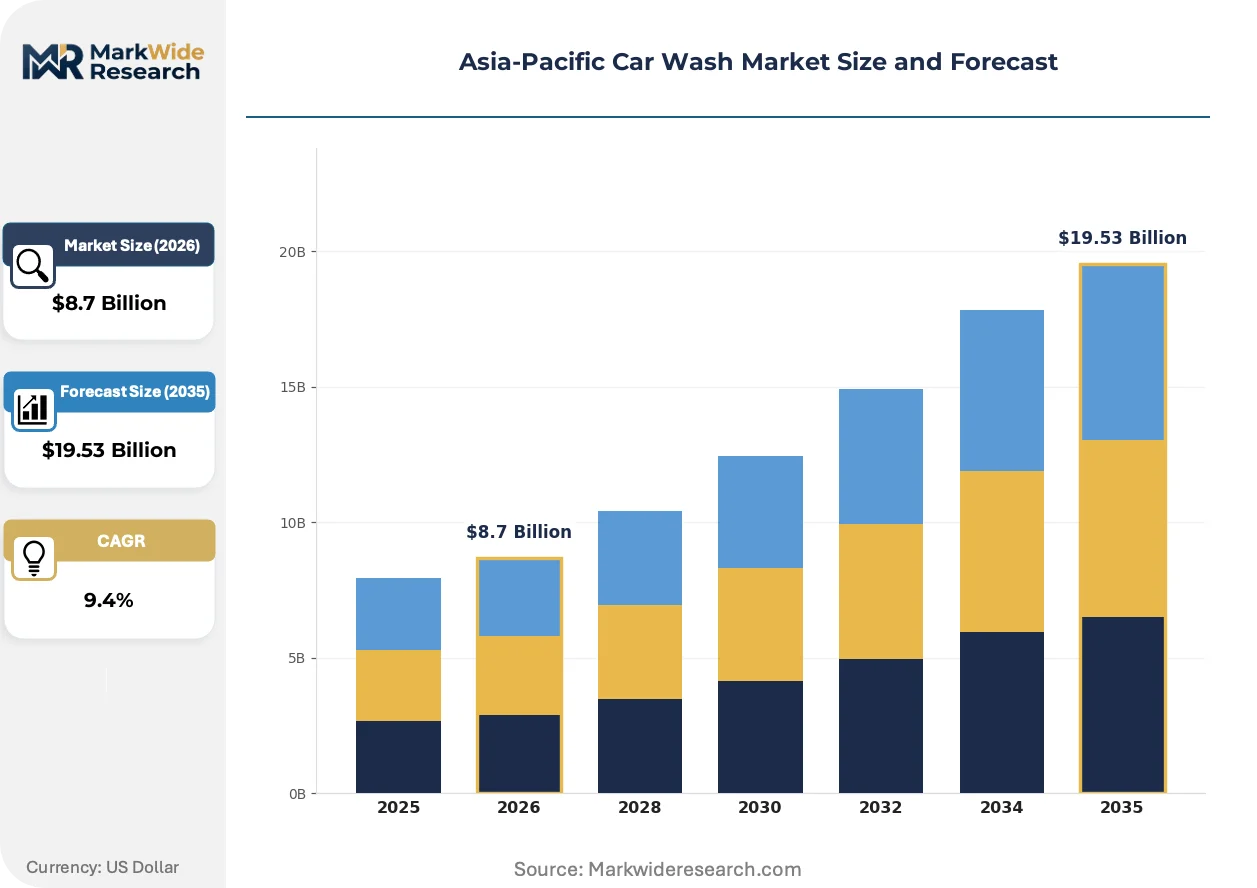
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automatic, Self-Service, Mobile, Hand Wash End User: Individual Owners, Fleet Operators, Businesses, Rental Services Technology: Waterless, High-Pressure, Touchless, Foam-Based Packaging Type: Bulk, Ready-to-Use, Concentrated, Eco-Friendly |
| Companies Covered | WashUp, CleenBee, WashEasy, Spiffy, WashMyCar, EcoWash, Mobile Car Wash, CleanCar, CarSpa, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Car Wash Market Trends and Innovations
Digital telemetry and sensor fusion are compressing operational decision cycles across wash modalities, enabling predictive maintenance and dynamic chemical dosing. These capabilities are reconfiguring competitive advantage toward data-integrated service platforms.
Touchless laser-guided contour mapping is virtualizing the physical brush contact point in automated tunnel systems. Japanese premium fleet operators are piloting these installations at 15-20% throughput premiums over conventional friction-based tunnels. The technology is virtualizing damage liability exposure while enabling safe cleaning of wrapped and matte-finish vehicles previously excluded from automated processing.
Australia's state-level environmental protection agencies are mandating water recycling thresholds in drought-declared regions, compelling facility operators to install closed-loop filtration or face operating hour restrictions. Queensland and New South Wales have enacted the most stringent recovery rate requirements. Commercial wash chains are responding by consolidating site portfolios around captive recycled-water module suppliers to secure compliance at scale.
Subscription-based fleet wash contracts are displacing transactional per-wash pricing among logistics operators with predictable vehicle utilization patterns. Australian and Indonesian transport hubs are leading this shift, locking in volume commitments in exchange for guaranteed turnaround slots. The model concentrates buyer power among large fleet accounts while squeezing margin flexibility for service providers without dedicated capacity allocation systems.
Asia-Pacific Car Wash Market Segmentation
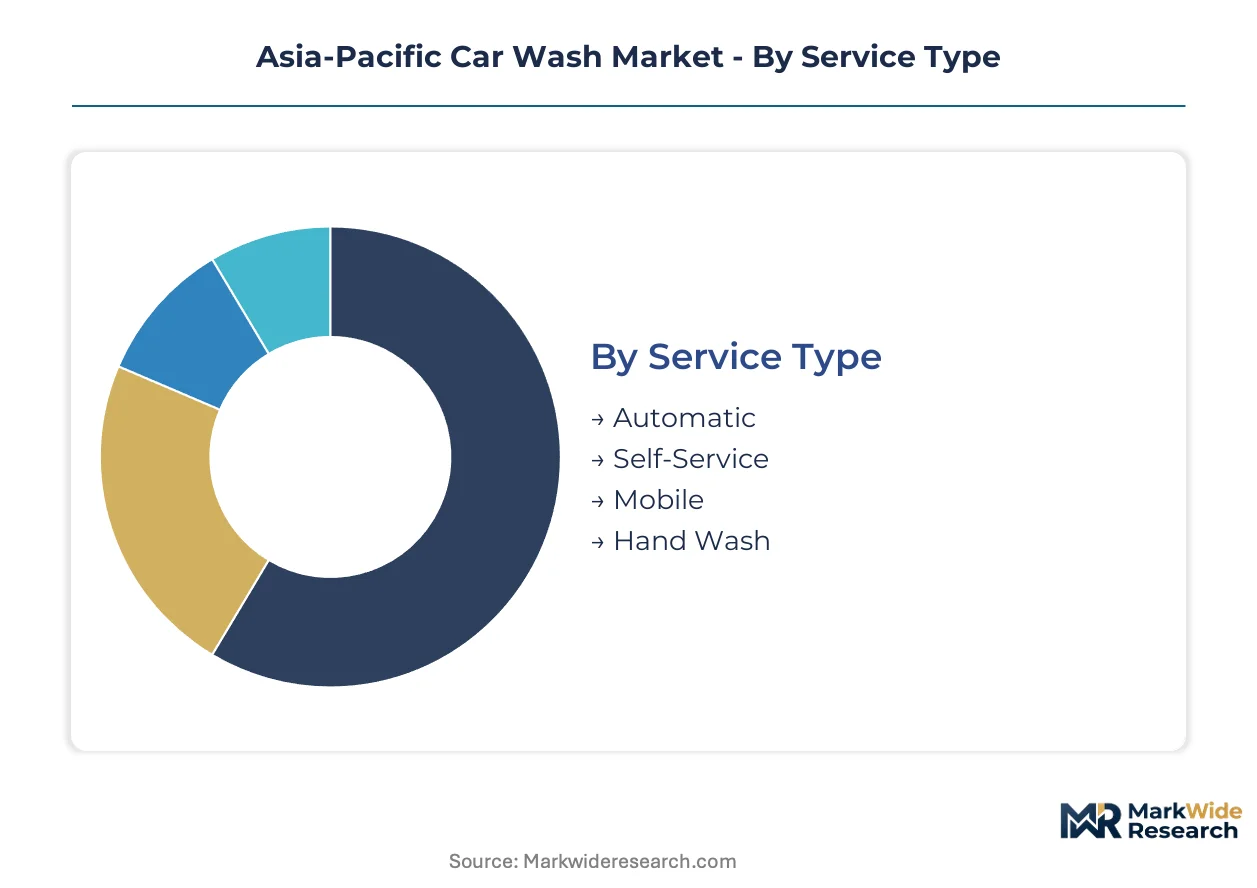
Technology modality and service delivery format determine capital intensity and regulatory compliance pathways across the Asia-Pacific Car Wash Market. Segment selection dictates water permit eligibility, fleet contract viability, and site economics in water-stressed corridors.
Service Type:
Mature automated infrastructure contrasts with emerging on-demand formats reshaping customer acquisition economics.
- Automatic:Tunnel systems operating at 60–150 bar pressure ratings dominate throughput economics for high-volume urban locations in Australian metropolitan zones. Indian tier-2 cities deploy these systems to compensate for fixed-bay infrastructure gaps amid rapid motorization.
- Self-Service:Coin-operated bay formats persist in Australian regional centers and Japanese suburban corridors where land costs support lower-utilization models. Regulatory water recycling mandates in Queensland and New South Wales compress site viability for non-compliant installations.
- Mobile:App-based scheduling platforms penetrate dense Indian and Indonesian metropolitan zones with limited fixed infrastructure.
- Hand Wash:Labor-intensive formats retain share in Vietnamese and Indonesian markets where wage differentials offset equipment capex thresholds.
Automatic retains volume leadership; Mobile holds the steepest expansion curve.
End User:
Customer type stratification mirrors fleet commercialization intensity across regional logistics corridors.
- Fleet Operators:Scheduled wash programs for commercial vehicle pools in Jakarta and Surabaya preserve roadworthiness certifications and resale values for heavy-duty trucks. Subscription-based contracts displace transactional pricing among Australian and Indonesian transport hubs with predictable utilization patterns.
- Individual Owners:Premium passenger segments in Japanese metropolitan areas drive demand for low-flow equipment certified under METI resource-efficiency labeling schemes.
- Businesses:Corporate vehicle pools in Indian tier-2 cities source compliant cleaning to satisfy BIS water-efficiency mandates.
- Rental Services:Turnaround speed requirements favor automated processing for airport-adjacent and central business district locations.
Fleet Operators command the highest contract values; Individual Owners show the most price elasticity.
Technology:
Water intensity differentiates regulatory risk exposure across drought-declared and water-abundant zones.
- Waterless:Biodegradable surfactant formulations enable compliant cleaning without pressurized water discharge, unlocking operations in Australian drought-declared zones. Chemistry advancement concentrates supply among specialized Australian manufacturers.
- Touchless:Laser-guided contour mapping virtualizes brush contact points, enabling safe cleaning of wrapped and matte-finish vehicles at 15–20% throughput premiums in Japanese premium fleet installations.
- High-Pressure:Conventional 60–150 bar systems face compressed deployment timelines under India's BIS mandates and Australian drought-response codes.
- Foam-Based:Reduced water volume requirements offer intermediate compliance positioning for facilities in transitional regulatory jurisdictions.
Waterless gains share fastest in regulated corridors; High-Pressure retains installed base dominance.
Packaging Type:
Concentration economics and environmental positioning split procurement patterns across facility scale tiers.
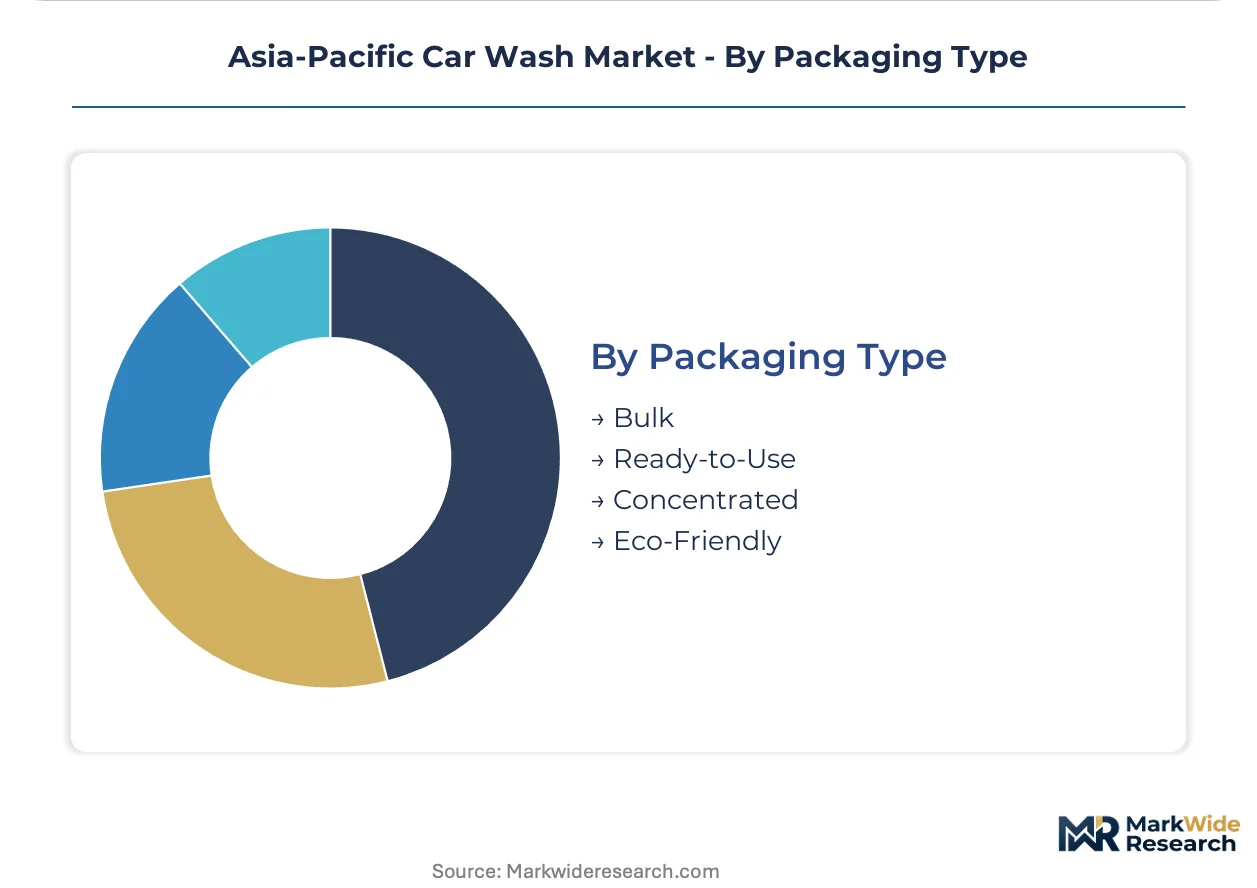
- Bulk:High-volume automated tunnels and fleet wash facilities in Australian and Indonesian logistics hubs procure chemistry at scale to minimize per-unit dosing costs.
- Ready-to-Use:Mobile operators and self-service bays favor pre-mixed formulations to eliminate on-site dilution complexity.
- Concentrated:Freight efficiency benefits support adoption among distributed facility networks in Indian tier-2 expansion markets.
- Eco-Friendly:Biodegradable chemistry integration aligns with emerging environmental compliance timelines in Australian state-level jurisdictions.
Bulk dominates procurement volumes; Eco-Friendly expands most quickly in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment and chemistry trade flows across the Asia-Pacific Car Wash Market reflect divergent water scarcity pressures, with drought-response infrastructure codes in Australia and BIS mandates in India reshaping import patterns for recycled-water modules and biodegradable formulations.
Australia
Fleet operators in Queensland and New South Wales are consolidating wash contracts around recycled-water module suppliers to meet state-level recovery rate requirements. The country's state-level environmental protection agencies enforce the region's most stringent water recycling thresholds in drought-declared zones. Sydney and Melbourne logistics corridors anchor subscription-based fleet wash adoption, locking in volume commitments for guaranteed turnaround slots.
India
Rapid passenger vehicle ownership growth in Lucknow and Indore outpaces fixed-bay infrastructure, creating demand pull for mobile and automated tunnel systems. The Central Pollution Control Board enforces wastewater discharge standards that generate 8-14 month approval windows for new commercial facilities in metropolitan jurisdictions. Tier-2 cities across Maharashtra and Gujarat represent the fastest-expanding addressable market for compliant cleaning services.
Japan
Premium fleet operators in Tokyo and Osaka are piloting touchless laser-guided contour mapping installations at throughput premiums over conventional friction-based tunnels. METI resource-efficiency labeling creates preference pull among service providers seeking differentiated positioning in premium passenger segments. The Kanto and Kansai industrial belts concentrate demand for low-flow equipment certification.
Indonesia
Commercial vehicle pools in Jakarta and Surabaya are instituting scheduled wash programs to maintain roadworthiness certifications for heavy-duty trucks. National logistics fleet expansion is compressing procurement timelines for compliant exterior cleaning services. Jababeka and Cikarang industrial zones anchor fleet wash contract consolidation around hyperlocal service platforms.
Vietnam
Logistics hubs around Ho Chi Minh City and Hai Phong present fragmented fleet wash contract structures, offering first-mover consolidation potential for platform operators. Wage differentials sustain labor-intensive hand-wash economics relative to automated equipment capex thresholds. The Mekong Delta and Red River Delta corridors concentrate commercial vehicle underpenetration for scheduled maintenance programs.
Asia-Pacific Car Wash Market Competitive Landscape
On the supply side, the industry is structurally fragmented across asset-light franchise operators, captive recycled-water module suppliers, and chemistry specialists, with consolidation pressure mounting in water-stressed corridors where compliance thresholds favor scaled deployment. Three archetypes dominate: platform operators leveraging mobile-on-demand scheduling, integrated chains controlling closed-loop filtration supply, and biodegradable chemistry formulators aligned with environmental compliance timelines. Competitive moves center on geographic consolidation of fleet contracts and backward integration into water recycling module production.
Among the named operators in this study, WashUp, CleenBee, and EcoWash occupy distinct positioning vectors. WashUp exemplifies the integrated chain archetype through its captive supply positioning in Australian drought corridors. CleenBee anchors the platform operator model with hyperlocal fleet contract concentration in Indonesian logistics hubs. EcoWash represents the chemistry-forward specialist tier, with biodegradable formulation integration aligned to emerging compliance timelines. These three illustrate how competitive advantage is reconfiguring around water access security and regulatory anticipation rather than throughput scale alone.
| Leading Market Players |
|---|
| WashUp |
| CleenBee |
| WashEasy |
| Spiffy |
| WashMyCar |
| EcoWash |
| Mobile Car Wash |
| CleanCar |
| CarSpa |
| Others |
Pricing and Supply Chain Analysis
The Port of Singapore's container freight rates directly compress landed costs for Australian recycled-water modules and Indian biodegradable chemistry imports, concentrating margin pressure among distributors serving tier-2 Indian cities while enabling premium positioning for compliant operators in Queensland drought corridors.
Pricing Analysis
Fleet operators anchor subscription-based contract structures across Indonesian logistics hubs and Australian metropolitan corridors. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified low-flow installations from conventional high-pressure systems and unlicensed hand-wash operations. Cost compression in the standard tier is intensifying because BIS mandate compliance adds capital recovery surcharges. Individual owners in Vietnamese urban zones exhibit highest price sensitivity; Japanese premium fleet operators show least elasticity due to damage liability concerns.
Supply Chain Analysis
Specialist Australian manufacturers hold captive capacity for closed-loop filtration modules and biodegradable surfactant formulations. Component sourcing draws from South Korean pressure-system fabricators, Chinese sensor and telemetry suppliers, and domestic Australian chemistry blenders. Single-source vulnerability concentrates in recycled-water module supply where Queensland and New South Wales recovery rate mandates outstrip manufacturing scale. Distribution runs through integrated chain operators in Australian drought corridors, platform aggregators in Indian metropolitan zones, and fragmented independent networks across Vietnamese provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mobile on-demand platforms that bypass fixed-bay infrastructure investments entirely, threatening site-based revenue models across Indian tier-2 expansion markets.
For Market Incumbents: Insulate fleet contract portfolios through backward integration into water recycling module production, securing compliance capacity ahead of Australian state-level threshold escalations. Anchor subscription pricing with guaranteed turnaround slot allocation to concentrate buyer lock-in against mobile platform erosion. Prioritize technician certification pipelines in Indonesian and Vietnamese labor markets to defend service quality differentiation. For New Entrants and Emerging Players: Build out hyperlocal fleet wash platforms in Vietnamese logistics corridors around Ho Chi Minh City and Hai Phong where contract fragmentation creates first-mover consolidation potential. Target waterless chemistry application services in Australian drought-declared zones where regulatory compliance barriers filter out conventional competitors. Deploy app-based scheduling with pre-mixed ready-to-use formulations to eliminate on-site dilution complexity and accelerate customer acquisition. For Investors and Strategic Acquirers: Captive recycled-water module suppliers with established Queensland and New South Wales deployment track records represent the highest-conviction acquisition archetype for medium-term water security positioning. Long-term viability hinges on regulatory anticipation rather than throughput scale alone across the analysis window. Monitor Australian state-level environmental protection agency threshold announcements as the critical inflection signal for compliance-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water Recycling Module Production | Secures captive compliance capacity for Queensland and New South Wales recovery rate mandates. |
| Subscription-Based Fleet Contract Lock-In | Concentrates buyer power among Australian and Indonesian transport hubs with predictable utilization patterns. |
| Mobile Platform Geographic Expansion | Penetrates dense Indian tier-2 cities where fixed-bay infrastructure gaps outpace motorization surge. |
| Biodegradable Chemistry Certification Investment | Aligns formulation portfolios with emerging Australian state-level environmental compliance timelines. |
| Technician Training Pipeline Development | Addresses competency scarcity for waterless application and high-pressure system maintenance in Southeast Asian labor markets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fleet operations managers, car wash facility operators, environmental compliance officers, and water recycling equipment manufacturers; and secondary validation through Australian state-level environmental protection agency filings, Indian Central Pollution Control Board discharge standards, METI resource-efficiency labeling databases, and trade flow records for pressure-system components. Bottom-up facility count modeling and top-down motorization-driven demand estimation were triangulated against subscription contract value aggregation.
Forecast inputs span service type segmentation across automatic tunnel, self-service bay, mobile on-demand, and hand-wash modalities; technology differentiation between waterless, touchless, high-pressure, and foam-based systems; and end-user stratification among fleet operators, individual owners, businesses, and rental services. CAGRs were derived from regression against vehicle ownership growth curves, regulatory implementation schedules, and water pricing trajectory assumptions across the projection horizon. Industry-specific inputs include BIS mandate compliance cost curves and Australian drought declaration frequency patterns.
Stress conditions across monsoon variability, state-level water pricing regime shifts, and touchless equipment capex threshold movements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fleet operator contract renewal rates. Quarterly review of Australian drought declaration status, Indian metropolitan permitting queue lengths, and Vietnamese logistics fleet expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market