
 Car Care Cosmetics Market | 2026-2036
Car Care Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Car Care Cosmetics Market Insights
Auto parts store distribution is rewriting competitive access across the car care cosmetics sector. Turtle Wax leverages its shelf dominance in mass retail to sustain volume leadership in North American channels. Liqui Moly GmbH anchors its position through specialized synthetic formulations that command premium placement in European auto parts networks. Chemical Guys competes via direct-to-consumer digital infrastructure that bypasses traditional wholesale gatekeepers.
Car care cosmetics encompass protective and restorative formulations applied to vehicle surfaces, typically incorporating polymers, silicones, carnauba wax, and synthetic sealants manufactured through emulsion or solvent-based processes. These products serve to preserve aesthetic finish, prevent oxidation, and extend substrate longevity across painted, plastic, rubber, and leather surfaces. Waxes and polishes occupy mature margin pools where brand recognition defends repeat purchase, while sealants represent the fastest-growing structural segment as ceramic and synthetic technologies displace conventional natural wax applications. Interior cleaners are gaining share within the application dimension as cabin hygiene standards tighten and premium vehicle interiors command specialized treatment protocols.
EPA registration requirements for volatile organic compound emissions constrain aerosol formulation strategies in the United States, while REACH chemical authorization procedures in Europe restrict certain solvent classes and mandate comprehensive safety data documentation. The EU Green Deal's chemical sustainability targets are forcing reformulation timelines across sealant and cleaner categories. Stakeholders must monitor evolving biodegradability thresholds and regional labeling harmonization to secure cross-border market access without portfolio fragmentation.
Market Dynamics
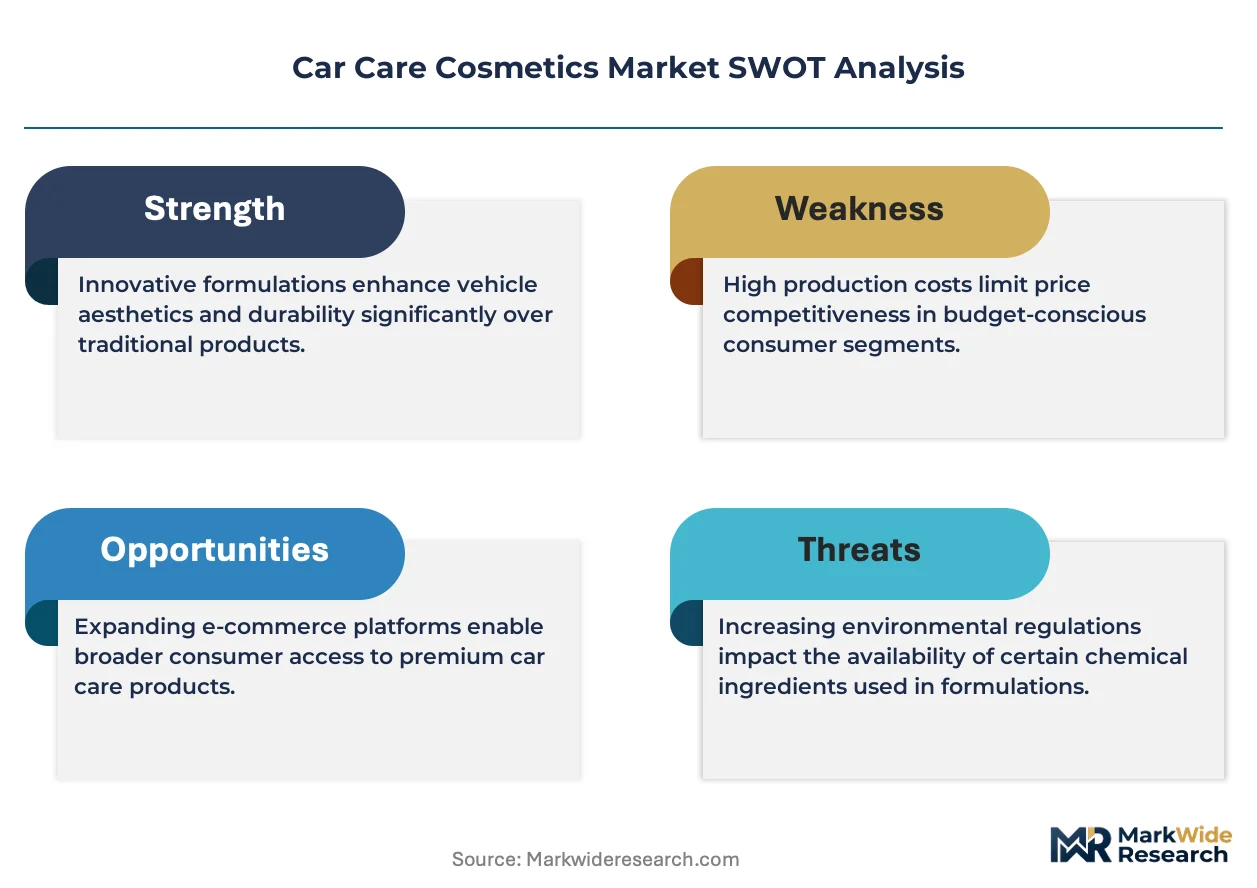
Water-based formulation mandates under EPA and REACH frameworks are forcing solvent-dependent manufacturers to rebuild product pipelines from raw material sourcing through finished goods labeling.
Growth Catalysts
- REACH chemical authorization:European biodegradability thresholds accelerate reformulation investment, opening premium positioning for compliant sealant producers.
- Professional detailing expansion:High-end service networks in Germany and the United States drive concentrated demand for ceramic coating systems and specialized interior protocols.
- Synthetic polymer advancement:Siloxane and fluoropolymer technologies extend durability claims beyond carnauba wax performance ceilings, capturing maintenance-averse vehicle owners.
Market Restraints
- Petrochemical feedstock volatility:Polymer and silicone precursor costs fluctuate with crude oil indices, compressing margin stability for mid-tier formulators.
- EPA VOC emission ceilings:Aerosol product lines face formulation constraints that increase R&D cycle length and reduce spray-applicable SKU viability.
- Natural wax substitution pressure:Carnauba harvest concentration in northeastern Brazil creates supply vulnerability during climate-disrupted growing seasons.
Strategic Opportunities
- EU Green Deal chemical sustainability targets:Early compliance investment unlocks preferential placement in European auto parts retail networks ahead of 2030 enforcement milestones.
- Direct-to-consumer digital infrastructure:Subscription-based replenishment models bypass wholesale margin stacking and capture lifetime value from enthusiast segments.
- EV-specific surface protocols:Battery housing coatings and reduced-friction wheel finishes address thermal management needs absent from internal combustion aftermarket.
Industry Challenges
- Formulation chemist scarcity:Expertise in emulsion stability and polymer crosslinking concentrates among aging specialists with limited pipeline replacement.
- Dual-registration compliance burden:Parallel EPA and REACH dossier preparation stretches regulatory affairs capacity for mid-scale exporters.
- Legacy solvent infrastructure stranding:Existing production lines engineered for hydrocarbon-based processes face accelerated obsolescence under tightening emission rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Care Cosmetics Market |
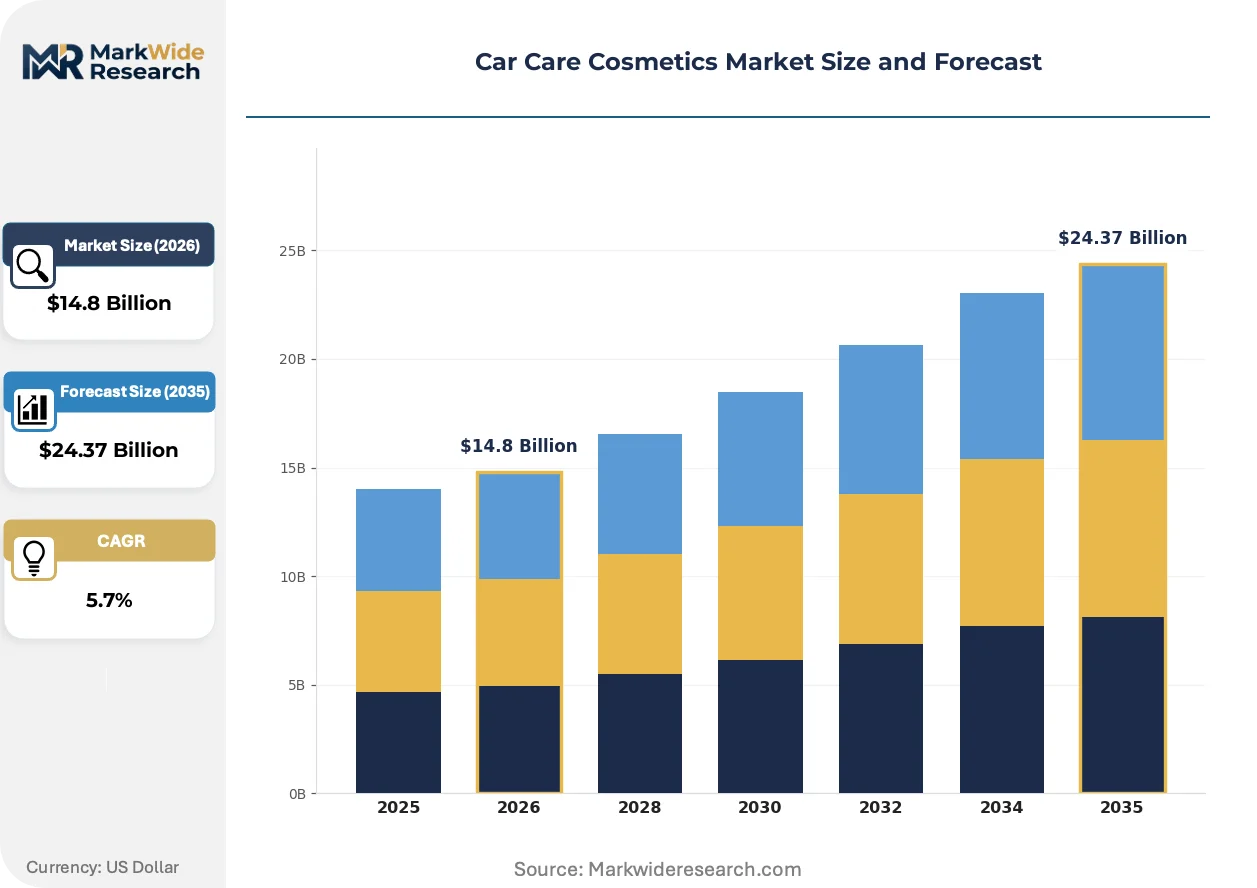
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxes, Polishes, Sealants, Cleaners Application: Exterior, Interior, Tires, Engine Formulation: Aerosol, Liquid, Paste, Gel Distribution Channel: Online Retail, Specialty Stores, Auto Parts Stores, Supermarkets |
| Companies Covered | Armor All, Liqui Moly GmbH, 3M Company, Tetrosyl Ltd., Autoglym, Turtle Wax, Meguiar's Inc., Chemical Guys, Sonax GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Care Cosmetics Market Trends and Innovations
Ceramic nanotechnology and digital distribution infrastructure are compressing traditional wax-to-retail cycles while regulatory chemistry mandates force material science investment.
Ceramic coating systems incorporating silicon dioxide and titanium dioxide nanoparticles create semi-permanent surface bonds measured in years rather than months. Professional detailers in the United States and Germany now specify these treatments as standard for premium service tiers. This technology is virtualizing the repeat-purchase revenue model that sustained natural wax brands for decades.
REACH authorization procedures for per- and polyfluoroalkyl substances restrict fluoropolymer use in sealant formulations across European markets. Manufacturers must submit comprehensive safety data packages or withdraw affected SKUs by designated sunset dates. Water-based acrylic alternatives gain shelf space as German and French distributors delist non-compliant legacy products.
Enthusiast buyers increasingly source concentrated formulations through manufacturer-direct channels rather than auto parts retail. Chemical education content and application tutorial libraries replace counter staff as the primary purchase decision support. This pattern concentrates in the United States and Australia where garage-based detailing commands cultural status.
Car Care Cosmetics Market Segmentation
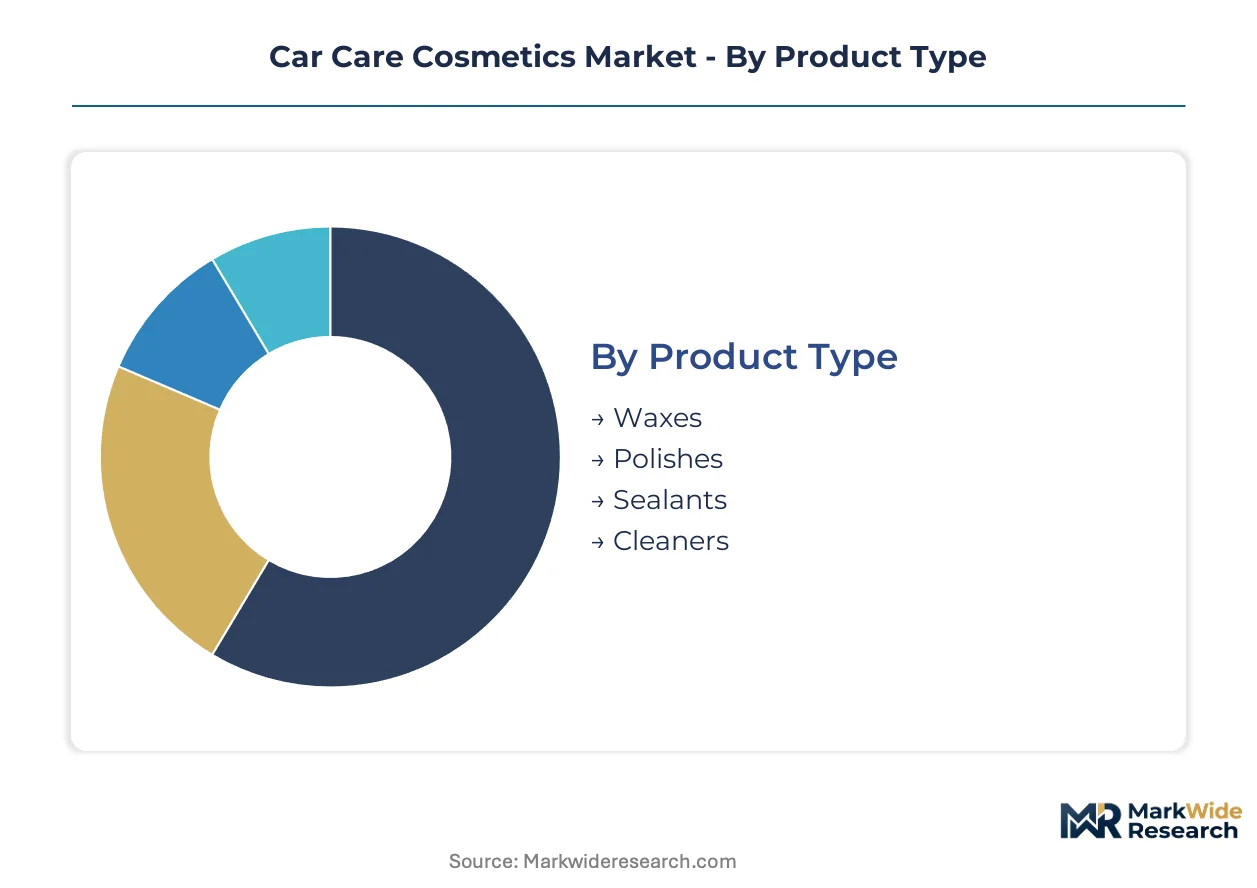
Car care cosmetics manufacturers align portfolio depth with service bay throughput patterns. Professional detailing networks demand concentrated formulations that reduce labor time per vehicle, while retail channels prioritize single-step application ease.
Product Type:
After-sales service intensity varies dramatically across formulation categories, with professional detailers driving premium tier adoption through labor-hour optimization.
- Waxes:Natural carnauba and synthetic polymer blends create sacrificial surface layers that fill micro-scratches and enhance gloss depth. Demand concentrates in United States enthusiast segments where weekend garage detailing commands cultural status, constrained by Brazilian harvest volatility during climate-disrupted growing seasons.
- Sealants:Ceramic and fluoropolymer technologies form covalent bonds with clear coat substrates, extending protection intervals from weeks to years. German professional detailing networks specify these systems as standard for premium service tiers, displacing repeat-purchase wax revenue models.
- Polishes:Abrasive compounds containing diminishing abrasives or chemical cleaners restore optical clarity to oxidized paint surfaces.
- Cleaners:pH-balanced surfactant formulations remove bonded contaminants without stripping existing protection layers.
Waxes hold the largest share; momentum sits with sealants.
Application:
Cost tier differentiation separates professional service protocols from consumer-grade convenience products.
- Exterior:Paint, glass, and trim formulations represent the highest-margin application category due to visible aesthetic impact and durability claims.
- Interior:Leather conditioners, plastic protectants, and fabric cleaners gain share as cabin hygiene standards tighten and premium vehicle interiors command specialized treatment protocols.
- Tires:Solvent-based dressings and water-based gels restore sidewall appearance with varying longevity profiles.
- Engine:Degreasers and dressing products address bay detailing for resale preparation and enthusiast display.
Exterior applications dominate value capture; interior protocols are expanding most quickly.
Formulation:
Volume concentration favors liquid formats that integrate with automated dispensing systems in high-throughput service environments.
- Liquid:Pump-spray and trigger-spray formats enable precise application control and bulk refill economics in professional settings.
- Paste:High-viscosity carnauba and synthetic blends target hand-application enthusiasts seeking tactile feedback and controlled working time.
- Aerosol:EPA VOC emission ceilings constrain spray-applicable SKU viability, forcing reformulation investment or portfolio withdrawal.
- Gel:Thixotropic formulations cling to vertical surfaces without runoff, addressing tire dressing and trim coating applications.
Liquid formats command the greatest volume; gel applications show steepest expansion trajectory among specialized detailers.
Distribution Channel:
Customer type fragmentation separates enthusiast direct procurement from convenience-driven mass retail purchasing.
- Auto Parts Stores:Shelf placement in dedicated automotive retail networks captures maintenance-conscious vehicle owners during parts purchase occasions.
- Online Retail:Manufacturer-direct channels and marketplace platforms concentrate enthusiast buyers seeking concentrated formulations and educational content.
- Specialty Stores:Detailing supply boutiques serve professional service providers with bulk pricing and technical support.
- Supermarkets:Mass retail placement reaches incidental purchasers through seasonal promotional cycles and impulse positioning.
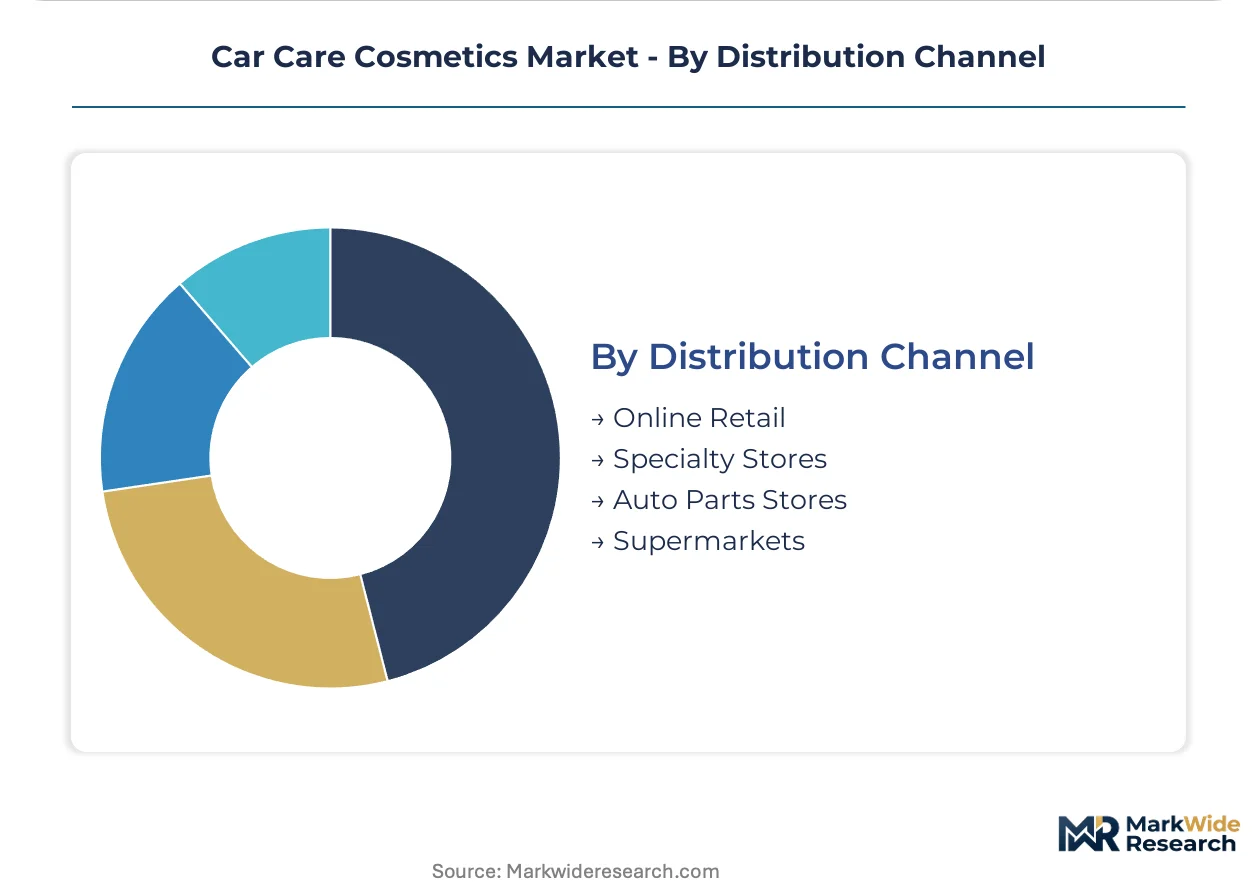
Auto parts stores retain the largest transaction volume; online retail is gaining share fastest among educated enthusiast segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German chemical formulators to Brazilian carnauba wax suppliers and Asian silicone precursor markets. This maritime infrastructure underwrites Europe's formulation leadership while sustaining raw material pipelines for water-based sealant innovation.
United States
Professional detailing networks in Los Angeles and Miami drive concentrated demand for ceramic coating systems and specialized interior protocols. EPA VOC emission ceilings under the Clean Air Act constrain aerosol formulation strategies, forcing R&D cycle extensions. The Detroit automotive cluster sustains aftermarket parts retail density that captures maintenance-conscious vehicle owners during purchase occasions.
Germany
REACH chemical authorization procedures restrict fluoropolymer use in sealant formulations, mandating comprehensive safety data documentation. The EU Green Deal's chemical sustainability targets force reformulation timelines across cleaner categories. Stuttgart's automotive engineering corridor anchors premium vehicle ownership rates that command specialized cabin treatment protocols.
China
Vehicle ownership expansion in Shanghai and Guangzhou accelerates aftermarket spending on protective surface formulations. MEE enforcement of dual carbon goals pressures solvent-dependent manufacturers toward water-based pipeline rebuilds. The Yangtze River Delta manufacturing belt concentrates emulsion chemistry capacity serving domestic and export sealant demand.
Japan
PMDA-aligned chemical safety standards and METI industrial policy shape formulation registration requirements for imported car care products. Tokyo-Osaka metropolitan vehicle density supports premium detailing service networks. The Kanto region's precision chemical sector supplies polymer additives for ceramic nanotechnology applications.
Brazil
Carnuaba wax harvest concentration in northeastern Ceará and Piauí states creates supply vulnerability during climate-disrupted growing seasons. ANVISA chemical registration procedures govern imported sealant and cleaner formulations entering São Paulo's aftermarket retail channels. The São Paulo industrial corridor processes raw wax exports while developing domestic blending capacity for regional distribution.
Car Care Cosmetics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and formulation technology. The vendor base organizes around three archetypes: mass retail shelf dominators leveraging auto parts store networks, professional-grade specialists serving detailing service bays, and direct-to-consumer digital natives bypassing wholesale gatekeepers. Consolidation pressure concentrates among mid-tier formulators facing dual EPA and REACH compliance burdens. Dominant competitive moves include portfolio diversification into water-based formulations and geographic expansion through distributor partnerships in Asian growth markets.
Among German-based chemical formulators, Liqui Moly GmbH and Sonax GmbH exemplify the professional-grade specialist archetype, anchoring premium placement in European auto parts networks through synthetic formulation expertise. Turtle Wax occupies a position within the mass retail platform tier, leveraging shelf dominance to sustain volume leadership across North American channels. Chemical Guys represents the direct-to-consumer digital native model, utilizing educational content infrastructure to capture enthusiast segments outside traditional wholesale structures.
| Leading Market Players |
|---|
| Armor All |
| Liqui Moly GmbH |
| 3M Company |
| Tetrosyl Ltd. |
| Autoglym |
| Turtle Wax |
| Meguiar's Inc. |
| Chemical Guys |
| Sonax GmbH |
| Others |
Pricing and Supply Chain Analysis
Brazilian carnauba wax harvest concentration in Ceará and Piauí states anchors premium tier pricing power for natural formulation suppliers, while synthetic polymer feedstock volatility in Asian petrochemical corridors compresses margin stability for mid-tier sealant producers competing on volume.
Pricing Analysis
Volume-discount tiering structures separate professional detailing bulk procurement from retail single-unit purchases, with concentrated formulations commanding per-liter premiums that offset dilution economics. Price differentiation rests on EPA compliance certification tiers and ceramic nanotechnology performance claims. Cost compression in mid-tier wax blends is intensifying because Brazilian climate disruptions constrain carnauba supply reliability. Mass retail auto parts purchasers exhibit highest price sensitivity, while German professional detailers prioritize durability claims over unit economics.
Supply Chain Analysis
Contract manufacturing concentration among German chemical formulators and Yangtze River Delta emulsion specialists holds capacity for water-based sealant production. Raw material pipelines draw from Brazilian carnauba cooperatives, South Korean silicone precursor plants, and German polymer additive facilities. Single-source vulnerability concentrates in northeastern Brazilian wax harvesting regions exposed to drought cycles. Distribution runs through auto parts retail networks in North America and Europe, with direct-to-consumer channels gaining share among enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward professional detailing networks as service bay consolidation in Germany and the United States concentrates procurement volume among fewer high-throughput operators capable of dictating formulation specifications.
For Market Incumbents: Build regulatory compliance moats through early REACH biodegradability certification and EPA VOC registration dossiers. Secure carnauba supply through backward integration into Brazilian harvesting cooperatives before climate volatility disrupts competitor pipelines. Ceramic coating substitution threatens repeat-purchase wax revenue models; defend through sealant technology licensing to captive professional networks. For New Entrants and Emerging Players: China's interior cleaner segment offers underpenetrated white space as cabin hygiene standards tighten in Shanghai and Guangzhou vehicle ownership expansion. EV-specific surface protocols for battery housing coatings represent adjacent application territory absent entrenched competition. Capture share through educational content infrastructure that replaces counter staff as purchase decision support. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier formulators facing dual EPA and REACH compliance burdens without scale economies for dossier preparation. Five-to-ten year viability favors water-based technology platforms over solvent-dependent legacy infrastructure. Monitor ANVISA registration timelines for Brazilian market access as inflection indicator for regional expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Transition | EPA VOC ceilings and REACH biodegradability mandates force pipeline rebuilds from raw material sourcing through labeling. |
| Direct-to-Consumer Channel Buildout | Manufacturer-direct digital infrastructure bypasses wholesale margin stacking and captures enthusiast lifetime value. |
| Ceramic Nanotechnology Licensing | Silicon dioxide and titanium dioxide nanoparticle systems displace repeat-purchase wax models with semi-permanent bonds. |
| Brazilian Supply Integration | Captive carnauba harvesting arrangements mitigate climate disruption exposure in Ceará and Piauí growing regions. |
| EV-Specific Surface Protocol Development | Battery housing coatings and reduced-friction wheel finishes address thermal management needs absent from ICE aftermarket. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, professional detailing network operators, auto parts retail category managers, and regulatory affairs specialists; and secondary validation through EPA registration databases, ECHA REACH dossier filings, customs trade records, and automotive aftermarket production data. Bottom-up triangulation across SKU-level volume estimates and top-down market sizing anchored projection reliability.
Forecast inputs considered product type segmentation across waxes, sealants, polishes, and cleaners; application dimension across exterior, interior, tires, and engine protocols; formulation format across liquid, paste, aerosol, and gel; and distribution channel fragmentation across auto parts stores, online retail, specialty boutiques, and supermarkets. CAGRs were derived from regression analysis against vehicle ownership trajectories and aftermarket spending intensity across the analysis window. Ceramic coating adoption curves and water-based formulation transition timelines served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese emulsion specialists or accelerated EU Green Deal enforcement milestones would shift outcomes. Quarterly review of EPA VOC rulemaking dockets, ECHA authorization sunset dates, and Brazilian agricultural climate indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market