
 Car Care Products Market | 2026-2036
Car Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Car Care Products Market Intelligence
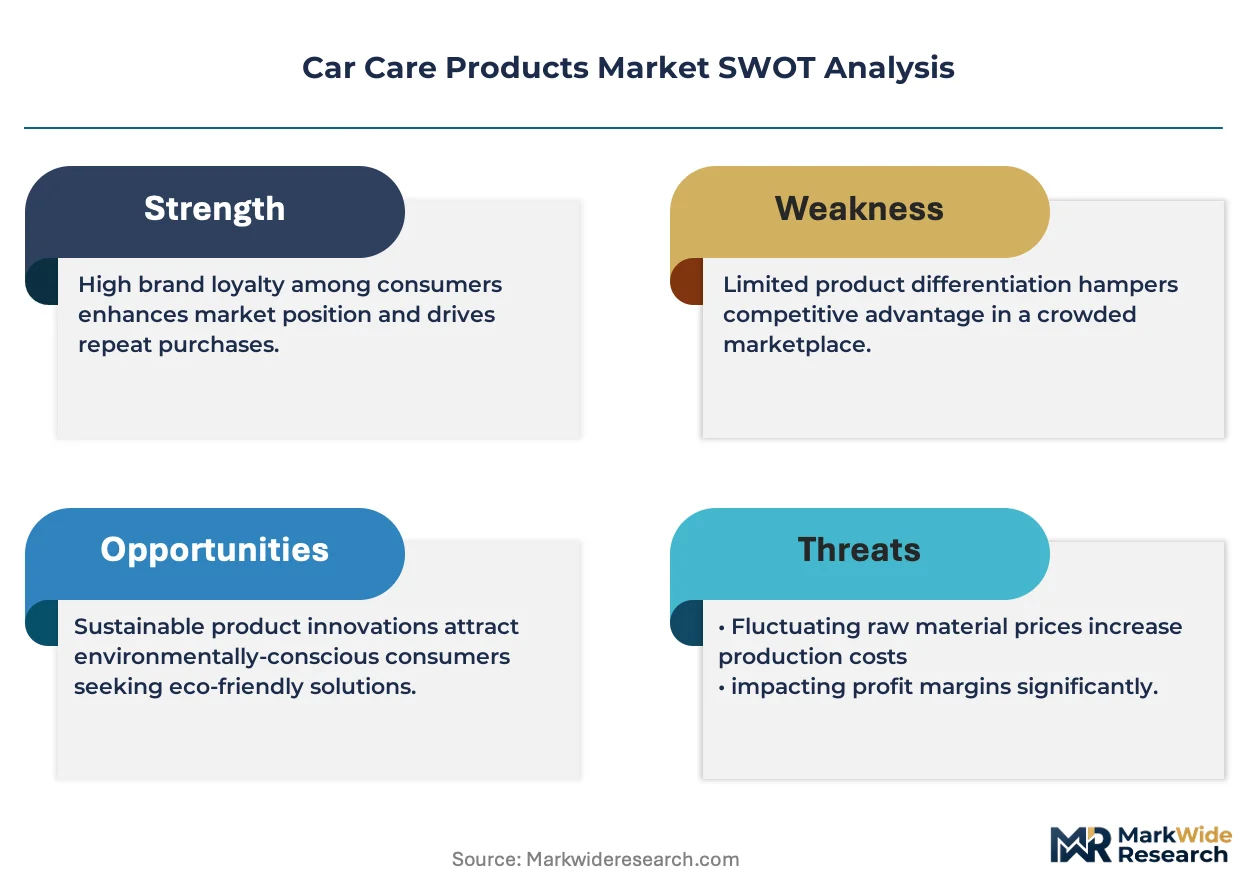
ISO 14001 environmental management certification is bifurcating the competitive landscape between compliant formulators and legacy suppliers. 3M Company leverages its materials science portfolio to sustain premium positioning in professional sealant categories. Turtle Wax, Inc. anchors mass-market volume through dominant shelf placement at North American auto retailers. Sonax GmbH differentiates via German-engineered polish formulations that command workshop loyalty across European automotive shops.
Car care products encompass chemical formulations including carnauba wax blends, synthetic polymer sealants, pH-neutral surfactant cleaners, and abrasive compounds engineered for specific substrate compatibility on painted, glass, and interior surfaces; these products protect vehicle surfaces from oxidation, UV degradation, and contaminant bonding while restoring optical clarity and tactile finish. Waxes and polishes occupy mature margin pools sustained by enthusiast consumer segments, while sealants represent the fastest-growing product category as ceramic and graphene-infused technologies displace traditional natural wax durability benchmarks. Interior care applications are expanding fastest among end-user segments as cabin air quality and antimicrobial surface treatments gain priority among fleet providers and detailers.
EPA VOC regulations in the United States and REACH chemical restrictions in Europe are forcing reformulation of solvent-based cleaners toward waterborne and bio-based alternatives, while California Air Resources Board Phase II limits specifically constrain aerosol propellant selections. China's MEE national standards on hazardous substance labeling and GB/T quality benchmarks for automotive chemicals are raising import compliance barriers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional SKUs deliver superior compliance economics.
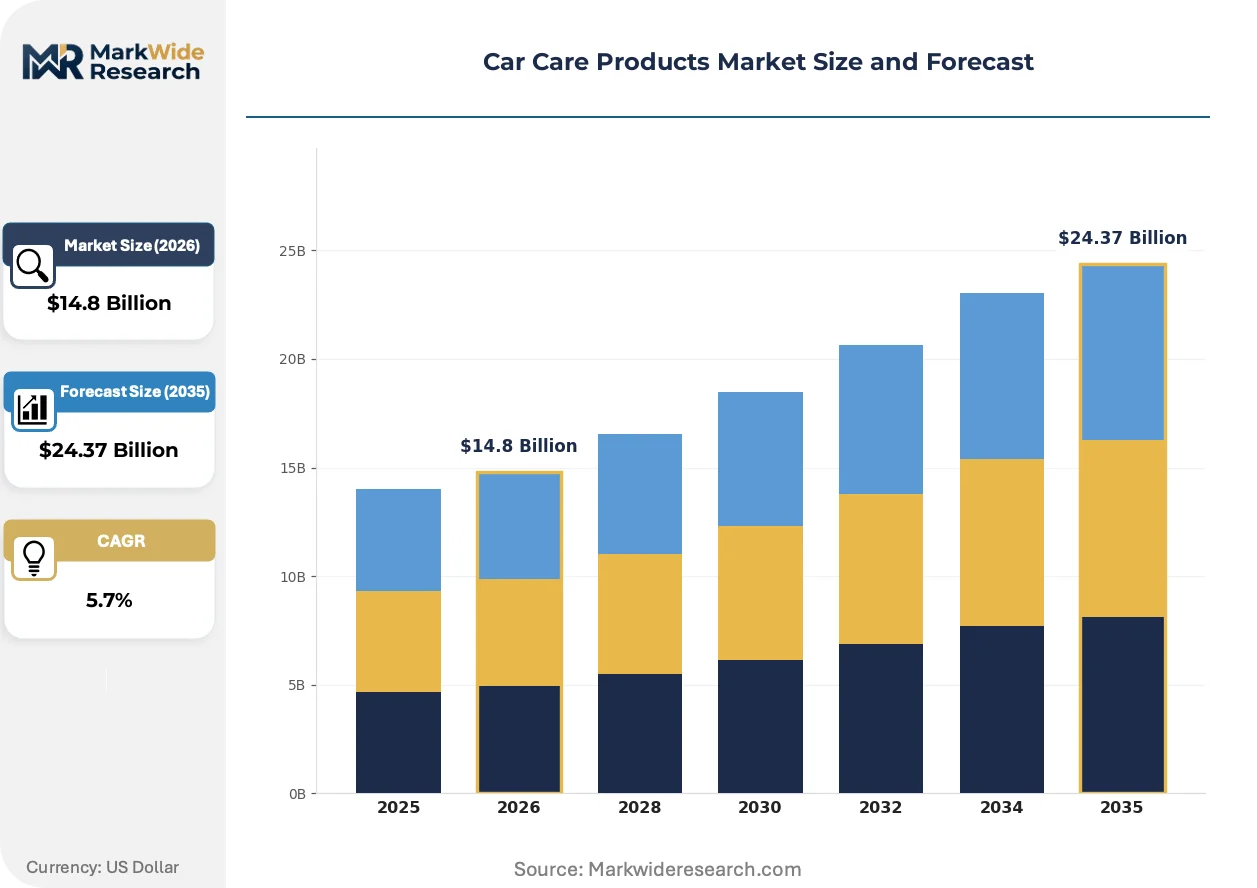
Market Dynamics
Ceramic and graphene-infused sealant technologies are compressing traditional wax durability benchmarks while forcing formulators to rebuild R&D roadmaps around nanoscale surface engineering. Fleet procurement teams now specify performance warranties measured in years rather than months, redirecting volume toward professional-grade synthetic formulations.
Growth Catalysts
- REACH Phase-Down Mandates:European chemical restrictions on VOC emissions are accelerating waterborne cleaner adoption across German and French automotive workshops, creating compliant product pull-through.
- China Domestic Car Parc Expansion:Vehicle fleet growth and aftermarket service network densification in Shanghai and Guangzhou are concentrating wax and polish consumption in independent detailer channels.
- Ceramic Coating Durability Standards:Professional detailers now specify 3-5 year protection guarantees, shifting specification authority from retail consumers to B2B procurement teams.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer sealants depend on propylene and silane derivatives whose price swings compress formulator margins unpredictably.
- California Air Resources Board Aerosol Limits:Phase II propellant restrictions constrain spray-can cleaner formulations, forcing capital-intensive production line reconfigurations for US-market suppliers.
- DIY Consumer Substitution:Home-improvement retailers now bundle basic wash-and-wax kits at price points that undercut professional-grade chemical margins by half.
Strategic Opportunities
- Antimicrobial Interior Treatments:Fleet providers and rideshare operators are specifying cabin air quality protocols, opening formulation white space beyond traditional vinyl conditioners.
- ISO 14001 Certification Arbitrage:Environmental management credentials now gate access to European automotive OEM approved supplier lists, rewarding early compliance investment.
- Direct-to-Detailer E-Commerce:Specialized chemical distributors are bypassing traditional auto parts wholesalers to capture margin through subscription replenishment models.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of polymer science and regulatory compliance expertise is narrowing the qualified talent pool for next-generation sealant development.
- Multi-Jurisdiction SKU Proliferation:Divergent VOC limits between California, the European Union, and China's MEE standards are fragmenting production runs and compressing batch economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Care Products Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxes, Polishes, Cleaners, Sealants Application: Interior Care, Exterior Care, Maintenance, Detailing End User: Individual Consumers, Automotive Shops, Fleet Providers, Detailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Workshops |
| Companies Covered | 3M Company, Turtle Wax, Inc., Sonax GmbH, Tetrosyl Ltd., Autoglym, ITW Global Brands, Liqui Moly GmbH, SOFT99 Corporation, Chemical Guys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Care Products Market Strategic Shifts & Innovations
Surface chemistry innovation is bifurcating the market between nanotechnology-enabled durability and bio-based regulatory compliance. Formulators must now engineer simultaneous performance against oxidation, UV degradation, and microbial colonization while navigating tightening chemical restrictions across multiple jurisdictions.
Graphene-oxide ceramic hybrids are displacing traditional carnauba-synthetic blends in premium sealant categories by offering measurable hardness ratings and extended hydrophobic performance. Professional detailing shops in California and Florida are specifying these formulations for fleet contracts requiring multi-year protection intervals. The technology is displacing natural wax volume in high-margin professional channels while compressing reapplication frequency and aftermarket chemical consumption.
EPA VOC regulations and REACH chemical restrictions are forcing synchronized reformulation of solvent-based cleaners toward waterborne and bio-based surfactant systems. California Air Resources Board protocols specifically constrain aerosol propellant selections, pushing manufacturers toward trigger-spray and bulk-concentrate delivery formats. European automotive chemical suppliers are responding by consolidating regional formulation platforms to reduce compliance-driven SKU complexity.
Fleet procurement teams are consolidating chemical purchasing through national service contracts that bundle exterior protection, interior sanitization, and windshield treatment into single-source agreements. Independent detailers and small multi-location operators are losing specification authority to centralized procurement functions at rental car and logistics fleet operators. This concentration is most visible in the United States and Germany where vehicle fleet standardization programs now mandate approved chemical registries.
Car Care Products Market Segmentation
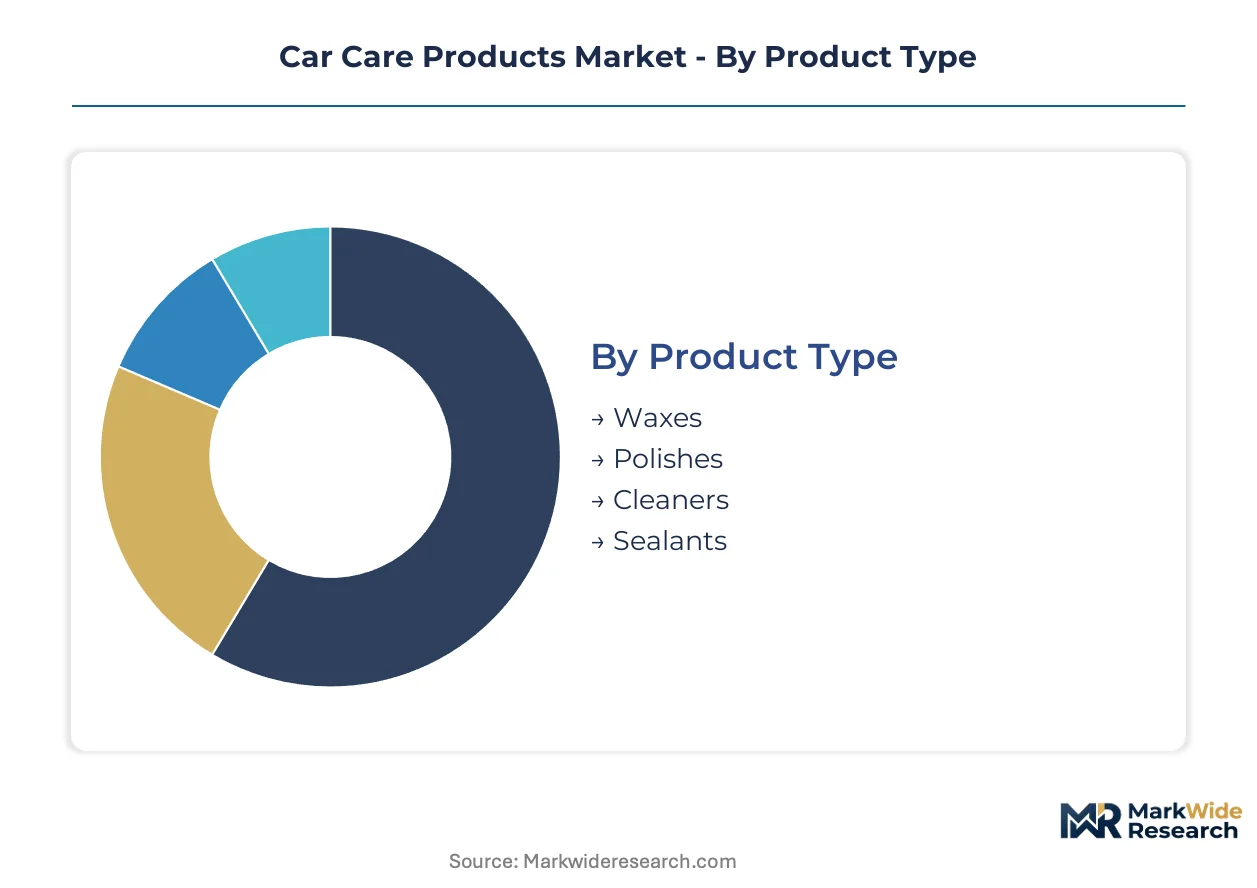
Chemical formulation requirements diverge sharply across use cases, forcing suppliers to maintain parallel product architectures. Segmentation discipline determines whether formulators capture fleet procurement contracts or surrender volume to compliant competitors.
Product Type:
REACH Phase-Down mandates and California Air Resources Board protocols are fragmenting formulation platforms by volatility classification.
- Waxes:Carnauba-synthetic blends dominate enthusiast retail channels with tactile finish characteristics. German and French automotive workshops now specify waterborne alternatives to meet ECHA compliance deadlines, compressing solvent-based volume.
- Sealants:Ceramic and graphene-infused formulations command specification authority from fleet procurement teams requiring multi-year protection warranties. Professional detailers in California and Florida specify these for rental car contracts with 3-5 year durability guarantees.
- Polishes:Abrasive compounds engineered for specific substrate compatibility serve European automotive shops with German-engineered formulations commanding workshop loyalty.
- Cleaners:pH-neutral surfactant systems displace solvent-based alternatives under EPA VOC regulations, with waterborne formats gaining share in US and EU markets.
Established volume favors waxes; emerging adoption favors sealants.
Application:
Performance guarantees now vary by surface exposure and reapplication economics.
- Interior Care:Antimicrobial surface treatments and cabin air quality protocols are expanding fastest among fleet providers and rideshare operators. This segment climbs the fastest as vinyl conditioners give way to sanitization-focused formulations.
- Exterior Care:UV degradation and oxidation protection remain core specifications for consumer retail channels, with durability claims determining price positioning.
- Detailing:Optical clarity restoration commands premium pricing from professional shops serving luxury vehicle owners.
- Maintenance:Routine wash protocols concentrate volume in mass-market retail with compressed margins from bundled kit offerings.
Volume concentrates in exterior care; margin expansion concentrates in interior care.
End User:
Procurement centralization is bifurcating the customer base between specification authority and price sensitivity.
- Fleet Providers:National service contracts bundle exterior protection, interior sanitization, and windshield treatment into single-source agreements. Rental car and logistics operators in the United States and Germany now mandate approved chemical registries.
- Detailers:Professional shops specify ceramic coating durability standards, shifting authority from retail consumers to B2B procurement teams with multi-year protection requirements.
- Automotive Shops:Workshop loyalty programs reward compliant formulators with ISO 14001 certification access to European OEM approved supplier lists.
- Individual Consumers:DIY substitution pressures professional-grade margins as home-improvement retailers bundle basic wash-and-wax kits at discounted price points.
Specification authority concentrates with fleet providers; volume concentrates with individual consumers.
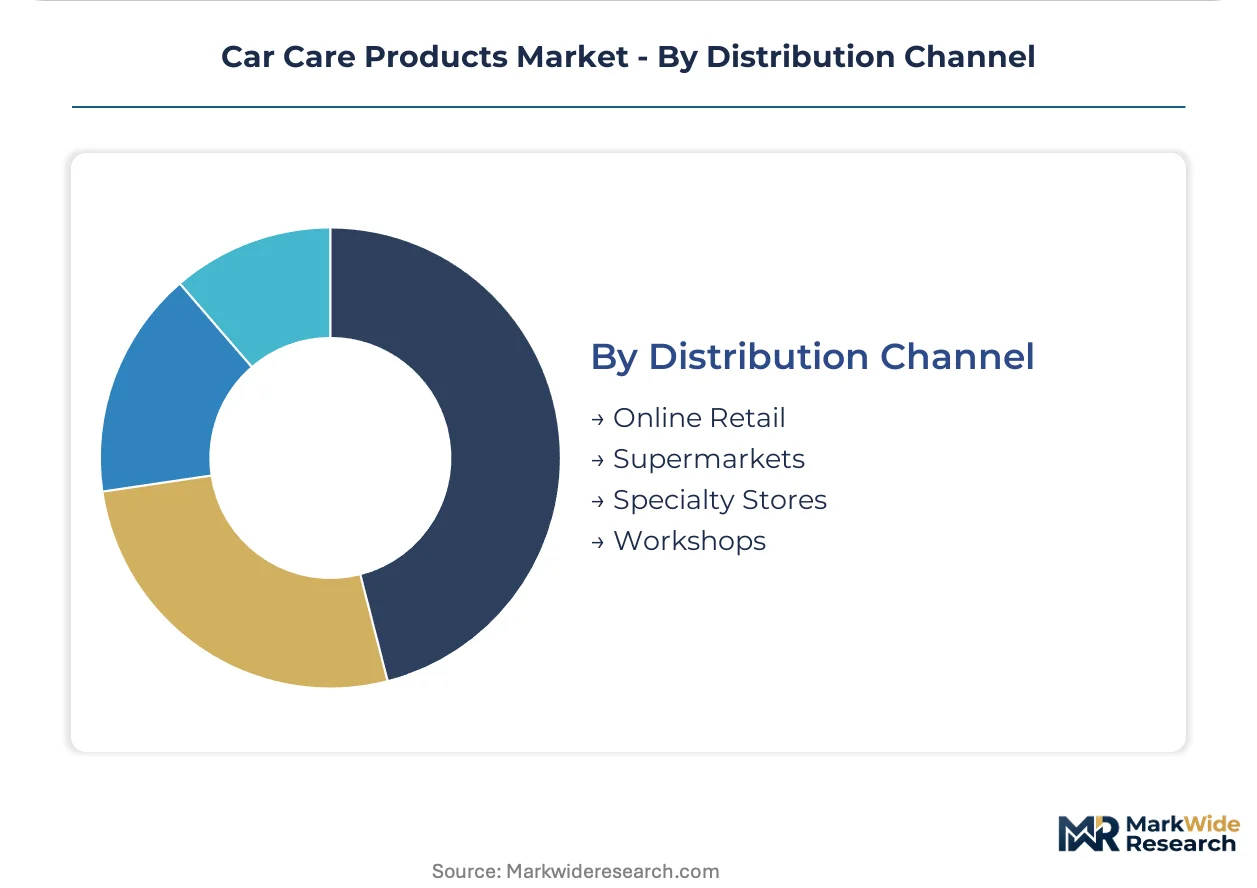
Distribution Channel:
Channel economics determine compliance investment recovery rates and customer acquisition costs.
- Workshops:Direct technical relationships enable formulation customization for professional durability requirements. European automotive chemical suppliers consolidate regional platforms to serve this channel efficiently.
- Specialty Stores:Dominant shelf placement at North American auto retailers anchors mass-market volume for established brands.
- Online Retail:Subscription replenishment models allow specialized chemical distributors to bypass traditional auto parts wholesalers and capture margin directly.
- Supermarkets:Price-competitive bundling serves occasional users with compressed formulation complexity and limited performance claims.
Margin recovery favors workshops; volume scale favors specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California Air Resources Board Phase II protocols and REACH Phase-Down mandates are redirecting formulation investments toward compliant manufacturing hubs. Fleet standardization programs in Germany and the United States are consolidating procurement authority into national service contracts.
United States
Fleet procurement centralization at rental car and logistics operators drives specification authority toward professional-grade synthetic sealants. EPA VOC regulations and California Air Resources Board aerosol limits constrain solvent-based cleaner formulations. Professional detailing clusters in Los Angeles and Miami specify ceramic coating durability guarantees for fleet contracts.
Germany
Automotive workshop loyalty programs reward ISO 14001-certified formulators with access to OEM approved supplier lists. ECHA REACH compliance deadlines accelerate waterborne wax adoption across Bavarian and Baden-Württemberg service networks. Frankfurt and Stuttgart detailing hubs command premium positioning for German-engineered polish formulations.
China
Domestic car parc expansion and aftermarket service network densification concentrate wax and polish consumption in independent detailer channels. MEE national standards on hazardous substance labeling and GB/T quality benchmarks raise import compliance barriers. Shanghai and Guangzhou aftermarket clusters accelerate consumption of professional-grade maintenance chemicals.
Japan
Precision manufacturing heritage sustains demand for substrate-specific abrasive compounds in automotive refinishing applications. METI industrial standards and JIS quality benchmarks govern automotive chemical formulation requirements. Osaka and Nagoya industrial corridors maintain workshop loyalty through technical service relationships.
United Kingdom
Independent detailer channels retain specification authority for enthusiast-grade carnauba-synthetic wax blends. Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance obligations for UK-market formulations. London and Birmingham metropolitan areas concentrate premium detailing service demand.
Car Care Products Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with materials science capabilities and specialized automotive formulators with regional workshop relationships. Market structure exhibits moderate consolidation at the premium professional tier alongside fragmentation in mass-market retail channels. Two dominant archetypes emerge: integrated materials science operators leveraging polymer portfolios and focused automotive chemical specialists commanding workshop loyalty. Competitive dynamics center on M&A activity targeting ceramic coating technology assets and geographic expansion through distributor partnership networks.
Within the materials science tier, 3M Company and SOFT99 Corporation exemplify integrated operators with polymer and surface chemistry capabilities. Among European workshop-focused formulators, Sonax GmbH and Liqui Moly GmbH occupy positions anchored by technical service relationships with automotive service networks. Turtle Wax, Inc. represents the mass-market retail archetype through dominant shelf placement at North American auto retailers.
| Leading Market Players |
|---|
| 3M Company |
| Turtle Wax, Inc. |
| Sonax GmbH |
| Tetrosyl Ltd. |
| Autoglym |
| ITW Global Brands |
| Liqui Moly GmbH |
| SOFT99 Corporation |
| Chemical Guys |
| Others |
Cost & Logistics Intelligence
Batch-scale economies in sealant manufacturing concentrate margin recovery among German and Chinese formulators running multi-tonne polymer synthesis, compressing price floors for smaller regional blenders while elevating procurement leverage for fleet buyers consolidating national contracts.
Pricing Analysis
Certification level creates the primary spread between professional-grade and mass-market tiers, with ISO 14001 environmental credentials commanding premium positioning in European automotive workshops. Three-tier pricing structure across premium ceramic sealants, standard synthetic waxes, and economy wash concentrates reflects performance warranty duration and VOC compliance investment. Cost compression in economy tiers intensifies as home-improvement retailers bundle basic kits, while fleet procurement teams show lowest price sensitivity due to total-cost-of-ownership framing around multi-year protection intervals.
Supply Chain Analysis
Inventory cycles for silane-derived ceramic precursors stretch 8-12 weeks from German and Chinese specialty chemical producers to North American blending facilities, constraining just-in-sequence responsiveness for rush fleet orders. Propylene feedstock draws from Gulf Coast petrochemical complexes and Middle Eastern export hubs, exposing formulators to commodity volatility. Single-source vulnerability concentrates in graphene-oxide nanoparticle supply, where patent-protected production rests on three global licensors. Distribution runs through authorized chemical distributors serving professional detailer networks, bypassing traditional auto parts wholesalers for margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic coating durability standards and REACH Phase-Down mandates are disrupting procurement patterns, rewarding formulators with compliant waterborne platforms and punishing legacy solvent-dependent suppliers.
For Market Incumbents: Fortify specification authority by deepening captive supply of silane precursors through backward integration into German or Chinese specialty chemical production. Secure ISO 14001 certification arbitrage to gatekeep European OEM approved supplier lists against emerging competitors lacking environmental management credentials. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or France opens workshop channel access without incumbent distributor entrenchment. Target antimicrobial interior treatments as the most penetrable white space, where fleet rideshare protocols outpace existing supplier formulation roadmaps. Lead with direct-to-detailer subscription replenishment models to bypass wholesale margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ceramic coating technology specialists with fleet service contract backlogs. Long-term viability favors acquisition targets combining polymer science R&D capabilities with existing ISO 14001 certification infrastructure. Watch for inflection when California Air Resources Board Phase III propellant restrictions force aerosol line reconfigurations, triggering distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Captive supply of ceramic coating feedstock secures margin against propylene volatility. |
| ISO 14001 Certification Investment | Environmental credentials gate European OEM approved supplier list access. |
| Direct-to-Detailer E-Commerce Launch | Subscription replenishment bypasses traditional auto parts wholesale margin extraction. |
| Antimicrobial Interior Formulation R&D | Fleet cabin air quality protocols open white space beyond traditional vinyl conditioners. |
| Regional Formulation Platform Consolidation | Unified waterborne platforms reduce SKU complexity under divergent VOC regulations. |
Research Approach
Operator-level perspectives from formulator R&D directors, fleet procurement managers, professional detailer shop owners, and automotive workshop service managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement actions, ECHA REACH substance restriction updates, China MEE hazardous substance labeling standards, and customs trade data on automotive chemical imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness against petrochemical feedstock price scenarios, regulatory phase-in timing variations, and fleet procurement centralization rates across the projection horizon. Segmentation dimensions modeled included chemical formulation class, surface application type, buyer procurement archetype, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating vehicle fleet growth, aftermarket service network expansion, and technology substitution curves for ceramic versus natural wax durability benchmarks.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH Phase-Down enforcement and stable fleet standardization program adoption; material deviation in regulatory timelines or feedstock cost regimes would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market