
 Car Duster Market | 2026-2036
Car Duster Market Size, Share, and Industry Trends Forecast 2026-2036
Car Duster Market Outlook
ISO 9001 quality management certification is unwinding the competitive landscape for smaller duster manufacturers unable to sustain audit costs. California Car Duster leverages its West Coast manufacturing base to control specialty retail channels. Mothers Polish anchors its position through R&D intensity in microfiber weave technologies. Meguiar's competes on brand strength among enthusiast segments willing to pay premium prices for validated performance claims.
A car duster is a handheld cleaning instrument composed of treated or untreated fibers—typically cotton, microfiber, or synthetic blends—mounted on a handle, designed to lift and trap particulate matter from painted automotive surfaces without scratching or marring the clear coat. The device serves the primary commercial purpose of maintaining vehicle cosmetic appearance between washes, reducing swirl marks and preserving resale value. Microfiber variants command the dominant share of product type revenue due to superior particle retention and reusability, while feather dusters face structural decline amid animal welfare sourcing concerns. The automotive application segment leads absolute volume, though car washes and rental services within the end user dimension represent the fastest-growing procurement channel as fleet maintenance standardization spreads.
The US EPA regulates volatile organic compound emissions in duster treatments under consumer product rules, while California's Proposition 65 mandates disclosure of chemical additives that may contact vehicle surfaces. REACH compliance in Europe restricts certain dye and preservative chemistries, forcing exporters to maintain dual formulation inventories. Stakeholders must monitor evolving state-level chemical restrictions and fiber traceability mandates to anticipate reformulation costs and sourcing disruptions.
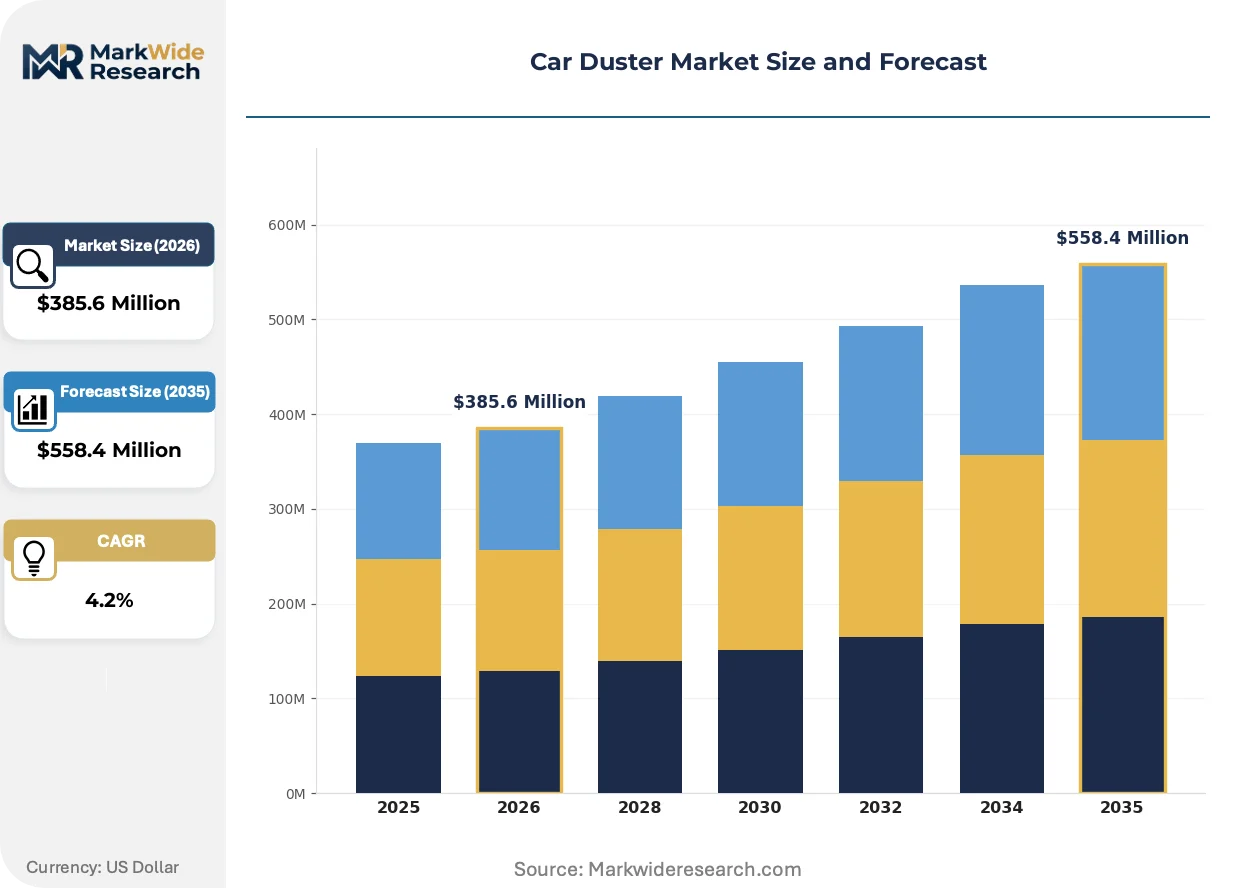
Market Dynamics
California's Proposition 65 chemical labeling mandates are forcing reformulation of treated fiber dusters toward untreated cotton and certified microfiber, compressing margins for manufacturers reliant on paraffin-based treatments while creating certification barriers for new entrants.
Growth Catalysts
- Professional car wash procurement:National chains are standardizing microfiber duster specifications across fleet maintenance programs, creating volume pull-through.
- REACH dye restrictions:European chemical compliance is accelerating dual-formulation R&D investment among exporters serving transatlantic markets.
- Sun Belt dust exposure:Arizona, Texas, and Florida vehicle ownership concentrations sustain replacement demand cycles.
Market Restraints
- Cotton fiber price volatility:Commodity cotton futures fluctuation compresses margin stability for untreated fiber specialists.
- ISO 9001 audit cost concentration:Quality management certification expenses disproportionately burden sub-$5M revenue manufacturers.
- Feather duster substitution collapse:Animal welfare sourcing concerns eliminate premium ostrich feather alternatives.
Strategic Opportunities
- Rental fleet standardization:Enterprise Holdings and Avis Budget Group procurement centralization creates vendor consolidation windows.
- Amazon private label entry:E-commerce direct-to-consumer channel bypasses specialty retail margin stacking.
- EU Green Deal fiber traceability:Blockchain-enabled supply chain verification commands premium positioning in European markets.
Industry Challenges
- Microfiber weave engineering talent scarcity:Polymer science expertise gaps constrain R&D velocity for domestic manufacturers.
- Dual inventory complexity:REACH-compliant versus EPA-compliant formulation separation strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Duster Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiber, Feather, Synthetic, Cotton Application: Automotive, Home, Industrial, Aerospace End User: Consumers, Dealerships, Car Washes, Rental Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | California Car Duster, Mothers Polish, Libman Company, Prolux, Meguiar's, Turtle Wax, Armor All, Carrand, AutoBra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
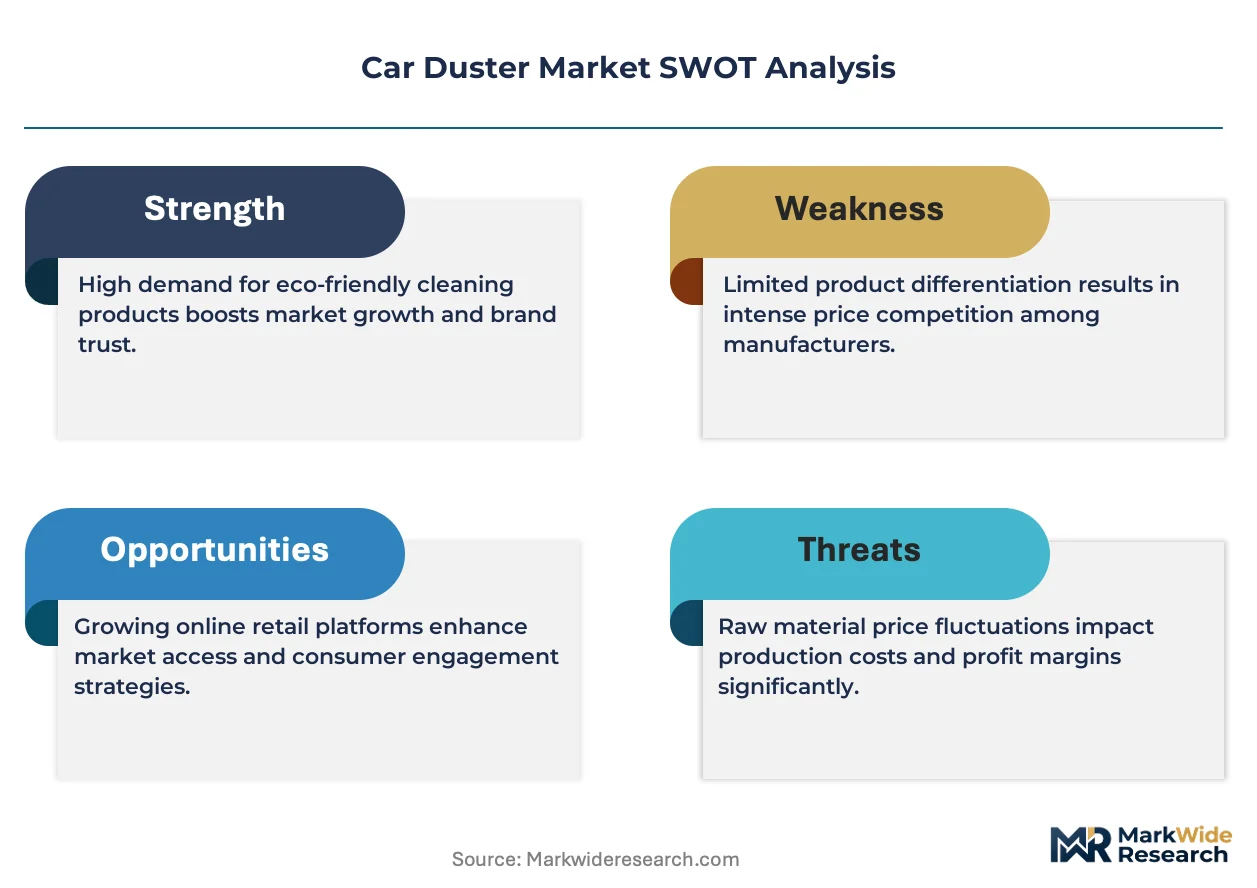
Car Duster Market Strategic Shifts
Material science advancement and regulatory chemistry restrictions are converging to reshape fiber composition and treatment protocols. Distribution channel compression is accelerating direct procurement relationships.
Electrostatic microfiber blends with split-fiber architecture are supplanting traditional cotton and feather formulations in professional detailing applications. Meguiar's and Mothers Polish are accelerating adoption through validated performance claims in enthusiast segments. This transition is compressing commodity cotton duster margins while expanding addressable market for premium reusable systems.
REACH Annex XVII dye and preservative restrictions are forcing European exporters to maintain segregated formulation inventories. Manufacturers serving EU markets must now certify fiber traceability through ECHA-registered supply chains. California exporters face parallel pressure from Proposition 65 disclosure mandates, creating compliance cost stacking for transatlantic suppliers.
Fleet procurement centralization is consolidating purchasing authority among national car wash chains and rental service operators. Specialty retail channel intermediaries are losing volume to direct vendor relationships. This pattern concentrates most visibly in Sun Belt states where vehicle density supports dedicated logistics contracts.
Car Duster Market Segmentation
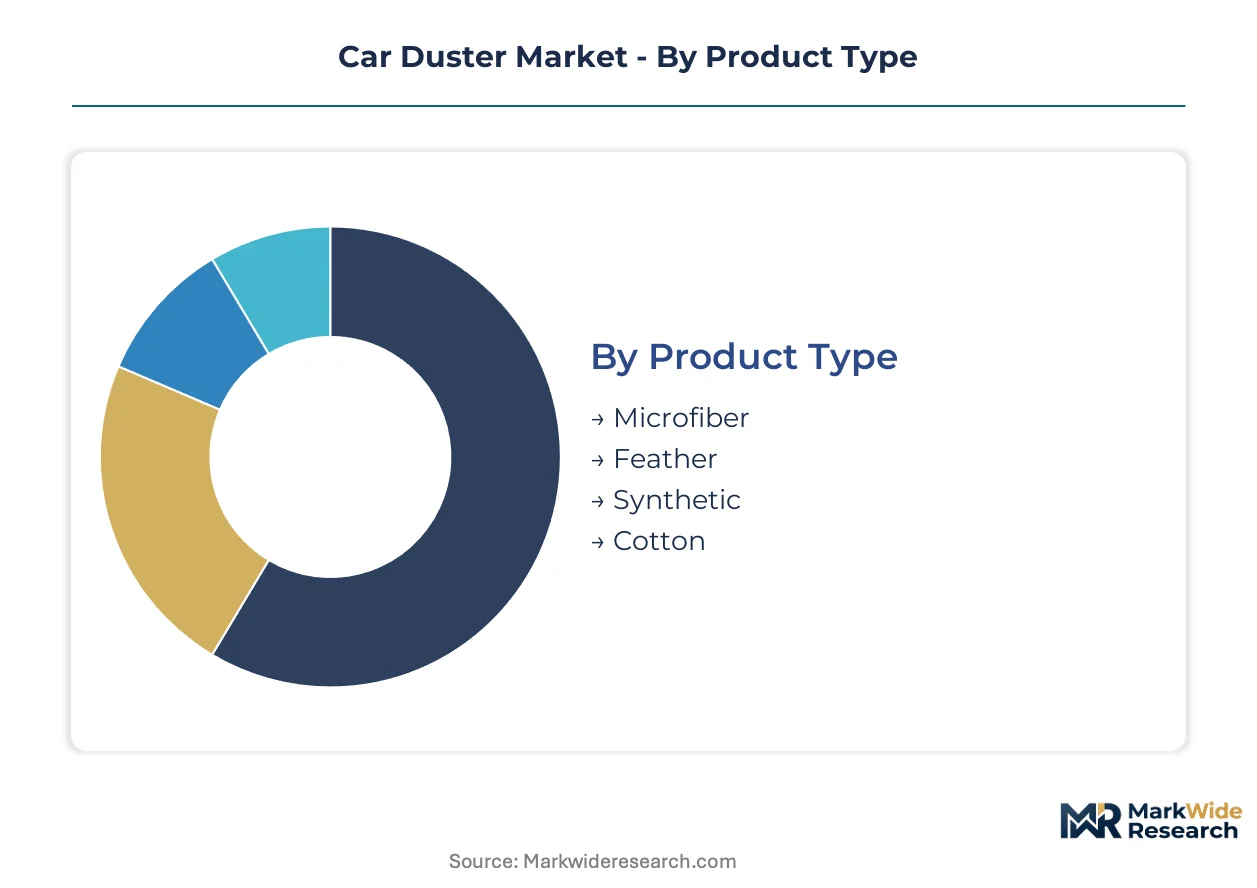
Segmentation in the car duster market reveals how fiber technology, procurement channels, and regulatory exposure create divergent margin profiles. Understanding these divisions exposes where volume concentrates versus where value accumulates.
Product Type:
Microfiber and synthetic variants dominate export flows to REACH-regulated European markets, while untreated cotton serves domestic Sun Belt demand with minimal compliance overhead.
- Microfiber:Split-fiber architecture with electrostatic charge retention traps particles below 10 microns without surface abrasion. Demand clusters in professional car wash chains across Texas and Florida where fleet standardization mandates reusable, high-cycle durability. REACH dye restrictions and California Proposition 65 disclosure rules favor this segment's synthetic chemistry transparency.
- Cotton:Untreated natural fibers bypass paraffin-based treatment regulations entirely. Arizona and California retail channels favor this formulation for consumer segments seeking chemical-free vehicle contact surfaces. Margin compression from commodity futures volatility constrains specialist manufacturers.
- Feather:Ostrich and synthetic feather alternatives face structural demand collapse amid animal welfare sourcing scrutiny.
- Synthetic:Polypropylene and polyester blends offer cost positioning for economy-tier procurement in rental fleet programs.
Microfiber holds the largest share; momentum sits with untreated cotton as regulatory disclosure requirements tighten.
Application:
Automotive and aerospace applications command premium pricing through validated performance specifications, while home and industrial segments compete on unit cost.
- Automotive:Clear-coat safe fiber engineering with ISO 9001-certified manufacturing protocols serves OEM dealership networks and enthusiast detailing segments. Sun Belt states with high vehicle density sustain replacement cycles.
- Aerospace:Anti-static fiber formulations meeting FAA-adjacent material flammability standards capture specialized MRO procurement.
- Home:Multi-surface dusting tools with automotive-grade fiber quality differentiate premium positioning from commodity household alternatives.
- Industrial:Heavy-duty fiber density for manufacturing facility maintenance competes on durability metrics rather than cosmetic finish preservation.
Automotive dominates absolute volume; aerospace climbs fastest on specification-driven procurement.
End User:
Procurement centralization separates consolidated fleet operators from fragmented consumer purchasing patterns.
- Car Washes:National chain standardization programs specify microfiber weave densities and handle ergonomics across hundreds of locations. Volume contracts bypass specialty retail margin stacking.
- Rental Services:Enterprise Holdings and Avis Budget Group centralized purchasing creates vendor consolidation windows with multi-year supply agreements.
- Consumers:Amazon direct-to-consumer channel growth displaces supermarket and auto parts retail intermediaries.
- Dealerships:OEM-affiliated service departments bundle duster procurement with detailing chemical programs.
Car washes command the largest procurement volume; rental services expand most quickly through fleet maintenance standardization.
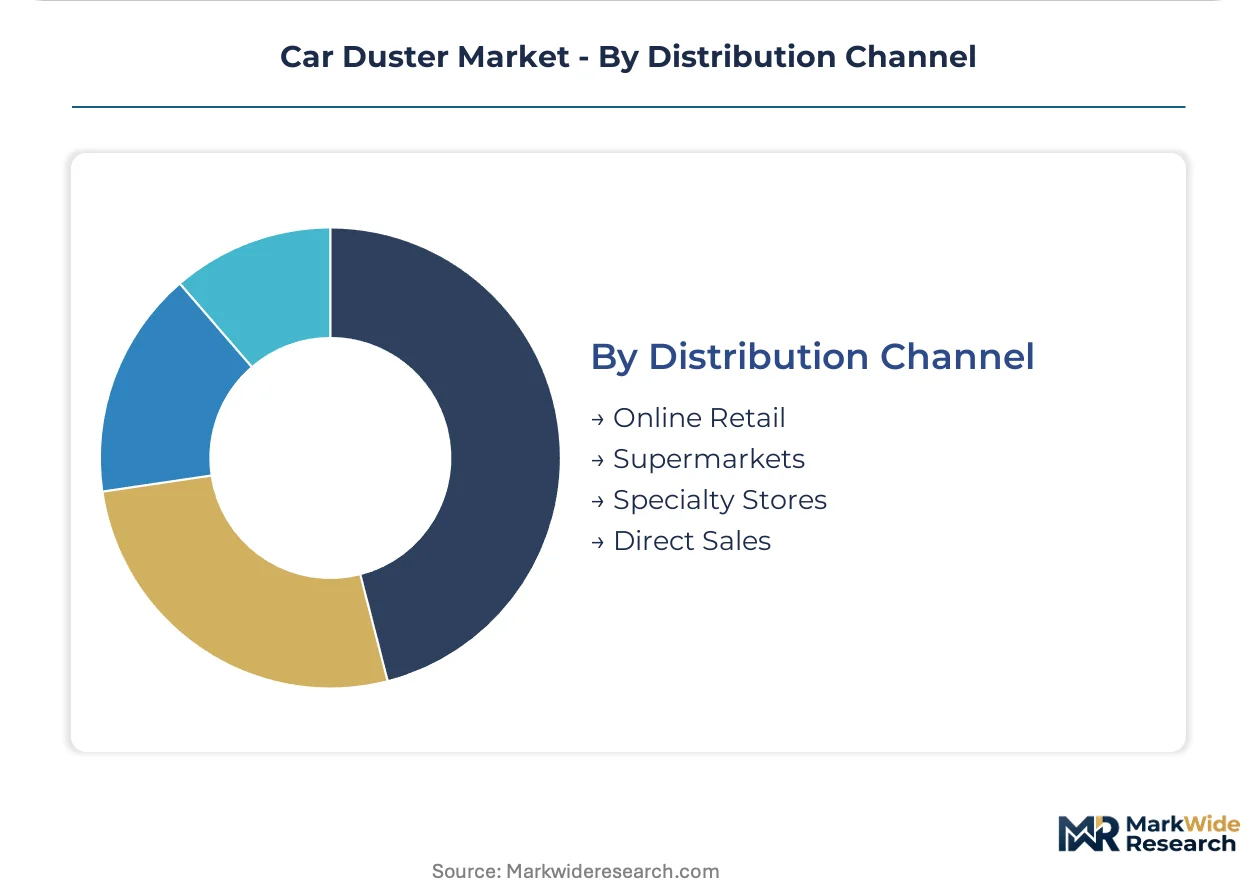
Distribution Channel:
Channel compression favors direct relationships with institutional buyers over retail intermediation.
- Online Retail:Amazon private label entry and direct-to-consumer brand storefronts aggregate fragmented consumer demand with logistics efficiency.
- Direct Sales:Vendor relationships with national car wash chains and rental fleet operators eliminate distributor margins.
- Specialty Stores:West Coast auto detailing retailers maintain curated selection for enthusiast segments seeking validated performance claims.
- Supermarkets:Mass-market cotton duster placement competes on impulse purchase pricing with minimal brand differentiation.
Online retail captures the largest consumer volume; direct sales gain share fastest through B2B procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Proposition 65 chemical disclosure mandates are reshaping procurement patterns across multiple jurisdictions. National regulators are tightening fiber traceability requirements. Vehicle ownership density and dust exposure severity determine regional demand concentration.
United States
Sun Belt states sustain replacement demand through high vehicle density and frequent dust exposure. EPA volatile organic compound rules govern treated fiber formulations under consumer product regulations. Dallas-Fort Worth metro anchors fleet procurement standardization for national car wash chains.
Germany
REACH Annex XVII dye restrictions force segregated formulation inventories for transatlantic suppliers. ECHA-registered fiber traceability certification commands premium positioning in European markets. Stuttgart industrial corridor concentrates automotive aftermarket distribution infrastructure.
China
Domestic vehicle fleet expansion drives microfiber weave technology investment. SAMR consumer product safety standards govern synthetic fiber chemical content disclosure. Yangtze River Delta manufacturing clusters supply cost-optimized synthetic blends for export markets.
Japan
Enthusiast detailing segments validate premium reusable system performance claims. METI industrial standards influence regional fiber quality specifications. Osaka-Kobe corridor maintains specialty retail channel relationships for curated auto care selection.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance pathways for fiber treatment formulations. FCA consumer protection frameworks extend to automotive accessory marketing claims. Midlands distribution hubs serve European re-export demand through established logistics contracts.
Car Duster Market Competitive Environment
Player mix skews toward specialty automotive care brands with established retail channel relationships. Market structure concentrates around three to four dominant manufacturers with ISO 9001-certified production protocols. Strategic archetypes include West Coast manufacturing specialists, Midwest chemical R&D integrators, and mass-market brand licensors. Competitive moves center on direct procurement relationship cultivation with national fleet operators and specialty retail channel curation for enthusiast segments.
Within the specialty manufacturing tier, California Car Duster exemplifies geographic proximity advantages for regulatory responsiveness, while Mothers Polish and Meguiar's anchor premium positioning through enthusiast segment brand equity. These three represent distinct competitive vectors: regional manufacturing control, chemical formulation expertise, and validated performance marketing respectively. Each occupies a defensible position against mass-market private label encroachment through differentiated fiber technology claims and retail channel access depth.
| Leading Market Players |
|---|
| California Car Duster |
| Mothers Polish |
| Libman Company |
| Prolux |
| Meguiar's |
| Turtle Wax |
| Armor All |
| Carrand |
| AutoBra |
| Others |
Value Chain & Pricing Dynamics
ISO 9001 certification gates both supplier qualification and price tier placement simultaneously, compressing sub-scale manufacturers into commodity cotton segments while rewarding certified microfiber specialists with fleet contract premiums. California Proposition 65 compliance costs stack onto REACH dye restrictions for transatlantic exporters, forcing dual-formulation inventory carrying costs that transmit directly into landed pricing spreads.
Pricing Analysis
Certification level creates the primary spread between premium microfiber and economy cotton tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 audit status, fiber weave density, and handle ergonomics. Cost compression in untreated cotton runs through commodity futures volatility and paraffin treatment reformulation expenses. Rental fleet operators exhibit highest price sensitivity due to volume procurement centralization, while enthusiast detailing segments absorb premiums for validated performance claims.
Supply Chain Analysis
China and Vietnam anchor synthetic fiber and handle component manufacturing for cost-optimized production. Raw material flows draw from Yangtze River Delta polymer facilities, Texas cotton belt harvests, and Stuttgart industrial corridor precision molding. Single-source vulnerability concentrates in electrostatic microfiber weave engineering talent pools. Distribution runs through Amazon fulfillment centers for consumer segments and dedicated logistics contracts for national car wash chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car duster market tracks cyclical recovery patterns tied to vehicle ownership replacement cycles, with Sun Belt dust exposure severity and fleet standardization programs now converging to lift procurement volumes from trough levels.
For Market Incumbents: Consolidate procurement relationships with Enterprise Holdings and Avis Budget Group through multi-year supply agreements before Amazon private label encroachment intensifies. Deepen backward integration into Yangtze River Delta fiber manufacturing to offset commodity cotton margin compression. Prioritize REACH-compliant microfiber R&D to defend European export positioning against certification-stacked compliance costs. For New Entrants and Emerging Players: Differentiate on untreated cotton formulations targeting California retail channels seeking Proposition 65 disclosure avoidance. White-space sits with blockchain-enabled fiber traceability for EU Green Deal premium positioning. Penetrate through direct-to-consumer Amazon storefronts bypassing specialty retail margin stacking, with initial focus on Arizona and Texas consumer segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across certified microfiber manufacturing as polymer science automation spreads. Long-term viability favors ISO 9001-certified specialists with established fleet procurement relationships over commodity cotton assemblers. Target acquisition archetype: West Coast manufacturers with California Proposition 65 compliance infrastructure and existing national car wash chain contracts. Watch for inflection in ECHA-registered fiber traceability mandate enforcement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Microfiber R&D Investment | ECHA-registered fiber traceability certification commands premium positioning in European procurement channels. |
| Direct Fleet Procurement Relationship | National car wash chain volume contracts bypass specialty retail margin stacking entirely. |
| Untreated Cotton Formulation Pivot | Proposition 65 disclosure avoidance creates California retail channel differentiation. |
| Blockchain Supply Chain Verification | EU Green Deal fiber traceability mandates enable premium pricing in German aftermarket distribution. |
| Amazon Private Label Defense | Direct-to-consumer brand storefronts aggregate fragmented demand with logistics efficiency. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA consumer product filings, ECHA REACH registration databases, and cotton futures exchange data. Conversations with car wash chain procurement directors, auto detailing supply distributors, microfiber weave engineers, and specialty retail category managers informed demand segmentation. Bottom-up volume builds triangulate against top-down value estimates from customs trade flows and fleet operator maintenance spend disclosures.
Segmentation dimensions modeled include fiber technology type, end-user procurement channel, application surface specification, and regional regulatory compliance cluster across the analysis window. CAGRs derive from regression analysis against vehicle ownership density, dust exposure indices, and fleet standardization penetration curves. Industry-specific forecast inputs incorporate Sun Belt replacement cycle timing and REACH Annex XVII dye restriction implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained Sun Belt vehicle density growth or accelerated Proposition 65 enforcement would require recalibration. Forecasts reflect assumptions around fiber substitution elasticity and fleet procurement centralization velocity. Recalibration cycles align with material shifts in EPA volatile organic compound rulemaking and EU Green Deal traceability mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market