
 Engine Module-Level Repair and Refurbishment Services Market | 2026-2036
Engine Module-Level Repair and Refurbishment Services Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Module-Level Repair and Refurbishment Services Market Insights
India is rewriting the competitive map for engine module repair as new MRO facilities near Hyderabad and Bangalore add turbine overhaul capacity. GE Aerospace leverages its global network of licensed repair stations to control high-value hot-section module work. Pratt & Whitney anchors its aftermarket position through proprietary diagnostics that lock fleet operators into recurring refurbishment cycles. Rolls-Royce sustains premium pricing by dominating large turbofan module programs with captive material sciences expertise.
Engine module-level repair and refurbishment services encompass the disassembly, inspection, reconditioning, and reassembly of discrete engine subsystems—compressor, combustor, turbine, and accessory modules—rather than whole-engine replacement, with processes governed by OEM-approved technical specifications for dimensional restoration, coating reapplication, and blade-tip clearance tolerances measured in thousandths of an inch. These services extend time-on-wing for powerplants across aviation, marine, and heavy industrial applications while preserving original design performance envelopes. Overhaul and component repair command the largest share of service revenue due to recurring airworthiness mandates and predictable maintenance intervals, while remote diagnostics and predictive refurbishment represent the fastest-expanding delivery model as connected sensor networks reduce unscheduled removals and optimize shop visit timing.
FAA airworthiness directives and EASA continuing airworthiness regulations shape module repair demand by mandating specific inspection intervals and life-limited part replacements that drive predictable shop visit volumes. EPA emissions standards for commercial marine and rail engines extend refurbishment requirements beyond aviation into heavy propulsion sectors. Stakeholders must monitor evolving OEM intellectual property restrictions on additive repair processes and powder metallurgy techniques that could reshape which service providers retain market access.
Market Dynamics
Fleet operators are compressing engine shop visit intervals as FAA and EASA airworthiness directives mandate tighter dimensional tolerances for hot-section modules, forcing repair stations to recalibrate capacity planning around regulatory clockspeed rather than traditional flight-hour cycles.
Growth Catalysts
- Aviation emissions compliance:EPA standards for commercial propulsion systems compel operators to refurbish existing powerplants rather than replace them, extending module-level repair demand across narrowbody and widebody fleets.
- India:New MRO facilities near Hyderabad and Bangalore are adding turbine overhaul capacity, drawing regional lessors away from legacy Singapore and Dubai service hubs.
- Additive repair techniques:Powder metallurgy and directed energy deposition processes enable dimensional restoration of life-limited parts previously condemned to scrap, expanding addressable repair volumes.
Market Restraints
- OEM intellectual property barriers:Proprietary technical specifications for hot-section coatings and blade-tip tolerances restrict independent repair station access to high-value module work.
- Superalloy supply concentration:Vacuum-melted nickel-based alloys for turbine blade restoration concentrate among a limited supplier base, exposing repair stations to input cost volatility.
- Life-limited part substitution:New-engine programs with extended on-wing intervals reduce shop visit frequency for mature powerplants, compressing refurbishment addressable market.
Strategic Opportunities
- Marine propulsion extension:EPA emissions standards for commercial shipping engines extend module repair requirements beyond aviation into heavy marine sectors with less consolidated supplier bases.
- Predictive refurbishment models:Connected sensor networks on next-generation powerplants enable condition-based module replacement, creating recurring revenue streams for diagnostics-integrated service providers.
- Industrial gas turbine aftermarket:Power generation operators facing FERC grid reliability mandates represent an underpenetrated vertical for aviation-derived repair techniques.
Industry Challenges
- Specialized welder scarcity:Precision joining of single-crystal superalloys requires technicians with rare combinations of metallurgical certification and aero-engine specific experience.
- Part 145 certification timelines:FAA repair station approvals for new module capabilities stretch 18-24 months, delaying market entry for emerging techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Module-Level Repair and Refurbishment Services Market |
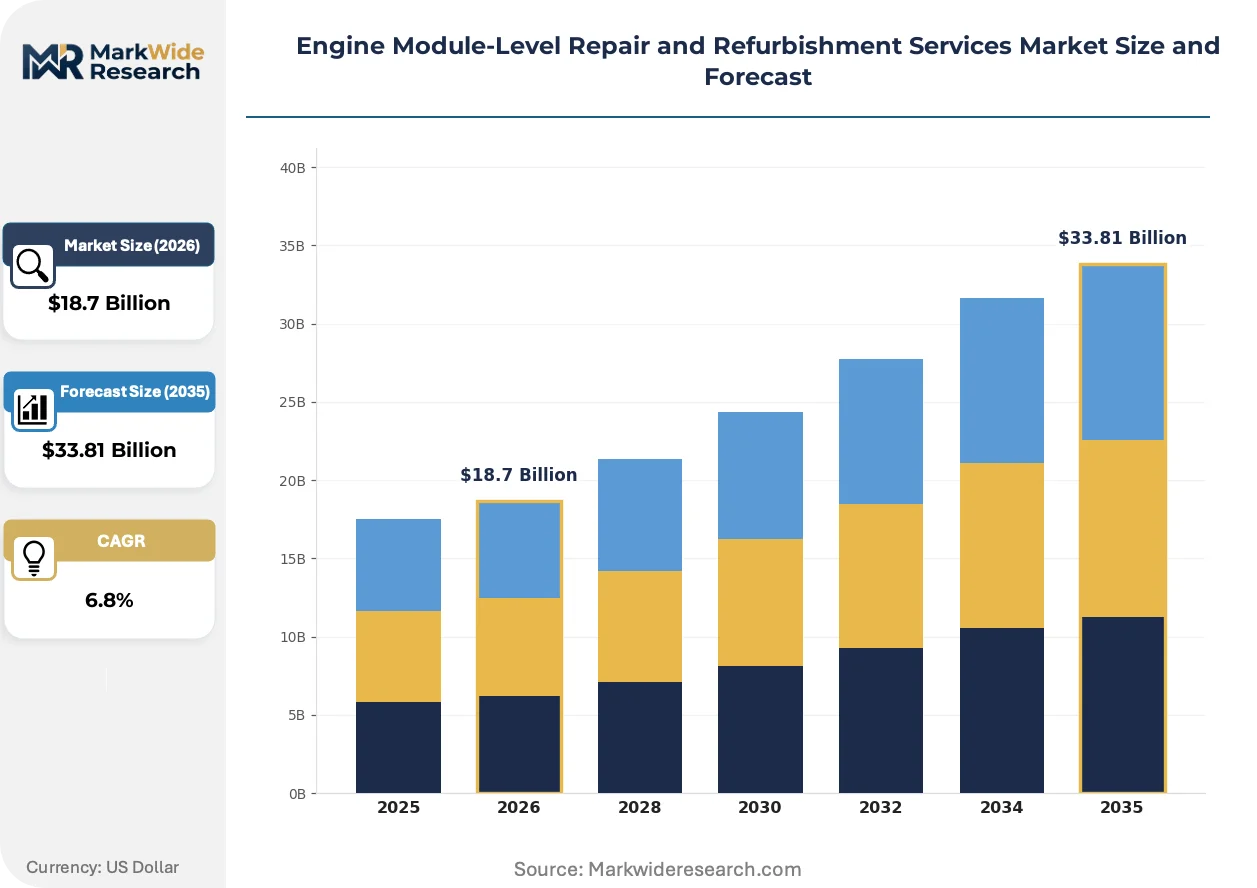
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overhaul, Diagnostics, Component Repair, Refurbishment, Testing, Calibration Application: Commercial Vehicles, Aerospace Equipment, Marine Engines, Heavy Machinery, Agricultural Machinery, Rail Transport End User: Fleet Operators, Maintenance Workshops, OEM Service Centers, Leasing Companies, Government Agencies, Defense Contractors Delivery Model: On-site Service, Off-site Repair, Mobile Workshops, Remote Diagnostics, Contractual Agreements, Emergency Support |
| Companies Covered | GE Aerospace, Pratt & Whitney, Rolls-Royce Holdings, Safran Aircraft Engines, MTU Aero Engines, Lufthansa Technik, StandardAero, Delta TechOps, ST Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Module-Level Repair and Refurbishment Services Market Trends and Innovations
Repair methodology is migrating from fixed-interval overhaul toward condition-responsive intervention, compressing the traditional planning horizon for module shop visits and demanding real-time data integration between operators and service providers.
Cold spray deposition is migrating from experimental blade restoration toward production-scale dimensional repair. Regional carriers with aging CFM56 and V2500 fleets are adopting the technique fastest to avoid new-part procurement delays. The technology is migrating from niche applications toward mainstream combustor and turbine vane repair, compressing turnaround times for high-value module work.
EASA continuing airworthiness regulations now mandate traceable coating reapplication protocols for high-pressure turbine modules. This industrial consequence forces repair stations to invest in automated thermal spray cells with closed-loop process control. Narrowbody operators in Europe are responding by consolidating module work with EASA Part 145 stations holding OEM-licensed coating approvals.
Power-by-the-hour contracts are unbundling module-level repair from bundled aftermarket agreements. Lessors and fleet operators now separately negotiate hot-section work, compressor overhauls, and accessory module refurbishment. This behavior shift is most visible among US-based lessors with diversified powerplant portfolios seeking granular cost visibility.
Engine Module-Level Repair and Refurbishment Services Market Segmentation
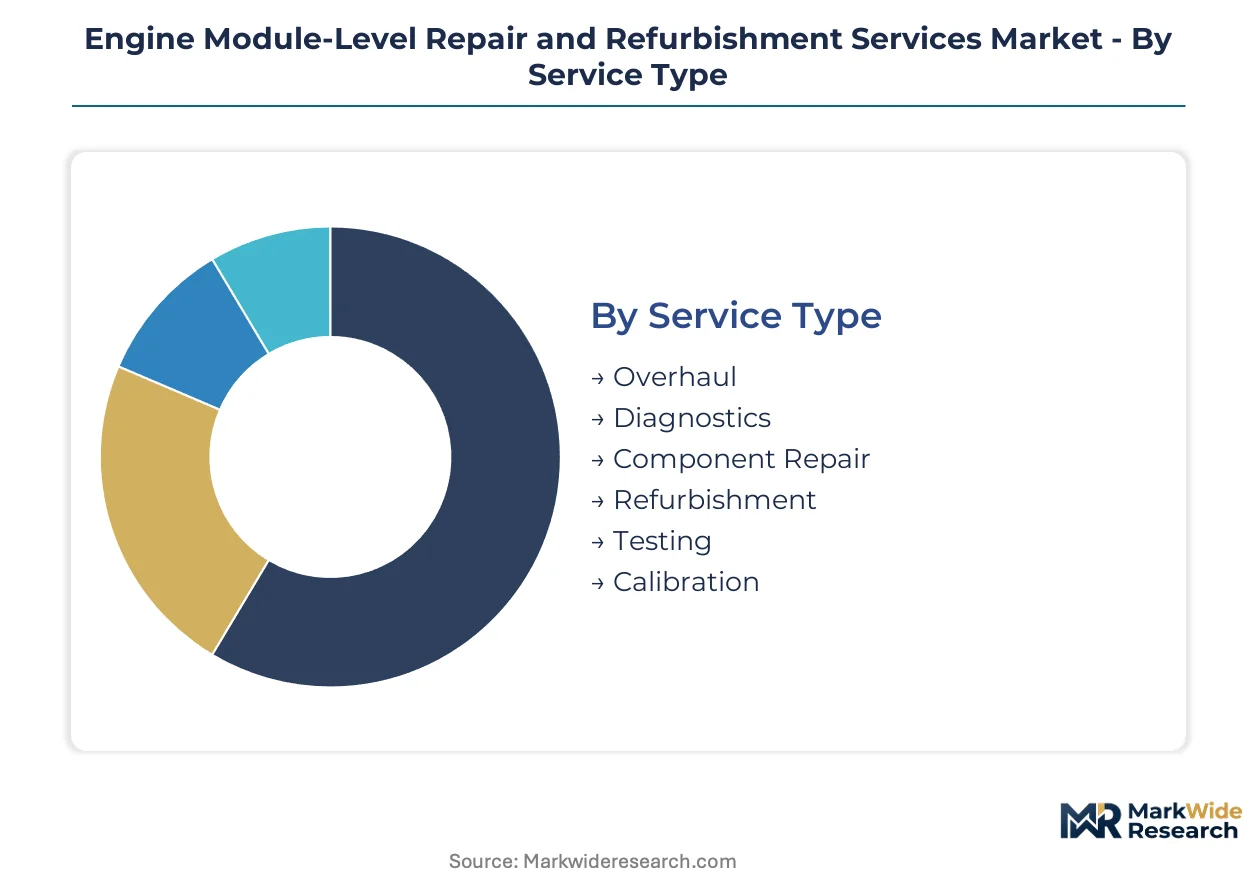
Module-level repair services fragment across service intensity, equipment application, and procurement relationships. Each dimension shapes margin structure, certification requirements, and customer retention mechanics differently.
Service Type:
Cost tier determines capital intensity and technician specialization requirements for each service category.
- Overhaul:Complete disassembly, dimensional restoration, and reassembly of compressor, combustor, and turbine modules to OEM-approved specifications. Demand concentrates among US-based lessors with aging narrowbody fleets facing FAA airworthiness directive compliance deadlines.
- Component Repair:Targeted restoration of individual life-limited parts including blade recontouring, coating reapplication, and seal replacement. European operators under EASA continuing airworthiness regulations drive volume for high-pressure turbine module work.
- Diagnostics:Non-destructive inspection and condition assessment using borescope, eddy current, and ultrasonic techniques.
- Refurbishment:Cosmetic and functional renewal of accessory modules and external surfaces without full dimensional restoration.
- Testing:Post-repair validation of airflow, vibration, and thermal performance against OEM acceptance criteria.
- Calibration:Precision adjustment of fuel metering, clearance control, and sensor alignment systems.
Overhaul commands the established base. The steepest expansion runs through diagnostics as connected sensor networks enable predictive intervention.
Application:
Equipment category dictates thermal cycle severity, regulatory jurisdiction, and turnaround time pressure.
- Aerospace Equipment:Turbofan and turboprop powerplants for commercial and cargo aircraft requiring FAA and EASA dual certification. Indian MRO facilities near Hyderabad are capturing regional lessor demand previously routed through Singapore.
- Commercial Vehicles:Heavy-duty diesel and natural gas engines for trucking and bus fleets. EPA emissions standards for commercial propulsion systems extend refurbishment demand as operators avoid new powerplant capital expenditure.
- Marine Engines:Commercial shipping and offshore platform powerplants subject to EPA marine emissions regulations.
- Heavy Machinery:Mining and construction equipment engines with extended overhaul intervals and severe operating environments.
- Agricultural Machinery:Seasonal-use engines with intermittent maintenance patterns and price-sensitive owner-operators.
- Rail Transport:Locomotive powerplants under FERC grid reliability mandates for freight and passenger operators.
Aerospace equipment anchors revenue concentration. Commercial vehicles are gaining share fastest as emissions compliance tightens replacement economics.
End User:
Customer type shapes contract structure, pricing power, and technical specification access.
- Fleet Operators:Airlines, shipping lines, and trucking companies with captive maintenance planning and power-by-the-hour contract experience. US-based carriers in Georgia, Texas, and Arizona MRO corridors concentrate demand for integrated module programs.
- OEM Service Centers:Factory-authorized facilities with proprietary technical specifications and licensed coating processes. These operators control high-value hot-section work through intellectual property restrictions on additive repair techniques.
- Maintenance Workshops:Independent repair stations with Part 145 certification competing on turnaround time and labor rates.
- Leasing Companies:Asset owners negotiating granular module-level contracts separate from bundled aftermarket agreements.
- Government Agencies:Military and civilian fleet operators with mission-critical uptime requirements and specialized procurement protocols.
- Defense Contractors:Prime contractors managing depot-level maintenance for military propulsion systems.
Fleet operators represent the core revenue base. Leasing companies are restructuring procurement fastest through unbundled module negotiations.
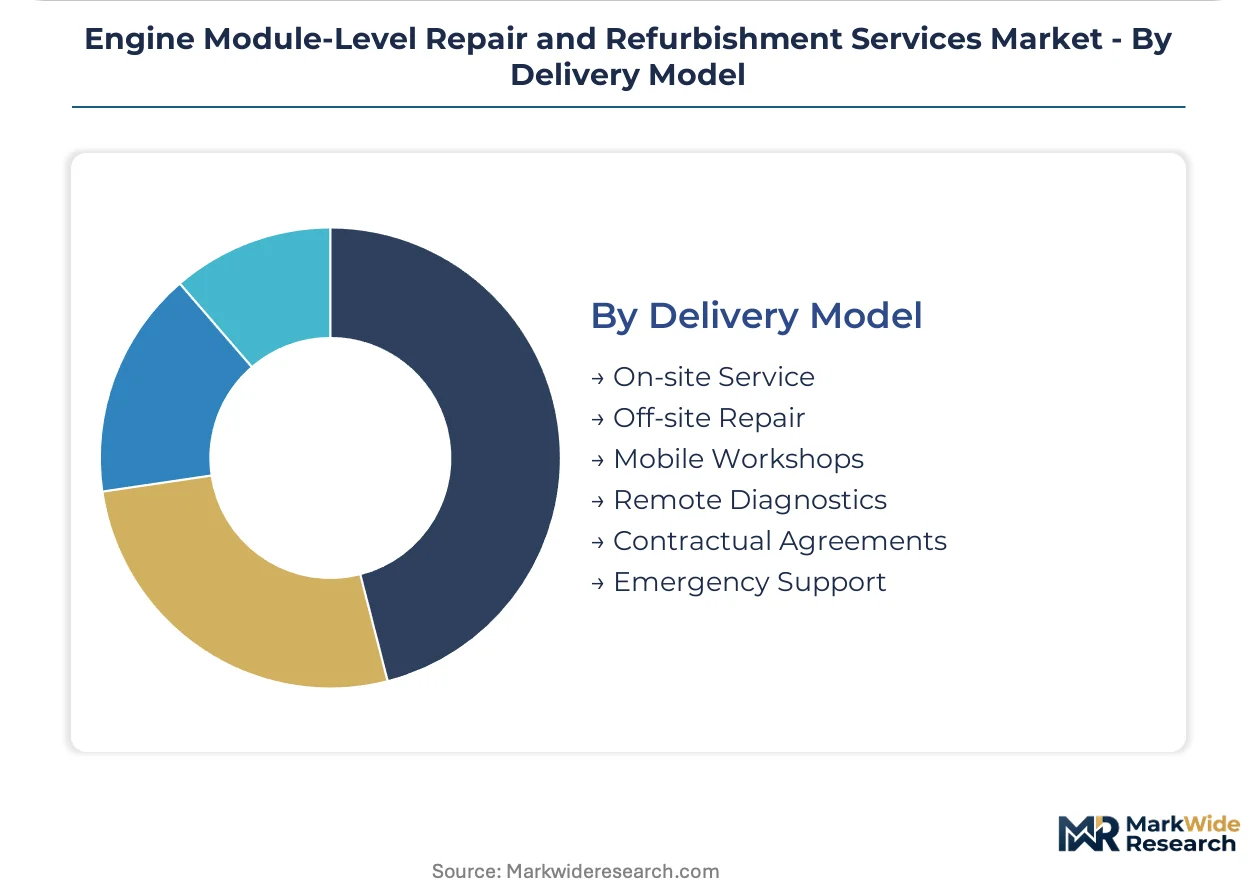
Delivery Model:
Geographic proximity to equipment and urgency of need define service configuration.
- Off-site Repair:Centralized facility-based processing with automated thermal spray cells and closed-loop process control. EASA Part 145 stations with OEM-licensed coating approvals in Europe are consolidating narrowbody operator demand.
- Remote Diagnostics:Sensor-enabled condition monitoring with predictive algorithms optimizing shop visit timing. Cold spray deposition for blade restoration is migrating fastest through this channel for aging CFM56 and V2500 fleets.
- On-site Service:Field deployment for urgent module replacement without aircraft or vessel removal.
- Mobile Workshops:Containerized repair capacity for remote mining and agricultural operations.
- Contractual Agreements:Multi-year fixed-price or cost-plus arrangements with volume commitments.
- Emergency Support:Premium-priced rapid response for unscheduled removals and airworthiness directive compliance deadlines.
Off-site repair dominates volume economics. Remote diagnostics is expanding most quickly as connected powerplant penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed repair stations cluster near major aviation hubs where FAA and EASA dual certification creates regulatory arbitrage. MRO capacity expansion in India and Southeast Asia is redirecting regional lessor traffic from legacy Singapore and Dubai service centers.
United States
Major carriers and international lessors drive module overhaul demand through Georgia, Texas, and Arizona MRO corridors. FAA airworthiness directives on emissions and noise compliance tighten overhaul standards and accelerate refurbishment cycles. Dallas-Fort Worth and Atlanta service hubs process narrowbody fleet work for US-based lessors with diversified powerplant portfolios.
Germany
EASA continuing airworthiness regulations mandate traceable coating reapplication protocols for high-pressure turbine modules. The country's national aviation regulator enforces strict Part 145 certification timelines that delay market entry for emerging repair techniques. Hamburg and Munich industrial clusters host OEM-authorized facilities with proprietary thermal spray cells and closed-loop process control.
India
New MRO facilities near Hyderabad and Bangalore add turbine overhaul capacity, drawing regional lessors away from legacy Singapore and Dubai service hubs. The country's national aviation regulator aligns with EASA standards to attract foreign carrier business. Telangana and Karnataka state governments offer incentives for aerospace manufacturing zones targeting module-level repair specialization.
Singapore
Seletar Aerospace Park and Changi North industrial estates host concentrated OEM service center operations for Asia-Pacific fleet operators. The country's civil aviation authority maintains bilateral agreements with FAA and EASA that streamline dual certification for repair stations. Cold spray deposition techniques for aging CFM56 and V2500 fleets migrate fastest through Singapore-based technical partnerships.
United Arab Emirates
Dubai South and Al Ain aviation districts position module repair capacity at the intersection of European and Asian air traffic flows. The country's civil aviation regulator adopts EASA-aligned standards to attract third-party MRO investment. Emirates Engineering and third-party providers compete for widebody module work from Gulf carrier fleets and transit traffic.
Engine Module-Level Repair and Refurbishment Services Market Competitive Landscape
OEM-authorized service centers and independent repair stations split the market along intellectual property access lines. Factory-licensed facilities control high-value hot-section module work through proprietary technical specifications. Independent stations compete on turnaround time and labor rates for compressor and accessory module refurbishment. Capacity expansion and technology licensing represent the dominant competitive moves as repair stations invest in automated thermal spray cells and additive repair capabilities.
Within the OEM-authorized tier, GE Aerospace, Pratt & Whitney, and Rolls-Royce Holdings exemplify archetypes that dominate large turbofan module programs through captive material sciences expertise. GE Aerospace leverages its global network of licensed repair stations to control high-value hot-section module work. Pratt & Whitney anchors its aftermarket position through proprietary diagnostics that lock fleet operators into recurring refurbishment cycles. Rolls-Royce sustains premium pricing by dominating large turbofan module programs with specialized metallurgical capabilities.
| Leading Market Players |
|---|
| GE Aerospace |
| Pratt & Whitney |
| Rolls-Royce Holdings |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Lufthansa Technik |
| StandardAero |
| Delta TechOps |
| ST Engineering |
| Others |
Pricing and Supply Chain Analysis
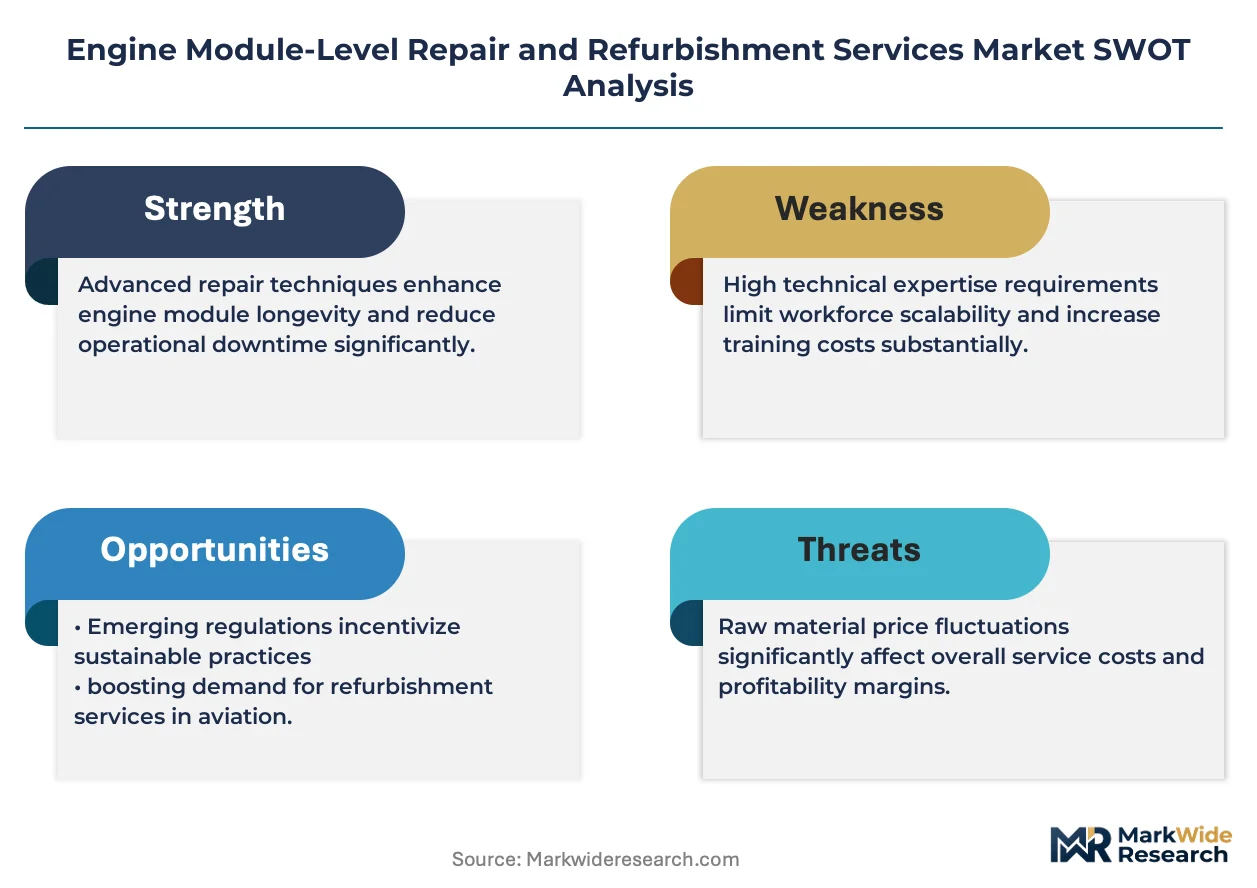
Vacuum-melted nickel-based superalloy suppliers in the United States and Germany concentrate upstream input control, funneling margin capture toward repair stations with captive metallurgical capabilities and OEM-licensed coating approvals. This concentration shapes downstream pricing power by tethering high-value hot-section module work to facilities with proprietary thermal spray cells and closed-loop process control.
Pricing Analysis
FAA Part 145 certification requirements and EASA continuing airworthiness regulations dictate the pricing tier structure across the module repair market. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized facilities with proprietary technical specifications from independent stations competing on labor rates and turnaround time. Price differentiation hinges on certification grade and volume scale, with narrowbody fleet operators showing highest price sensitivity due to compressed maintenance budgets. Cost compression in standard-tier compressor module work is intensifying because independent repair stations are adding automated inspection capacity.
Supply Chain Analysis
Specialized contract manufacturers in the United States, Germany, and Singapore hold concentrated capacity for precision turbine blade restoration and automated thermal spray deposition. The supply chain draws from vacuum-melted nickel-based superalloys, ceramic thermal barrier coatings, and single-crystal casting feedstock. Single-source vulnerability concentrates around limited superalloy suppliers, exposing repair stations to input cost volatility. Distribution runs through centralized Part 145 facilities with dual FAA-EASA certification serving regional lessor and fleet operator demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engine module-level repair incumbents face substitution pressure from additive manufacturing techniques that enable dimensional restoration of life-limited parts previously condemned to scrap, threatening traditional overhaul revenue pools.
For Market Incumbents: Pre-empt additive repair disruption by licensing powder metallurgy and directed energy deposition capabilities before independent stations secure Part 145 approvals for these techniques. Lock in regional lessor relationships through predictive refurbishment contracts that integrate remote diagnostics, creating switching costs that resist unbundling pressure from leasing companies seeking granular module-level negotiations.
For New Entrants and Emerging Players: Marine propulsion modules under EPA emissions standards represent the most penetrable entry point, with less consolidated supplier bases and lower OEM intellectual property barriers than aviation hot-section work. Target industrial gas turbine operators facing FERC grid reliability mandates with aviation-derived repair techniques adapted for power generation applications, using condition-based maintenance contracts as the go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent repair station networks lacking additive manufacturing capabilities but holding established Part 145 certifications in Georgia, Texas, and Arizona MRO corridors. Long-term viability depends on technology licensing access and regulatory approval velocity rather than scale alone. Watch FAA certification timelines for cold spray deposition and directed energy deposition as the signal indicating which service providers will retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Licensing | OEM licensing agreements for powder metallurgy techniques determine independent repair station access to high-value hot-section module work. |
| Dual Certification Expansion | FAA-EASA Part 145 dual certification in India and Southeast Asia redirects regional lessor traffic from legacy Singapore and Dubai hubs. |
| Predictive Refurbishment Contracts | Connected sensor networks on next-generation powerplants enable condition-based module replacement with recurring diagnostics revenue. |
| Marine Sector Diversification | EPA marine emissions standards extend module repair requirements beyond aviation into commercial shipping with less OEM IP concentration. |
| Automated Thermal Spray Investment | EASA-mandated traceable coating reapplication protocols force repair stations to deploy closed-loop process control cells. |
Research Methodology
A standing panel of MRO operations directors, fleet maintenance planners, Part 145 certification specialists, and OEM aftermarket executives provided ongoing calibration across primary fieldwork and secondary validation. This study triangulated bottom-up repair station capacity surveys with top-down lessor fleet data, drawing from FAA airworthiness directive filings, EASA continuing airworthiness regulations, EPA emissions compliance databases, and customs records for superalloy trade flows.
Scenario bracketing anchored the analytical framework across the projection horizon, modeling volume and value outputs through service type, application equipment, end user category, and delivery model dimensions. CAGRs were derived from repair station visit frequency projections tied to airworthiness mandate timelines and fleet age distributions. Forecast inputs incorporated connected sensor penetration rates on next-generation powerplants and additive repair technique adoption curves.
Practitioners should monitor FAA certification timeline extensions for emerging repair techniques and superalloy supply disruptions for early signals of forecast revision. Forecasts reflect documented assumptions around regulatory clockspeed and OEM intellectual property licensing trajectories. Quarterly review of Part 145 approval backlogs and additive manufacturing patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market