
 MUV Rental Market | 2026-2036
MUV Rental Market Size, Share, and Industry Trends Forecast 2026-2036
MUV Rental Market Analysis
The gap between premium experience tiers and commodity self-service rentals is expanding across the MUV rental landscape. Enterprise Holdings sustains its fleet scale advantage through centralized procurement and airport dominance. Localiza Rent a Car anchors Latin American operations with dense urban coverage in Brazil. Turo differentiates through peer-to-peer inventory access, bypassing traditional depot infrastructure.
Multi-utility vehicle rental denotes the short-to-medium term leasing of sport utility vehicles, minivans, pickup trucks, and crossovers to consumer and commercial end-users, typically featuring seating capacity above five passengers and cargo volume exceeding 500 liters. These vehicles serve family mobility, contractor logistics, and corporate ground transportation where load flexibility outweighs sedan efficiency. Short-term rental duration captures the highest transaction frequency, while subscription service models concentrate emerging margin pools as consumers seek alternatives to ownership. Corporate clients represent the most structurally stable demand segment, with event planners generating acute seasonal spikes.
The EPA tailpipe standards and NHTSA Corporate Average Fuel Economy rules compel fleet operators to integrate hybrid and electric multi-utility vehicles, elevating capital requirements and reshaping supplier negotiations. State-level zero-emission vehicle mandates in California and New York further fragment compliance obligations for national operators. Stakeholders must monitor battery supply constraints and charging infrastructure gaps as electrified fleet transitions accelerate capital intensity and reshape regional competitive positioning.
Market Dynamics
Fleet electrification mandates from NHTSA and EPA are compressing depreciation schedules and forcing capital reallocation toward hybrid and battery-electric multi-utility vehicles.
Growth Catalysts
- EPA Tailpipe Standards:Fleet operators must replace internal combustion engine vehicles with electrified alternatives, accelerating turnover cycles and rental demand during transition periods.
- Corporate Mobility Restructuring:Enterprises are eliminating owned fleets in favor of flexible access models, creating structurally stable commercial contracts for MUV providers.
- Urban Sprawl Patterns:Metropolitan expansion in car-dependent regions sustains household reliance on temporary vehicle access where public transit remains underdeveloped.
Market Restraints
- Battery Supply Concentration:Cathode material processing and cell manufacturing cluster in East Asian supply chains, exposing fleet operators to geopolitical disruption and input cost volatility.
- Charging Infrastructure Gaps:Depots in secondary markets lack DC fast-charging capacity, constraining electric MUV deployment outside major metropolitan corridors.
- Residual Value Uncertainty:Rapid technology obsolescence in electrified powertrains complicates fleet financing and remarketing strategies for lessors.
Strategic Opportunities
- Subscription Service Models:Consumers seeking alternatives to vehicle ownership create recurring revenue streams with higher lifetime value than transactional rentals.
- State-Level ZEV Mandates:California and New York zero-emission vehicle requirements generate guaranteed demand pull for electric MUV fleet investment.
- Telematics-Enabled Pricing:Real-time usage data allows dynamic rate adjustment based on actual vehicle utilization and driver behavior patterns.
Industry Challenges
- Technician Skill Shortages:High-voltage system certification requirements outpace vocational training program output, delaying maintenance turnaround times.
- Legacy Reservation System Integration:Electrified fleet management platforms must interface with outdated enterprise software, creating data synchronization failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MUV Rental Market |
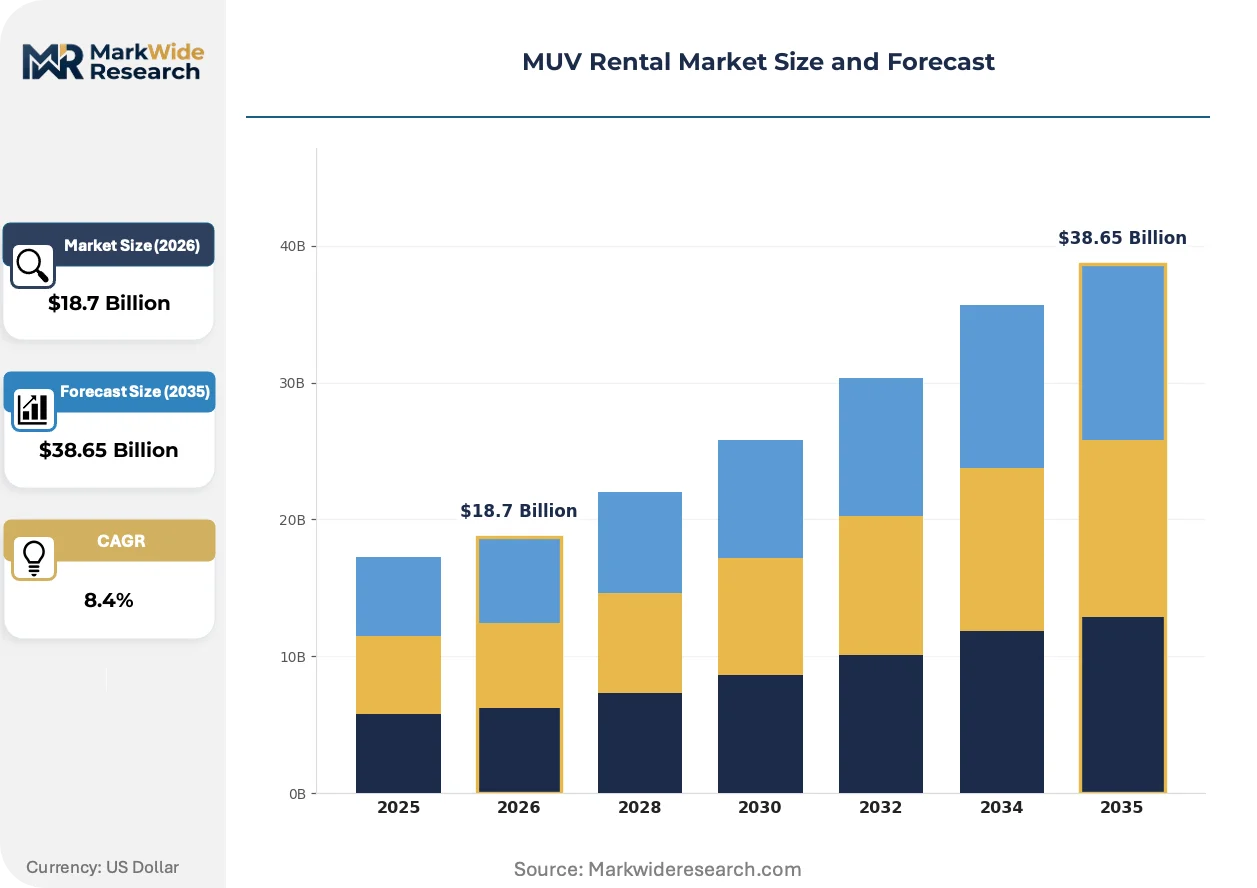
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Minivan, Pickup Truck, Crossover Rental Duration: Short-term, Long-term, Weekend, Weekly Customer Type: Corporate Clients, Tourists, Local Residents, Event Planners Service Model: Self-service, Full-service, Peer-to-peer, Subscription |
| Companies Covered | SIXT SE, Uber Technologies Inc., Enterprise Holdings Inc., Localiza Rent a Car SA, Turo Inc., Avis Budget Group Inc., Europcar Mobility Group SA, Carzonrent India Pvt. Ltd., Hertz Global Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MUV Rental Market Emerging Trajectories
Digital fleet management systems are compressing operational decision cycles while regulatory pressure accelerates powertrain diversification across rental portfolios.
Telematics platforms with embedded predictive maintenance algorithms are automating vehicle health monitoring and dispatch optimization. Large fleet operators deploy these systems across multi-state networks to reduce unplanned downtime. The technology is automating route assignment and charge-state balancing, eliminating manual fleet coordination overhead.
NHTSA Corporate Average Fuel Economy rules compel fleet composition shifts toward electrified powertrains with escalating stringency through 2032. Rental operators face capital intensity spikes as compliance timelines compress procurement windows. Commercial long-term rental segments bear the highest compliance burden due to mileage concentration and utilization rates.
Flexible access contracts are displacing traditional ownership models among suburban households with intermittent vehicle needs. Peer-to-peer platforms capture demand from price-sensitive segments while established operators defend corporate accounts with guaranteed availability tiers. This behavioral pivot concentrates in United States metropolitan areas where parking costs and insurance burdens erode ownership economics.
MUV Rental Market Segmentation
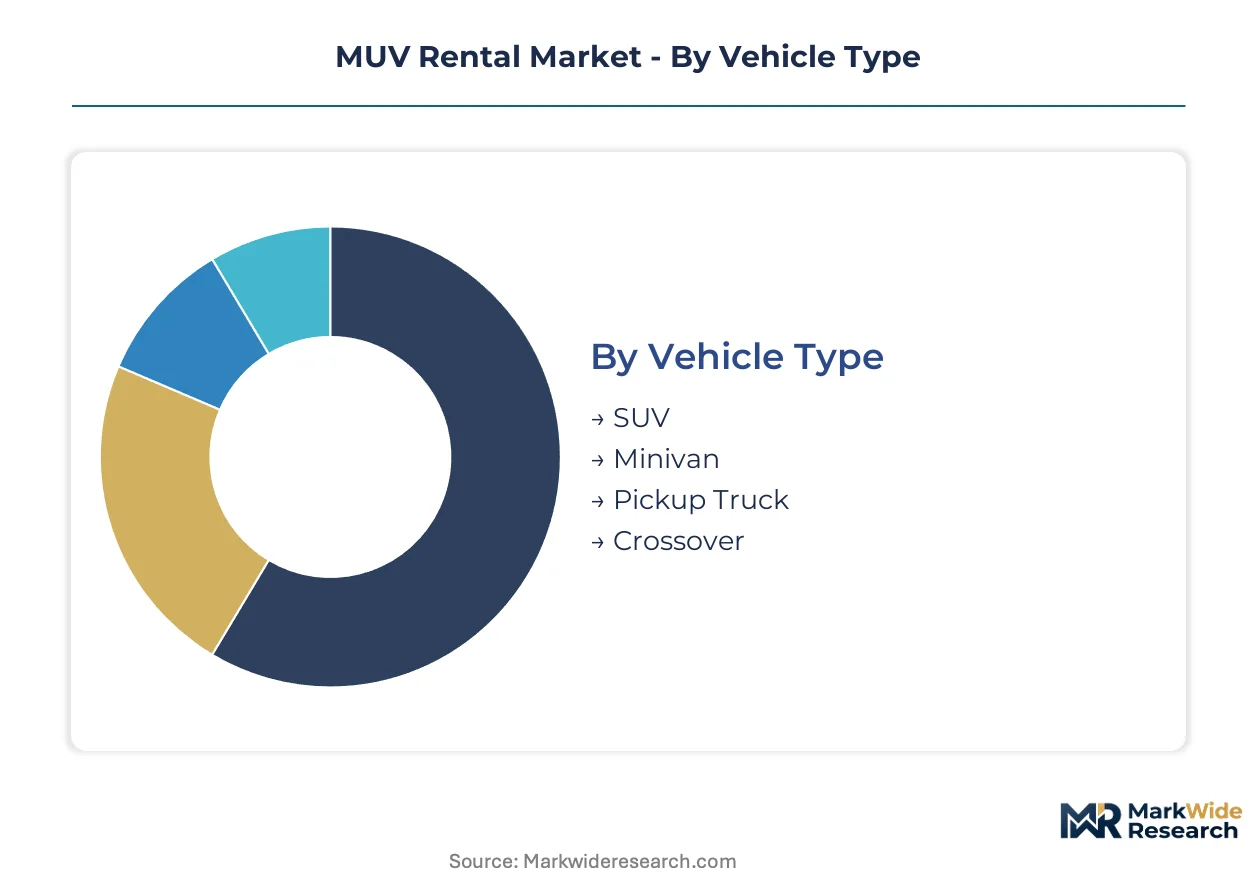
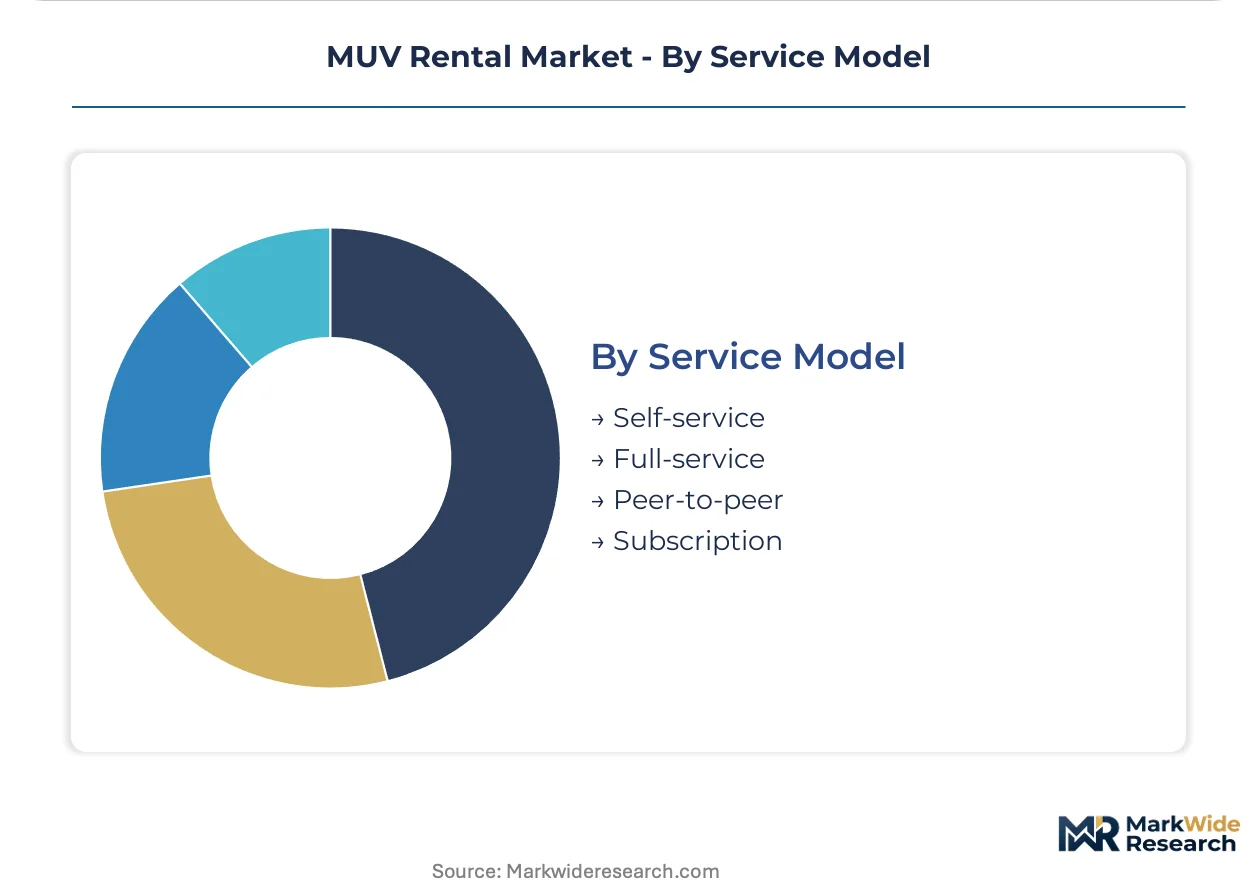
Segmentation in the MUV rental market reveals divergent capital intensity and margin profiles across vehicle configurations and service architectures. Fleet operators configure procurement and depreciation strategies around these axes, while customer acquisition costs vary dramatically by duration and service model.
Vehicle Type:
Powertrain specification and chassis architecture differentiate rental economics across utility vehicle categories.
- SUV:Body-on-frame and unibody configurations dominate fleet procurement, with seating for 7-8 passengers and towing capacity above 2,000 kg. Corporate ground transportation contracts in Texas and Florida concentrate demand here, where NHTSA fuel economy rules force hybrid powertrain integration.
- Minivan:Sliding-door accessibility and flat-load flooring optimize for family mobility and light commercial logistics. Tourist segments in Orlando and Anaheim generate acute seasonal demand spikes during school vacation periods.
- Pickup Truck:Contractor logistics and last-mile delivery applications drive commercial utilization, with open-bed cargo volume exceeding 1,200 liters.
- Crossover:Car-based unibody platforms deliver sedan-like efficiency with elevated seating positions, capturing price-sensitive local resident demand.
Mature deployment sits with SUV configurations in airport-centric corporate fleets. Newer deployment is concentrated in crossover segments as urban parking constraints reshape vehicle size preferences.
Rental Duration:
Utilization patterns and revenue per vehicle-day diverge sharply across time-based booking structures.
- Short-term:Single-day to three-day bookings generate the highest transaction frequency and per-day revenue rates. Business travelers at Hartsfield-Jackson Atlanta and Dallas Fort Worth International drive consistent weekday demand.
- Long-term:Monthly and quarterly contracts stabilize fleet utilization and reduce customer acquisition overhead. Corporate procurement teams in California negotiate these structures to satisfy EPA tailpipe compliance without capital ownership.
- Weekend:Friday-through-Sunday patterns concentrate leisure demand with premium pricing elasticity.
- Weekly:Seven-day blocks optimize for vacation travel and temporary replacement vehicle needs.
Long-term contracts anchor fleet planning for major operators. Weekend bookings are climbing the fastest as suburban households seek intermittent vehicle access without ownership burdens.
Customer Type:
Contract structure and pricing power vary substantially across end-user categories with divergent loyalty profiles.
- Corporate Clients:Master service agreements with guaranteed availability tiers and consolidated billing. Enterprise sales teams in Chicago and Houston negotiate multi-year contracts with electrified fleet mandates.
- Tourists:Price-sensitive demand with high seasonality and low repeat rates, concentrated in gateway markets.
- Local Residents:Subscription and peer-to-peer platform adoption concentrates here as parking costs in New York and San Francisco erode ownership economics.
- Event Planners:Acute demand spikes around conventions, weddings, and sporting events with premium willingness-to-pay.
Corporate clients provide the most structurally stable revenue base. Local resident segments are expanding most quickly as flexible access models displace traditional ownership.
Service Model:
Operational infrastructure requirements and margin structures differentiate delivery mechanisms across the rental value chain.
- Self-service:Kiosk and mobile-app check-in eliminate labor overhead but require dense depot networks. Airport operators in Denver and Phoenix deploy this model to compress transaction costs.
- Full-service:Counter-based agent interaction commands rate premiums and captures upsell revenue on insurance and accessories.
- Peer-to-peer:Asset-light inventory access through owner-operator marketplaces bypasses capital-intensive fleet ownership.
- Subscription:Flat-fee monthly access with vehicle swap flexibility creates recurring revenue streams and higher customer lifetime value.
Full-service counters dominate premium corporate accounts. Subscription deployment is gaining share fastest as technology platforms enable seamless vehicle exchange logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American MUV rental density through airport-centric corporate procurement and sprawling metropolitan geography that sustains vehicle dependency. Fleet operators concentrate electrified inventory here to satisfy enterprise contracts while navigating Texas state-level infrastructure constraints.
United States
Corporate fleet restructuring and suburban household demand for flexible vehicle access dominate transaction volumes. The EPA tailpipe emission standards and NHTSA fuel economy rules compel hybrid and electric MUV procurement across national depot networks. Los Angeles and Miami operators face acute charging infrastructure gaps despite California ZEV mandates driving electrified fleet investment.
Germany
Industrial corridor logistics and premium corporate ground transportation sustain diesel-to-hybrid transition demand. The EU Green Deal and national fleet emission targets accelerate electrified utility vehicle procurement timelines. Munich and Frankfurt airport hubs concentrate long-term commercial contracts with integrated telematics platforms.
Brazil
Urban freight logistics and tourism circuits around coastal metropolitan areas drive pickup truck and minivan utilization. ANVISA vehicle safety regulations and state-level environmental programs in São Paulo reshape fleet composition toward cleaner powertrains. Localiza Rent a Car anchors dense urban coverage in São Paulo and Rio de Janeiro with depot networks optimized for contractor logistics.
India
Intercity family mobility and SME logistics applications concentrate demand for seven-seater utility vehicles. The PLI scheme for automotive manufacturing and FAME subsidy structures accelerate electric MUV adoption in fleet procurement. Bangalore and Hyderabad technology corridors generate emerging subscription service demand among young professionals.
United Arab Emirates
Event logistics and luxury tourism segments sustain premium SUV rental tiers with high per-vehicle revenue yields. Dubai's Road and Transport Authority fleet electrification targets and federal net-zero commitments reshape procurement toward hybrid powertrains. Dubai International Airport and Abu Dhabi urban clusters concentrate full-service counter infrastructure with integrated hospitality partnerships.
MUV Rental Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service tier and fleet technology dimensions, with airport-dominant operators capturing corporate contract stability while peer-to-peer platforms erode price-sensitive leisure segments. The vendor base consolidates around three strategic archetypes: capital-intensive fleet owners with centralized procurement, asset-light marketplace platforms, and hybrid operators blending owned inventory with third-party supply. M&A activity concentrates on telematics platform acquisition and regional depot network expansion, while strategic partnerships with charging infrastructure providers reshape electrified fleet deployment economics.
Within the integrated fleet ownership tier, Enterprise Holdings Inc. and Avis Budget Group Inc. represent capital-intensive archetypes with airport-dominant positioning and centralized procurement scale. SIXT SE and Europcar Mobility Group SA anchor European operations with premium service tier focus and corporate contract density. Turo Inc. exemplifies the asset-light marketplace model, bypassing depot infrastructure through peer-to-peer inventory aggregation. Localiza Rent a Car SA occupies the emerging market specialist position with concentrated Latin American geographic coverage. Uber Technologies Inc. and Hertz Global Holdings Inc. sit within technology-integrated mobility platforms, blending rental access with broader transportation service ecosystems.
| Leading Market Players |
|---|
| SIXT SE |
| Uber Technologies Inc. |
| Enterprise Holdings Inc. |
| Localiza Rent a Car SA |
| Turo Inc. |
| Avis Budget Group Inc. |
| Europcar Mobility Group SA |
| Carzonrent India Pvt. Ltd. |
| Hertz Global Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Premium-corporate tier divergence from commodity-leisure rentals manifests in both rate structures and fleet procurement configurations. Airport-dominant operators command guaranteed-availability premiums through centralized SUV and minivan procurement, while peer-to-peer platforms undercut depot infrastructure costs with owner-operator inventory aggregation.
Pricing Analysis
Utilization-based pricing anchors MUV rental economics, with per-day rates scaling to vehicle throughput and downtime risk. Three-tier pricing structure across premium, standard, and economy levels separates corporate master service agreements from tourist walk-up rates and subscription flat-fee models. Cost compression in short-term leisure tiers intensifies because Turo and similar platforms eliminate fixed depot overhead. Tourist segments exhibit highest price sensitivity; corporate procurement teams with EPA compliance mandates show lowest sensitivity.
Supply Chain Analysis
Vehicle remarketing and refurbishment flows create reverse-logistics complexity as electrified fleet turnover accelerates. OEM supply concentrates in Japan, Germany, and South Korea for hybrid powertrain components; battery cell manufacturing clusters in China and South Korea. Cathode material processing draws from Indonesian nickel and Chilean lithium supply chains. Single-source vulnerability in semiconductor-based telematics modules poses structural risk. Distribution runs through airport depot networks and urban satellite locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MUV rental consolidation accelerates as electrification capital requirements force subscale operators toward exit or acquisition. EPA and NHTSA compliance timelines compress procurement windows, advantaging fleet owners with centralized financing scale.
For Market Incumbents: To counter peer-to-peer platform erosion in price-sensitive leisure segments, Enterprise-scale operators should deepen airport counter density with guaranteed-availability tiers and secure captive battery supply agreements with Korean cell manufacturers to lock in electrified fleet economics. For New Entrants and Emerging Players: Digital-native subscription platforms offer the lowest customer acquisition cost route into underserved suburban household segments with intermittent vehicle needs. White-space targets include secondary-market depot networks in Texas and Florida corridor cities lacking DC fast-charging infrastructure, plus corporate SME logistics accounts below Enterprise contract minimums. For Investors and Strategic Acquirers: Re-rating potential sits with telematics-enabled fleet operators given NHTSA fuel economy enforcement tightening. Long-term viability favors asset-light marketplace models with software-defined vehicle integration capability. Acquisition target archetype: regional operators with dense urban depot networks and nascent electrified inventory. Signal to watch: state-level ZEV mandate acceleration beyond California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | DC fast-charging depot deployment in Dallas-Fort Worth and Houston satisfies Texas corporate fleet electrification contracts. |
| Telematics Platform Acquisition | Predictive maintenance algorithms from specialized vendors compress unplanned downtime across multi-state SUV networks. |
| Battery Supply Agreement | Long-term cathode material offtake with Korean manufacturers hedges East Asian supply chain concentration risk. |
| Subscription Service Launch | Flat-fee monthly models with vehicle-swap flexibility capture suburban household defection from ownership economics. |
| Corporate Mobility Integration | API-linked enterprise travel platforms embed MUV access into Fortune 500 ground transportation procurement workflows. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Fleet operator procurement directors, airport depot managers, corporate travel managers, and EV charging infrastructure developers contributed primary perspectives. EPA enforcement documentation, NHTSA CAFE rulemaking records, state ZEV mandate filings, and vehicle registration databases supplied secondary validation. Bottom-up transaction modeling and top-down fleet composition analysis triangulated market sizing.
Granularity-level modeling distinguished powertrain architecture, rental duration tiers, customer contract types, and service delivery mechanisms across the projection horizon. CAGRs derived from fleet turnover velocity, electrification penetration curves, and corporate mobility restructuring rates. Vehicle depreciation schedules, battery residual value uncertainty, and charging infrastructure buildout timelines entered as industry-specific forecast inputs.
The model holds under steady EPA enforcement and NHTSA rulemaking timelines; deviation in federal regulatory rollback or battery supply disruption would shift fleet procurement trajectories. Forecasts embed assumptions about electrified vehicle total cost of ownership parity. Practitioners should monitor cathode material price volatility and secondary-market charging infrastructure deployment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
India Car Rental Market
Transportation Services
India Taxi Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Bike and Scooter Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Philippines Car Rental Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Aerial Lift Rental Services Market