
 Solar Laser Drilling Market | 2026-2036
Solar Laser Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Laser Drilling Market Analysis
ISO 9001 quality management certification is reorganizing supplier qualification protocols for solar laser drilling equipment vendors. Coherent leverages its vertical integration across laser sources and beam delivery systems to sustain pricing power in precision texturing applications. TRUMPF anchors its position through R&D intensity in ultrafast laser architectures for PERC and TOPCon cell architectures. DMG MORI competes by extending its machine tool expertise into photovoltaic-specific automation platforms.
Solar laser drilling employs focused coherent radiation to create micro-scale vias and surface textures on crystalline silicon and thin-film substrates, typically operating at pulse durations below 50 picoseconds to minimize heat-affected zones and preserve carrier lifetime. Fiber laser systems dominate current installation bases due to their wall-plug efficiency exceeding 30 percent and maintenance intervals stretching beyond 30,000 hours, while ultraviolet laser configurations capture premium positioning in shingled cell and heterojunction applications demanding finer feature resolution. Material removal applications absorb the largest share of deployed capacity, though precision cutting segments for half-cell and shingled module formats represent the fastest-growing margin pool as module architects pursue higher packing densities.
FDA laser safety classifications and OSHA workplace exposure limits govern equipment design and factory deployment protocols in the United States, while REACH substance restrictions and CE machinery directives shape component sourcing and market access across European installations. China's MIIT enforces GB standards for industrial laser equipment efficiency and electromagnetic compatibility, creating compliance layers that filter non-domestic suppliers from state-backed photovoltaic expansion programs. Stakeholders must monitor how evolving module efficiency mandates in multiple jurisdictions recalibrate the technical specifications that define competitive equipment procurement criteria.
Market Dynamics
GB standards for solar module efficiency are compressing process windows for laser drilling equipment, forcing photovoltaic manufacturers to upgrade from nanosecond to picosecond architectures to preserve carrier lifetime in thinner silicon wafers.
Growth Catalysts
- Dual carbon goals:China's binding emissions targets are accelerating gigawatt-scale fab construction in Jiangsu province, creating concentrated demand for precision tooling.
- PERC-to-TOPCon migration:Cell architecture transitions require finer via formation, expanding addressable equipment spend for ultrafast laser configurations.
- Shingled cell formats:Module architects pursuing higher packing densities are commissioning precision cutting capacity for half-cell and overlapping busbar designs.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers dominate precision beam delivery subsystems, exposing procurement to single-source vulnerability.
- Ultrafast laser cost structure:Titanium-sapphire and thin-disk architectures carry 3-4x capex multiples versus fiber alternatives, slowing adoption outside premium cell lines.
- CE machinery directive friction:European safety certification timelines for Class 4 laser systems extend factory deployment schedules by 6-9 months.
Strategic Opportunities
- Heterojunction cell penetration:Japanese and South Korean manufacturers are qualifying ultraviolet laser texturing for amorphous silicon interfaces, opening premium positioning.
- Service contract unbundling:Equipment vendors are separating laser source maintenance from motion platform support, creating recurring revenue streams.
- India PLI scheme:Domestic content requirements for solar manufacturing are incentivizing localized assembly of beam delivery systems.
Industry Challenges
- Ultrafast laser technician scarcity:Fiber laser maintenance skills are commoditized; picosecond system calibration requires specialized photonics training that fabs struggle to source.
- ISO 9001 certification timelines:Supplier qualification protocols now demand 12-18 month quality management audits, extending sales cycles.
- Legacy nanosecond integration:Retrofitting existing PERC lines with picosecond sources requires custom beam path engineering that disrupts production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Laser Drilling Market |
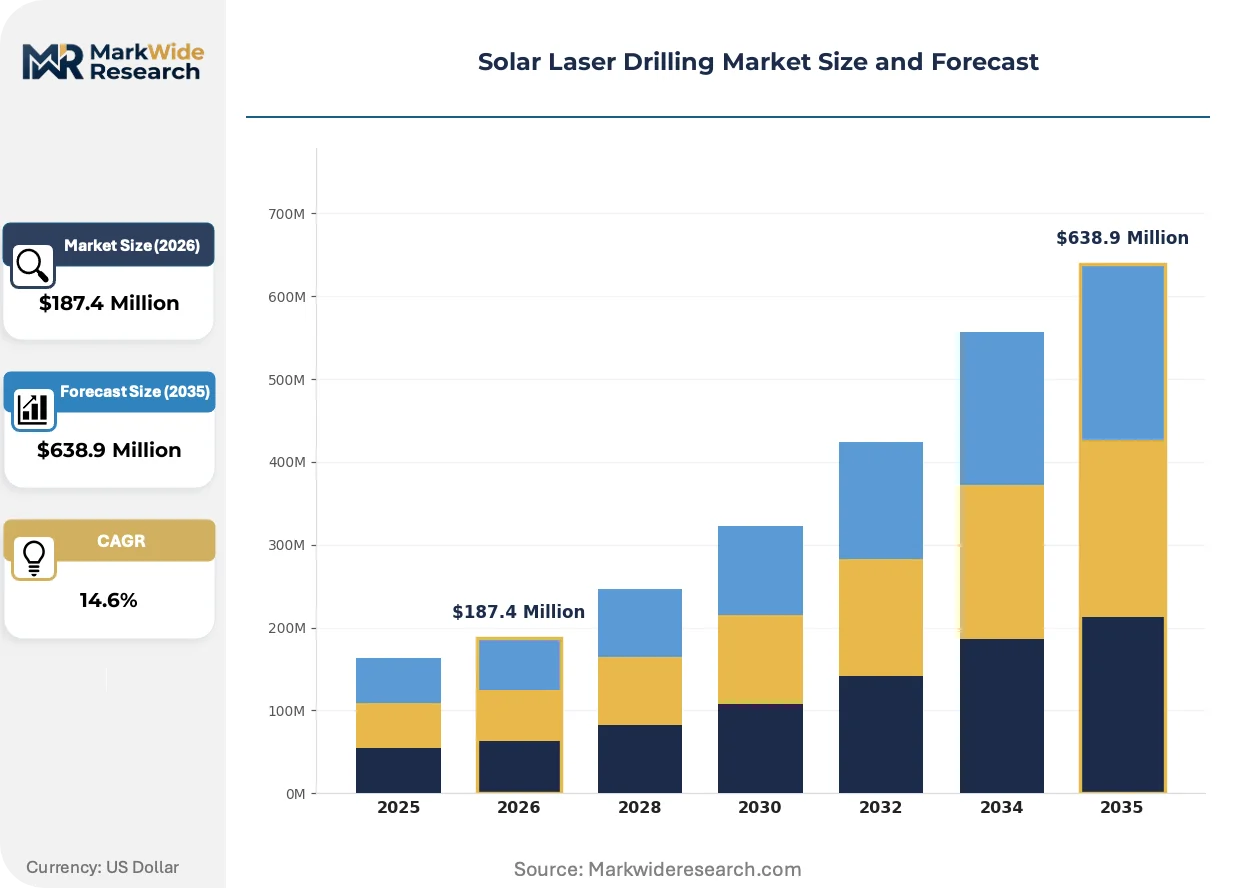
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Material Removal, Precision Cutting, Texturing, Structuring Technology: Fiber Laser, CO2 Laser, Solid-State Laser, Ultraviolet Laser End User: Aerospace, Automotive, Electronics, Manufacturing Size: Small-Scale, Medium-Scale, Large-Scale, Industrial |
| Companies Covered | DMG MORI, Sahajanand Laser Technology Limited, Coherent, 3D Micromac, Mitsuboshi Diamond Industrial, IPG Photonics Corporation, SPI Lasers, GF Machining Solutions, TRUMPF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Laser Drilling Market Emerging Trajectories
Ultrafast laser architectures are decomposing established process boundaries between material removal and precision cutting, enabling single-platform flexibility that reduces capital redundancy across cell format transitions.
Picosecond fiber lasers are decomposing the traditional separation between contact finger drilling and edge isolation steps. Tier-1 photovoltaic manufacturers in China and Southeast Asia are adopting dual-purpose platforms that switch between via formation and wafer dicing without mechanical retooling. This convergence is decomposing equipment vendor margins by collapsing two machine categories into one procurement decision.
REACH substance restrictions on laser cooling fluids and optical coatings are forcing reformulation of thermal management systems across European installations. ECHA's expanded SVHC candidate list now captures several fluorinated compounds common in ultrafast laser chillers. German and Italian equipment integrators are accelerating qualification of water-glycol alternatives, though thermal stability testing extends validation cycles.
Module architects are consolidating laser drilling procurement decisions at the gigafactory level rather than delegating to cell line subcontractors. This concentration is compressing vendor count and elevating technical service capabilities as a selection criterion. The shift is most visible in China's Jiangsu and Anhui manufacturing clusters, where state-backed fabs now mandate 10-year spare parts availability commitments.
Solar Laser Drilling Market Segmentation
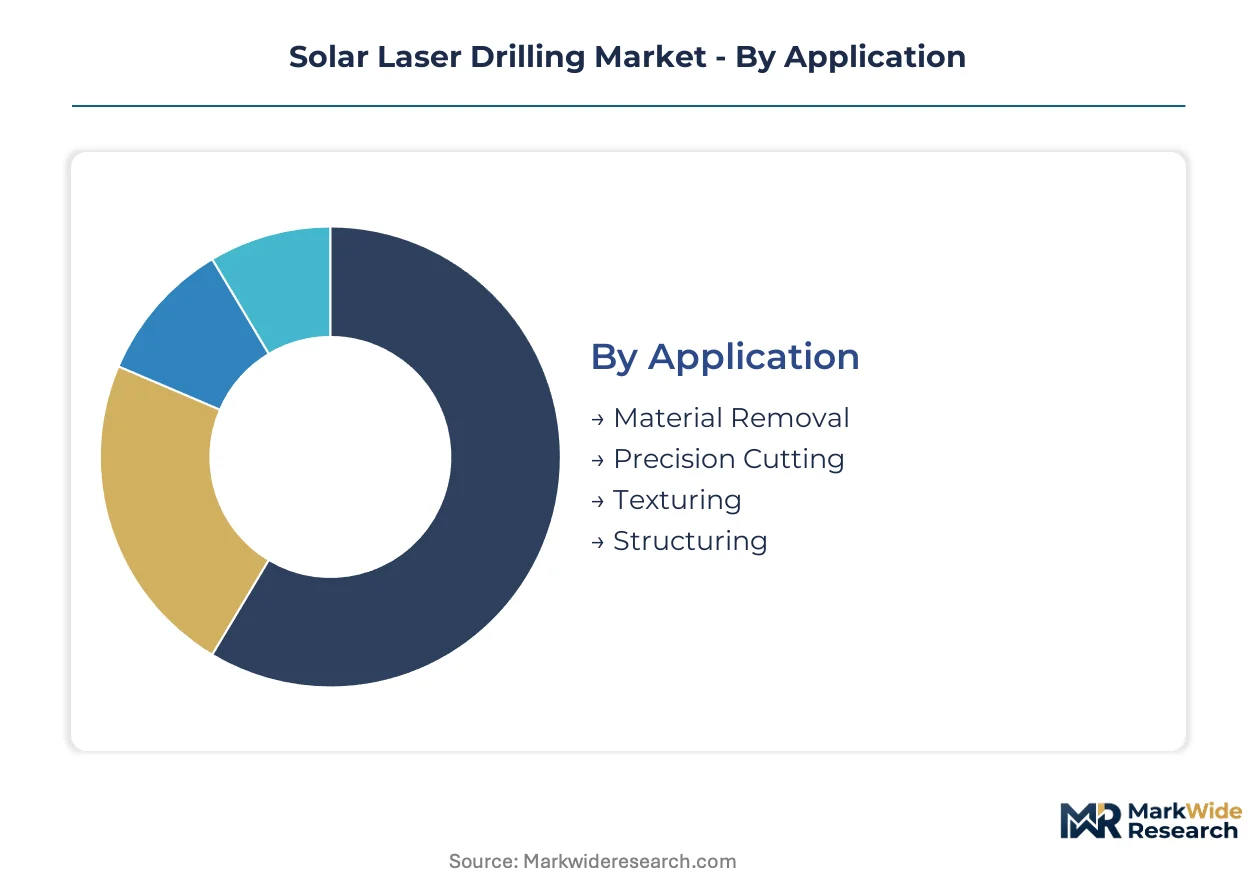
Laser drilling configurations in photovoltaic manufacturing diverge sharply by thermal budget and feature resolution requirements. Equipment procurement patterns cluster around specific cell architectures and regional efficiency mandates rather than generic manufacturing scale.
Application:
Domestic Chinese fabs concentrate procurement in material removal and texturing for PERC and TOPCon lines, while export-oriented manufacturers in Southeast Asia prioritize precision cutting for half-cell and shingled formats serving European and North American module markets.
- Material Removal:Picosecond fiber lasers ablate dielectric layers for contact finger formation on silicon wafers. Jiangsu province's gigawatt-scale fabs drive volume procurement as GB efficiency standards tighten process windows.
- Precision Cutting:Ultrafast architectures dice wafers into half-cells and shingled strips without thermal damage. Demand concentrates in Vietnam and Malaysia for export modules targeting EU packing density requirements.
- Texturing:Ultraviolet configurations create anti-reflective surface structures on monocrystalline substrates.
- Structuring:Laser-induced periodic surface structures enhance light trapping in thin-film and heterojunction architectures.
Material removal commands the established base. The steepest expansion runs through precision cutting.
Technology:
Cost tier differentiation separates maintenance-light fiber platforms from precision-grade ultraviolet systems requiring specialized technician training and shorter source lifecycles.
- Fiber Laser:Ytterbium-doped fiber architectures deliver wall-plug efficiency exceeding 30 percent with maintenance intervals beyond 30,000 hours. Chinese PERC manufacturers in Anhui province standardize on these systems for contact finger drilling economics.
- Ultraviolet Laser:Frequency-tripled solid-state sources achieve sub-10 micrometer feature resolution for heterojunction texturing. Japanese and South Korean cell makers absorb 3-4x capex multiples for amorphous silicon interface quality.
- CO2 Laser:Long-wavelength infrared systems process thin-film cadmium telluride and CIGS substrates.
- Solid-State Laser:Nd:YAG and thin-disk architectures bridge nanosecond and picosecond pulse regimes for legacy line retrofits.
Fiber laser configurations dominate installed capacity. Ultraviolet platforms are climbing the fastest as heterojunction penetration deepens.
End User:
Customer type determines specification stringency, with automotive and aerospace procurement demanding ISO 9001-certified quality management and traceable calibration protocols absent in general manufacturing.
- Electronics:Photovoltaic cell and module manufacturers constitute the primary demand pool. Tier-1 Chinese fabs mandate 10-year spare parts availability and localized service presence.
- Automotive:Solar roof-integrated vehicle programs require precision cutting for curved glass substrates. German and Japanese OEMs specify Class 4 laser safety systems with redundant interlock architectures.
- Aerospace:Satellite solar array manufacturers demand hermetic sealing integrity for space-grade cells.
- Manufacturing:General industrial users deploy laser drilling for tooling and prototyping outside photovoltaic mainstream.
Electronics absorbs the dominant equipment spend. Automotive applications are expanding most quickly as vehicle-integrated photovoltaics mature.
Size:
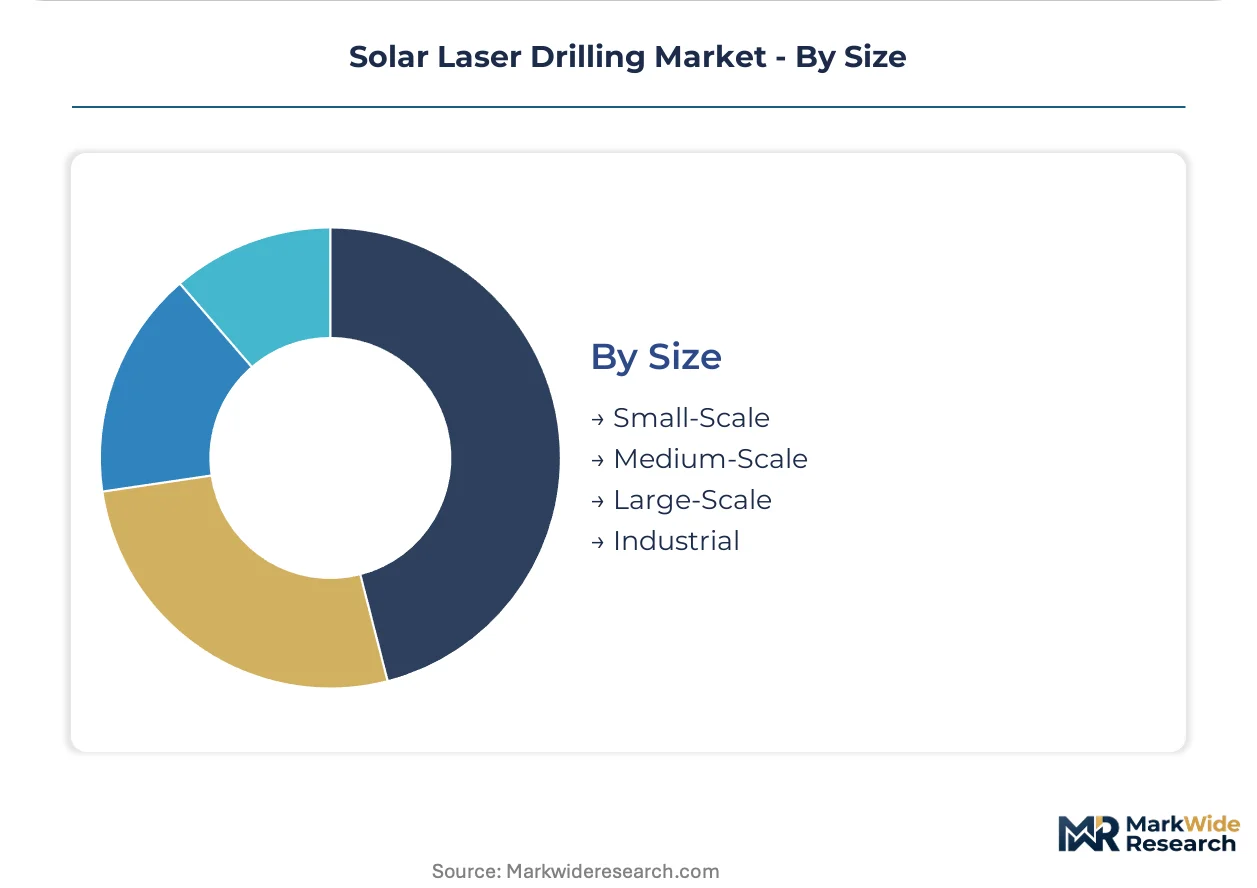
Volume tier alignment reflects capital deployment scale, with industrial-scale platforms commanding integrated automation and small-scale systems serving pilot line and R&D functions.
- Large-Scale:Multi-beam platforms process 10,000+ wafers per hour with automated loading and optical inspection. State-backed Chinese gigafactories in Jiangsu and Anhui provinces exclusively procure at this tier.
- Industrial:Standalone systems with palletized material handling serve mid-volume module assemblers. Indian PLI scheme beneficiaries in Gujarat and Tamil Nadu favor this tier for phased capacity ramp.
- Medium-Scale:Semi-automated platforms target emerging cell architectures and process development.
- Small-Scale:Laboratory and pilot line configurations qualify new laser sources before production scale-up.
Large-scale systems command the dominant procurement volume. Industrial-tier platforms are gaining share fastest as India's manufacturing incentives attract new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's grid interconnect capacity underwrites China's dominance in photovoltaic laser tooling procurement. Jiangsu province's coastal ports handle precision optical component imports that feed gigawatt-scale cell manufacturing clusters.
China
MIIT's GB standards for industrial laser equipment efficiency are compressing process windows for contact finger formation. The dual carbon goals mandate binding emissions reductions that accelerate fab construction. Jiangsu province's manufacturing corridor concentrates demand where state-backed facilities procure multi-beam platforms with 10-year spare parts commitments.
United States
OSHA workplace exposure limits for Class 4 laser systems govern factory deployment protocols across Arizona and Texas solar corridors. The IRA manufacturing tax credits are reshoring module assembly capacity. Greater Phoenix's semiconductor-adjacent workforce pools support precision photonics technician training for picosecond system calibration.
Germany
ECHA's REACH substance restrictions on fluorinated cooling fluids are forcing thermal management system reformulations. The CE machinery directive extends safety certification timelines for ultrafast laser installations. Baden-Württemberg's precision engineering cluster anchors beam delivery subsystem production for European photovoltaic equipment integrators.
Japan
METI's efficiency benchmarks for heterojunction cell architectures are qualifying ultraviolet laser texturing for amorphous silicon interfaces. JIS standards govern electromagnetic compatibility for industrial laser deployments. Kyushu's photovoltaic research corridor is validating sub-10 micrometer feature resolution for premium cell lines.
India
The PLI scheme's domestic content requirements are incentivizing localized assembly of beam delivery systems. BIS certification protocols filter imported laser equipment for compliance with national safety standards. Gujarat's manufacturing incentives attract new entrants procuring industrial-tier platforms for phased capacity ramp.
Solar Laser Drilling Market Vendor Landscape
Listed leaders compete with private specialists across capital access and R&D intensity. The vendor base stratifies into three tiers: diversified machine tool conglomerates, pure-play laser source manufacturers, and regional automation integrators. Consolidation pressures favor scale-driven players with captive optical component supply. Dominant competitive moves include backward integration into beam delivery subsystems and strategic partnerships for localized service networks.
Among diversified machine tool conglomerates, DMG MORI and TRUMPF exemplify archetypes extending precision automation expertise into photovoltaic-specific platforms. Coherent occupies a position within laser source specialists leveraging vertical control across beam generation and delivery. These three represent the premium-tier vector where ISO 9001 certification and 10-year spare parts availability separate procurement winners from commodity suppliers.
| Leading Market Players |
|---|
| DMG MORI |
| Sahajanand Laser Technology Limited |
| Coherent |
| 3D Micromac |
| Mitsuboshi Diamond Industrial |
| IPG Photonics Corporation |
| SPI Lasers |
| GF Machining Solutions |
| TRUMPF |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with German and Japanese optical component suppliers lock in beam delivery subsystem access while fixing 60-70 percent of equipment BOM costs for photovoltaic laser drilling platforms. These arrangements concentrate pricing power with precision optics manufacturers as Chinese gigafabs scale picosecond architecture procurement.
Pricing Analysis
Certification level creates the primary spread between equipment tiers. Three-tier pricing structure across ISO 9001-certified premium, CE-compliant standard, and uncertified economy levels separates procurement winners in Jiangsu province's state-backed fabs from commodity suppliers. Price erosion runs through fiber laser configurations as Chinese domestic source manufacturers achieve wattage parity with IPG Photonics and SPI Lasers. Tier-1 photovoltaic manufacturers absorb 3-4x capex multiples for ultraviolet platforms, while Indian PLI scheme beneficiaries exhibit highest price sensitivity in industrial-tier procurement.
Supply Chain Analysis
Strategic stockpiling of ytterbium-doped fiber and precision optical substrates supersedes just-in-time preferences given 12-18 month qualification timelines for alternative suppliers. German and Japanese suppliers dominate beam delivery subsystems, creating single-source vulnerability for picosecond pulse compressors and galvanometer scanning heads. Tariff exposure runs through precision optics imports into China's Jiangsu manufacturing corridor. Distribution runs through direct vendor-fab relationships with localized service presence mandates, bypassing traditional industrial equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Picosecond architecture adoption represents a high-growth disruption as GB efficiency standards compress process windows and displace legacy nanosecond systems. China's dual carbon goals accelerate this inflection by mandating binding emissions reductions that concentrate gigawatt-scale fab construction.
For Market Incumbents: Secure captive supply of precision beam delivery subsystems through backward integration or long-term offtake arrangements with German and Japanese optical manufacturers. Anchor R&D investment in dual-purpose platforms that collapse contact finger drilling and edge isolation into single procurement decisions, defending against margin compression from equipment category convergence. For New Entrants and Emerging Players: Anchor in India's PLI scheme beneficiaries procuring industrial-tier platforms for phased capacity ramp, where domestic content requirements for beam delivery assembly create localization partnerships. Target ultraviolet laser texturing for heterojunction cell architectures as Japanese and South Korean manufacturers qualify sub-10 micrometer feature resolution, opening premium positioning outside Chinese fiber laser dominance. For Investors and Strategic Acquirers: Pure-play laser source specialists with in-house beam generation and delivery capabilities present acquisition targets as module architects consolidate procurement at the gigafactory level. Watch for heterojunction cell penetration rates crossing 15 percent in Japanese and South Korean manufacturing as the signal that ultraviolet platform demand is accelerating beyond current fiber laser installation bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Captive supply of beam delivery subsystems insulates against German and Japanese supplier concentration. |
| Dual-Purpose Platform Development | Single-system flexibility for via formation and wafer dicing collapses equipment categories and captures consolidated procurement. |
| Localized Service Network Expansion | Ten-year spare parts availability commitments separate winners in China's Jiangsu and Anhui state-backed fab tenders. |
| Ultraviolet Laser Source Qualification | Sub-10 micrometer resolution for heterojunction texturing opens premium positioning as Japanese cell makers advance amorphous silicon interfaces. |
| India PLI Scheme Localization Partnership | Domestic beam delivery assembly meets BIS certification requirements for Gujarat and Tamil Nadu manufacturing incentives. |
Methodological Framework
Desk research of SEC filings from laser equipment manufacturers, MIIT GB standard documentation, and photovoltaic industry association technical reports preceded structured interviews with fab equipment procurement directors, precision optics supplier account managers, and aftermarket service technicians. Primary fieldwork across Jiangsu province's manufacturing corridor and Baden-Württemberg's precision engineering cluster validated secondary data on beam delivery subsystem supply concentration. Bottom-up equipment installation tracking and top-down solar cell capacity expansion forecasts were triangulated against trade data for ytterbium-doped fiber and ultraviolet laser crystal imports.
Variance decomposition across technology segments, application types, and end-user tiers shaped the analytical framework over the projection horizon. Modeled dimensions include laser source architecture, cell format requirements, and regional regulatory cluster alignment with GB standards, CE machinery directives, and OSHA workplace exposure limits. CAGRs were derived from equipment spend intensity per gigawatt of cell capacity and migration curves from PERC to TOPCon and heterojunction architectures. Forecast inputs incorporated pulse duration requirements for carrier lifetime preservation and spare parts availability contract prevalence in tier-1 fab procurement.
Material uncertainties — abrupt shifts in China's dual carbon goal enforcement, REACH substance restriction expansion to additional fluorinated compounds, and ultrafast laser technician training pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about picosecond architecture cost curves and heterojunction cell efficiency benchmark trajectories. Revision becomes warranted when ultraviolet laser platform qualification timelines in Japanese manufacturing accelerate or decelerate substantially from current validation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market