
 Flexible Lighting Foils Market | 2026-2036
Flexible Lighting Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Lighting Foils Market Analysis
Automotive interior lighting is hardening as the dominant demand vertical for flexible lighting foils, displacing slower-growing decorative segments. Tridonic GmbH & Co KG leverages its luminaire control heritage to anchor European specification pipelines. Canatu competes through carbon nanobased conductor integration that enables 3D-formable light engines. DuPont sustains material science leadership in high-temperature polymer substrates for under-hood and cabin applications.
Flexible lighting foils are thin, bendable electroluminescent or LED-backed substrates, typically 0.1–2.0 mm thick, that convert electrical energy into uniform surface illumination across curved or irregular geometries; they serve architectural accent, automotive ambient, and wearable display applications where rigid panels fail. LED Strips dominate current volume owing to retrofit compatibility and low installation cost, while Light Sheets capture expanding margin pools in automotive dashboard and door-panel integration where optical uniformity commands premium positioning. Neon Flex occupies a mature niche in entertainment and signage, with growth tethered to IP-rated outdoor durability upgrades rather than new application development.
REACH restrictions on phthalate plasticizers and RoHS limits on heavy metals in electrical equipment constrain PVC and certain polyethylene formulations, compelling reformulation toward silicone and polycarbonate alternatives. ECHA substance evaluation protocols extend compliance timelines but raise R&D barriers for new market entrants. FDA and FAA standards govern cabin lighting in commercial aviation and medical device applications, creating dual-certification requirements for suppliers targeting transportation and healthcare verticals. Stakeholders must monitor evolving polymer exemption lists and solid-state efficiency thresholds to preserve product-market fit without stranded formulation investments.
Market Dynamics
Automotive OEM interior lighting programs are hardening specification requirements for conformable illumination substrates, compressing qualification timelines while expanding performance envelopes for thermal stability and optical uniformity.
Growth Catalysts
- REACH substance restrictions:ECHA evaluation protocols are accelerating material substitutions away from halogenated plasticizers toward silicone and polycarbonate alternatives, opening specification windows for compliant suppliers.
- LED-backed light sheet integration:Dashboard and door-panel ambient lighting programs in premium vehicle segments are pulling volume from retrofit LED strips into factory-integrated conformable substrates.
- German specification intensity:KBA type-approval integration requirements and OEM lighting standardization are concentrating demand in Stuttgart and Munich engineering centers.
Market Restraints
- Polycarbonate resin volatility:Bisphenol-A supply concentration and energy-intensive polymerization are transmitting crude oil and natural gas price swings directly into substrate cost structures.
- Carbon nanotube conductor sourcing:Single-walled nanotube purification capacity concentrates in East Asian specialty chemical producers, creating qualification bottlenecks for 3D-formable light engine developers.
- Optical uniformity thresholds:Automotive cabin applications require sub-5% luminance variation across curved surfaces, excluding lower-grade electroluminescent formulations from specification pipelines.
Strategic Opportunities
- Aviation cabin retrofits:FAA Part 25 cabin interior certification pathways for solid-state lighting are creating dual-certification demand alongside automotive programs for suppliers with polymer fire-resistance expertise.
- Medical device integration:FDA 510(k) illumination subsystem approvals for surgical navigation and diagnostic equipment represent underpenetrated volume pools with premium positioning potential.
- RoHS exemption expiration management:Proactive reformulation toward heavy-metal-free phosphors and lead-free solder interconnects is securing long-term product-market fit ahead of 2026-2027 sunset dates.
Industry Challenges
- Cross-functional lighting-system engineering:Integrating thermal management, optical design, and vehicle-network protocol compliance requires rare combinations of polymer science, electronics, and automotive domain expertise.
- Dual-certification timeline compression:Concurrent ECE R48 automotive lighting and IEC 62471 photobiological safety testing extends qualification cycles by 8-14 months for multi-vertical suppliers.
- Legacy PVC formulation stranded assets:Phthalate-dependent production lines face accelerated obsolescence as REACH authorization lists expand, demanding capital redeployment into silicone extrusion and polycarbonate film casting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Lighting Foils Market |
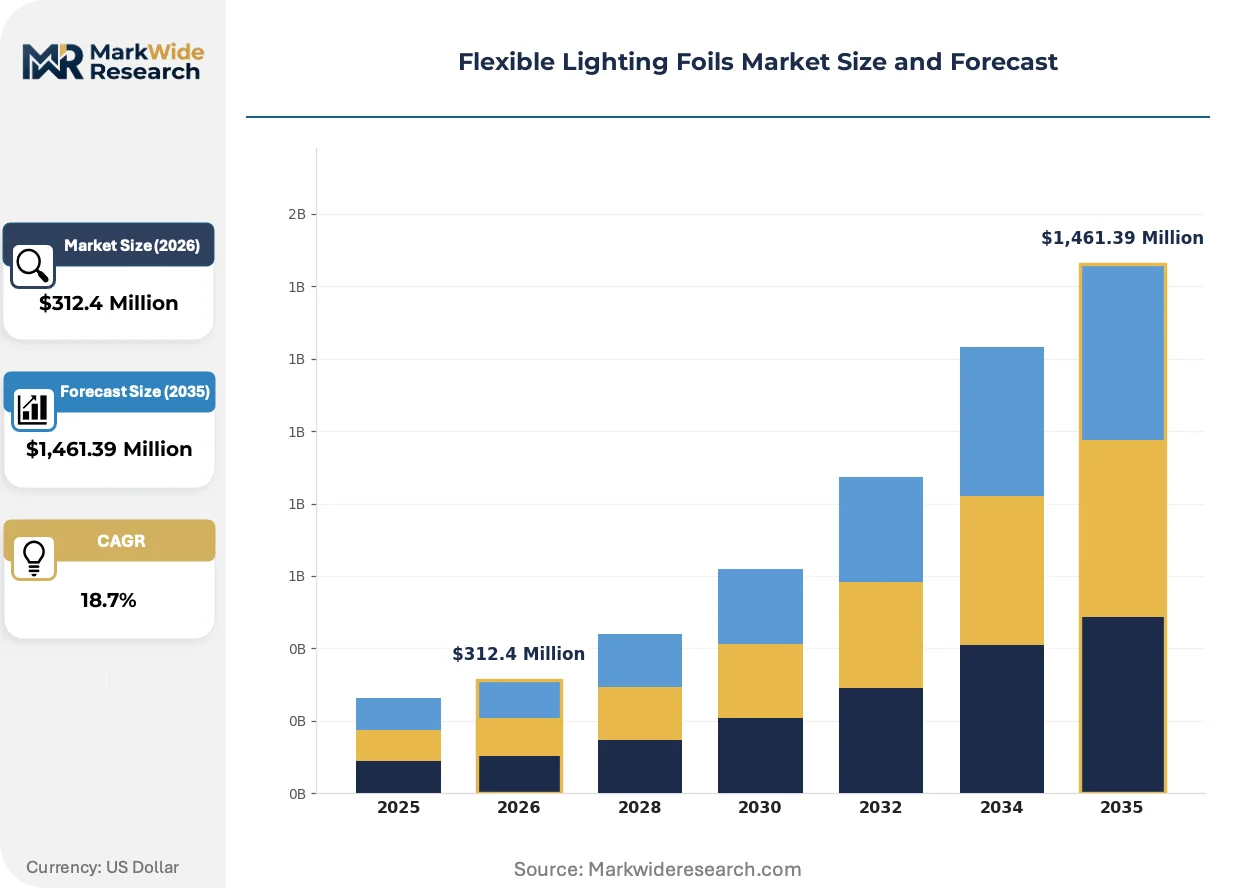
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Strips, Neon Flex, Light Panels, Light Sheets Application: Architectural Lighting, Automotive Lighting, Decorative Lighting, Stage Lighting Material: Polyethylene, Polycarbonate, Silicone, PVC End User: Residential, Commercial, Industrial, Entertainment |
| Companies Covered | Tridonic GmbH & Co KG, InovisCoat GmbH, Agfa-Gevaert Group, Flexbright Oy, Quad Industries, Canatu, 3M Company, DuPont, LG Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Lighting Foils Market Emerging Trajectories
Process automation and materials convergence are compressing development cycles while expanding the geometric complexity addressable by conformable illumination systems.
Micro-LED die transfer technology is automating the placement of sub-100-micron emitters onto flexible polymer substrates with precision previously requiring manual assembly. Tier-1 automotive suppliers in Germany and Japan are adopting roll-to-roll micro-LED bonding lines at pilot scale. This automation is compressing per-unit assembly costs while enabling pixel-dense addressable lighting zones for cabin personalization.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon blowing agents used in certain polymer foam substrates, forcing reformulation toward CO2 or water-based physical foaming processes. Material suppliers with in-house extrusion competence are internalizing these process transitions faster than compounders dependent on external substrate sourcing. Light sheet manufacturers serving automotive verticals face the most acute compliance pressure given OEM sustainability scorecard requirements.
Specification consolidation around integrated lighting modules is displacing component-level procurement patterns that previously separated substrate, driver electronics, and thermal management sourcing. Automotive Tier-2 suppliers are responding by acquiring optical design and control firmware capabilities to preserve margin capture. This behavioral shift concentrates most visibly in German and Japanese OEM supply chains where platform standardization programs are hardening module-level supplier relationships.
Flexible Lighting Foils Market Segmentation
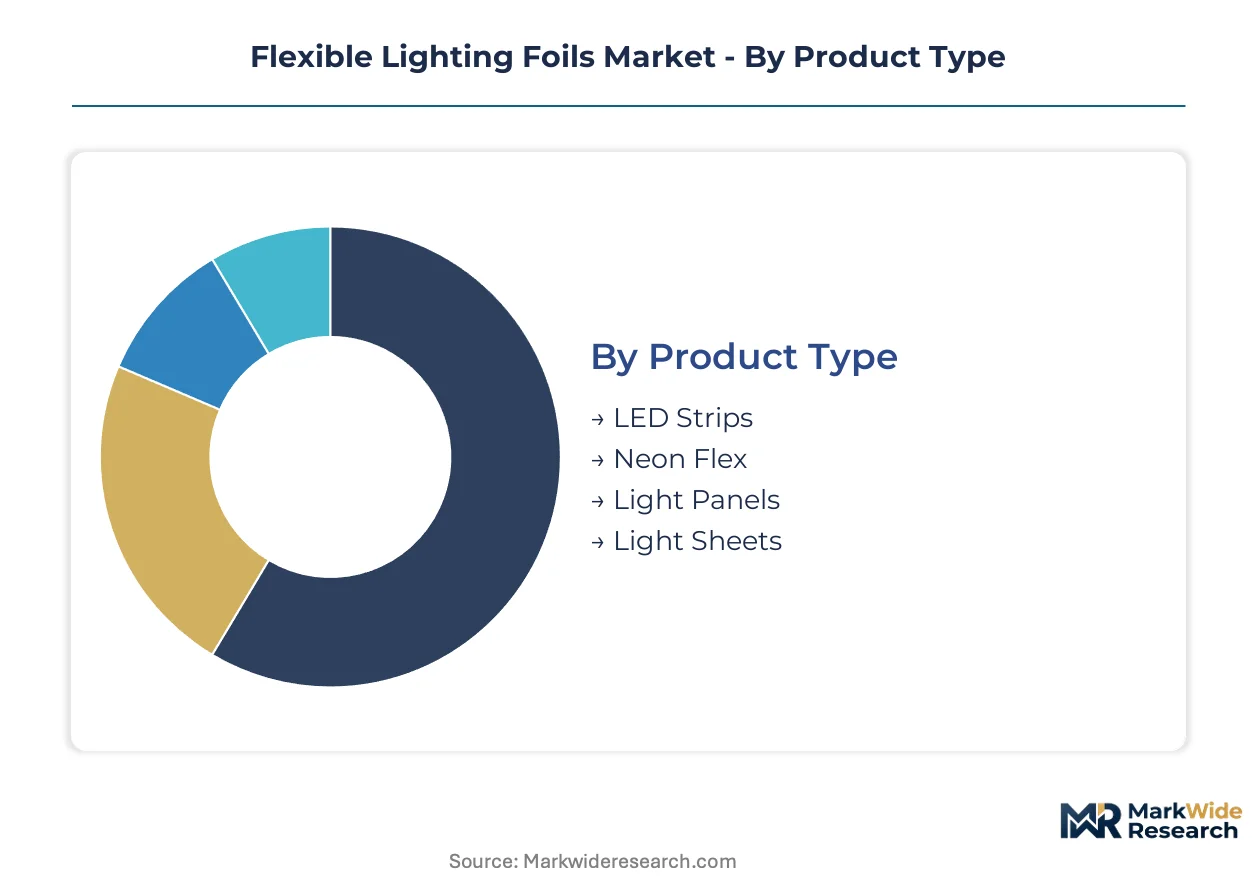
Segmentation in flexible lighting foils tracks how substrate specifications diverge across thermal, optical, and form-factor requirements. Upgrade cycles in automotive cabin programs and commercial building retrofits are redefining which product formats capture specification intensity.
Product Type:
Replacement dynamics favor formats that simplify legacy installation footprints while expanding geometric freedom for designers.
- LED Strips:Modular linear arrays mounted on flexible printed circuit boards with adhesive backing, typically 8-12 mm wide. Demand concentrates in Germany and Japan where automotive Tier-1 suppliers specify narrow-pitch variants for dashboard accent channels; retrofit compatibility with existing 12V and 24V infrastructure sustains volume leadership despite margin compression.
- Light Sheets:Large-area electroluminescent or LED-backed substrates delivering uniform illumination across curved surfaces without pixelation. Premium vehicle programs in Stuttgart and Munich are pulling specification intensity toward factory-integrated cabin ambient systems where optical uniformity commands positioning above component cost.
- Neon Flex:Silicone-encapsulated LED chains mimicking traditional glass neon with improved durability and bend radius. Entertainment venues and outdoor signage in Dubai and Las Vegas drive demand for IP67-rated variants.
- Light Panels:Rigid-to-semi-rigid edge-lit or back-lit assemblies for flat-surface applications. Commercial office retrofits in Singapore and Sydney specify ultra-thin profiles for ceiling integration.
LED Strips sits at the top of the volume ranking, with Light Sheets climbing the fastest.
Application:
Cost-tier differentiation separates specification pipelines where optical performance premiums apply from price-sensitive retrofit markets.
- Automotive Lighting:Cabin ambient, dashboard accent, and door-panel illumination programs requiring ECE R48 compliance and sub-5% luminance variation. OEM integration timelines in Germany and Japan are compressing qualification cycles while expanding thermal stability requirements.
- Architectural Lighting:Coves, soffits, and facade accent systems in commercial and institutional buildings. LEED certification pathways in California and New York are pulling specification toward low-VOC silicone formulations.
- Decorative Lighting:Residential accent and furniture integration where aesthetic flexibility outweighs optical precision. Mass-market retail channels in Brazil and India dominate procurement patterns.
- Stage Lighting:Temporary and permanent entertainment installations requiring DMX control compatibility and rapid deployment. Rental houses in London and Los Angeles prioritize durability over energy efficiency.
Architectural Lighting commands the broadest geographic footprint, while Automotive Lighting gains share fastest on OEM integration momentum.
Material:
Supply concentration in polymer feedstocks is forcing reformulation timelines that favor vertically integrated compounders over external substrate purchasers.
- Silicone:Platinum-cured elastomer systems with temperature stability to 150°C and inherent UV resistance. REACH phthalate restrictions are accelerating substitution from PVC in European automotive programs; Wacker Chemie and Dow Corning supply chains concentrate in Germany and Michigan.
- Polycarbonate:High-clarity thermoplastic films and sheets with impact resistance and optical grade transparency. Bisphenol-A supply volatility and energy-intensive polymerization transmit crude oil price swings directly into substrate costs.
- Polyethylene:Low-density and linear-low-density formulations for cost-sensitive outdoor and temporary applications. Commodity pricing and limited thermal ceiling constrain specification in premium segments.
- PVC:Legacy plasticized formulations facing accelerated obsolescence under REACH authorization expansion. Stranded production capacity in Eastern Europe and Southeast Asia demands capital redeployment.
Silicone leads the value ranking, with Polycarbonate expanding most quickly on optical-grade automotive demand.
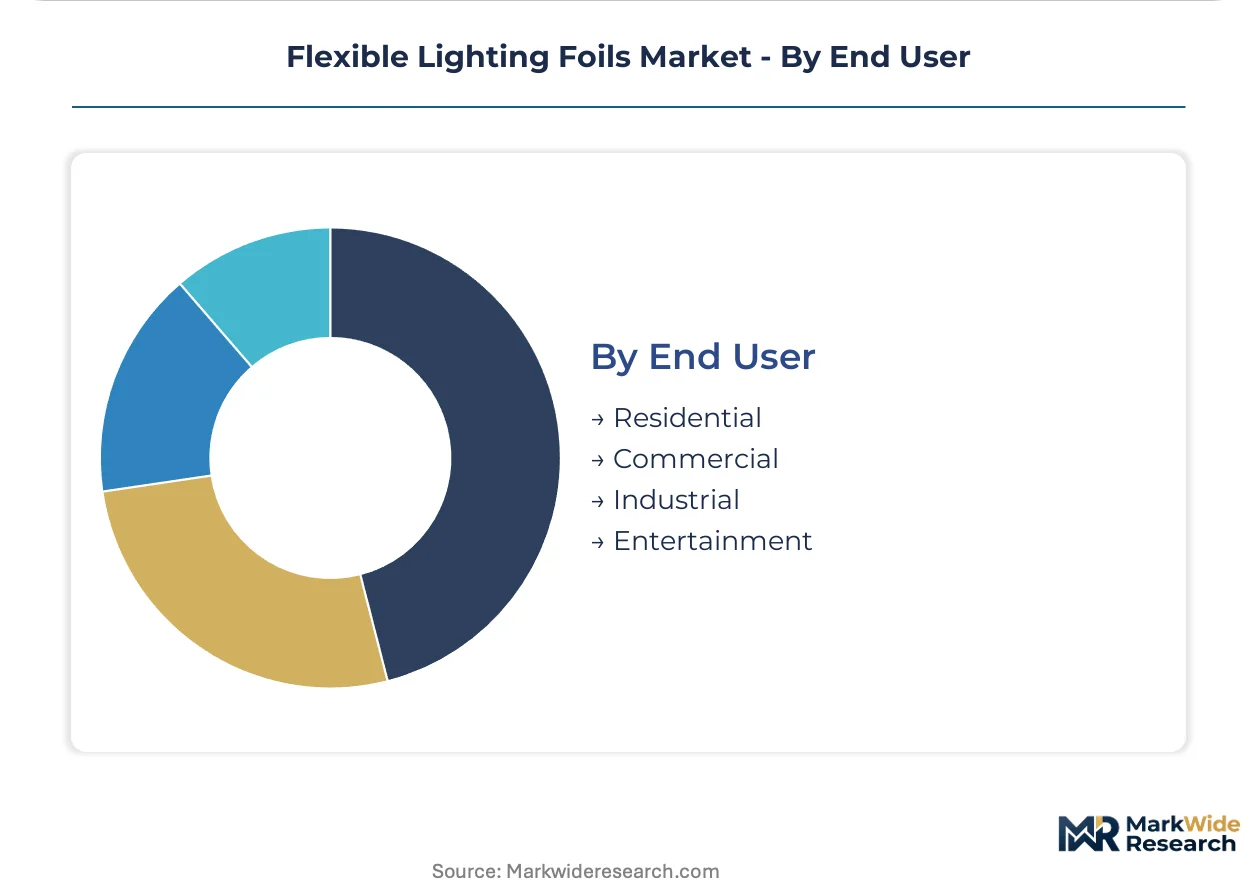
End User:
Customer-type segmentation reveals diverging procurement sophistication between specification-driven verticals and price-elastic replacement markets.
- Commercial:Office, hospitality, and retail fit-outs where lighting-as-a-service contracts and energy code compliance reshape purchasing criteria. JLL and CBRE facility management specifications in London and New York favor modular upgrade paths.
- Residential:Consumer-direct and contractor-channel sales for home improvement and new construction. Big-box retail concentration in Texas and Florida drives private-label sourcing.
- Industrial:Manufacturing, warehousing, and logistics facilities requiring high-bay and task illumination with minimal maintenance intervals. OSHA compliance and 50,000-hour lumen maintenance specifications dominate.
- Entertainment:Theaters, concert venues, and broadcast studios where color rendering and dynamic control override energy efficiency. IATSE union jurisdictions in California and New York influence equipment procurement.
Commercial captures the largest absolute spend, with Entertainment posting the steepest expansion trajectory on post-pandemic venue investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart engineering corridors anchor specification intensity for conformable illumination substrates as OEM integration programs compress qualification timelines across multiple jurisdictions.
Germany
KBA type-approval requirements harden automotive lighting standards while REACH authorization lists accelerate PVC phase-outs. ECHA substance evaluation protocols extend compliance timelines but raise R&D barriers for new entrants. Munich and Stuttgart engineering centers concentrate OEM specification pipelines for dashboard and door-panel ambient systems.
United States
FAA Part 25 certification pathways for aviation cabin retrofits create dual-certification demand alongside automotive programs. FDA 510(k) illumination subsystem approvals open medical device integration opportunities. Detroit and Austin clusters house Tier-1 suppliers qualifying silicone and polycarbonate substrates for thermal stability requirements.
Japan
METI energy efficiency standards push solid-state lighting adoption in commercial and transportation applications. JIS certification requirements govern optical uniformity thresholds for premium vehicle programs. Nagoya and Osaka manufacturing bases specialize in roll-to-roll micro-LED bonding automation for pixel-dense addressable zones.
China
MIIT automotive industry policies incentivize domestic supply chain localization for interior lighting modules. GB standards for vehicle lighting safety create parallel certification tracks alongside ECE regulations. Shenzhen and Shanghai production corridors scale LED-backed light sheet manufacturing for export and domestic OEM integration.
South Korea
MFDS medical device regulations intersect with automotive lighting standards for suppliers targeting dual-vertical certification. Seoul Capital Area concentration of display technology expertise transfers to flexible substrate development. Busan-Ulsan chemical complexes supply high-clarity polymer films for optical-grade applications.
Flexible Lighting Foils Market Vendor Landscape
Capacity expansion dominates the current landscape as substrate suppliers retrofit phthalate-dependent production lines toward silicone extrusion and polycarbonate film casting. The vendor base stratifies across three tiers: diversified chemical conglomerates with captive polymer supply, specialized lighting component fabricators, and emerging nanomaterial specialists. Strategic archetypes include vertically integrated compounders controlling formulation-to-substrate pipelines, Tier-2 module assemblers acquiring optical design capabilities, and carbon nanotube purifiers addressing 3D-formability requirements. M&A activity concentrates on optical design and control firmware acquisitions, while geographic expansion targets German and Japanese OEM engineering centers.
Within the European specification tier, Tridonic GmbH & Co KG and InovisCoat GmbH exemplify luminaire control heritage and coating specialization respectively. Canatu occupies a position among nanomaterial specialists leveraging carbon nanobased conductor integration. These three anchors represent divergent strategic postures: legacy lighting electronics, precision coating technology, and advanced conductor materials.
| Leading Market Players |
|---|
| Tridonic GmbH & Co KG |
| InovisCoat GmbH |
| Agfa-Gevaert Group |
| Flexbright Oy |
| Quad Industries |
| Canatu |
| 3M Company |
| DuPont |
| LG Display |
| Others |
Supply Flow & Price Mechanics
Bisphenol-A spot pricing volatility cascades through polycarbonate resin contracts into substrate cost structures, compressing margins for non-integrated compounders while rewarding suppliers with captive polymerization capacity in Germany and Michigan.
Pricing Analysis
Input-cost pass-through from silicone and polycarbonate feedstocks dominates pricing structures, with three-tier pricing stratification across automotive OEM, aviation certified, and retrofit consumer segments. Price differentiation hinges on REACH compliance certification and thermal stability grades, with automotive Tier-1 specifications commanding substantial premiums over architectural retrofit volumes. Pricing pressure stems from carbon nanotube conductor scarcity, which is transmitting East Asian purification bottlenecks into 3D-formable light engine cost bases. Consumer retrofit channels exhibit highest price sensitivity, while aviation and medical device verticals absorb premiums for dual-certification assurance.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit orchestrate hub-and-spoke fulfillment patterns for just-in-time automotive sequencing. Manufacturing concentration clusters in Germany, Japan, and China, with substrate production drawing from bisphenol-A, platinum-cured silicone, and single-walled carbon nanotube inputs. Single-source vulnerability concentrates in East Asian nanotube purification, where qualification timelines create 8-14 month procurement chokepoints. Distribution runs through Tier-1 automotive supplier consolidation points and lighting-as-a-service contract channels in commercial facilities management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive interior lighting programs function as a stable compounder, with OEM platform standardization generating recurring specification pipelines that outlast individual vehicle cycle volatility.
For Market Incumbents: Extend silicone extrusion capacity in Germany to capture REACH-driven PVC substitution demand, while deepening optical design firmware capabilities to defend module-level margin capture against component commoditization. Carbon nanotube conductor sourcing partnerships represent the critical lever for preserving 3D-formability differentiation.
For New Entrants and Emerging Players: Micro-LED die transfer automation offers a technology-first wedge into automotive pilot production lines, where roll-to-roll bonding equipment shortages create qualification windows. Medical device illumination subsystems present the most penetrable white-space target, with FDA 510(k) pathways less congested than automotive ECE R48 pipelines. Go-to-market execution should anchor on dual-certification bundling with polymer fire-resistance expertise.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating compounders possessing in-house silicone formulation and aviation certification heritage. Long-term viability favors suppliers with backward integration into polymer feedstocks, insulating margin structures from bisphenol-A volatility. Monitor REACH authorization list expansion velocity as the signal for accelerated PVC asset stranding and silicone substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Extrusion Capacity Expansion | REACH phthalate restrictions in Europe are accelerating PVC line obsolescence and raw-material repositioning. |
| Micro-LED Bonding Automation | Pilot-scale roll-to-roll lines in Nagoya and Stuttgart compress per-unit assembly costs for pixel-dense cabin zones. |
| Dual-Certification Investment | Concurrent FAA Part 25 and ECE R48 pathways open aviation and automotive volume pools for compliant suppliers. |
| Carbon Nanotube Purification Partnership | East Asian specialty chemical concentration creates qualification bottlenecks that sourcing agreements can mitigate. |
| Optical Design Firmware Acquisition | Module-level procurement consolidation favors suppliers integrating thermal management and vehicle-network protocol compliance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive Tier-1 procurement officers, polymer compounder R&D directors, aviation cabin engineering leads, and lighting-as-a-service contract managers with secondary validation against ECHA substance databases, KBA type-approval filings, FAA Part 25 certification registries, and customs trade flows for silicone and polycarbonate resin categories. Bottom-up segment builds and top-down macro anchoring were cross-checked for convergence.
Comparable-period anchoring tied projection trajectories to historical automotive production cycles and commercial construction retrofit waves across the analysis window. Segmentation dimensions modeled include product format, application vertical, material substrate, thermal stability grade, and end-user procurement sophistication. CAGRs were derived from installed base turnover rates and specification intensity indices, with inputs from solid-state efficiency thresholds and polymer exemption list evolution.
The model holds under stable REACH authorization timelines and OEM platform standardization continuity; deviation in ECHA acceleration schedules or carbon nanotube supply disruptions would shift volume and value trajectories. Forecasts reflect documented assumptions around regulatory phase-in rates and substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
North America Smart Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
UAE Smart Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Illuminating Signs Market
Lighting
Dimmers Market
Lighting
Europe Decorative Lighting Market
Lighting
Wireless Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Street and Roadway Lighting Market
Lighting
Display Light Control Film Market
Lighting
US Indoor LED Lighting Market
Lighting
Residential Lighting Fixtures Market