
 Europe Photoresist and Photoresist Ancillaries Market | 2026-2036
Europe Photoresist and Photoresist Ancillaries Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Photoresist and Photoresist Ancillaries Market Intelligence
The EU F-Gas Regulation is recalibrating the cost-of-entry calculus for fluorinated solvent-based photoresist strippers and cleaners. MERCK KGaA leverages its integrated electronic materials platform to sustain supply security across EUV and DUV chemistries. TOKYO OHKA KOGYO CO., LTD anchors its European position through localized blending operations and foundry-qualified product portfolios. Fujifilm Corporation differentiates via proprietary polymer architectures optimized for sub-7nm resolution requirements.
Photoresist and photoresist ancillaries comprise light-sensitive polymer formulations and their complementary process chemicals, typically spun onto silicon wafers at thicknesses between 50 nanometers and several micrometers, then selectively solubilized through patterned UV or EUV exposure to create etched circuit geometries. Positive photoresist dominates volume flows in leading-edge semiconductor fabrication where EUV lithography dissolves exposed regions with alkaline developers. Photoresist ancillaries capture disproportionate margin pools as anti-reflective coatings and edge bead removers grow in complexity alongside multi-patterning schemes.
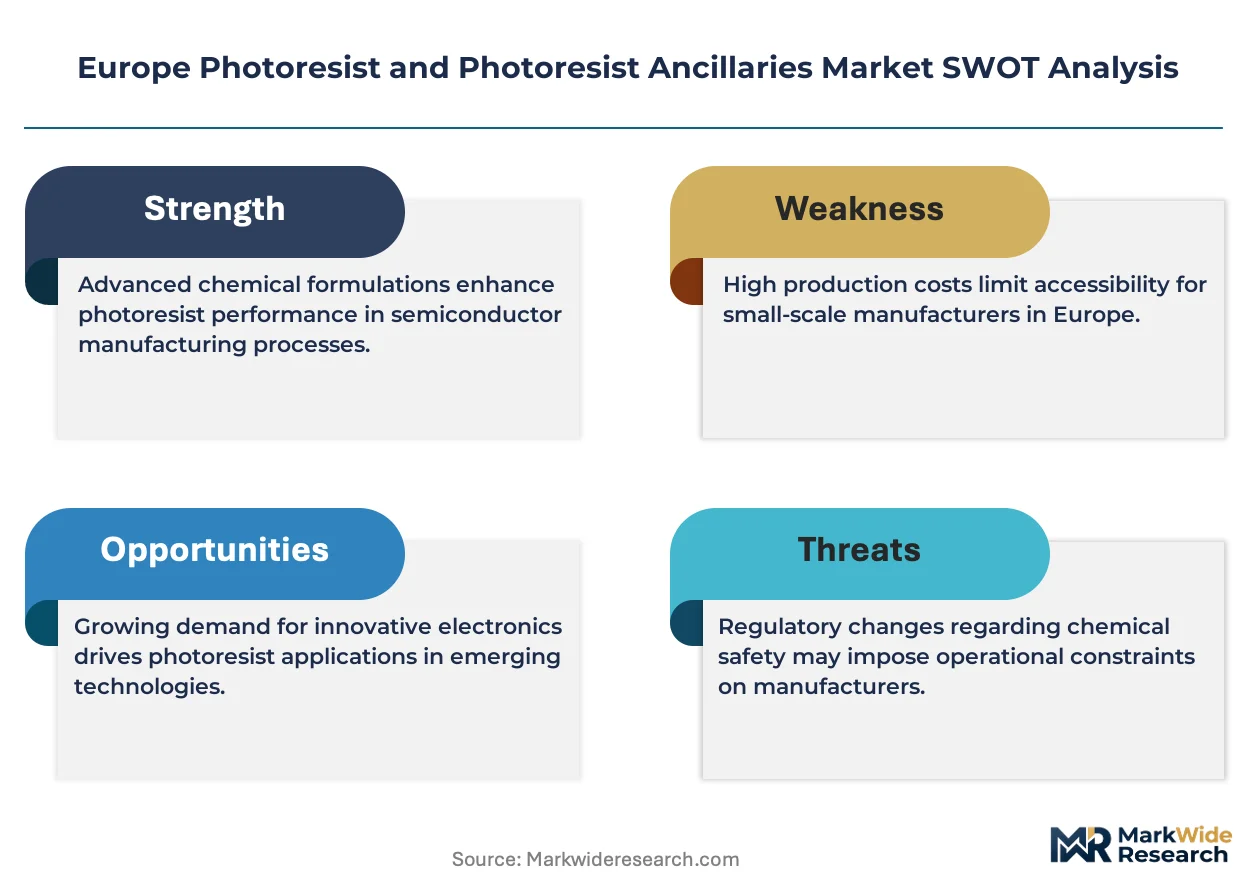
EMA chemical substance evaluations, REACH authorization procedures, and the EU Green Deal chemicals strategy collectively constrain permissible monomer chemistries and solvent profiles in European formulation plants. ECHA's expanding candidate list of substances of very high concern threatens legacy novolac resin feedstocks unless suppliers complete substitution roadmaps. Foundries and material vendors must monitor regulatory divergence between EU chemical safety thresholds and customer fab sustainability scorecards.
Market Dynamics
EUV lithography node transitions are multiplying photoresist layers per wafer, creating a structural pull for advanced formulations across the Franco-German semiconductor corridor. This technology forcing function concentrates procurement power among advanced logic foundries while tightening regulatory scrutiny on chemical inputs.
Growth Catalysts
- Node Transition Intensity:Sub-7nm EUV adoption by logic foundries in Germany and France is expanding photoresist consumption per wafer as multi-patterning schemes proliferate.
- REACH Registration Momentum:Chemical substance evaluations under ECHA are accelerating substitution of legacy novolac resins, opening formulation refresh cycles for compliant suppliers.
- Cluster Proximity Effects:Dresden-Grenoble corridor investments are localizing demand density, reducing logistics friction for just-in-time photoresist delivery to fabs.
Market Restraints
- Feedstock Concentration:Specialty fluorinated monomers for EUV resists depend on limited European polymerization capacity, exposing formulators to input bottlenecks.
- EUV Throughput Limitations:Source power constraints at 13.5nm wavelength extend exposure times, capping wafer-per-hour economics and dampening volume pull-through.
- F-Gas Cost Recalibration:The EU F-Gas Regulation is elevating solvent recovery costs for fluorinated photoresist strippers, compressing margin pools for cleaning chemistry suppliers.
Strategic Opportunities
- Eastern European Fab Expansion:Greenfield semiconductor investments in Poland and the Czech Republic are creating new demand nodes beyond the established Franco-German axis.
- CSRD-Driven Transparency:Corporate Sustainability Reporting Directive mandates are rewarding suppliers with verified supply chain carbon footprints, favoring localized European blending operations.
- Anti-Reflective Coating Complexity:Multi-layer EUV stacks are expanding ancillaries margin capture as bottom anti-reflective coatings grow critical for pattern fidelity at sub-5nm.
Industry Challenges
- EUV Resist Chemist Scarcity:Formulation expertise combining photochemistry with polymer physics is concentrated among retiring specialists, constraining R&D velocity for next-generation platforms.
- Foundry Qualification Timelines:Multi-year product validation cycles at TSMC and Samsung analogs in Europe lock out new entrants, entrenching incumbents despite performance gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Photoresist and Photoresist Ancillaries Market |
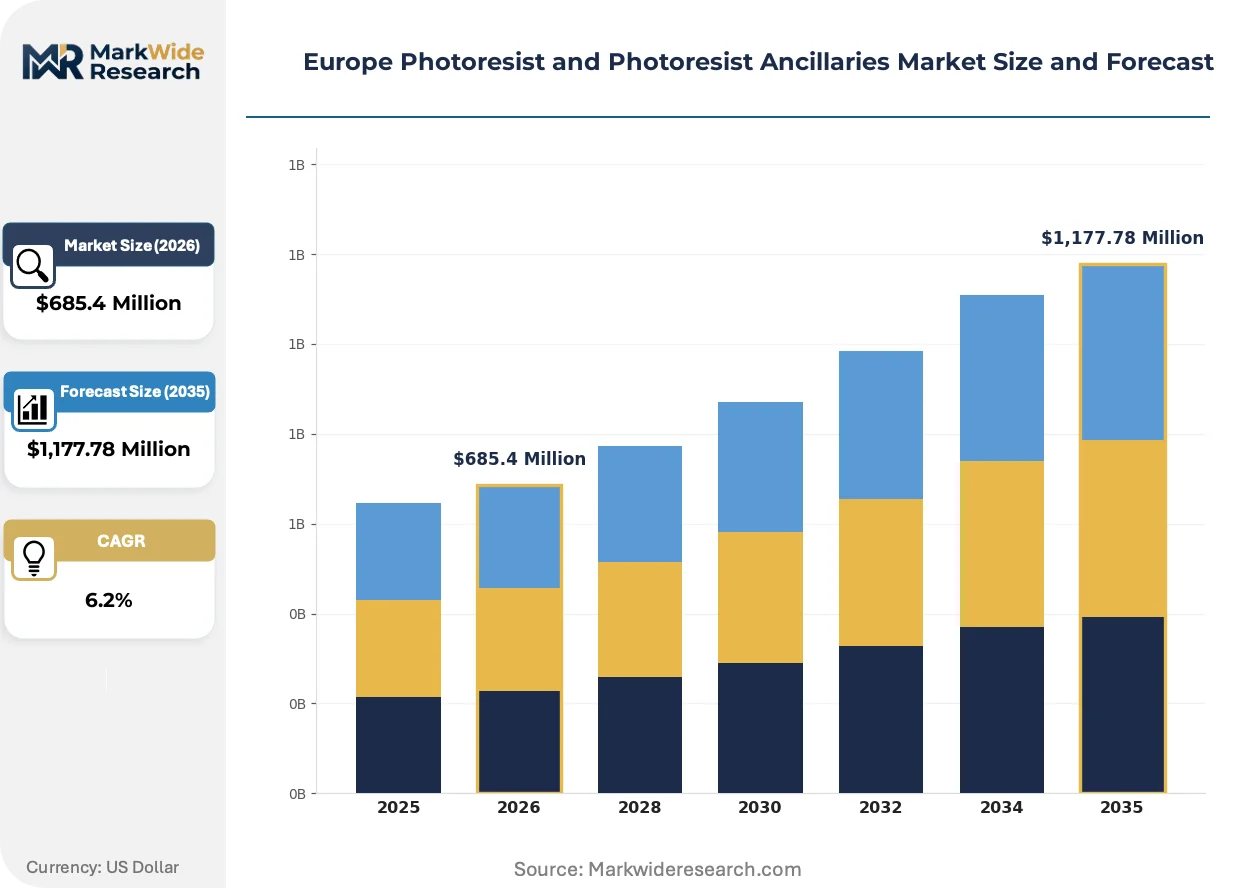
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Specialty Photoresist, Photoresist Ancillaries Application: Semiconductor Fabrication, Display Technologies, Microelectronics, PCB Manufacturing End User: OEMs, Foundries, Electronic Manufacturers, Research Institutions Technology: UV Lithography, EUV Lithography, Nanoimprint Lithography, Traditional Lithography |
| Companies Covered | MERCK KGaA, Sumitomo Chemical Co., Ltd., TOKYO OHKA KOGYO CO., LTD, Micro Resist Technology GmbH, ALLRESIST GmbH, Shin-Etsu Chemical Co., Ltd., DJ MicroLaminates, Inc., DuPont de Nemours, Inc., Fujifilm Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Photoresist and Photoresist Ancillaries Market Strategic Shifts & Innovations
Metal oxide photoresist platforms are disrupting molecular glass architectures as resolution demands outpace organic polymer capabilities. Formulation science, regulatory chemistry, and procurement engineering are converging to reshape competitive positioning.
Metal oxide resists incorporating tin-oxo clusters are overtaking conventional chemically amplified platforms in EUV sensitivity benchmarks. Leading-edge foundries in Germany are qualifying these formulations for 2nm-class production ramps. The technology is overtaking incumbent market share by enabling single-exposure patterning where organic resists require costly double-patterning flows.
REACH authorization procedures are tightening monomer disclosure thresholds for non-EU suppliers seeking European formulation rights. ECHA's expanding candidate list of substances of very high concern is forcing substitution roadmaps for legacy cresol-novolac feedstocks. Photoresist vendors with captive European polymerization assets are responding by accelerating in-house resin production to preserve formulation autonomy.
Long-term supply agreements are displacing spot procurement as foundries seek chemical supply security amid geopolitical fragmentation. Direct vendor-managed inventory programs now dominate advanced logic procurement in Dresden and Grenoble, compressing distributor roles. This behavioral shift is most visible in Germany, where foundries are consolidating supplier panels to three qualified photoresist sources per technology node.
Europe Photoresist and Photoresist Ancillaries Market Segmentation
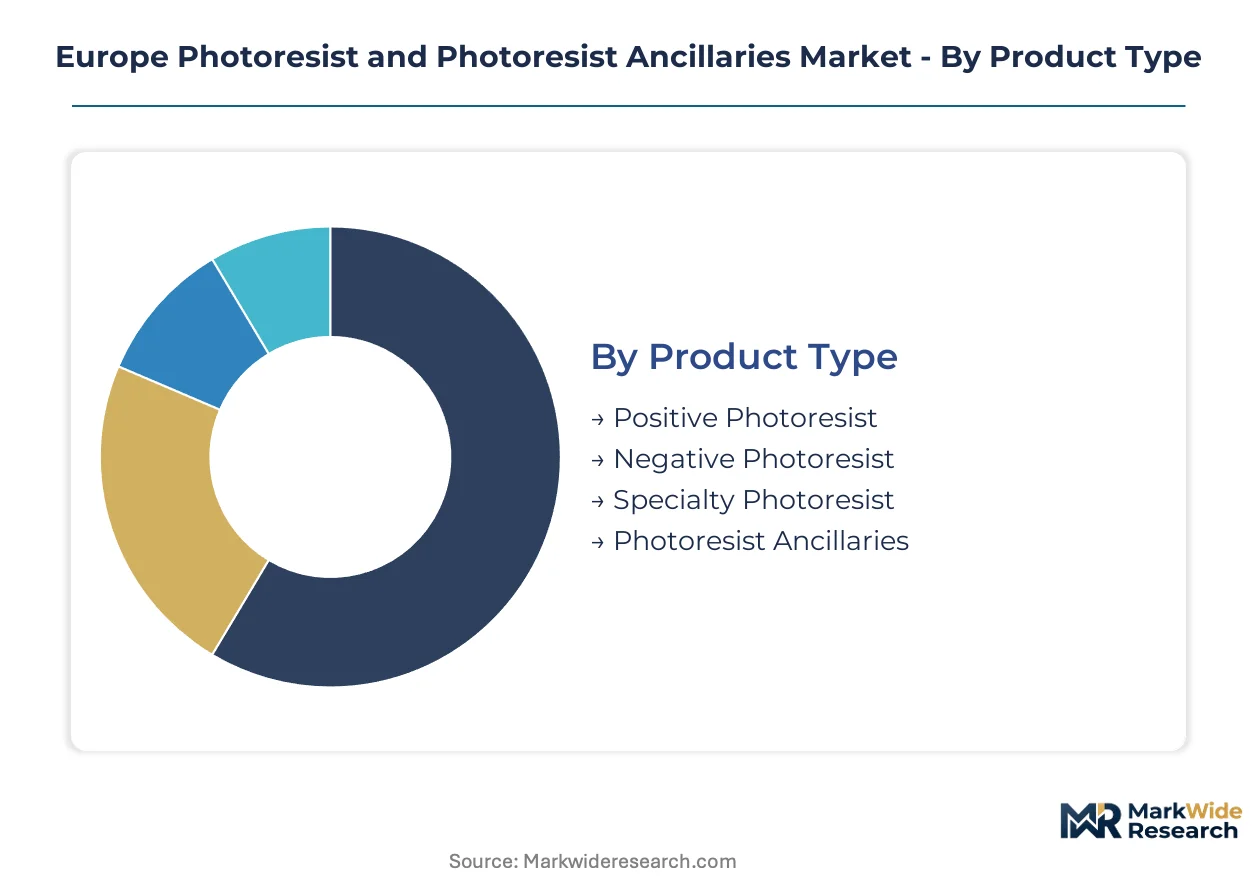
Photoresist segmentation in Europe tracks divergent supply economics across lithography generations. Formulation chemistry and foundry process requirements create distinct margin pools that reshape procurement patterns.
Product Type:
Supply concentration in European photoresist manufacturing favors formulators with captive polymerization assets and REACH-compliant resin supply chains.
- Positive Photoresist:Chemically amplified formulations dissolve exposed regions in alkaline developers, dominating EUV and DUV layers at advanced logic foundries in Dresden. Procurement concentrates among three qualified suppliers per node as foundries consolidate panels for supply security.
- Photoresist Ancillaries:Anti-reflective coatings, edge bead removers, and developers capture disproportionate margins as multi-patterning schemes multiply process steps. Demand intensifies in Grenoble's MEMS and imaging sensor fabs where layer complexity exceeds mainstream logic.
- Negative Photoresist:Cross-linking formulations polymerize exposed regions, serving legacy analog and power semiconductor applications in older European fabs.
- Specialty Photoresist:Metal oxide and molecular glass platforms target sub-7nm resolution requirements at leading-edge EUV installations.
Today's leader: Positive Photoresist. Tomorrow's challenger: Photoresist Ancillaries.
Application:
Cost tier stratification separates premium semiconductor formulations from commodity display and PCB chemistries.
- Semiconductor Fabrication:Logic and memory wafer processing commands formulation precision at molecular tolerances. German foundries driving EUV node transitions generate the steepest expansion trajectory for advanced positive-tone and metal oxide resists.
- Display Technologies:Large-area coating requirements for OLED and LCD manufacturing favor high-throughput negative-tone formulations with relaxed resolution specifications.
- Microelectronics:Sensor and MEMS production in France and Germany utilizes mid-tier DUV resists with specialized thickness profiles.
- PCB Manufacturing:Printed circuit board lithography operates on cost-optimized dry film and liquid resists with minimal regulatory complexity.
Volume concentrates in Semiconductor Fabrication. Margin expansion favors Display Technologies.
End User:
Customer type determines procurement modality, with foundries enforcing vendor-managed inventory while OEMs retain spot purchasing flexibility.
- Foundries:Dedicated semiconductor manufacturing facilities in Germany and France negotiate multi-year supply agreements with direct inventory management. TSMC analogs in Dresden consolidate to three qualified photoresist sources per technology node.
- OEMs:Integrated device manufacturers maintain broader supplier panels and spot procurement for non-critical layers.
- Electronic Manufacturers:Assembly and packaging operations consume ancillaries for substrate patterning with standardized specifications.
- Research Institutions:IMEC in Belgium and Fraunhofer institutes in Germany pilot next-generation formulations before commercial qualification.
Procurement power centers on Foundries. Technology validation depends on Research Institutions.
Technology:
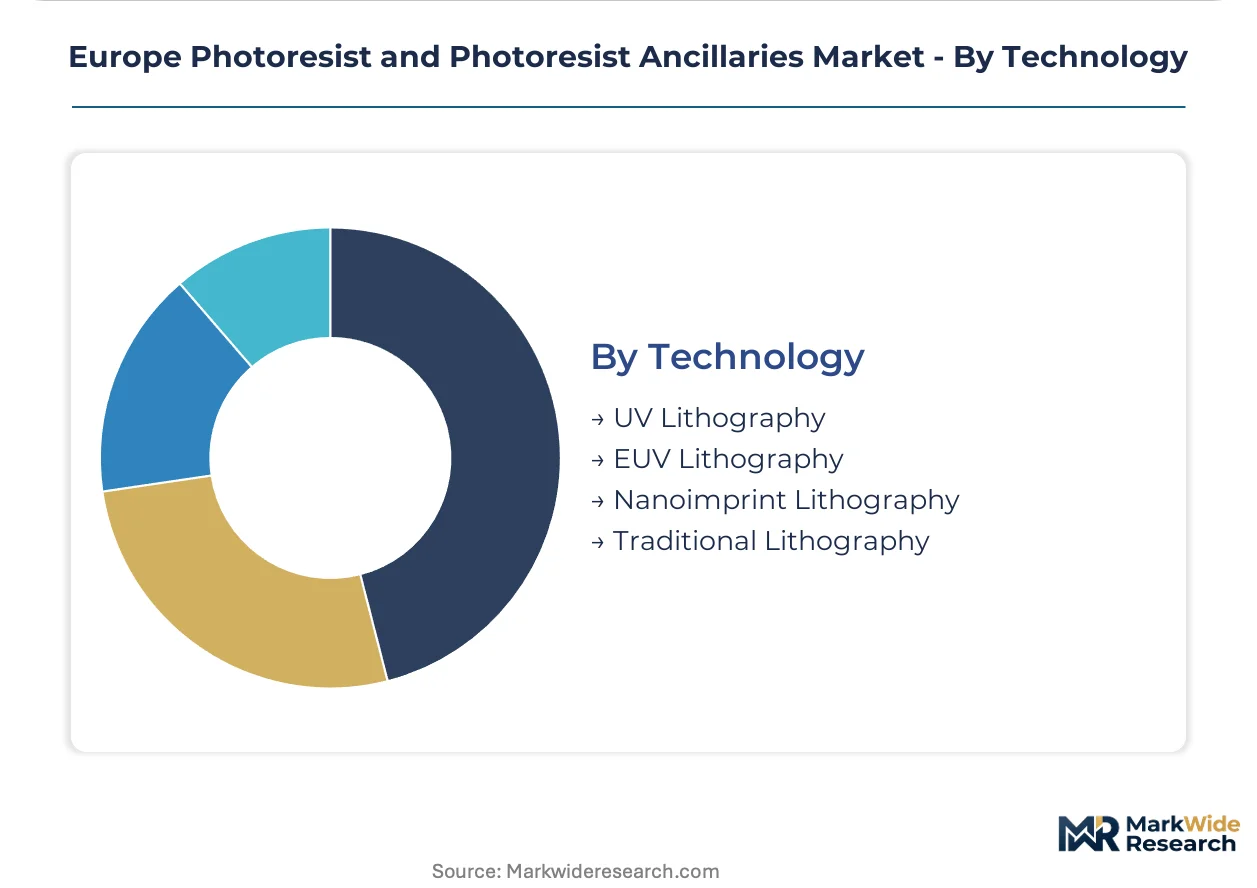
Maturity gradients separate established UV platforms from emerging nanoimprint alternatives, with EUV commanding premium formulation economics.
- EUV Lithography:13.5nm wavelength exposure systems at German logic foundries multiply photoresist layers per wafer through multi-patterning. Metal oxide resists incorporating tin-oxo clusters enable single-exposure patterning where organic platforms require double-patterning flows.
- UV Lithography:193nm and 248nm DUV systems continue serving mature nodes and memory applications across the Franco-German corridor.
- Nanoimprint Lithography:Mechanical patterning alternatives target display and storage applications with cost advantages at relaxed resolution nodes.
- Traditional Lithography:G-line and I-line mercury lamp systems persist in analog, power, and automotive semiconductor fabrication.
Investment flows toward EUV Lithography. Cost-sensitive volume remains with Traditional Lithography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and polymer scientists concentrate in the Franco-German corridor, anchoring Europe's photoresist technical workforce. Dresden and Grenoble host the densest clusters of EUV lithography expertise outside Asia. This talent geography shapes procurement patterns and supplier localization decisions.
Germany
Dresden's Silicon Saxony cluster drives EUV photoresist demand through advanced logic foundry expansions. The F-Gas Regulation elevates compliance costs for fluorinated solvent-based strippers, favoring suppliers with recovery infrastructure. Bavaria's chemical parks near Munich host localized blending operations serving just-in-time fab requirements.
France
Grenoble's semiconductor ecosystem generates ancillaries demand for MEMS and imaging sensor fabrication. ANSM chemical oversight intersects with REACH obligations, tightening formulation disclosure for non-EU suppliers. The Auvergne-Rhône-Alpes region anchors CEA-Leti research partnerships that pre-qualify next-generation resist platforms.
Netherlands
ASML's Veldhoven headquarters creates indirect photoresist pull through lithography system placements across European fabs. The Dutch National Institute for Public Health and the Environment enforces REACH implementation with stringent substance evaluation timelines. Eindhoven's Brainport region concentrates equipment-chemistry integration expertise.
Belgium
IMEC's Leuven research campus validates EUV resist formulations before commercial foundry qualification. The country's federal chemical regulator enforces ECHA candidate list compliance for legacy novolac feedstocks. Flanders' nanotechnology cluster attracts formulation pilots from Japanese and Korean suppliers.
Poland
Emerging fab investments in Wrocław and Warsaw create new demand nodes beyond the established corridor. The country's chemical authority implements REACH registration requirements for imported photoresist intermediates. Lower Silesia's industrial zones offer cost-competitive blending locations for EU-facing suppliers.
Europe Photoresist and Photoresist Ancillaries Market Key Industry Players
The competitive structure tilts toward integrated electronic materials platforms with captive polymerization assets. Three qualified suppliers per technology node dominate procurement panels at advanced foundries, compressing opportunities for unqualified entrants. Strategic archetypes include diversified chemical conglomerates, specialized photoresist pure-plays, and regional formulation specialists. Capacity expansion and supply security partnerships constitute the dominant competitive moves as fabs consolidate vendor relationships.
Within the diversified chemical tier, MERCK KGaA and DuPont de Nemours, Inc. exemplify platform breadth spanning EUV and DUV chemistries. TOKYO OHKA KOGYO CO., LTD represents the specialized pure-play archetype with foundry-qualified portfolios. These three anchors demonstrate how geographic origin and corporate structure shape positioning: German KGaA, American Inc., and Japanese Co., Ltd. formats each carry distinct stakeholder governance implications for long-term supply agreements.
| Leading Market Players |
|---|
| MERCK KGaA |
| Sumitomo Chemical Co., Ltd. |
| TOKYO OHKA KOGYO CO., LTD |
| Micro Resist Technology GmbH |
| ALLRESIST GmbH |
| Shin-Etsu Chemical Co., Ltd. |
| DJ MicroLaminates, Inc. |
| DuPont de Nemours, Inc. |
| Fujifilm Corporation |
| Others |
Cost & Logistics Intelligence
Fluorinated solvent feedstock indices cascade through European photoresist formulation tiers, compressing margin pools for non-integrated suppliers while rewarding captive polymerization assets with pricing autonomy against REACH disclosure obligations.
Pricing Analysis
Photoresist procurement splits between bundled vendor-managed inventory programs and unbundled spot transactions. Three-tier pricing structure across premium EUV formulations, standard DUV chemistries, and economy legacy resists reflects qualification status and layer criticality. Cost compression in fluorinated strippers intensifies because F-Gas Regulation recovery mandates elevate solvent handling expenses. Foundries exhibit lowest price sensitivity for EUV layers where single-source qualification locks in supply security, while PCB manufacturers drive hardest bargain negotiations on commodity dry film resists.
Supply Chain Analysis
Direct-to-foundry channels handle just-in-time delivery requirements for Dresden and Grenoble fabs, displacing traditional distributor intermediaries. Specialty fluorinated monomer supply concentrates in Japan, Germany, and the United States, anchoring formulation autonomy to geographic polymerization assets. European photoresist production draws from cresol-novolac resins, tin-oxo cluster precursors, and high-purity solvent feedstocks. Single-source vulnerability in EUV-grade monomer supply threatens continuity for non-captive formulators. Distribution runs through qualified supplier panels capped at three sources per technology node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines compound formulation complexity into sustained demand for compliant resin supply chains, with ECHA's expanding SVHC candidate list forcing substitution investments that favor incumbent technical resources.
For Market Incumbents: Deepen captive polymerization capacity in Bavarian chemical parks to preserve formulation autonomy against ECHA disclosure thresholds. Accelerate metal oxide resist qualification timelines to defend position against molecular glass substitution threats. Consolidate long-term supply agreements with Dresden foundries before Eastern European fab investments mature alternative procurement relationships. For New Entrants and Emerging Players: Enter via Poland and Czech Republic greenfield semiconductor investments, where supplier panels remain unformed and qualification timelines compress against Franco-German incumbency. Target MEMS and imaging sensor ancillaries in Grenoble's CEA-Leti ecosystem, where layer complexity exceeds mainstream logic penetration. Pursue joint development partnerships with IMEC Leuven to secure pre-qualification validation before commercial foundry engagement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized photoresist pure-plays possessing foundry-qualified EUV portfolios and European blending operations. Five-to-ten-year viability hinges on metal oxide platform transitions and REACH-compliant resin substitution completion. Monitor ECHA authorization grant rates for legacy novolac feedstocks as inflection indicator for formulation refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Polymerization | Captive production of cresol-novolac and fluorinated monomers insulates margins from ECHA supply disruptions. |
| EUV Metal Oxide Qualification Acceleration | Single-exposure patterning capability at German foundries displaces double-patterning organic resist volumes. |
| Vendor-Managed Inventory Expansion | Direct fab inventory programs in Dresden consolidate procurement panels to three qualified sources per node. |
| Eastern European Blending Localization | Poland and Czech Republic facilities reduce logistics friction for emerging fab demand beyond Franco-German corridor. |
| REACH Substitution Roadmap Completion | SVHC-compliant resin portfolios preserve European formulation rights against ECHA candidate list expansion. |
Research Approach
Coverage spans Germany, France, Netherlands, Belgium, and Poland, with primary inputs from each market cluster combining interviews with photoresist formulation chemists, foundry procurement directors, ECHA regulatory affairs specialists, and polymer plant managers with secondary validation. Secondary sources include REACH registration databases, ECHA substance evaluation dossiers, SEC 10-K filings from electronic materials suppliers, and customs trade data for fluorinated monomer flows. Bottom-up wafer demand modeling triangulates against top-down chemical consumption estimates from Cefic sector reports.
Granularity extends to product type, application tier, end-user procurement modality, and lithography technology node across the projection horizon. Segmentation dimensions encompass formulation chemistry, layer criticality, and foundry qualification status. CAGRs derive from node transition intensity curves and multi-patterning layer multiplication factors. Forecast inputs incorporate EUV source power roadmaps from ASML and REACH authorization timelines from ECHA.
The model holds under stable EUV adoption trajectories and REACH implementation schedules; deviation in F-Gas Regulation enforcement intensity or metal oxide resist qualification delays would shift volume and value outputs. Forecasts reflect documented assumptions regarding foundry capex commitments and polymerization capacity expansion plans. Periodic stress-testing of base assumptions is recommended against ECHA regulatory announcements and lithography system placement disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Chip Melting Furnace Market