
 Silicon on Insulator Market | 2026-2036
Silicon on Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon on Insulator Market Intelligence
CE marking under the EU Medical Device Regulation is collapsing the supplier pool for SOI wafers bound for implantable electronics. SOITEC leverages its Smart Cut technology to sustain leadership in 300mm engineered substrates. GlobalFoundries anchors its differentiation through FD-SOI process nodes at its Dresden facility. Tower Semiconductor competes via specialized RF-SOI foundry services for 5G front-end modules.
Silicon on Insulator refers to a layered semiconductor structure comprising a thin silicon film atop an insulating oxide layer, typically silicon dioxide, bonded to a bulk silicon handle wafer with film thicknesses ranging from sub-50nm to several micrometers depending on application. This architecture eliminates latch-up, reduces parasitic capacitance, and enables lower power consumption for high-frequency and radiation-hardened circuits. SOI wafers command premium positioning as substrate platforms for advanced nodes, while CMOS Technology dominates volume production and RF Technology captures the fastest expansion from 5G infrastructure deployment. The Automotive application segment is deepening penetration as electric vehicles integrate more SOI-based power management and sensor chips.
FDA clearance pathways for Class III medical devices incorporating SOI substrates create compliance barriers that filter non-qualified wafer vendors. REACH restrictions on semiconductor manufacturing chemicals and the EU F-Gas Regulation constrain etching processes used in SOI fabrication, pushing fabs toward alternative chemistries. The EU AI Act's hardware transparency requirements will soon extend to chip provenance documentation. Stakeholders must monitor how subsidy disbursement timelines under competing national semiconductor programs reshape foundry capacity allocation across substrate suppliers.
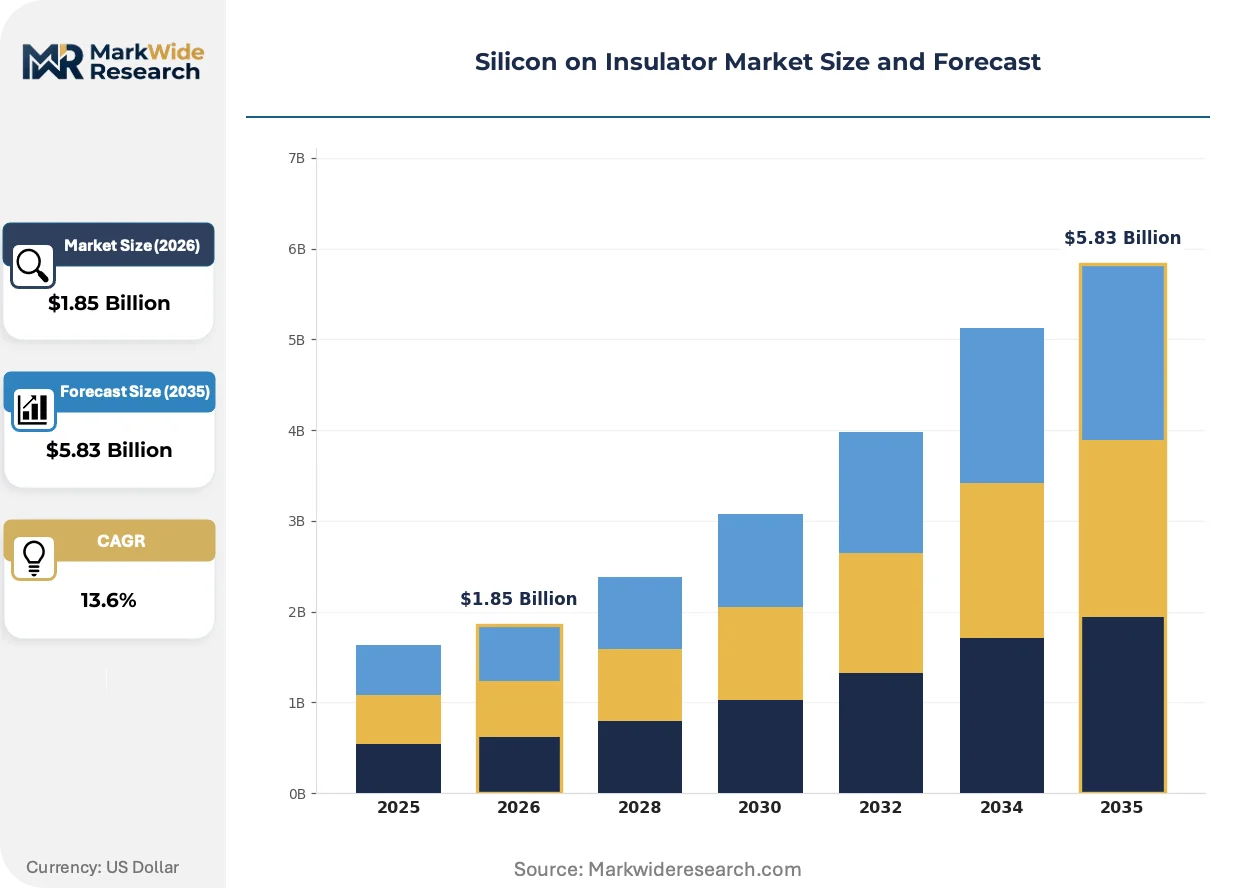
Market Dynamics
FD-SOI process maturation at 22nm and 12nm nodes is compressing the cost gap with bulk CMOS, pulling automotive and IoT designers away from planar alternatives and reshaping foundry capacity allocation across substrate suppliers.
Growth Catalysts
- EU Chips Act disbursements:Subsidy frameworks in Germany, France, and Spain are accelerating 300mm wafer fab construction, directly expanding SOI substrate pull-through.
- Electric vehicle power electronics:Silicon carbide gate drivers and battery management systems are integrating SOI-based isolation chips for higher voltage tolerance.
- 5G mmWave densification:Base station and handset front-end modules are consuming RF-SOI wafers at volumes that outpace legacy GaAs alternatives.
Market Restraints
- Helium supply concentration:SOI manufacturing depends on helium for wafer cooling during Smart Cut layer transfer, with sourcing concentrated in Qatar and the US federal reserve.
- 300mm substrate oligopoly:Engineered substrate supply rests on fewer than five qualified vendors, creating single-source exposure for advanced node ramps.
- REACH chemical restrictions:ECHA classifications on fluorinated etchants are forcing process requalification and yield compression during chemistry transitions.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic fab incentives are creating first-mover substrate qualification opportunities as foundry construction begins in Gujarat.
- Photonics-electronics convergence:Silicon photonics transceivers are adopting SOI platforms for co-packaged optical interconnects in data centers.
- EU MDR implantable device pathways:CE marking requirements for active implantables are filtering wafer vendors and creating premium positioning for qualified substrate suppliers.
Industry Challenges
- Thin-film metrology talent scarcity:Sub-50nm silicon layer thickness control requires specialized ellipsometry and X-ray reflectometry expertise that outstrips current training pipelines.
- Cross-fab process portability:SOI device performance varies with handle wafer resistivity and buried oxide quality, complicating multi-source manufacturing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon on Insulator Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.83 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Silicon, SOI Wafers, SOI Circuits, SOI Modules Application: Consumer Electronics, Telecommunications, Automotive, Aerospace Technology: Bipolar Technology, CMOS Technology, RF Technology, MEMS Technology End User: Semiconductor Manufacturers, Research Institutions, Electronics Producers, Government Agencies |
| Companies Covered | SUMCO Corporation, GlobalFoundries, SOITEC, Tower Semiconductor, STMicroelectronics, Shin-Etsu Chemical Co., Ltd., Shanghai Simgui Technology Co., Ltd., Silicon Valley Microelectronics, Inc., GlobalWafers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon on Insulator Market Strategic Shifts & Innovations
Wafer-level engineering is migrating from substrate commoditization toward application-specific customization, with buried oxide thickness and silicon film strain becoming tunable design parameters rather than fixed specifications.
FD-SOI with backside power delivery is supplanting FinFET architectures for designs below 7nm where power efficiency outweighs peak performance. Automotive SoC designers at European and Japanese OEMs are adopting these nodes for zonal controllers. The shift is compressing the addressable market for bulk silicon at advanced nodes while expanding SOI's viable performance envelope.
REACH restrictions on per- and polyfluoroalkyl substances are forcing etching chemistry transitions at SOI fabs in Germany and France. ECHA's 2023 PFAS restriction proposals are accelerating plasma dry etch adoption and wet bench reconfiguration. RF-SOI lines at Dresden and Crolles facilities are absorbing the highest compliance costs due to their reliance on legacy wet processes.
Automotive chip buyers are consolidating their approved vendor lists and demanding substrate provenance documentation extending to polysilicon source. Tier-1 suppliers in Germany and South Korea are requiring lot-level traceability for functional safety certification. This behavioral shift is favoring vertically integrated substrate suppliers with captive polysilicon and crystal growth operations over merchant wafer merchants.
Silicon on Insulator Market Segmentation
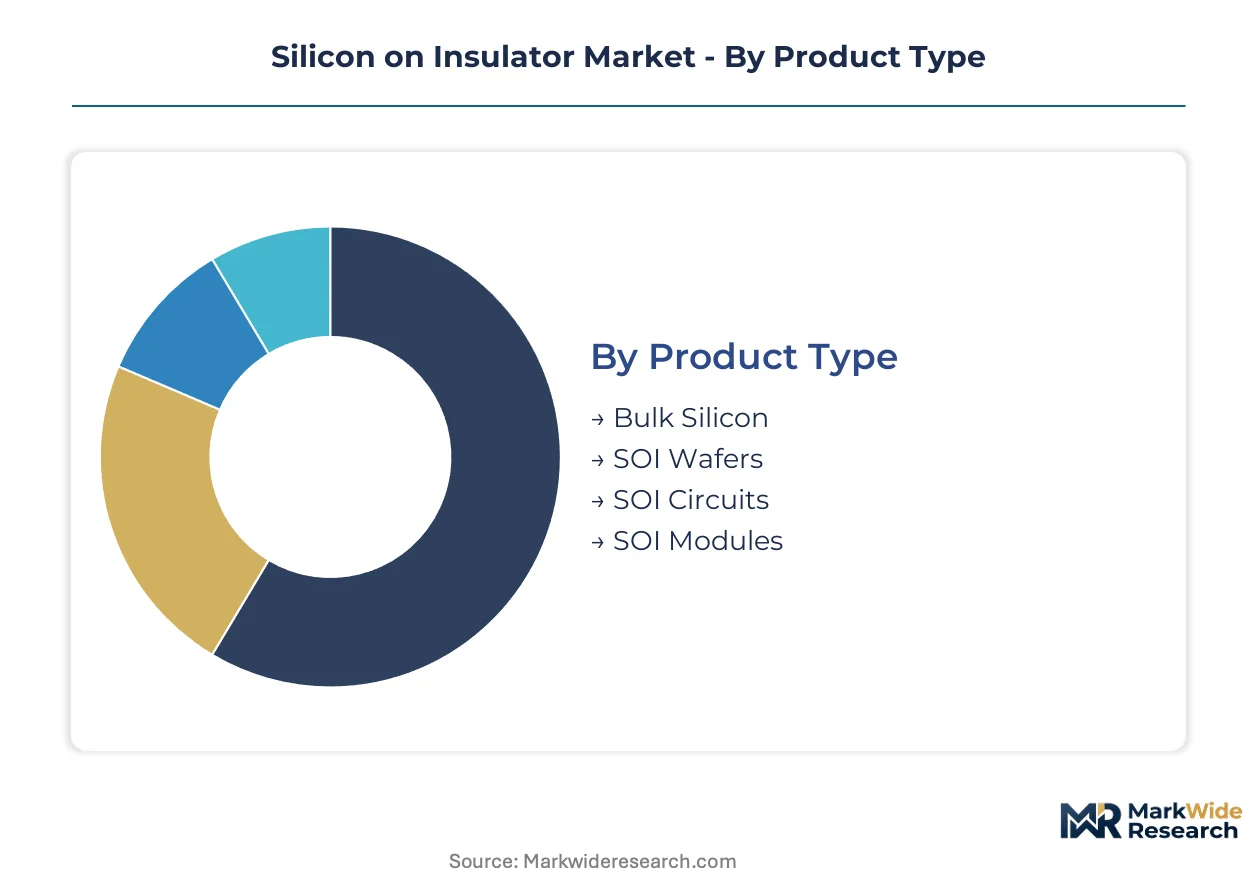
SOI market segmentation reveals distinct procurement patterns across substrate types and integration levels. Wafer-level products dominate volume trade, while module-level solutions concentrate in defense and medical device supply chains with stringent provenance requirements.
Product Type:
Export-led segments ship predominantly to East Asian fabrication clusters, whereas domestic consumption concentrates in European automotive and defense programs.
- SOI Wafers:Engineered substrates with tunable buried oxide thickness and silicon film specifications serve as the foundational platform for advanced node manufacturing. Demand concentrates in Taiwan and South Korea for leading-edge logic and memory foundry ramps, with Smart Cut technology enabling layer transfer precision that bulk alternatives cannot match.
- SOI Circuits:Pre-processed die and integrated assemblies reduce customer design cycles for radiation-hardened and power-efficient applications. European automotive OEMs and Japanese industrial equipment makers are pulling these through qualified supply chains to shorten time-to-market for zonal controllers and sensor hubs.
- SOI Modules:Complete subsystem packages with thermal and electrical integration for aerospace and medical implantables.
- Bulk Silicon:Commodity substrate alternative for cost-sensitive designs at mature nodes, primarily serving domestic appliance and industrial control markets.
SOI Wafers holds the largest share; momentum sits with SOI Circuits.
Application:
Cost tier stratification separates high-reliability aerospace programs from consumer electronics with compressed qualification cycles.
- Automotive:Electric vehicle power electronics and battery management systems drive isolation chip requirements for 800V architectures. German and Japanese OEMs are consolidating approved vendor lists and demanding lot-level traceability from polysilicon source through wafer processing for functional safety certification.
- Telecommunications:5G mmWave infrastructure and handset front-end modules consume RF-SOI at volumes displacing legacy GaAs alternatives. Tower Semiconductor's foundry services in Israel and GlobalFoundries' Dresden facility anchor supply for European and North American base station deployments.
- Consumer Electronics:Wearables and mobile devices prioritize FD-SOI for power efficiency at mainstream nodes.
- Aerospace:Radiation-hardened SOI for satellite and avionics applications with extended qualification timelines and captive supply arrangements.
Automotive commands premium pricing; telecommunications is expanding most quickly.
Technology:
Volume concentration favors CMOS for mainstream production, while margin capture sits with specialized RF and MEMS variants.
- CMOS Technology:Dominant planar and FinFET-compatible processing for digital logic, memory, and mixed-signal designs. FD-SOI maturation at 22nm and 12nm nodes is compressing cost gaps with bulk alternatives and pulling automotive and IoT designers from planar silicon in Germany, France, and Japan.
- RF Technology:Specialized process modules for high-frequency performance with reduced parasitic capacitance and substrate noise. 5G densification in South Korea, the United States, and China is driving front-end module consumption that outstocks GaAs capacity expansion.
- MEMS Technology:Micromechanical structures integrated with SOI substrates for sensors and actuators in automotive and industrial applications.
- Bipolar Technology:Legacy high-voltage and analog designs for industrial power and automotive traction systems.
CMOS Technology holds the largest share; RF Technology is gaining share fastest.
End User:
Customer type determines contract structure, with semiconductor manufacturers driving volume and government agencies mandating domestic sourcing.
- Semiconductor Manufacturers:Integrated device manufacturers and foundries purchasing wafers for captive processing or customer programs. Procurement is consolidating around fewer than five qualified 300mm substrate vendors, creating single-source exposure for advanced node ramps in Taiwan, South Korea, and the United States.
- Electronics Producers:System houses and module assemblers sourcing processed die and packaged components. Tier-1 automotive suppliers in Germany and South Korea are requiring substrate provenance documentation extending to polysilicon source for CE marking under EU MDR and functional safety certification.
- Research Institutions:Universities and national laboratories purchasing small volumes for process development and prototype validation.
- Government Agencies:Defense and space programs with mandated domestic sourcing and extended qualification protocols.
Semiconductor Manufacturers holds the largest share; Electronics Producers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and foundry operators concentrate procurement in three fabrication clusters. Taiwan and South Korea dominate leading-edge wafer consumption. Germany and Japan anchor automotive-qualified substrate demand. The United States sustains defense and aerospace programs with captive supply arrangements.
Taiwan
TSMC and UMC foundries consume engineered substrates for advanced node ramps. The island's National Development Council subsidizes domestic material sourcing under semiconductor self-sufficiency programs. Hsinchu Science Park hosts qualification labs where SOI wafer vendors validate film thickness uniformity for 3nm-class processes.
South Korea
Samsung Foundry and SK Hynix drive RF-SOI volumes for 5G modem integration. KOTRA trade incentives support substrate import diversification away from Japanese suppliers. Pyeongtaek and Yongin semiconductor complexes require lot-level traceability documentation for automotive customer programs.
Germany
Bosch and Infineon source FD-SOI wafers for automotive zonal controllers and power management ICs. KBA safety certification mandates substrate provenance documentation extending to polysilicon origin. Dresden's Silicon Saxony cluster anchors GlobalFoundries' 22FDX production with direct rail links to Czech and Polish material suppliers.
Japan
Toyota and Denso integrate SOI-based isolation chips into 800V EV inverter systems. METI's semiconductor revitalization fund subsidizes domestic 300mm wafer fab construction. Kyushu's Fukuoka and Kumamoto prefectures concentrate specialty substrate processing for radiation-hardened satellite applications.
United States
Defense primes Raytheon and Lockheed Martin procure radiation-hardened SOI through DMEA-trusted foundry networks. The CHIPS Act directs subsidy disbursement toward onshore substrate manufacturing capacity. Arizona's Phoenix metro and Texas's Austin-San Antonio corridor attract foundry construction with direct water and power infrastructure commitments.
Silicon on Insulator Market Key Industry Players
Player mix skews toward integrated substrate suppliers with captive crystal growth and layer transfer capabilities. The vendor base concentrates in fewer than five qualified 300mm engineered substrate sources. Two strategic archetypes dominate: vertically integrated material specialists controlling polysilicon through wafer processing, and foundry-affiliated substrate programs securing captive supply. Competitive moves center on backward integration into polysilicon refining and multi-source qualification partnerships with automotive tier-1 suppliers.
Within the integrated material tier, SOITEC and Shin-Etsu Chemical Co., Ltd. exemplify full-chain control from polysilicon to engineered substrate. GlobalFoundries occupies a distinct position as a foundry with substrate-level process differentiation through its FD-SOI node offerings. Tower Semiconductor represents the specialty foundry archetype, leveraging RF-SOI process modules for 5G front-end module production. Shanghai Simgui Technology Co., Ltd. anchors Chinese domestic supply efforts under national semiconductor self-sufficiency programs.
| Leading Market Players |
|---|
| SUMCO Corporation |
| GlobalFoundries |
| SOITEC |
| Tower Semiconductor |
| STMicroelectronics |
| Shin-Etsu Chemical Co., Ltd. |
| Shanghai Simgui Technology Co., Ltd. |
| Silicon Valley Microelectronics, Inc. |
| GlobalWafers |
| Others |
Cost & Logistics Intelligence
CE marking under the EU Medical Device Regulation gates both substrate qualification and price differentiation, compressing the vendor pool for implantable SOI wafers while enabling certified suppliers to command sustained premiums over merchant alternatives. Automotive OEMs in Germany and Japan mirror this dynamic through KBA and METI functional safety documentation requirements that stratify pricing across traceability tiers.
Pricing Analysis
Long-term offtake contracts with polysilicon indexation dominate procurement between substrate suppliers and foundry customers. Pricing stratifies across automotive-qualified, RF-specialized, and commodity research-grade tiers, with film thickness uniformity and buried oxide specifications as primary differentiation levers. Cost compression in 300mm engineered substrates is intensifying because Smart Cut technology licensing fees amortize across expanding wafer volumes. Fabless automotive chip designers exhibit highest price sensitivity, while defense primes with DMEA-trusted foundry arrangements show lowest.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication consumption for leading-edge logic and memory foundry ramps. Helium for Smart Cut layer transfer cooling draws from Qatar and the US federal reserve, while polysilicon refining rests on German and Japanese chemical suppliers. Single-source vulnerability concentrates in sub-50nm silicon film metrology equipment. Distribution runs through direct rail-linked clusters like Dresden's Silicon Saxony to Czech and Polish material suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film metrology expertise for sub-50nm silicon layer control represents the critical capability gap constraining substrate vendor expansion, with specialized ellipsometry and X-ray reflectometry training pipelines lagging demand acceleration from automotive and 5G ramps.
For Market Incumbents: Fortify polysilicon-to-wafer backward integration to defend against merchant merchant displacement as automotive tier-1 suppliers consolidate approved vendor lists. Expand 300mm qualification lab capacity in Hsinchu and Dresden to capture FD-SOI node ramp demand from European and Japanese OEMs. Prioritize helium supply diversification through long-term offtake agreements with Qatari and US reserve sources. For New Entrants and Emerging Players: CE marking fast-track pathways for implantable medical devices create accessible entry points for substrate vendors with existing ISO 13485 quality systems. Target India's Gujarat semiconductor cluster as domestic fab construction initiates under PLI scheme incentives, where first-mover substrate qualification partnerships face limited incumbent presence. Pursue joint qualification programs with Tower Semiconductor or GlobalFoundries to accelerate process portability validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 300mm engineered substrate manufacturing as Smart Cut technology licensing and helium infrastructure requirements escalate. Five-to-ten year viability favors vertically integrated material specialists with captive crystal growth and layer transfer capabilities over merchant wafer merchants dependent on external polysilicon. Monitor EU Chips Act subsidy disbursement timelines as inflection signal for foundry capacity allocation shifts affecting substrate pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | SOITEC and Shin-Etsu secure supply independence from merchant silicon feedstock volatility. |
| 300mm Qualification Lab Expansion | Hsinchu Science Park facilities validate film uniformity for TSMC and UMC 3nm-class processes. |
| Helium Supply Diversification Agreement | Long-term Qatari and US federal reserve contracts mitigate single-source cooling gas exposure. |
| RF-SOI Process Module Licensing | Tower Semiconductor monetizes 5G front-end module expertise through foundry service partnerships. |
| Automotive Traceability System Deployment | German OEMs demand lot-level polysilicon-to-wafer documentation for KBA functional safety certification. |
Research Approach
Cross-validation between foundry procurement executives and substrate vendor sales directors anchors the qualitative findings, supplemented by secondary analysis of SEC 10-K filings, EU Chips Act disbursement records, and Japan METI semiconductor fund announcements. Primary interviews encompass thin-film metrology specialists, automotive tier-1 supplier quality managers, and national laboratory radiation-hardened device researchers. Bottom-up wafer volume estimates triangulate against top-down foundry capacity expansion announcements across Taiwan, South Korea, and Germany.
Sensitivity analysis frames the quantitative modeling across the projection horizon, with segmentation by substrate type, technology node, application vertical, and end-user procurement structure. CAGRs derive from wafer shipment trajectories indexed to foundry equipment capex cycles and automotive platform electrification roadmaps. Key forecast inputs include helium supply elasticity coefficients and FD-SOI design win conversion rates at 22nm and 12nm nodes.
Underlying assumptions cover sustained EU Chips Act and CHIPS Act subsidy disbursement, with deviation risk concentrated in ECHA PFAS restriction enforcement timelines and Qatar helium export policy shifts. Recalibration cycles align with material shifts in automotive OEM approved vendor list consolidation and 5G base station deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
China Power Transistor Market