
 Printed Circuit Board (PCB) Laminate Market | 2026-2036
Printed Circuit Board (PCB) Laminate Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Circuit Board (PCB) Laminate Market Analytics
Modular laminate configurations is pivoting procurement patterns as buyers bundle high-frequency cores with standard FR-4 layers to reduce stack-up complexity. Rogers Corporation leverages its ceramic-filled hydrocarbon expertise to anchor premium RF substrate demand. Shengyi Technology sustains cost-competitive FR-4 output across massive Guangdong manufacturing footprints. Kingboard Laminates Holdings dominates volume supply through backward integration into copper foil and glass fiber production.
Printed Circuit Board laminate denotes a layered composite of resin-impregnated glass fiber and copper foil, cured under heat and pressure to specified thickness tolerances and dielectric constants for electrical insulation and signal transmission in electronic assemblies. FR-4 grade occupies the mature volume core with thin margins, while polyimide substrates command premium positioning for flexible and high-temperature applications where thermal stability exceeds standard epoxy systems. Automotive electronics application segments attract fastest-growing laminate demand as electrified powertrains require thermally robust, high-reliability substrate materials.
EPA air quality standards and OSHA workplace chemical exposure limits constrain North American laminate manufacturing processes and resin handling protocols. REACH registration requirements in Europe restrict certain halogenated flame retardants, pushing formulators toward phosphorus-based and nitrogen-based alternatives. China's MEE enforces wastewater discharge standards that elevate treatment capital requirements for major substrate producers. Stakeholders must monitor evolving flame-retardant chemistry regulations across multiple jurisdictions to anticipate reformulation timelines and qualification cycles.
Market Dynamics
Automotive electrification is compressing qualification cycles for thermally robust laminates as OEMs specify higher glass transition temperatures and thermal conductivity for powertrain modules.
Growth Catalysts
- China MIIT dual carbon mandates:Domestic substrate producers are retooling resin formulations to meet carbon intensity targets, accelerating adoption of low-emission curing processes in Guangdong fabrication clusters.
- EV powertrain thermal demands:Battery management systems and inverter modules require ceramic-filled hydrocarbon laminates that withstand sustained operating temperatures above standard FR-4 limits.
- Modular stack-up bundling:Procurement teams are consolidating high-frequency core purchases with standard layers to simplify supplier management and reduce qualification overhead.
Market Restraints
- Copper foil and glass fiber input volatility:Backward-integrated suppliers control critical raw material streams, constraining margin flexibility for non-integrated laminate fabricators.
- EU REACH chemical restrictions:Phased halogenated flame retardant limitations force costly reformulation cycles and extended qualification timelines for European-bound product lines.
- Guangdong production concentration:Geographic clustering of substrate fabrication creates exposure to regional power rationing, water discharge enforcement, and logistics bottlenecks.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor and PCB assembly are attracting laminate suppliers to establish local compounding and prepreg operations.
- Phosphorus-nitrogen flame retardant convergence:Next-generation halogen-free chemistries open qualification pathways for aerospace and medical device substrates previously blocked by legacy material specifications.
- Direct OEM contracting models:Tier-1 automotive suppliers are bypassing traditional distribution to negotiate volume commitments directly with laminate manufacturers for EV platform programs.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for high-frequency dielectric materials concentrates among senior technologists approaching retirement, constraining R&D pipeline velocity.
- Multi-jurisdiction flame retardant compliance:Divergent EPA, REACH, and China GB standards require parallel qualification tracks, extending time-to-revenue for new product introductions.
- Legacy FR-4 equipment retooling costs:Capital requirements for high-precision thickness control and low-loss resin systems strain mid-tier fabricators with aging press lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Circuit Board (PCB) Laminate Market |
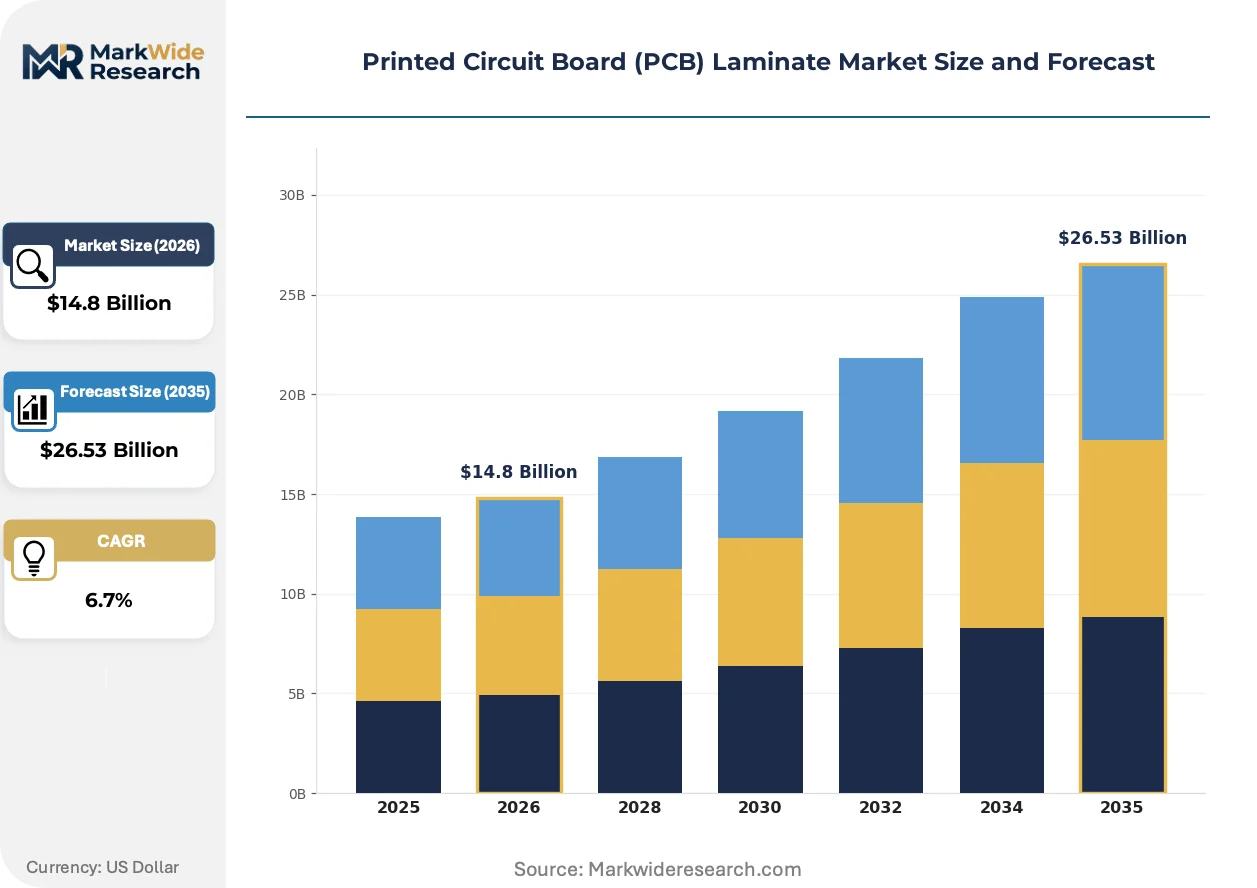
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FR-4, CEM-1, CEM-3, Polyimide Material: Copper, Glass Fiber, Epoxy, Resin Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distribution Partners |
| Companies Covered | ITEQ Corporation, Rogers Corporation, Shengyi Technology, Samsung Electro-Mechanics, Doosan Corporation Electro-Materials, Kingboard Laminates Holdings, Taiwan Union Technology Corporation, Unimicron Technology Corp, Nan Ya Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Circuit Board (PCB) Laminate Market Evolving Landscape
Resin chemistry and copper surface treatment advances are redefining performance benchmarks as signal integrity requirements intensify across 5G infrastructure and automotive radar applications.
Ceramic-filled hydrocarbon laminates are consolidating RF substrate specifications as base station and automotive radar manufacturers standardize on Rogers Corporation's dielectric constant stability for millimeter-wave frequencies. Telecom equipment OEMs in South Korea and Germany are qualifying these materials for 28 GHz and 39 GHz antenna arrays. The technology is consolidating procurement decisions around fewer qualified suppliers capable of tight thickness tolerance and controlled impedance.
EU REACH Annex XVII restrictions on halogenated flame retardants are compelling formulators to validate phosphorus-based and nitrogen-based alternatives across full thermal aging profiles. Laminate producers serving European automotive and industrial markets face 18-24 month requalification cycles for existing product lines. Medical device and aerospace segments are accelerating adoption of pre-validated halogen-free material sets to preempt regulatory disruption.
Automotive procurement teams are compressing supplier qualification timelines from 36 months to 18 months for EV platform laminates, forcing substrate manufacturers to front-load testing and documentation. Tier-1 powertrain suppliers in Germany and Japan are consolidating approved vendor lists to three qualified sources per material grade. This behavioral shift concentrates volume with vertically integrated producers capable of simultaneous resin synthesis, glass treatment, and copper cladding operations.
Printed Circuit Board (PCB) Laminate Market Segmentation
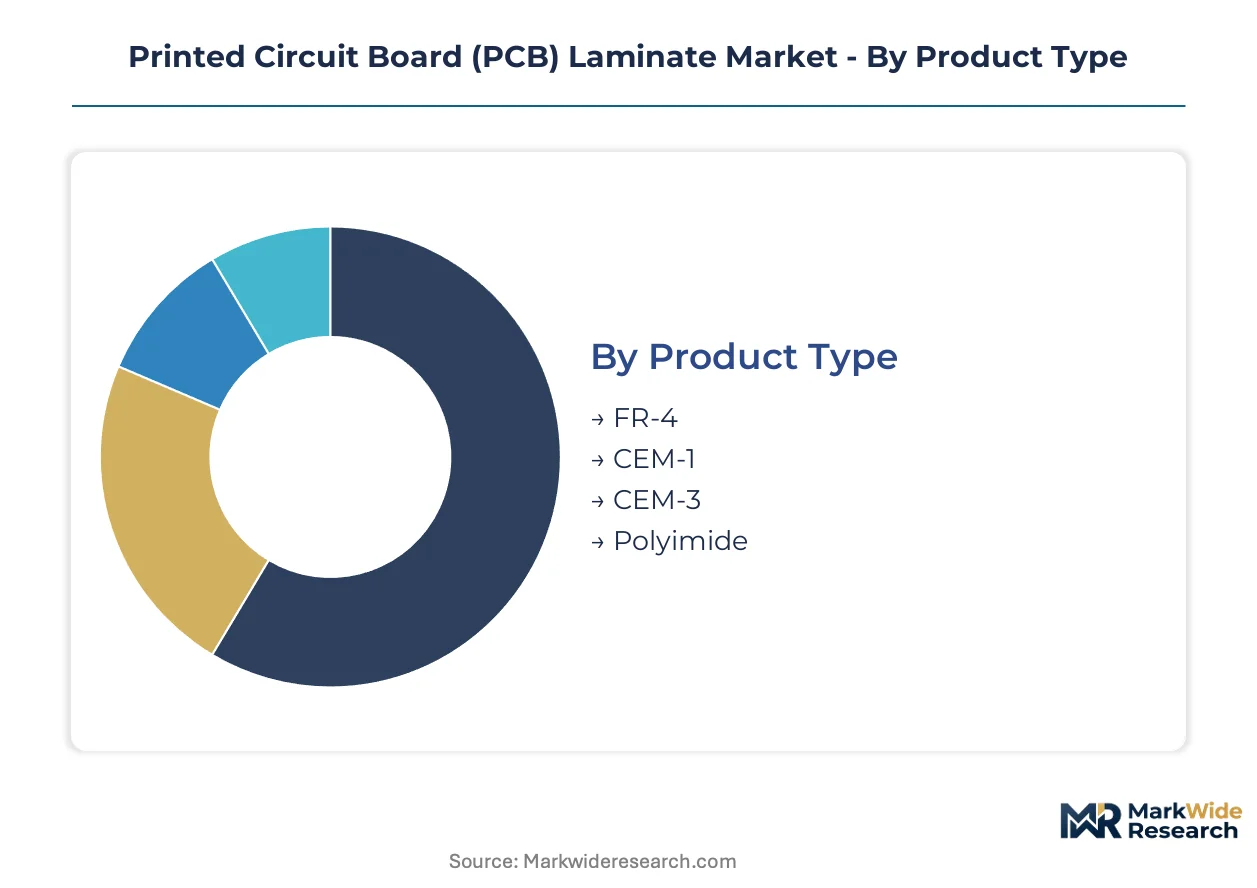
PCB laminate segmentation reveals how material specifications and supply chain roles determine margin structures. Procurement patterns diverge sharply between cost-driven commodity grades and performance-critical specialty substrates.
Product Type:
Customization intensity spans from standardized epoxy systems to engineered high-temperature formulations, with specification flexibility directly correlating to qualification overhead and pricing power.
- FR-4:Brominated epoxy-impregnated glass fiber composite dominates volume production with dielectric constant stability around 4.5. Massive Guangdong fabrication clusters in China process FR-4 for consumer motherboard and standard industrial applications where cost minimization overrides performance margins.
- Polyimide:Aromatic polymer backbone delivers thermal stability exceeding 300°C glass transition temperature for flexible circuit applications. Aerospace manufacturers in Germany and medical device OEMs in the US specify polyimide for implantable electronics and avionics where thermal cycling resistance is non-negotiable.
- CEM-1:Cellulose paper core with glass fiber surface layers offers intermediate cost positioning for single-sided consumer electronics boards.
- CEM-3:Non-woven glass fiber mat construction provides improved mechanical strength over CEM-1 for double-sided applications in cost-sensitive industrial controls.
Most installed capacity flows through FR-4. Expansion is steepest in Polyimide.
Material:
Backward integration depth varies dramatically by raw material, with captive copper foil and glass fiber production separating volume leaders from margin-constrained assemblers.
- Copper:Electrodeposited and rolled copper foil thickness precision down to 3-micron tolerances determines signal integrity in high-frequency layers. South Korean and Japanese smelters supply ultra-low profile foil for 5G base station laminates where skin effect losses must be minimized.
- Resin:Epoxy, cyanate ester, and hydrocarbon formulations define dielectric loss characteristics across frequency bands. Rogers Corporation's ceramic-filled hydrocarbon systems anchor premium RF substrate specifications for automotive radar modules.
- Glass Fiber:E-glass and low-Dk glass weave styles control coefficient of thermal expansion matching to copper traces.
- Epoxy:Standard bisphenol-A and specialized novolac hardener systems balance cost against Tg requirements.
Copper foil supply concentrates among integrated producers. Resin formulation capability is expanding most quickly through automotive-qualified compounders.
Application:
End-use thermal and reliability specifications create divergent qualification barriers, with automotive electrification forcing the steepest material upgrades.
- Automotive Electronics:Battery management systems and inverter modules demand ceramic-filled laminates with thermal conductivity above 1.5 W/mK and Tg exceeding 170°C. Tier-1 German powertrain suppliers compress qualification cycles to 18 months for EV platform laminates.
- Telecommunications:5G infrastructure and millimeter-wave antenna arrays require tightly controlled dielectric constant stability across -40°C to 125°C operating ranges. South Korean equipment OEMs qualify Rogers Corporation materials for 28 GHz and 39 GHz deployments.
- Consumer Electronics:Smartphone and laptop motherboard volumes prioritize FR-4 cost minimization through Guangdong mass production.
- Industrial Equipment:Factory automation and power electronics balance thermal performance against multi-year supply security requirements.
Automotive Electronics commands the fastest-growing trajectory. Consumer Electronics retains the deepest installed base.
End User:
Procurement sophistication and technical specification authority determine how laminate suppliers structure pricing and qualification support.
- OEMs:Original equipment manufacturers in automotive and telecommunications sectors specify material grades directly, bypassing distribution for strategic laminate procurement. Tesla and BMW negotiate volume commitments with Rogers Corporation and Shengyi Technology for platform-standardized substrates.
- Tier-1 Suppliers:Continental and Bosch consolidate approved vendor lists to three qualified sources per material grade, front-loading testing documentation to meet compressed EV timelines.
- Distribution Partners:Arrow and Avnet stock FR-4 and standard high-frequency cores for mid-volume electronics manufacturers without direct mill relationships.
- Aftermarket Providers:Repair and refurbishment operations source laminates through fragmented wholesale channels with minimal technical support.
OEMs and Tier-1 Suppliers absorb the majority of qualified laminate volume. Distribution Partners are gaining share in mid-market RF applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCB laminate fabrication originated in post-war Japan and scaled through Taiwan's electronics manufacturing boom before consolidating in China's Pearl River Delta. Today's supply geography reflects this historical diffusion, with production clustering shifting toward cost-optimized zones while qualification authority remains concentrated in automotive and telecom OEM hubs.
China
Guangdong province processes the majority of global FR-4 volume through substrate fabrication clusters serving domestic and export PCB assembly. MIIT dual carbon mandates compel resin formulators to adopt low-emission curing processes and carbon intensity tracking. Shenzhen and Dongguan house massive prepreg operations where Shengyi Technology and Kingboard Laminates Holdings maintain backward-integrated manufacturing footprints.
United States
Defense and aerospace OEMs in California and Texas specify polyimide laminates for thermal cycling resistance in avionics and satellite systems. EPA air quality standards and OSHA workplace chemical exposure limits constrain resin handling protocols and press line emissions. Rogers Corporation anchors premium RF substrate demand from its Connecticut ceramic-filled hydrocarbon expertise base.
Germany
Tier-1 automotive suppliers in Bavaria and Baden-Württemberg compress laminate qualification cycles to 18 months for EV powertrain platforms. EU REACH Annex XVII restrictions on halogenated flame retardants force 18-24 month reformulation timelines for European-bound product lines. Stuttgart and Munich host qualification laboratories where Bosch and Continental consolidate approved vendor lists to three sources per material grade.
South Korea
Samsung Electro-Mechanics and telecom equipment OEMs qualify ceramic-filled laminates for 28 GHz and 39 GHz 5G antenna arrays. MFDS chemical substance registration aligns with REACH-equivalent disclosure requirements for flame retardant chemistry. Gyeonggi-do province concentrates millimeter-wave substrate testing facilities serving base station export programs.
Japan
Automotive radar manufacturers in Aichi and Kanagawa prefectures specify tightly controlled dielectric constant stability for 77 GHz ADAS modules. METI industrial standards govern thermal aging test protocols for powertrain-qualified materials. Nagoya hosts polymer chemist expertise for high-frequency dielectric formulation that concentrates among senior technologists approaching retirement.
Printed Circuit Board (PCB) Laminate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across dielectric performance and qualification overhead. The market structures around three tiers: vertically integrated resin-to-laminate producers capturing volume economics, specialty compounders commanding RF and high-temperature premiums, and regional fabricators competing on FR-4 cost minimization. Dominant competitive moves include backward integration into copper foil and glass fiber production, and direct OEM contracting that bypasses traditional distribution channels.
Within the premium specialty tier, Rogers Corporation exemplifies ceramic-filled hydrocarbon expertise anchoring millimeter-wave substrate specifications. Among Asia-Pacific volume producers, Shengyi Technology and Kingboard Laminates Holdings occupy positions defined by massive Guangdong manufacturing footprints and backward integration into raw material streams. Taiwan Union Technology Corporation represents the mid-tier specialist archetype serving high-frequency applications with regional qualification support.
| Leading Market Players |
|---|
| ITEQ Corporation |
| Rogers Corporation |
| Shengyi Technology |
| Samsung Electro-Mechanics |
| Doosan Corporation Electro-Materials |
| Kingboard Laminates Holdings |
| Taiwan Union Technology Corporation |
| Unimicron Technology Corp |
| Nan Ya Plastics |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement consolidation for EV powertrain laminates is forcing substrate manufacturers to absorb qualification cost burdens while maintaining price competitiveness, compressing margins across ceramic-filled hydrocarbon and high-Tg FR-4 tiers. This buyer-driven pressure concentrates pricing power with backward-integrated producers capable of offsetting resin formulation costs through captive copper foil and glass fiber supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the PCB laminate market, with Rogers Corporation ceramic-filled hydrocarbon systems commanding RF substrate premiums against Shengyi Technology's mass-market FR-4 volumes. Price differentiation hinges on dielectric constant stability certification and automotive qualification status, with Tier-1 powertrain suppliers least sensitive to unit cost. Pricing pressure stems from copper foil input volatility and compressed automotive qualification cycles, while consumer electronics procurement teams in Guangdong drive the most aggressive cost negotiations.
Supply Chain Analysis
Regional distribution centers in Dongguan and Shenzhen anchor hub-and-spoke patterns serving PCB assembly clusters across China's Pearl River Delta, with secondary nodes in South Korea and Japan for millimeter-wave substrate qualification. Raw material flows draw from electrodeposited copper foil smelters in South Korea, E-glass weavers in Taiwan, and epoxy resin compounders in Japan. Single-source vulnerability concentrates in ultra-low profile copper foil for 5G antenna applications. Distribution runs through direct OEM contracting for automotive volumes and Arrow-Avnet channels for mid-market RF applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme subsidies for electronics manufacturing create 15-20% cost advantages against Guangdong's rising environmental compliance capital requirements.
For Market Incumbents: Lock in resin formulation expertise through targeted hiring of senior polymer chemists approaching retirement in Japan, while expanding captive copper foil capacity to offset input cost volatility from South Korean smelters. Defend automotive qualification positions by front-loading documentation for compressed 18-month OEM timelines. For New Entrants and Emerging Players: Launch via direct contracting with India-based EMS providers qualifying for PLI scheme benefits, targeting halogen-free FR-4 for European automotive exports as the most penetrable white space. Prioritize phosphorus-nitrogen flame retardant formulations to bypass REACH Annex XVII restrictions blocking legacy suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier specialists possessing automotive-qualified resin synthesis capabilities but lacking scale, as OEM consolidation to three approved vendors per grade accelerates acquisition premiums. Watch for MIIT enforcement actions on Guangdong carbon intensity targets as the inflection signal for regional production cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Kingboard Laminates Holdings secures input cost control against South Korean smelter pricing volatility. |
| Halogen-Free Resin Reformulation | Phosphorus-nitrogen chemistry opens REACH-compliant pathways for European automotive substrate supply. |
| Direct OEM Contracting Model | Tesla and BMW negotiate volume commitments bypassing traditional distribution margin layers. |
| India PLI Scheme Manufacturing Footprint | Local compounding operations capture subsidy benefits for semiconductor and PCB assembly supply. |
| Ceramic-Filled Hydrocarbon R&D Expansion | Rogers Corporation anchors 28 GHz and 39 GHz antenna array specifications for South Korean telecom OEMs. |
Research Methodology
Bottom-up automotive electronics and telecommunications modeling reconciled against top-down copper foil and resin supply tracking forms the analytical core of this study. Primary interviews with laminate procurement managers at Tier-1 automotive suppliers, resin formulation directors at Guangdong fabrication clusters, and RF substrate qualification engineers at South Korean telecom equipment OEMs combined with secondary validation from MIIT carbon intensity disclosures, EU REACH Annex XVII regulatory filings, and SEC 10-K raw material cost disclosures. Bottom-up and top-down triangulation cross-checks volume assumptions against resin consumption patterns and copper foil shipment data.
Historical trendline analysis of FR-4 and polyimide pricing across Guangdong production clusters established baseline margin structures, with projection models segmenting by product type, material composition, application thermal requirements, and end-user procurement sophistication. CAGRs derive from fitted growth curves calibrated to EV powertrain laminate adoption rates and 5G infrastructure deployment timelines. Forecast inputs incorporate MIIT dual carbon mandate enforcement trajectories and REACH halogenated flame retardant phase-out schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Guangdong power rationing or accelerated EU chemical restrictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Gaming GPU Market