
 Asia-Pacific Semiconductor Device Market | 2026-2036
Asia-Pacific Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Device Market Insights
Automotive OEMs are collapsing the historical distance between chip design and vehicle assembly. Samsung Electronics leverages captive memory and foundry capacity to supply vertically integrated automotive platforms. Taiwan Semiconductor Manufacturing Company anchors leading-edge node production for fabless designers across the region. SK hynix sustains dominance in high-bandwidth memory stacks critical to AI accelerators.
Asia-Pacific semiconductor devices are solid-state electronic components fabricated on silicon, gallium nitride, or silicon germanium substrates, typically ranging from mature nodes at 28nm to advanced processes below 3nm, enabling signal processing, power conversion, and data storage across industrial systems. Analog and radiofrequency segments occupy stable margin pools in automotive radar and 5G base station deployments. Digital and microcontroller categories lead volume growth as industrial automation and consumer electronics manufacturers consolidate board-level component sourcing.
China's MIIT enforces domestic content benchmarks through GB standards and dual carbon mandates, while Japan's METI coordinates supply chain resilience investments under revised semiconductor support legislation. South Korea's K-Semiconductor Belt program ties tax incentives to local R&D spending minimums. Stakeholders must monitor how export control alignments between Washington, Tokyo, and Seoul reshape equipment procurement timelines for Chinese fabs.
Market Dynamics
Automotive OEMs in the Asia-Pacific region are collapsing design-to-assembly timelines for power semiconductors, forcing foundries to co-locate engineering teams at vehicle manufacturing sites. This structural compression is redrawing procurement relationships across South Korea, Taiwan, and Japan.
Growth Catalysts
- Dual carbon mandates:China's MIIT enforces domestic content benchmarks through GB standards, redirecting capital toward local fabrication capacity for power management devices.
- Electric drivetrain procurement:Automotive OEMs are accelerating volumes of silicon carbide MOSFETs and IGBT modules for traction inverters and onboard chargers.
- K-Semiconductor Belt incentives:South Korea ties tax benefits to R&D spending minimums, concentrating memory and foundry investments around Pyeongtaek and Yongin.
Market Restraints
- Equipment access limitations:Export control alignments between Washington, Tokyo, and Seoul are compressing procurement timelines for advanced lithography and deposition tools at Chinese fabs.
- Substrate supply concentration:Silicon carbide wafer production clusters in Hokkaido and Kumamoto, creating single-source vulnerability for wide-bandgap device manufacturers.
- Mature node margin compression:Foundries at 28nm and above face pricing pressure as Chinese capacity additions outpace regional demand growth for legacy automotive microcontrollers.
Strategic Opportunities
- High-bandwidth memory integration:AI accelerator designers in Taiwan and South Korea are stacking HBM3E with logic dies, creating captive demand for advanced packaging capacity.
- Vietnam and Malaysia backend expansion:Assembly and test houses are relocating flip-chip and wafer-level packaging operations to Southeast Asia to diversify geographic risk.
- METI resilience subsidies:Japan's revised semiconductor support legislation funds domestic 2nm pilot lines and materials R&D, opening equipment and chemical supplier entry points.
Industry Challenges
- Process engineer scarcity:Leading-edge node development requires expertise in extreme ultraviolet lithography and gate-all-around transistor architecture that remains concentrated among a small cohort of specialists in Hsinchu and Suwon.
- Heterogeneous integration complexity:Chiplets from multiple foundry sources must interface through standardized interconnects, yet UCIe and proprietary standards remain in conflict across TSMC, Samsung, and Intel packaging roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Device Market |
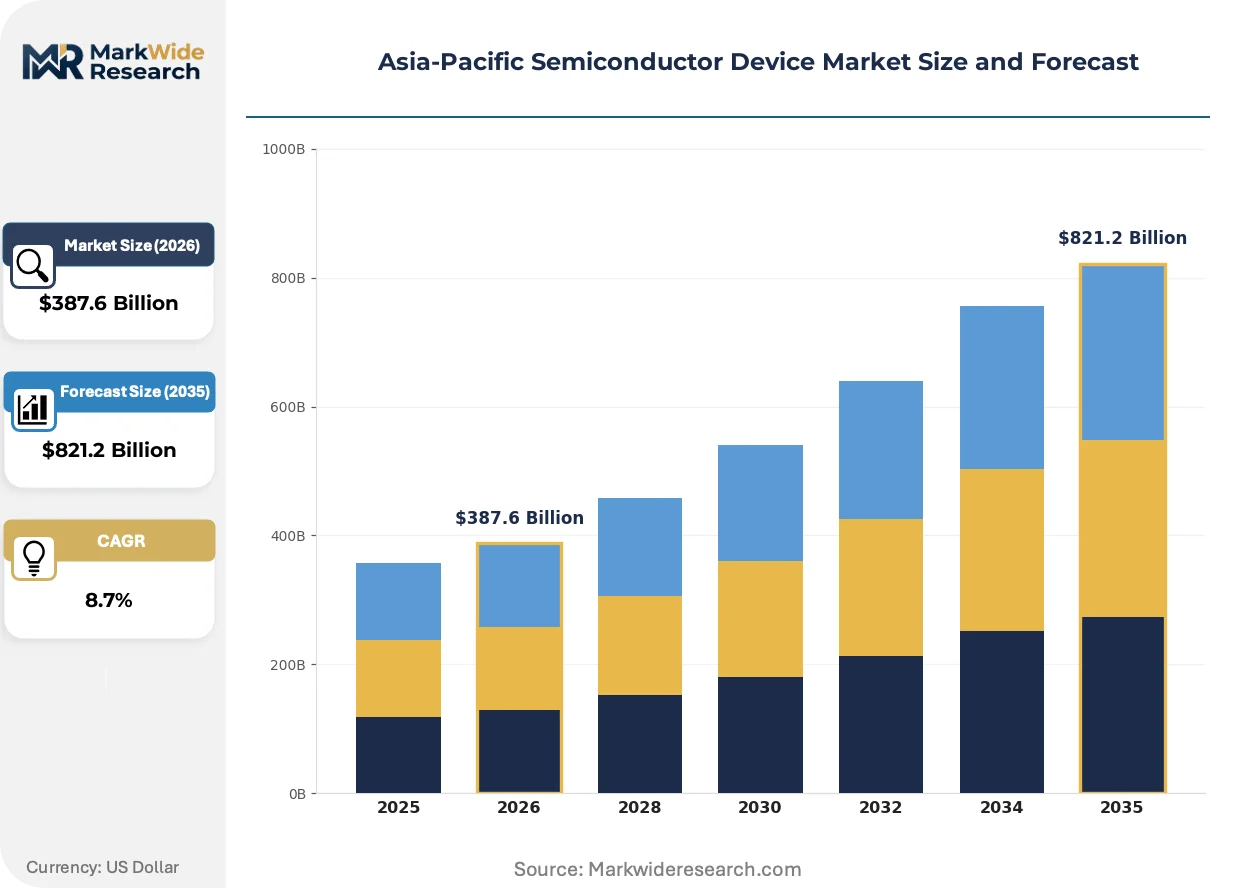
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Radiofrequency, Microcontroller Application: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Technology: CMOS, BiCMOS, GaN, SiGe End User: OEMs, System Integrators, Distributors, Aftermarket Providers |
| Companies Covered | Semiconductor Manufacturing International Corporation, Powerchip Semiconductor Manufacturing Corp., Taiwan Semiconductor Manufacturing Company, Tokyo Electron, MediaTek, Samsung Electronics, United Microelectronics Corporation, Infineon Technologies, SK hynix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Device Market Trends and Innovations
Process-node diversification and packaging innovation are fragmenting the traditional foundry-customer relationship across the Asia-Pacific semiconductor value chain. New technical capabilities are enabling device architectures that bypass conventional scaling limitations.
Gallium nitride power devices are fragmenting the silicon MOSFET landscape for consumer and automotive applications. Smartphone charger OEMs in Shenzhen and Dongguan have adopted GaN ICs at scale since 2022. The technology is compressing adapter form factors and enabling multi-port architectures that silicon cannot match at equivalent efficiency levels.
Japan's METI coordinates supply chain resilience investments under revised semiconductor support legislation passed in 2024. The framework mandates domestic sourcing ratios for critical materials and equipment. Memory and logic manufacturers in Kyushu and Tohoku are restructuring supplier qualification timelines to comply with these localization requirements.
Automotive Tier-1 suppliers are consolidating board-level component sourcing through direct foundry relationships rather than distributor channels. Bosch, Denso, and Hyundai Mobis have established dedicated capacity allocation agreements with Taiwanese and Korean foundries. This disintermediation is most visible in power semiconductor procurement for electric vehicle platforms, where design-in cycles have compressed from 36 months to 18 months.
Asia-Pacific Semiconductor Device Market Segmentation
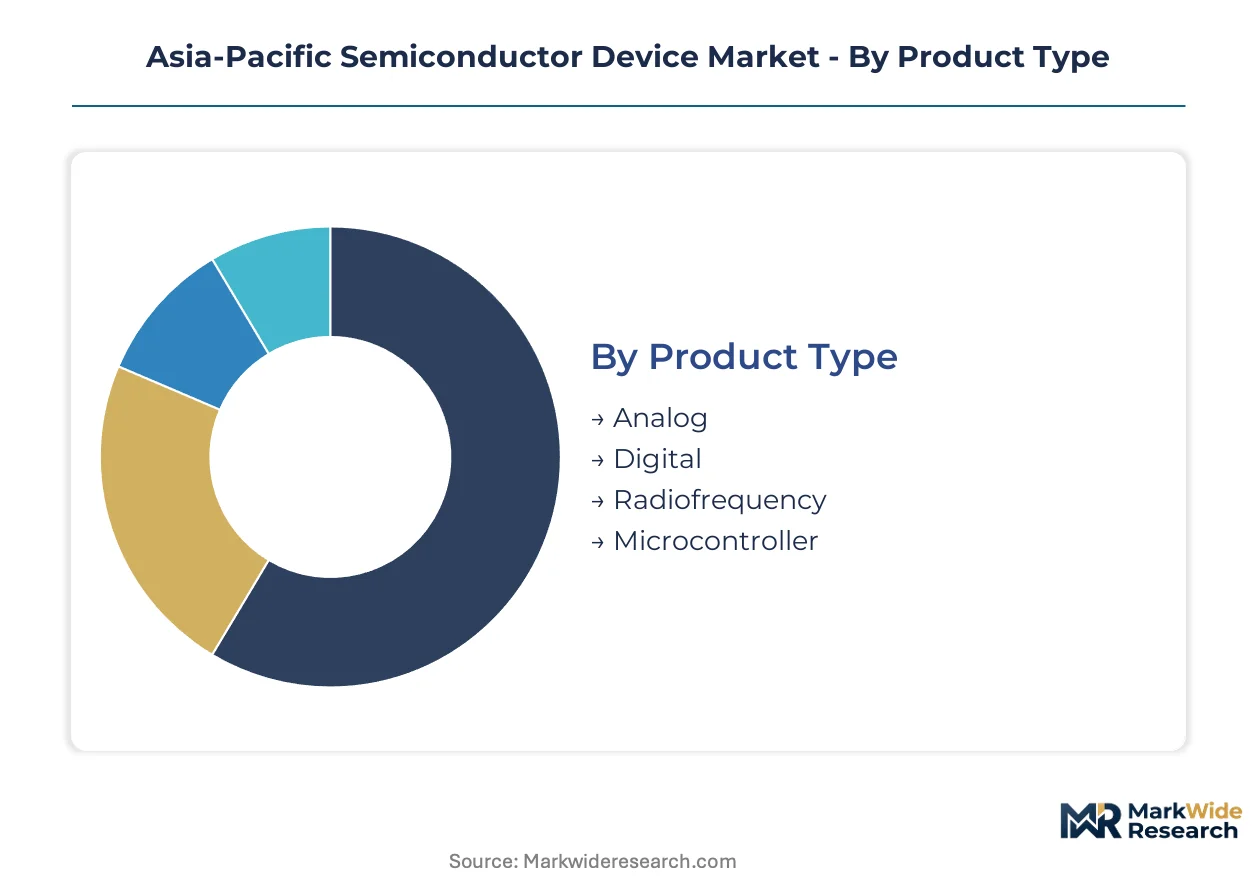
Device architectures across the Asia-Pacific semiconductor market fragment along power-performance tradeoffs that determine procurement channel selection. Analog and power management devices flow through distributor networks serving industrial automation clusters, while leading-edge digital logic moves through direct foundry relationships with fabless designers.
Product Type:
Channel mix varies sharply: analog and microcontroller units ship heavily through authorized distributors serving mid-sized industrial OEMs, whereas digital and radiofrequency devices increasingly bypass distribution through direct wafer supply agreements.
- Digital:Logic devices fabricated at nodes below 7nm enable AI accelerators and data center processors. Taiwan and South Korea concentrate demand from cloud infrastructure deployers and fabless chip designers seeking TSMC and Samsung foundry access.
- Analog:Signal processing components operate at mature nodes with extended product lifecycles. China's industrial automation sector drives procurement through Huaqiangbei distribution hubs serving Shenzhen and Dongguan equipment manufacturers.
- Radiofrequency:Front-end modules for 5G base stations and smartphones.
- Microcontroller:Embedded control units for automotive body electronics and appliance motor drives.
Digital dominates installed base value. Analog is where expansion concentrates.
Application:
Margin tiers separate automotive and telecommunications from consumer electronics and industrial automation, with the former commanding premium pricing for reliability certification and the latter competing on unit cost at volume.
- Automotive:Power semiconductors for electric drivetrains require AEC-Q100 qualification and functional safety documentation. South Korean and Japanese OEMs are collapsing design-in cycles from 36 months to 18 months for silicon carbide MOSFETs and IGBT modules.
- Telecommunications:Base station chipsets and optical transceivers demand high-frequency performance. China's 5G rollout sustains demand for massive MIMO radio units and 400G coherent DSPs from domestic and Taiwanese suppliers.
- Consumer Electronics:Smartphone application processors and display driver ICs.
- Industrial Automation:Motor drives, PLCs, and sensor interfaces.
Automotive commands premium positioning. Telecommunications is climbing the fastest.
Technology:
Substrate material determines foundry equipment requirements and thus geographic concentration of manufacturing capacity, with GaN and SiGe requiring specialized epitaxy tools concentrated in specific regional clusters.
- CMOS:Dominant silicon logic technology spanning planar and FinFET architectures. Taiwan's Hsinchu Science Park anchors leading-edge CMOS production for fabless designers across the Asia-Pacific region.
- GaN:Wide-bandgap power devices enable high-frequency switching in chargers and inverters. Shenzhen and Dongguan smartphone OEMs have adopted GaN ICs at scale since 2022, compressing adapter form factors.
- BiCMOS:Mixed-signal processes combining bipolar and CMOS devices for precision analog.
- SiGe:Silicon germanium heterojunction technologies for millimeter-wave RF applications.
CMOS holds the largest fabrication footprint. GaN is gaining share fastest.
End User:
Procurement authority is shifting from distributors toward direct OEM-foundry relationships in automotive and telecommunications, while industrial automation and aftermarket channels retain distributor intermediation.
- OEMs:Original equipment manufacturers in automotive and consumer electronics are consolidating board-level sourcing through direct capacity allocation agreements. Bosch, Denso, and Hyundai Mobis have established dedicated foundry relationships bypassing traditional distribution.
- System Integrators:Industrial automation deployers specify semiconductors for customized control systems. Japanese and Korean integrators concentrate procurement through authorized distributors with technical application support.
- Distributors:Channel intermediaries serving mid-volume customers without direct foundry access.
- Aftermarket Providers:Replacement component suppliers for repair and refurbishment services.
OEMs dominate high-value procurement. System integrators anchor mid-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity concentrates in Taiwan and South Korea, while China pursues import substitution through domestic fabrication investments. Japan maintains equipment and materials dominance. Southeast Asian nations capture backend assembly migration.
China
Electric vehicle manufacturers and industrial automation deployers drive silicon carbide and IGBT procurement volumes. MIIT enforces domestic content benchmarks through GB standards and dual carbon mandates. Yangtze River Delta fabs in Shanghai and Wuxi expand mature-node capacity for automotive microcontrollers.
Taiwan
Fabless designers from across the region secure leading-edge allocation for AI accelerators and smartphone application processors. The island's national development fund underwrites R&D tax credits for advanced packaging. Hsinchu Science Park anchors sub-3nm development with TSMC engineering teams co-located at customer sites.
South Korea
Memory stack demand from AI training clusters sustains HBM3E production ramps. K-Semiconductor Belt legislation ties tax incentives to local R&D spending minimums. Pyeongtaek and Yongin corridors concentrate DRAM and foundry investments with Samsung and SK hynix expanding cleanroom footprints.
Japan
Automotive Tier-1 suppliers source power discrete devices for traction inverters and onboard chargers. METI coordinates supply chain resilience investments under revised 2024 semiconductor support legislation. Kyushu and Tohoku clusters restructure supplier qualification timelines to meet domestic sourcing ratio mandates.
Vietnam
Assembly and test houses relocate flip-chip and wafer-level packaging to diversify geographic risk. The Ministry of Industry and Trade offers tax holidays for semiconductor manufacturing projects. Bac Ninh and Ho Chi Minh City industrial parks attract backend operations from Korean and Taiwanese parent companies.
Asia-Pacific Semiconductor Device Market Competitive Landscape
Concentration sits with integrated device manufacturers and pure-play foundries that command leading-edge node access. The structure tiers between captive memory producers, leading-edge logic specialists, and mature-node generalists. Strategic moves center on capacity pre-commitment agreements with automotive OEMs and co-location of engineering teams at customer design centers.
Among Taiwan-based fabricators, Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation occupy positions spanning leading-edge and specialty nodes. Samsung Electronics exemplifies the vertically integrated archetype combining memory, foundry, and system-level design capabilities. Semiconductor Manufacturing International Corporation represents the import-substitution fabricator archetype serving domestic Chinese demand.
| Leading Market Players |
|---|
| Semiconductor Manufacturing International Corporation |
| Powerchip Semiconductor Manufacturing Corp. |
| Taiwan Semiconductor Manufacturing Company |
| Tokyo Electron |
| MediaTek |
| Samsung Electronics |
| United Microelectronics Corporation |
| Infineon Technologies |
| SK hynix |
| Others |
Pricing and Supply Chain Analysis
300mm wafer scale economies at Pyeongtaek and Hsinchu anchor regional price floors, compressing margins for second-tier foundries while concentrating procurement leverage among automotive OEMs and cloud infrastructure deployers. This scale concentration simultaneously elevates entry barriers for new fabrication capacity and amplifies volume-discount power for buyers securing multi-year allocation agreements.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with automotive OEMs securing AEC-Q100 qualified silicon carbide MOSFETs at contracted premiums while industrial automation buyers source mature-node microcontrollers through spot-market distributors. Price differentiation hinges on certification grade and volume scale, with functional safety documentation commanding substantial premiums over commercial-grade alternatives. Cost compression in 28nm and above nodes is intensifying because Chinese capacity additions outpace regional demand absorption. Industrial automation deployers exhibit highest price sensitivity, whereas AI accelerator designers demonstrate lowest sensitivity due to performance-per-watt imperatives.
Supply Chain Analysis
Strait of Malacca transit underwrites substrate and equipment flows to Southeast Asian backend facilities, creating logistics vulnerability for assembly and test operations. Manufacturing concentration rests on Taiwan, South Korea, and Japan for leading-edge logic, memory, and materials respectively. Raw material dependencies span silicon carbide wafers from Hokkaido, photoresist from Kyushu, and high-purity gases from domestic suppliers. Single-source vulnerability pervades silicon carbide substrate supply. Distribution runs through direct foundry relationships for automotive and telecommunications OEMs, while authorized distributors serve mid-volume industrial customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation into direct foundry relationships is shifting procurement leverage decisively toward buyers, fragmenting traditional distributor intermediation across Taiwan, South Korea, and Japan. This buyer-power concentration demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Consolidate engineering co-location agreements with automotive Tier-1 suppliers to defend against emerging Chinese foundry competition. Prioritize captive supply of silicon carbide substrates through backward integration into Hokkaido and Kumamoto wafer production. METI resilience subsidies present channel control opportunities for Japanese materials suppliers qualifying under domestic sourcing mandates. For New Entrants and Emerging Players: Differentiate on heterogeneous integration capabilities for AI accelerator packaging, where UCIe standardization gaps create white-space opportunities. Vietnam and Malaysia backend expansion offers the most penetrable geography for flip-chip and wafer-level packaging entry. Target system integrators in industrial automation through authorized distribution partnerships with technical application support. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundries with multi-year capacity allocation agreements and automotive qualification pipelines. Long-term viability centers on advanced packaging integration capabilities and leading-edge node access. Acquisition target archetype: specialty analog foundries with AEC-Q100 certification infrastructure. Watch for inflection when export control alignments between Washington, Tokyo, and Seoul shift equipment procurement timelines at Chinese fabs.| Strategic Initiative | Industry Significance |
|---|---|
| Engineering Team Co-location | TSMC and Samsung embed process engineers at automotive OEM design centers, collapsing 36-month design-in cycles to 18 months. |
| HBM3E Capacity Expansion | SK hynix and Samsung scale cleanroom footprints in Pyeongtaek to supply AI training clusters with high-bandwidth memory stacks. |
| Domestic Sourcing Qualification | Kyushu and Tohoku manufacturers restructure supplier timelines to comply with METI's revised semiconductor support legislation mandates. |
| Backend Geographic Diversification | Korean and Taiwanese parent companies relocate flip-chip operations to Bac Ninh industrial parks under Vietnam's tax holiday incentives. |
| GaN Process Development | Shenzhen smartphone OEMs drive gallium nitride IC adoption since 2022, compressing adapter form factors beyond silicon MOSFET limits. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with foundry operations executives, automotive Tier-1 procurement directors, and equipment supplier technical leads; and secondary validation through customs filings, SEMI equipment shipment data, and national semiconductor subsidy disclosures. Bottom-up and top-down triangulation cross-checked capacity expansion announcements against capital expenditure flows and cleanroom construction permits.
Across the analysis window, the forecasting framework modeled device segmentation by substrate material, process node tier, and end-use application intensity. CAGRs derived from capacity utilization trajectories, design-in cycle compression rates, and regional subsidy absorption timelines. Specific inputs included MIIT domestic content benchmark enforcement patterns, K-Semiconductor Belt R&D spending qualification rates, and METI resilience investment disbursement velocities.
The analysis sits within stated boundaries; outcomes outside sustained export control alignment or abrupt subsidy program suspension would require recalibration. Forecasts reflect documented assumptions regarding equipment procurement timeline continuity and automotive electrification penetration curves. Practitioners should keep alternative scenarios live as dual carbon mandate enforcement intensity and heterogeneous integration standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Leap Engine Market