
 High Resistivity Silicon Wafers Market | 2026-2036
High Resistivity Silicon Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
High Resistivity Silicon Wafers Market Outlook
Japanese polysilicon purification capacity is hardening as the dominant supply-side constraint for substrate-grade feedstock. Shin-Etsu Chemical leverages captive chlorosilane refining to sustain cost advantages across 300mm float-zone ingots. GlobalWafers anchors its position through backward integration into crystal growth furnaces and expansive 200mm-300mm polishing lines in Taiwan. Siltronic competes on epitaxial deposition expertise for RF device substrates serving European automotive radar programs.
High resistivity silicon wafers are single-crystal or epitaxial substrates with bulk resistivity exceeding 1,000 ohm-cm, manufactured via float-zone or Czochralski methods with minimal oxygen content to suppress parasitic capacitance in high-frequency circuits. These wafers primarily enable low-loss signal transmission in RF switches, power amplifiers, and antenna tuning modules for wireless communication systems. Single crystal ingots dominate volume shipments for 5G infrastructure, while epitaxial layers command premium pricing in millimeter-wave phased arrays where defect density directly determines yield. Polycrystalline variants occupy a narrowing niche in cost-sensitive sensor applications facing displacement by SOI alternatives.
Japan's METI enforces export controls on advanced semiconductor manufacturing equipment under its Foreign Exchange and Foreign Trade Act, constraining Chinese wafer fabs from accessing crystal growth tools. The EPA regulates fluorinated greenhouse gas emissions from Czochralski furnace operations in the United States, elevating compliance costs for domestic ingot pulling. China's MEE mandates dual carbon disclosure from polysilicon smelters, reshaping energy sourcing decisions for wafer producers. Stakeholders must monitor evolving substrate specifications for 6G terahertz research programs while calibrating capacity commitments against foundry demand signals from RF filter and radar module designers.
Market Dynamics
The high resistivity silicon wafers market is being fundamentally restructured by the geographic concentration of polysilicon purification capacity, which has concentrated feedstock control among a handful of Japanese and German chemical conglomerates and created asymmetric bargaining power across the substrate supply chain.
Growth Catalysts
- 5G Infrastructure Deployment:Massive MIMO antenna arrays and millimeter-wave base stations require ultra-low-loss substrates, pulling volume from specialized RF foundries in Taiwan and South Korea.
- METI Semiconductor Revitalization:Japan's Ministry of Economy, Trade and Industry directs subsidies toward domestic 300mm float-zone capacity, hardening local supply security for advanced RF applications.
- Epitaxial Deposition Advances:Improved chemical vapor deposition techniques enable thicker, lower-defect layers for automotive radar at 77 GHz, expanding addressable device markets.
Market Restraints
- Chlorosilane Feedstock Concentration:Semiconductor-grade polysilicon purification requires Siemens-process reactors concentrated in Japan and Germany, exposing buyers to single-source vulnerability.
- Float-Zone Energy Intensity:RF heating of 300mm ingots consumes megawatt-scale electricity, elevating production costs in regions without subsidized industrial power.
- SOI Substrate Substitution:Silicon-on-insulator wafers from specialized suppliers encroach on cost-sensitive sensor applications, compressing polycrystalline silicon wafer demand.
Strategic Opportunities
- 6G Terahertz Research:Pre-standardization programs at national laboratories in Japan and Finland are validating sub-THz device architectures that will require resistivity above 10,000 ohm-cm.
- India's Semiconductor Mission:Production-linked incentives for compound semiconductor fabs create first-mover openings for high-resistivity silicon substrate qualification.
- Dual Carbon Disclosure Mandates:China's Ministry of Ecology and Environment carbon accounting rules favor wafer producers with verified renewable energy sourcing, rewarding early greenfield investments.
Industry Challenges
- Float-Zone Technician Scarcity:The ingot growth process requires operators with decade-long apprenticeship experience, and demographic shifts in Japan and Germany are shrinking this specialized workforce.
- Multi-Year Certification Cycles:RF device makers impose 18-36 month substrate qualification protocols, freezing out new entrants regardless of technical performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Resistivity Silicon Wafers Market |
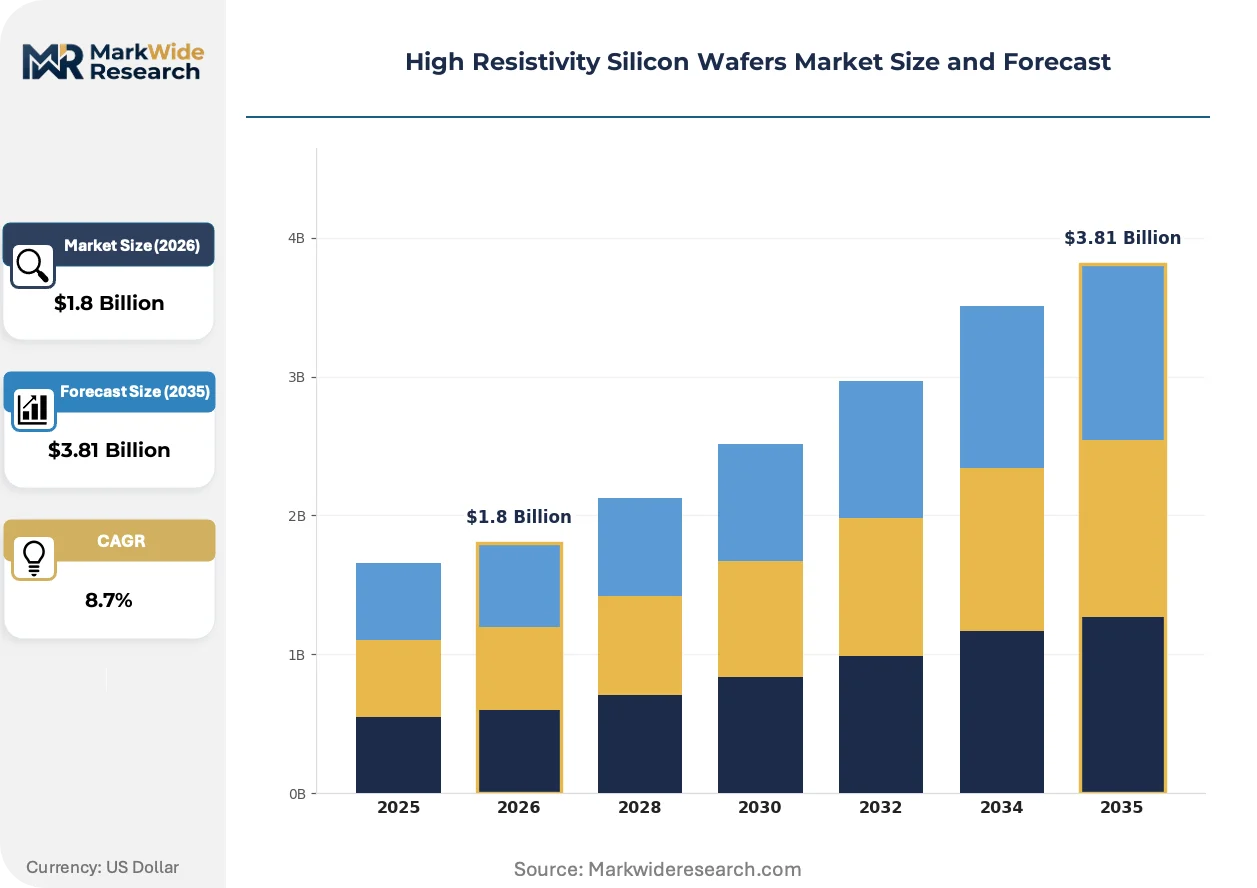
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Amorphous, Epitaxial End User: Consumer Electronics, Automotive, Aerospace, Telecommunications Application: Semiconductors, Photovoltaics, Sensors, Integrated Circuits Thickness: 200µm, 300µm, 500µm, 1mm |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., GlobalWafers Co., Ltd., Siltronic AG, Wafer Works Corporation, Okmetic, Sumco Corporation, SK Siltron, Semiconductor Wafer Inc., Soitec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Resistivity Silicon Wafers Market Strategic Shifts
Process integration across crystal growth and epitaxial deposition is compressing defect propagation pathways and enabling resistivity uniformity specifications that were unattainable with discrete manufacturing steps.
Magnetic field-applied Czochralski (MCZ) technology is integrating superconducting magnets into conventional pullers to suppress oxygen incorporation during ingot solidification. RF power amplifier manufacturers in South Korea are adopting MCZ substrates for sub-6 GHz infrastructure, accepting modest resistivity trade-offs for improved mechanical yield. This integration is bridging the cost-performance gap between standard Czochralski and premium float-zone methods.
Japan's METI export control regime under the Foreign Exchange and Foreign Trade Act now classifies advanced crystal growth furnaces as restricted items, constraining Chinese wafer fabs from accessing 300mm float-zone tools. Equipment makers in Tokyo and Osaka are redirecting R&D toward domestic capacity expansion while severing technical service relationships with mainland Chinese customers. European automotive radar programs now face extended lead times for substrate supply as alternative qualification pathways stretch.
Consolidated procurement by RF module integrators is displacing fragmented purchasing across discrete component vendors. Tier-one smartphone OEMs in Taiwan now contract directly with wafer producers for multi-year substrate supply, bypassing traditional distributor networks. This concentration is most visible in East Asian manufacturing clusters where foundry demand signals now transmit directly to ingot pull schedules.
High Resistivity Silicon Wafers Market Segmentation
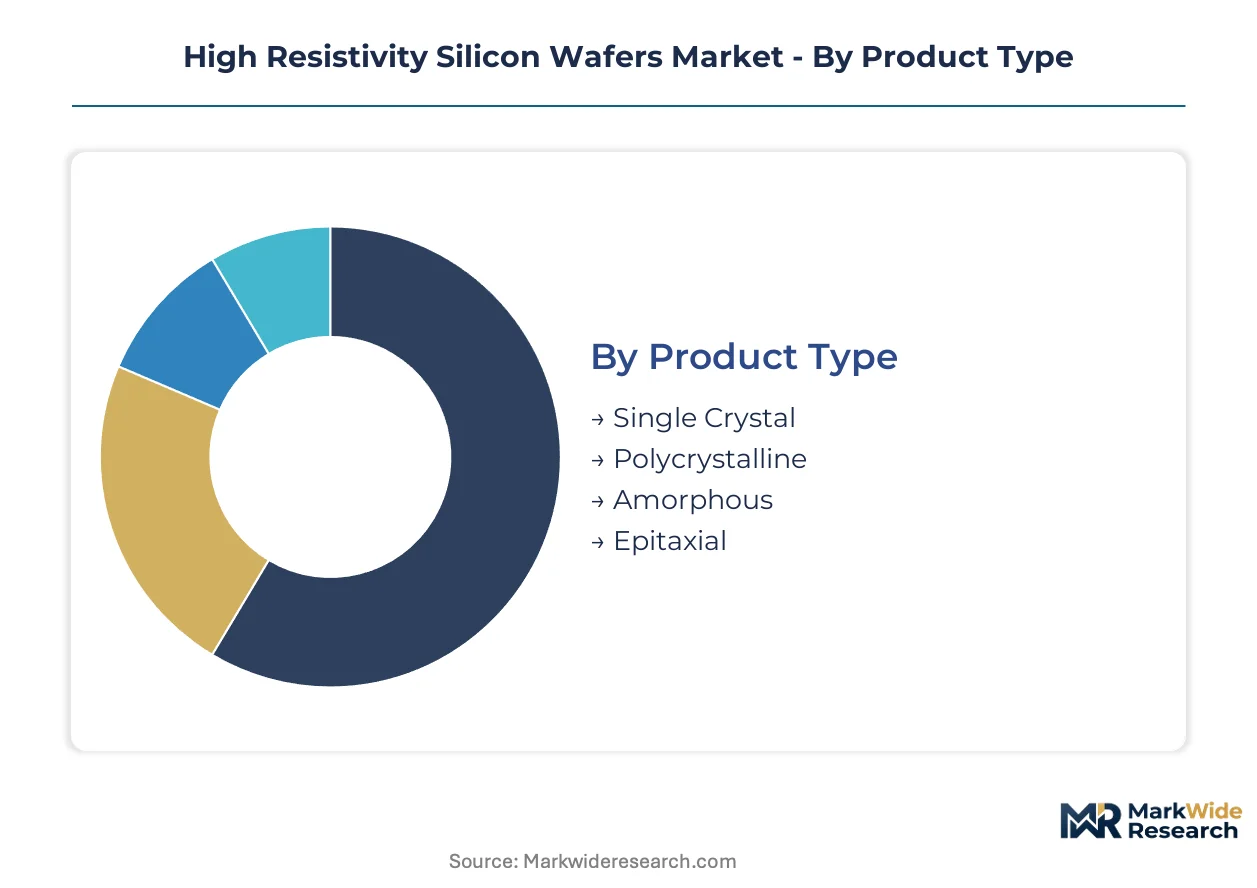
High resistivity silicon wafers serve distinct performance tiers across RF and power electronics. Specification requirements diverge sharply between millimeter-wave infrastructure and cost-constrained sensor applications. Each segmentation dimension reveals different buyer priorities and supplier capabilities.
Product Type:
Buyers differentiate primarily by defect tolerance and resistivity uniformity requirements, not raw material cost.
- Single Crystal:Float-zone or Czochralski-grown ingots sliced into substrates with bulk resistivity exceeding 1,000 ohm-cm and minimal oxygen content. Demand concentrates in 5G base station RF front-end modules from foundries in Taiwan and South Korea, constrained by chlorosilane feedstock concentration in Japan and Germany.
- Epitaxial:Chemical vapor deposition adds crystalline layers atop base substrates, enabling precise dopant profiling for 77 GHz automotive radar. Premium pricing reflects defect density specifications that directly determine device yield in millimeter-wave phased arrays.
- Polycrystalline:Lower-cost substrates with grain boundaries acceptable in pressure and temperature sensors.
- Amorphous:Non-crystalline silicon for specialized thin-film applications with relaxed electrical performance requirements.
Volume sits with single crystal; growth tilts toward epitaxial.
End User:
Specification stringency correlates with frequency band and reliability requirements, not purchase volume.
- Telecommunications:Massive MIMO and millimeter-wave infrastructure demand ultra-low-loss substrates with resistivity above 10,000 ohm-cm for sub-THz research programs. Deployment timelines in Japan and Finland validate device architectures that will drive next-generation qualification cycles.
- Automotive:Radar modules at 77 GHz require thick, low-defect epitaxial layers with extended temperature cycling reliability. European programs face elongated lead times as METI export controls constrain Chinese fabs from alternative qualification pathways.
- Consumer Electronics:RF switches and antenna tuning modules in smartphones pull volume through direct OEM contracting.
- Aerospace:Radiation-hardened specifications for satellite communications command niche premium pricing.
Procurement concentrates in telecommunications; margin expansion favors automotive.
Application:
Process complexity and certification burden separate segments more than end-market size.
- Semiconductors:Discrete and integrated RF devices require substrate qualification protocols spanning 18-36 months, freezing out new entrants regardless of technical performance. Foundry demand signals from RF filter designers now transmit directly to ingot pull schedules.
- Integrated Circuits:Power amplifiers and switches for sub-6 GHz infrastructure adopt MCZ substrates, accepting modest resistivity trade-offs for improved mechanical yield in South Korean manufacturing.
- Sensors:Pressure and inertial measurement units tolerate polycrystalline variants facing displacement by SOI alternatives.
- Photovoltaics:Minimal penetration due to resistivity overspecification for standard cell efficiency requirements.
Revenue concentrates in semiconductors; integrated circuits are expanding most quickly.
Thickness:
Mechanical handling constraints and furnace capacity economics shape buyer preferences.
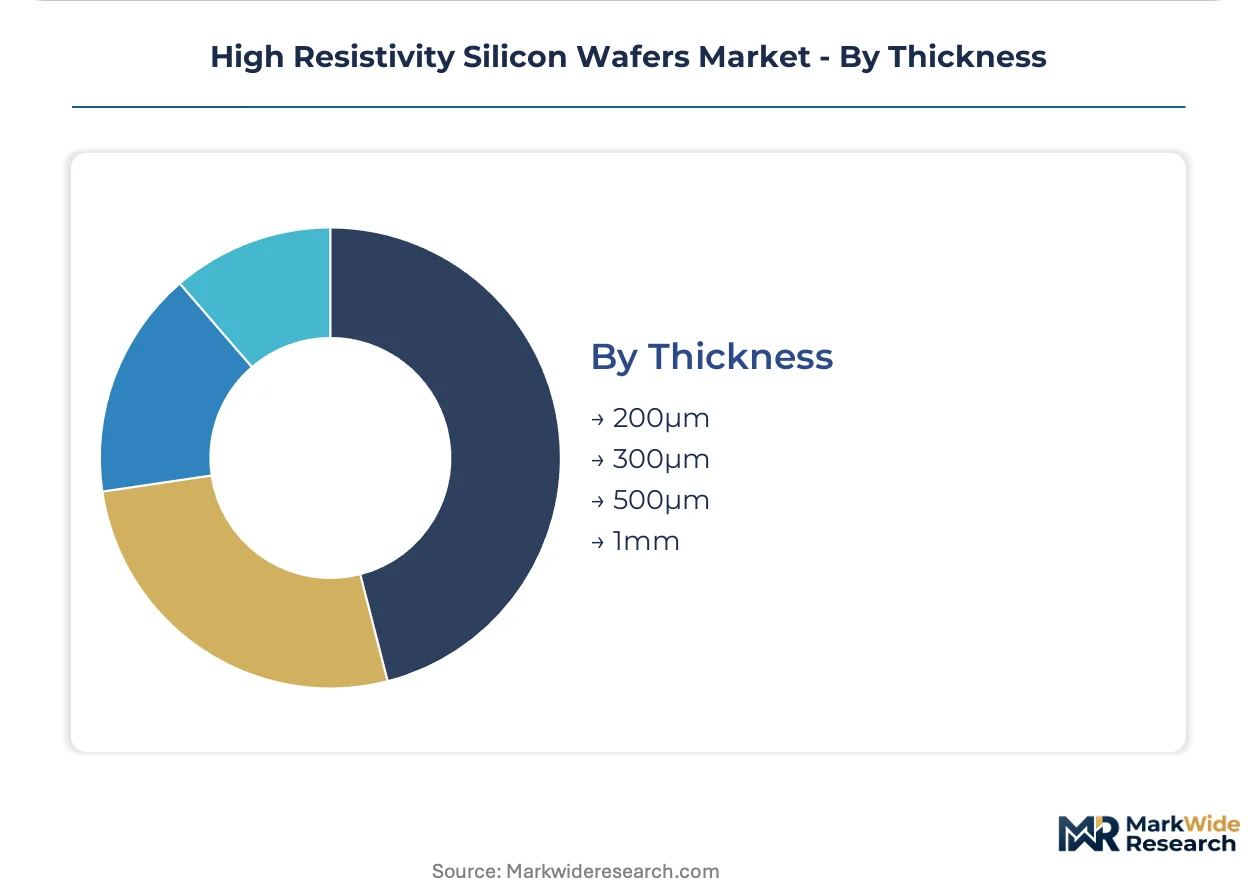
- 300µm:Standard thickness for 200mm and 300mm RF device wafers balancing mechanical robustness and material efficiency. Float-zone energy intensity for 300mm ingots elevates production costs in regions without subsidized industrial power.
- 500µm:Preferred for power amplifier substrates requiring enhanced thermal dissipation in base station applications.
- 200µm:Emerging specification for smartphone form-factor constraints.
- 1mm:Specialized thickness for high-power radar modules and test structures.
Shipment volume centers on 300µm; specification migration favors 200µm.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorosilane purification capacity in Japan and Germany anchors substrate-grade feedstock availability, while East Asian manufacturing clusters in Taiwan and South Korea pull volume for RF device fabrication.
Japan
Domestic 5G base station deployment and automotive radar programs drive demand for ultra-low-loss substrates. METI semiconductor revitalization policy directs subsidies toward 300mm float-zone capacity expansion. Tokyo and Osaka equipment makers redirect R&D toward domestic foundry supply after export control classifications restricted crystal growth furnace access.
Germany
European automotive radar initiatives at 77 GHz require thick epitaxial layers with extended reliability testing. ECHA REACH compliance and EU Green Deal carbon accounting reshape energy sourcing for polysilicon smelters. Bavarian chemical conglomerates maintain Siemens-process reactor dominance for semiconductor-grade feedstock purification.
Taiwan
RF front-end module foundries pull substrate volume through direct multi-year contracting with smartphone OEMs. The island's production-linked incentive frameworks support compound semiconductor fab development. Hsinchu Science Park anchors backward integration into crystal growth furnaces and expansive polishing lines.
South Korea
Sub-6 GHz power amplifier manufacturers adopt MCZ substrates, accepting resistivity trade-offs for improved mechanical yield. MFDS regulatory alignment with international semiconductor standards facilitates export qualification. Seoul and Busan manufacturing clusters concentrate RF device packaging and test operations.
China
Domestic wafer fabs face constrained access to advanced float-zone tools under foreign equipment export controls. MEE dual carbon disclosure mandates reshape energy sourcing decisions for polysilicon smelters. Yangtze River Delta manufacturing clusters pivot toward captive chlorosilane refining and renewable-powered ingot growth.
High Resistivity Silicon Wafers Market Competitive Environment
Global majors compete with regional champions across feedstock control and epitaxial deposition expertise. The vendor base concentrates among Japanese chemical conglomerates with captive chlorosilane refining, Taiwanese integrated fabricators, and European epitaxial specialists. Three archetypes dominate: backward-integrated feedstock owners, equipment-integrated scale producers, and deposition-technology specialists. Competitive moves center on multi-year foundry qualification contracts and furnace capacity expansion.
Within the feedstock-integrated tier, Shin-Etsu Chemical Co., Ltd. exemplifies captive chlorosilane refining advantages, while GlobalWafers Co., Ltd. represents equipment-integrated scale production across 200mm-300mm polishing lines. Siltronic AG occupies a position among epitaxial deposition specialists serving European automotive radar qualification programs.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| GlobalWafers Co., Ltd. |
| Siltronic AG |
| Wafer Works Corporation |
| Okmetic |
| Sumco Corporation |
| SK Siltron |
| Semiconductor Wafer Inc. |
| Soitec |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in Japan and Taiwan anchor supply-side discipline through METI-subsidized float-zone capacity and Hsinchu Science Park incentive frameworks, translating state financing into multi-year contract pricing power with RF foundries.
Pricing Analysis
Extended warranty and technical service bundling separates Shin-Etsu Chemical's captive chlorosilane supply contracts from spot-market polysilicon transactions. Three-tier pricing structure across premium float-zone, standard MCZ, and economy polycrystalline tiers reflects certification grade and volume scale differentiation. Cost compression in polycrystalline segments is intensifying because SOI substitution erodes sensor-application demand. Smartphone OEMs in Taiwan exhibit lowest price sensitivity due to direct multi-year substrate contracting, while cost-constrained sensor integrators face acute margin pressure.
Supply Chain Analysis
Japan's METI domestic-content mandates under semiconductor revitalization policy are reshaping sourcing toward Tokyo and Osaka equipment makers after export control classifications restricted crystal growth furnace access. Chlorosilane purification capacity concentrates in Japan and Germany, while RF device fabrication clusters in Taiwan and South Korea. Siemens-process reactor dependence creates single-source vulnerability for semiconductor-grade feedstock. Distribution runs through direct foundry contracting rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's METI export control regime functions as a cost-of-compliance moat, elevating qualification burdens for non-domestic equipment and hardening incumbent positioning through regulatory barrier construction.
For Market Incumbents: Acquire crystal growth furnace operators in Japan to secure captive equipment supply chains against METI foreign trade act restrictions. Defend margin position by accelerating 300mm float-zone capacity expansion before demographic technician scarcity intensifies. Prioritize multi-year foundry qualification contracts with South Korean power amplifier manufacturers adopting MCZ substrates.
For New Entrants and Emerging Players: India's Production-Linked Incentive scheme for compound semiconductors opens a window for high-resistivity silicon substrate qualification before established suppliers consolidate procurement relationships. Target automotive radar module designers in Europe facing elongated lead times from alternative qualification pathway constraints. Pursue direct technical partnership models with national laboratory 6G terahertz research programs in Finland and Japan.
For Investors and Strategic Acquirers: Distressed-cycle entries favor equipment-integrated scale producers in Taiwan with backward integration into crystal growth furnaces and expansive polishing lines. Long-term viability centers on five-to-ten year foundry demand alignment rather than spot-market commodity exposure. Monitor RF filter designer procurement signals as the inflection indicator for ingot pull schedule acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth Furnaces | GlobalWafers' Hsinchu equipment manufacturing secures capacity allocation priority during supply crunches. |
| Multi-Year Foundry Qualification Contracts | Direct OEM contracting with Taiwan smartphone manufacturers displaces fragmented distributor purchasing. |
| Green Manufacturing Transition | China's MEE dual carbon disclosure mandates favor renewable-powered ingot growth investments. |
| Epitaxial Deposition Technology Licensing | Siltronic's automotive radar expertise transfers yield optimization knowledge to 77 GHz module producers. |
| Joint Venture for 6G Terahertz Substrate Development | Finland and Japan national laboratory partnerships validate resistivity specifications above 10,000 ohm-cm. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF device procurement managers, float-zone furnace operators, epitaxial deposition engineers, and foundry supply chain directors combined with METI policy documents, EPA fluorinated gas emission reports, and semiconductor equipment trade data. Bottom-up wafer shipment tracking and top-down RF module production estimates provided triangulation validation.
Granularity-level modeling captured product type splits across single crystal, epitaxial, and polycrystalline tiers; end-use segmentation spanning telecommunications, automotive, and consumer electronics; and thickness specifications from 200µm to 1mm. CAGRs derived from foundry demand signal correlation with ingot pull schedules across the analysis window. Forecast inputs incorporated METI subsidy disbursement trajectories and 6G terahertz research program validation timelines.
The model assumes a particular technology adoption path; alternative pathways for silicon-on-insulator substitution in sensor applications would alter the outlook. Forecasts reflect assumptions about chlorosilane purification capacity expansion and export control regime persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
FPGA Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Asia-Pacific MLCC Market