
 Low Voltage AC Drive Market | 2026-2036
Low Voltage AC Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage AC Drive Market Foresight
EU Ecodesign Directive revisions are shifting the cost-of-entry calculus for low voltage AC drive suppliers by mandating minimum efficiency classes for motor-driven systems. ABB leverages its integrated powertrain portfolio to capture premium retrofit cycles in European process industries. Siemens sustains technology leadership through digital twin integration with its drive platforms. Danfoss anchors market position in HVAC and refrigeration compressor applications through specialized control algorithms.
Low voltage AC drives are power conversion devices that adjust motor speed and torque by varying input frequency and voltage, typically operating below 690V AC to optimize energy consumption in rotating equipment. These systems employ insulated-gate bipolar transistor switching and pulse-width modulation techniques to deliver precise motor control across industrial processes. VFD technology dominates installed capacity due to its proven energy savings in centrifugal load applications, while servo drives command higher margins in precision positioning segments. Vector control architectures are displacing scalar methods in demanding torque-response environments, particularly in manufacturing conveyor systems where dynamic performance directly affects throughput.
The US Department of Energy enforces motor efficiency standards under EPACT and subsequent rulemakings that directly accelerate drive adoption for compliance retrofitting. China's MIIT implements GB standards for motor system energy conservation that mandate variable speed controls in designated industrial equipment. Japan's METI Top Runner program extends efficiency benchmarking to motor-drive packages, shaping product development priorities for suppliers serving Asian industrial markets. Stakeholders must evaluate regulatory trajectory alignment against technology refresh cycles to optimize capital deployment timing.
Market Dynamics
Variable frequency drive architecture is fragmenting across distributed control topologies as industrial facilities displace centralized motor control rooms with edge-mounted drive units, compressing installation costs and rewiring industrial power distribution hierarchies.
Growth Catalysts
- EU Ecodesign Directive:Mandatory motor system efficiency classes are compelling retrofit cycles across German and French process industries, accelerating premium drive replacement demand.
- Pump station modernization:Water treatment utilities in China's eastern manufacturing corridor are deploying variable speed controls to cut centrifugal load energy consumption by double-digit percentages.
- Silicon carbide (SiC) switching:Next-generation power semiconductor integration is reducing drive thermal losses and enabling higher switching frequencies for precision motor control applications.
Market Restraints
- IGBT supply concentration:Power module fabrication capacity concentrates in East Asian foundries, exposing European and North American drive assemblers to semiconductor allocation volatility.
- Copper and rare earth magnet costs:Motor-drive package input material price swings compress OEM margin stability and complicate long-term project bidding.
- Scalar control legacy lock-in:Existing V/f-controlled installations in mature industrial bases resist vector control upgrades due to rewiring and parameterization complexity.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for industrial automation are attracting drive suppliers to establish local assembly for domestic and export markets.
- Digital twin convergence:Real-time drive telemetry integration with asset performance management platforms is opening recurring software revenue streams in predictive maintenance.
- HVAC-R compressor specialization:Refrigeration system OEMs seek algorithm-optimized drives for low-GWP refrigerant handling under evolving F-Gas Regulation phase-down schedules.
Industry Challenges
- Power electronics engineering scarcity:Shortages of specialists capable of thermal management and EMI mitigation design are extending product development cycles.
- Functional safety certification timelines:IEC 61800-5-2 safe torque off and safe stop implementations require extended validation periods that delay new product introductions.
- Legacy fieldbus integration:Retrofitting modern Ethernet-based drive communications into existing PROFIBUS-DP and DeviceNet plant architectures demands costly protocol gateway deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage AC Drive Market |
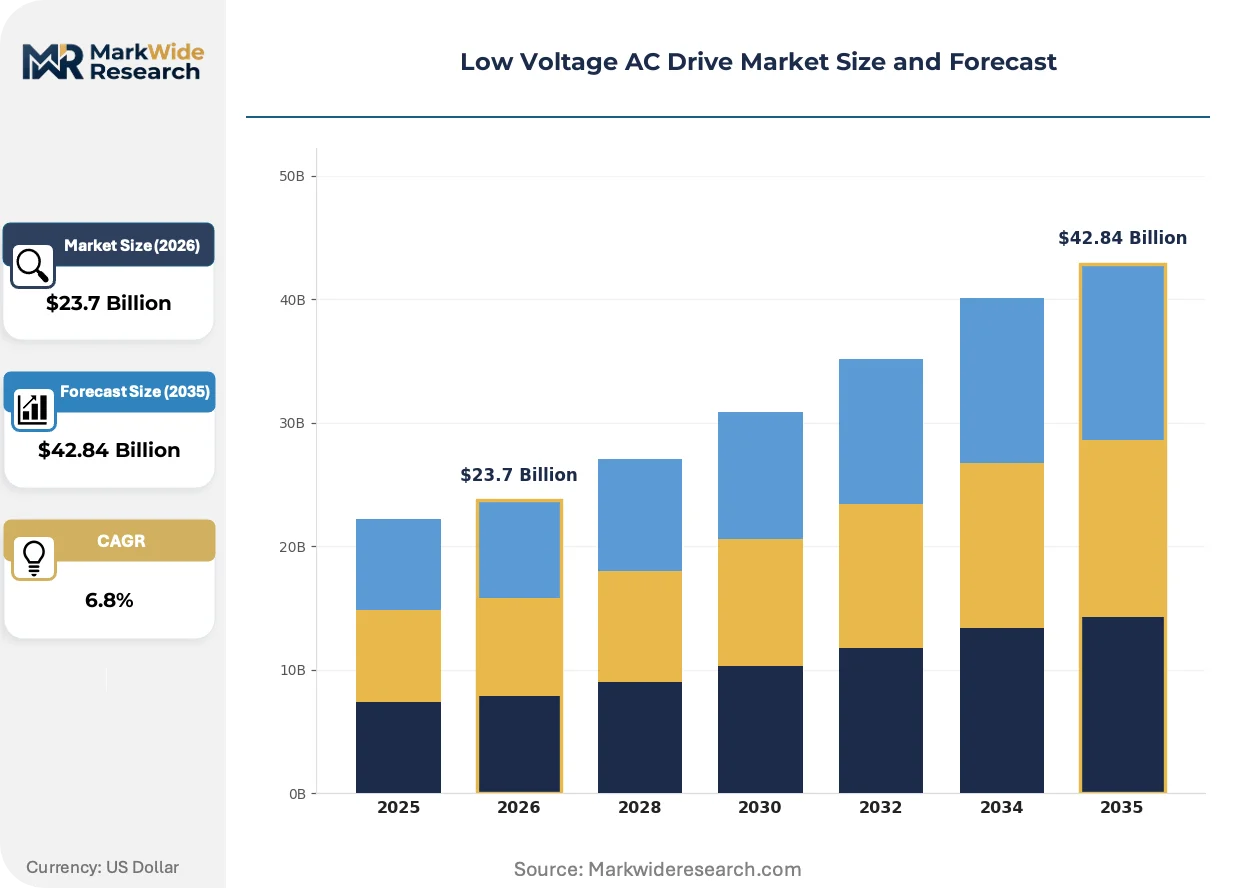
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverters, Controllers, Converters, Soft Starters Technology: VFD, Servo, Vector Control, Scalar Control End User: Manufacturing, Energy, Water Treatment, HVAC Application: Pumps, Fans, Compressors, Conveyors |
| Companies Covered | ABB, Danfoss, Siemens, Schneider Electric, Fuji Electric, Rockwell Automation, Delta Electronics, WEG, Yaskawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage AC Drive Market Shifts & Advancements
Power electronics integration and control software architecture are converging to redefine how motor-drive systems are specified, installed, and monetized across industrial verticals.
Edge computing capability embedded directly within drive enclosures is decentralizing motion control intelligence away from centralized PLCs. Packaging machinery OEMs in Germany and Italy are adopting these integrated controllers to eliminate separate automation hardware and reduce panel footprint. This topology compresses commissioning timelines and shifts value capture toward drive-embedded software licensing.
China's MIIT GB standards for motor system energy conservation are tightening enforcement scope to cover previously exempt equipment categories. Industrial facilities in Shandong and Jiangsu provinces face compliance deadlines that mandate variable speed retrofitting or replacement. Drive suppliers are responding with localized product lines optimized for regional grid conditions and thermal environments.
After-sales service unbundling is accelerating as end-users separate hardware procurement from commissioning and maintenance contracts. Large process operators in the US Gulf Coast petrochemical corridor now source drives through distributors while negotiating multi-year performance agreements directly with manufacturer service divisions. This bifurcation is compressing distributor margins while expanding recurring revenue pools for OEM technical service organizations.
Low Voltage AC Drive Market Segmentation
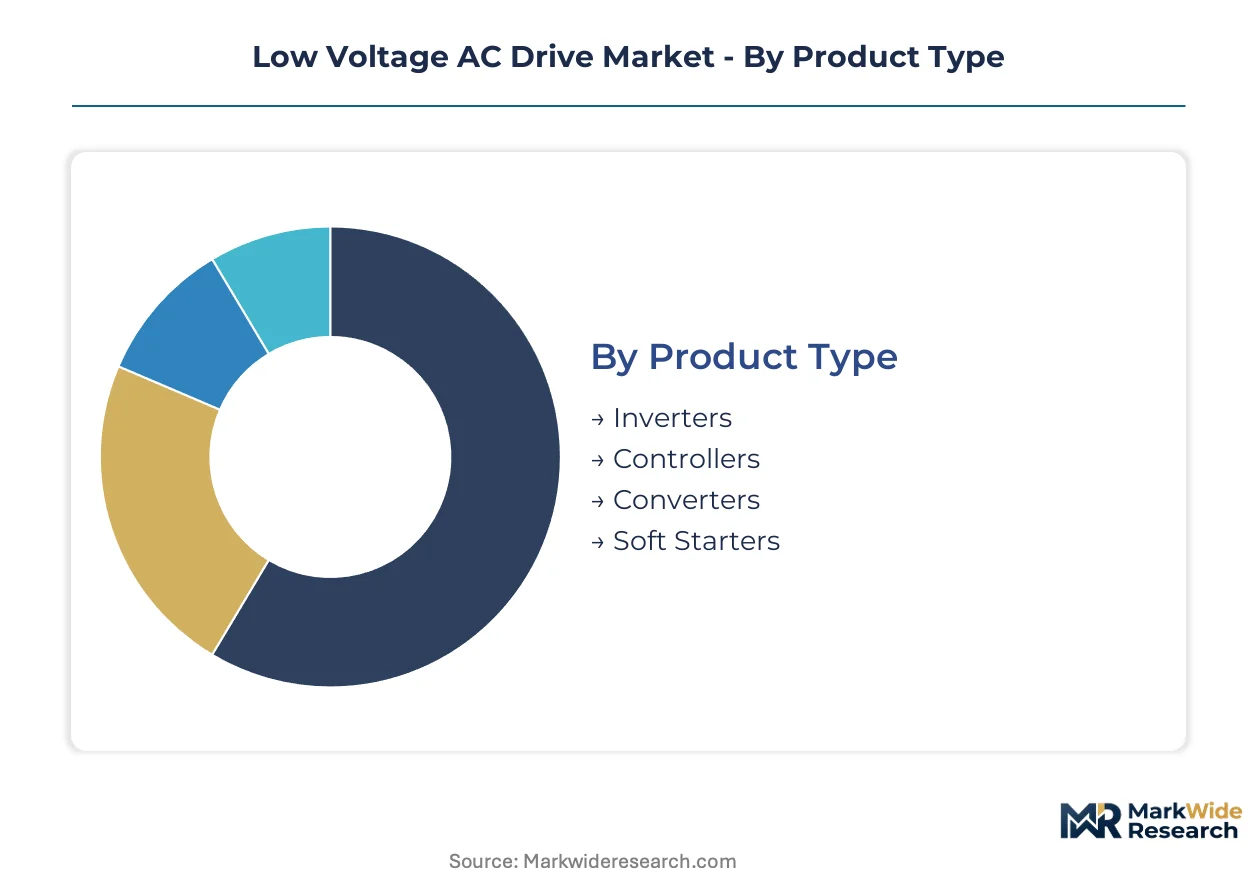
Low voltage AC drive segmentation reflects divergent technical requirements across power conversion architectures, control methodologies, and load-specific applications. Supplier portfolios must align with distinct efficiency mandates, precision demands, and retrofit compatibility constraints that vary sharply by industrial vertical.
Product Type:
Power conversion hardware segments differentiate by functional role in motor energy management, with thermal design and switching topology determining suitability for specific load profiles.
- Inverters:DC-to-AC conversion modules employing IGBT or SiC switching arrays dominate installed base volume. Water treatment utilities in China's eastern manufacturing corridor specify these for centrifugal pump energy recovery, driven by MIIT GB standards enforcement.
- Controllers:Embedded logic platforms with integrated PLCs and motion sequencing capability command premium positioning. German packaging machinery OEMs adopt controller-integrated drives to eliminate separate automation hardware and compress panel footprint.
- Converters:AC-to-DC rectification stages with active front-end regeneration support bidirectional power flow for high-duty-cycle applications.
- Soft Starters:Reduced-voltage motor starting equipment addresses legacy fixed-speed installations where full VFD retrofit cost cannot be justified.
Mature deployment sits with inverters. Newer deployment is concentrated in controllers with integrated edge computing capability.
Technology:
Control architecture selection governs torque response precision, with scalar methods yielding to vector approaches in dynamic load environments.
- VFD:Variable frequency drive platforms using pulse-width modulation deliver proven energy savings in centrifugal pump and fan applications. US municipal water authorities deploy VFD retrofits under EPACT motor efficiency compliance timelines.
- Servo:Closed-loop position control systems with resolver or encoder feedback command higher margins in precision manufacturing. Japanese automotive component suppliers specify servo drives for robotic assembly cells under METI Top Runner efficiency benchmarking.
- Vector Control:Field-oriented algorithms enabling independent torque and flux control displace scalar methods in conveyor systems demanding rapid dynamic response.
- Scalar Control:Legacy V/f control maintains presence in cost-sensitive HVAC fan applications where torque precision requirements remain minimal.
Scalar control dominates legacy installed base. Vector control and servo architectures are gaining share fastest in new manufacturing automation investments.
End User:
Vertical-specific regulatory pressure and energy cost exposure determine technology specification intensity and replacement cycle velocity.
- Manufacturing:Factory automation and process industries drive demand for integrated motion control with digital twin connectivity. EU Ecodesign Directive revisions compel German and French process industries into premium drive retrofit cycles.
- Energy:Oil and gas, power generation, and renewable integration applications require ruggedized enclosures and grid-forming capability. US Gulf Coast petrochemical operators unbundle hardware procurement from multi-year performance agreements.
- Water Treatment:Municipal and industrial pumping infrastructure prioritizes energy-efficient variable speed operation. China's Shandong and Jiangsu provinces face MIIT compliance deadlines mandating variable speed retrofitting.
- HVAC:Commercial building climate control and refrigeration systems seek algorithm-optimized compressor handling. F-Gas Regulation phase-down schedules in Europe drive low-GWP refrigerant-compatible drive specification.
Established volume concentrates in manufacturing. Steepest expansion trajectory appears in water treatment as infrastructure modernization accelerates across Asia-Pacific municipalities.
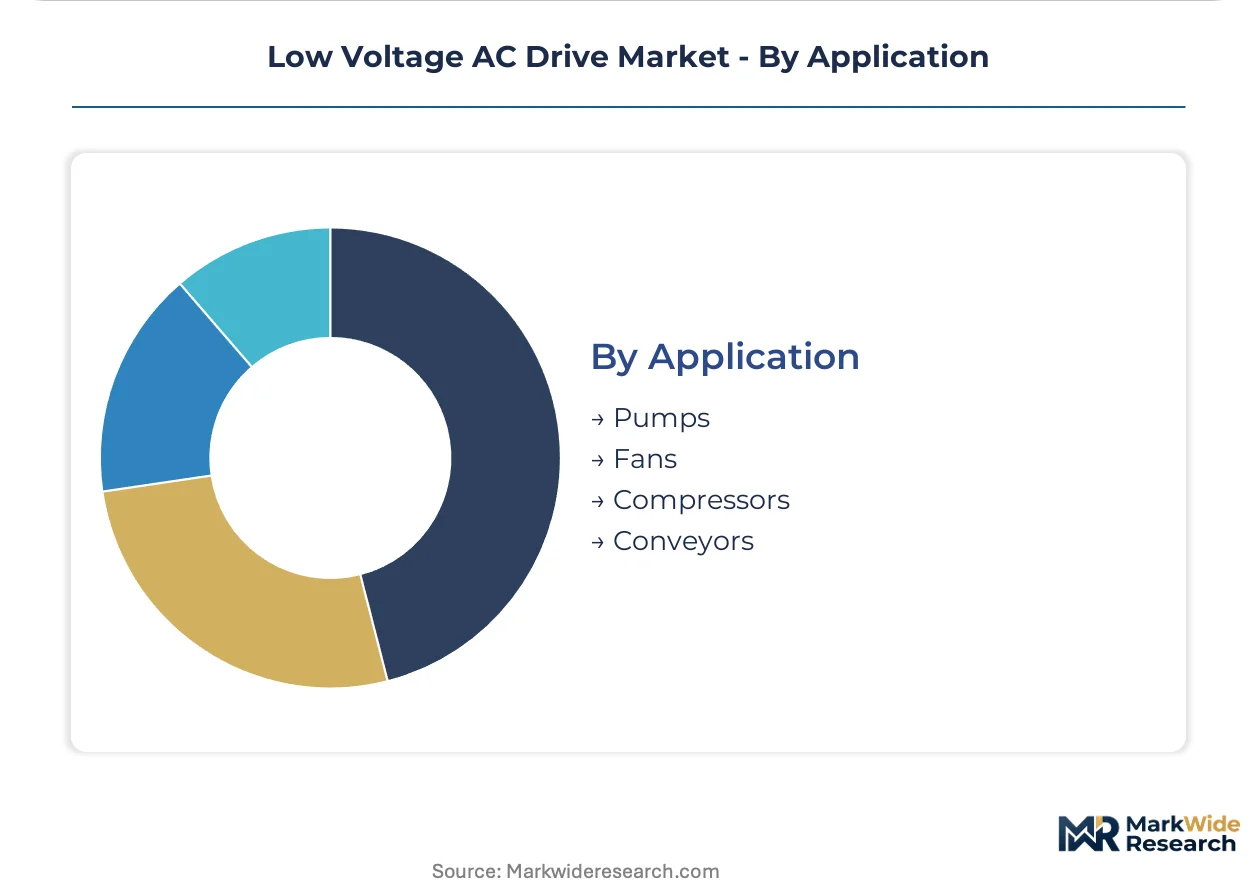
Application:
Load mechanical characteristics dictate drive specification for torque profiles, acceleration requirements, and energy recovery potential.
- Pumps:Centrifugal and positive displacement pump control represents the largest addressable load category. Variable speed deployment cuts energy consumption by double-digit percentages in China's eastern manufacturing corridor water utilities.
- Fans:Aerodynamic load control with cubic power-speed relationships delivers compelling payback periods in ventilation and combustion air applications.
- Compressors:Rotary and reciprocating compression equipment demands specialized algorithms for surge protection and capacity modulation. Refrigeration OEMs seek optimized drives for low-GWP refrigerant handling under evolving European regulation.
- Conveyors:Material handling systems require precise torque control for load sharing and emergency stopping. Vector control architectures displace scalar methods where dynamic performance directly affects throughput.
Pump applications anchor historical deployment. Compressor specialization is expanding most quickly with HVAC-R refrigerant transition pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor operates as the dominant tax-incentive zone concentrating variable frequency drive deployment. Factory automation investments across Shandong and Jiangsu provinces attract suppliers establishing localized assembly lines. Germany's industrial heartland anchors European retrofit demand through Ecodesign Directive enforcement timelines.
China
Water treatment utilities in Shandong province deploy variable speed controls for centrifugal pump energy recovery. MIIT GB standards enforcement mandates variable speed retrofitting across previously exempt equipment categories. Manufacturing clusters in Jiangsu province face compliance deadlines accelerating premium drive replacement cycles.
Germany
Process industries in the Ruhr region and Bavaria execute premium retrofit cycles under EU Ecodesign Directive efficiency mandates. The Federal Environment Agency tightens motor system efficiency class requirements for industrial equipment. Packaging machinery OEMs in Baden-Württemberg adopt controller-integrated drives to compress panel footprint.
United States
Municipal water authorities across the Gulf Coast petrochemical corridor unbundle hardware procurement from multi-year performance agreements. The Department of Energy enforces EPACT motor efficiency standards accelerating compliance retrofitting. Texas and Louisiana process operators negotiate service contracts directly with manufacturer technical divisions.
India
Production-linked incentives for industrial automation attract drive suppliers establishing local assembly for domestic and export markets. The Ministry of Heavy Industries implements phased manufacturing programs for power electronics components. Manufacturing investments concentrate in Gujarat and Maharashtra where factory modernization programs accelerate.
Japan
Automotive component suppliers specify servo drives for robotic assembly cells under METI Top Runner efficiency benchmarking. The Ministry of Economy, Trade and Industry extends efficiency standards to motor-drive packages. Industrial facilities in the Nagoya and Osaka manufacturing belts prioritize precision positioning equipment for assembly automation.
Low Voltage AC Drive Market Competitive Landscape
European producers anchor one tier; East Asian specialists hold manufacturing scale advantages in power module integration. The supplier base concentrates around integrated powertrain portfolios and digital twin-enabled platforms. Three archetypes dominate: diversified industrial conglomerates with full automation stacks, power electronics pure-plays with semiconductor advantages, and regional champions serving protected domestic markets. Competitive moves center on silicon carbide switching integration and after-sales service unbundling.
Within the diversified industrial tier, ABB leverages its integrated powertrain portfolio to capture premium retrofit cycles. Siemens sustains technology leadership through digital twin integration with drive platforms. Danfoss anchors market position in HVAC and refrigeration compressor applications through specialized control algorithms.
| Leading Market Players |
|---|
| ABB |
| Danfoss |
| Siemens |
| Schneider Electric |
| Fuji Electric |
| Rockwell Automation |
| Delta Electronics |
| WEG |
| Yaskawa Electric |
| Others |
Supply & Pricing Matrix
Power electronics engineering talent concentrates in Germany's Baden-Württemberg and Bavaria regions, where thermal management and EMI mitigation specialists command wage premiums that widen spreads between premium-tier vector control drives and economy scalar units. Labor-cost differentials between these engineering clusters and East Asian assembly operations create pricing-tier stratification that OEMs exploit across European and Asia-Pacific market segments.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium rates attaching to sub-four-week delivery commitments while spot inventory from distributors clears at discounted levels. Pricing stratifies across premium, standard, and economy tiers differentiated by certification grade and after-sales service bundling. Cost compression in economy-tier scalar drives intensifies because of copper and rare earth magnet price volatility. Municipal water authorities exhibit highest price sensitivity due to public procurement constraints, while German process industries demonstrate lowest sensitivity given Ecodesign Directive compliance imperatives.
Supply Chain Analysis
Reverse-logistics flows for drive refurbishment and remanufacturing are expanding as European operators extend asset life under circular economy mandates. IGBT and SiC power module fabrication concentrates in China, South Korea, and Japan, anchoring upstream supply. Drive assembly draws from copper busbar suppliers in Germany, enclosure fabricators in Mexico, and capacitor manufacturers in Taiwan. Single-source vulnerability around SiC wafer supply poses structural risk. Distribution runs through authorized distributors serving OEM procurement teams and direct manufacturer channels for large process operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where semiconductor allocation volatility and functional safety certification burdens are forcing sub-scale power electronics pure-plays toward exit or acquisition.
For Market Incumbents: Cement technology leadership through captive SiC switching supply arrangements with East Asian foundries. Expand service organization headcount in the US Gulf Coast petrochemical corridor to capture unbundled performance agreement revenue. Vector control algorithm R&D investment defends against emerging Chinese controller-integrated drive suppliers. For New Entrants and Emerging Players: Enter via India's PLI scheme production-linked incentive zones in Gujarat and Maharashtra, where local assembly requirements create protected demand pools. Target water treatment retrofit cycles in China's Shandong province as the most penetrable geography given MIIT compliance deadline concentration. Pursue OEM private-label partnerships with European HVAC-R compressor manufacturers seeking low-GWP refrigerant-optimized control algorithms. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given silicon carbide switching integration catalysts accelerating product refresh cycles. Five-to-ten-year viability favors suppliers with in-house power module packaging capability and digital twin software recurring revenue streams. Monitor IGBT spot pricing indices and MIIT enforcement timeline announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Switching Integration | Reduces thermal losses for precision motor control applications under EU Ecodesign Directive efficiency mandates. |
| Digital Twin Platform Convergence | Captures recurring software revenue from predictive maintenance contracts with German packaging machinery OEMs. |
| India PLI Scheme Local Assembly | Establishes tariff-advantaged production base for domestic Indian demand and Middle East export markets. |
| After-Sales Service Unbundling | Expands technical service division margins by separating hardware procurement from multi-year performance agreements. |
| HVAC-R Compressor Algorithm Specialization | Addresses low-GWP refrigerant handling requirements under evolving European F-Gas Regulation phase-down schedules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and power electronics R&D directors combined with secondary validation from MIIT GB standard publications, EU Ecodesign Directive implementation reports, and US Department of Energy EPACT rulemaking documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology, and end user segmentation dimensions.
Granularity-level modeling operated at the country-regulator-technology intersection, with separate CAGRs derived for VFD versus servo versus vector control architectures across the projection horizon. Segmentation dimensions included power conversion hardware type, control methodology, industrial vertical, and regional regulatory cluster. Forecast inputs incorporated motor efficiency standard enforcement timelines, factory automation investment patterns, and power semiconductor supply availability assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation disruptions or accelerated EU Ecodesign Directive revision schedules. Forecasts reflect documented assumptions regarding MIIT enforcement intensity and SiC module cost reduction trajectories. Practitioners should monitor F-Gas Regulation amendment proposals and India's PLI scheme phase extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
AC DC Power Adapter Market
Power Systems
Power Semiconductor Market
Power Systems
Synchrophasors Market
Power Systems
Pulse Generator Market
Power Systems
Charge Controller System Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
South America DC Distribution Network Market
Power Systems
Bypass Thyristor Market
Power Systems
EV Power Module Market
Power Systems
Converter Modules Market
Power Systems
Grid Forming Inverters Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
BCD Power IC Market
Power Systems
Global Plasma Generators Market