
 Asia Pacific Motherboard Market | 2026-2036
Asia Pacific Motherboard Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Motherboard Market Outlook
Enterprise server procurement among hyperscale data center operators is consolidating, narrowing the vendor base for high-reliability boards. ASUSTeK Computer Inc. leverages its R&D intensity across gaming and workstation tiers to maintain design leadership. Super Micro Computer Inc. anchors the server segment through manufacturing scale and direct-to-datacenter channel control. Gigabyte Technology Co., Ltd. competes aggressively in cloud infrastructure partnerships across Taiwan and South Korea.
A motherboard serves as the central printed circuit board interconnecting CPU, memory, storage, and peripheral subsystems via standardized buses and power delivery networks, typically fabricated on multi-layer FR-4 substrates with impedance-controlled traces for signal integrity above 5 GHz. Its primary purpose is to provide the electrical and mechanical foundation for computing systems ranging from embedded controllers to multi-socket servers. The ATX and Micro ATX product types dominate volume shipments due to established chassis ecosystem compatibility, while Mini ITX sustains premium pricing in compact workstation and edge server deployments where density constraints override expansion requirements. Server-class end users command the highest absolute spending, though gaming-oriented buyers generate superior margin per unit through bundled chipset differentiation and aesthetic customization.
China's MIIT enforces GB standards for electromagnetic compatibility and hazardous substance limits that constrain board material selection and manufacturing process chemistry. Taiwan's Bureau of Standards, Metrology and Inspection aligns with IEC frameworks for IT equipment safety, creating dual compliance obligations for cross-strait supply chains. India's BIS mandatory registration scheme for electronic goods is extending certification timelines for imported motherboards, altering market entry economics. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for IT hardware reshape regional manufacturing location decisions and component sourcing hierarchies.
Market Dynamics
Hyperscale data center operators are consolidating server procurement among fewer vendors, compressing design cycles and forcing motherboard suppliers to absorb validation costs previously borne by fragmented enterprise buyers across China, Taiwan, and South Korea.
Growth Catalysts
- GB Standards Compliance:China's MIIT enforcement of electromagnetic compatibility mandates is accelerating board redesigns toward higher-layer count substrates that command premium positioning.
- Cloud Infrastructure Expansion:Hyperscale operators in Taiwan's Hsinchu Science Park corridor are deploying multi-socket server configurations requiring specialized power delivery networks.
- Dual Carbon Goals:Beijing's energy efficiency targets are pulling demand toward low-power chipset architectures that reduce thermal design complexity.
Market Restraints
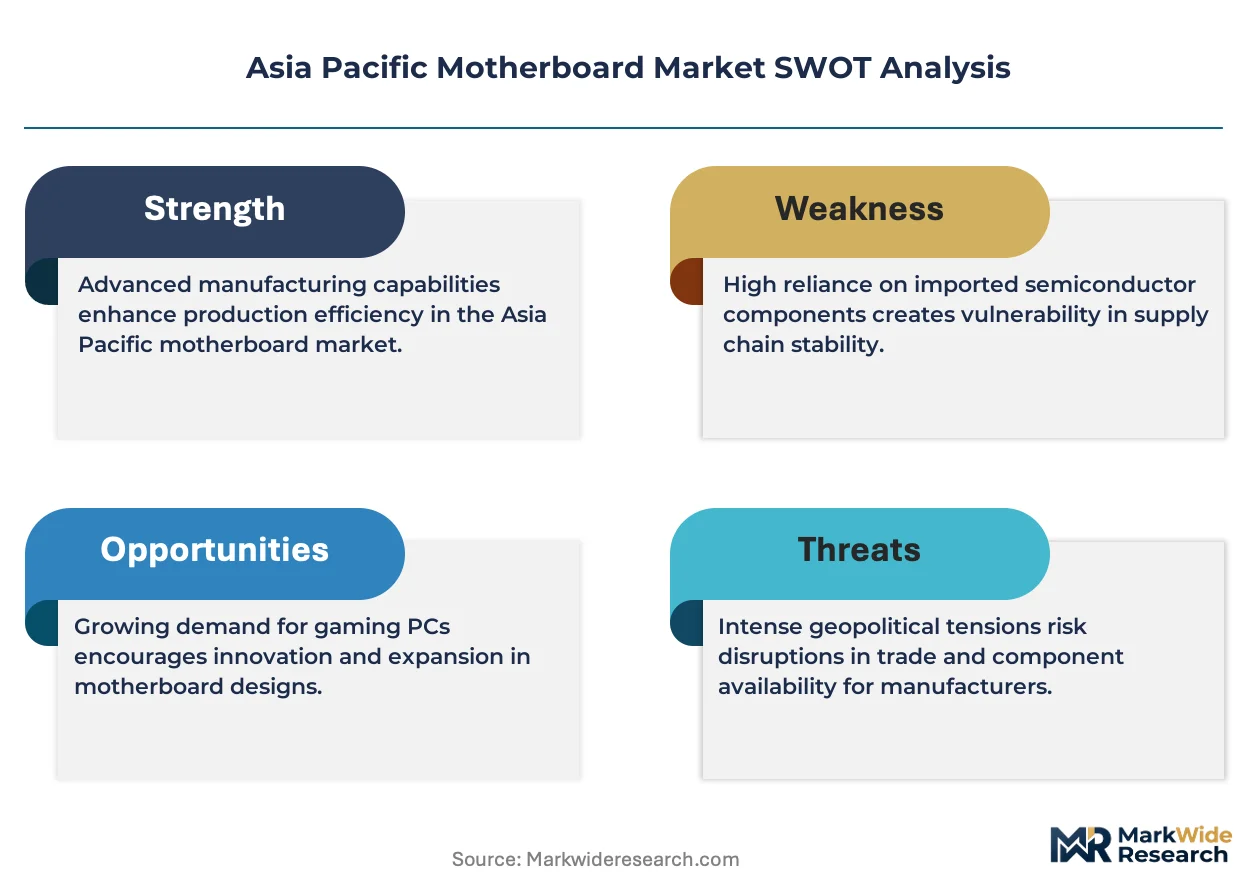
- Substrate Material Concentration:Ajinomoto Build-up Film and high-grade FR-4 resin supply concentrates among Japanese and Korean chemical suppliers, exposing cost volatility.
- Cross-Strait Logistics Friction:Taiwan Strait shipping lanes carry concentrated motherboard volume, creating single-point vulnerability for Guangdong assembly plants.
- Copper Trace Density Limits:Signal integrity requirements above 5 GHz are bumping against current etching precision thresholds without costly migration to alternative substrates.
Strategic Opportunities
- India PLI Scheme:New Delhi's production-linked incentive framework for IT hardware is creating greenfield motherboard assembly capacity outside established China-Taiwan corridors.
- Edge Server Deployments:Mini ITX form factors are capturing traction in 5G base station and smart factory installations across South Korea's manufacturing belts.
- PCIe 6.0 Convergence:The interface standard's integration with CXL memory pooling architectures is opening socket design contracts for next-generation datacenter builds.
Industry Challenges
- Signal Integrity Engineering Talent:The pool of designers capable of impedance-controlled routing above 8 GHz remains thin relative to project pipelines in Taiwan and China.
- BIS Certification Timelines:India's mandatory registration scheme is extending market entry cycles by 4-6 months for imported boards, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Motherboard Market |
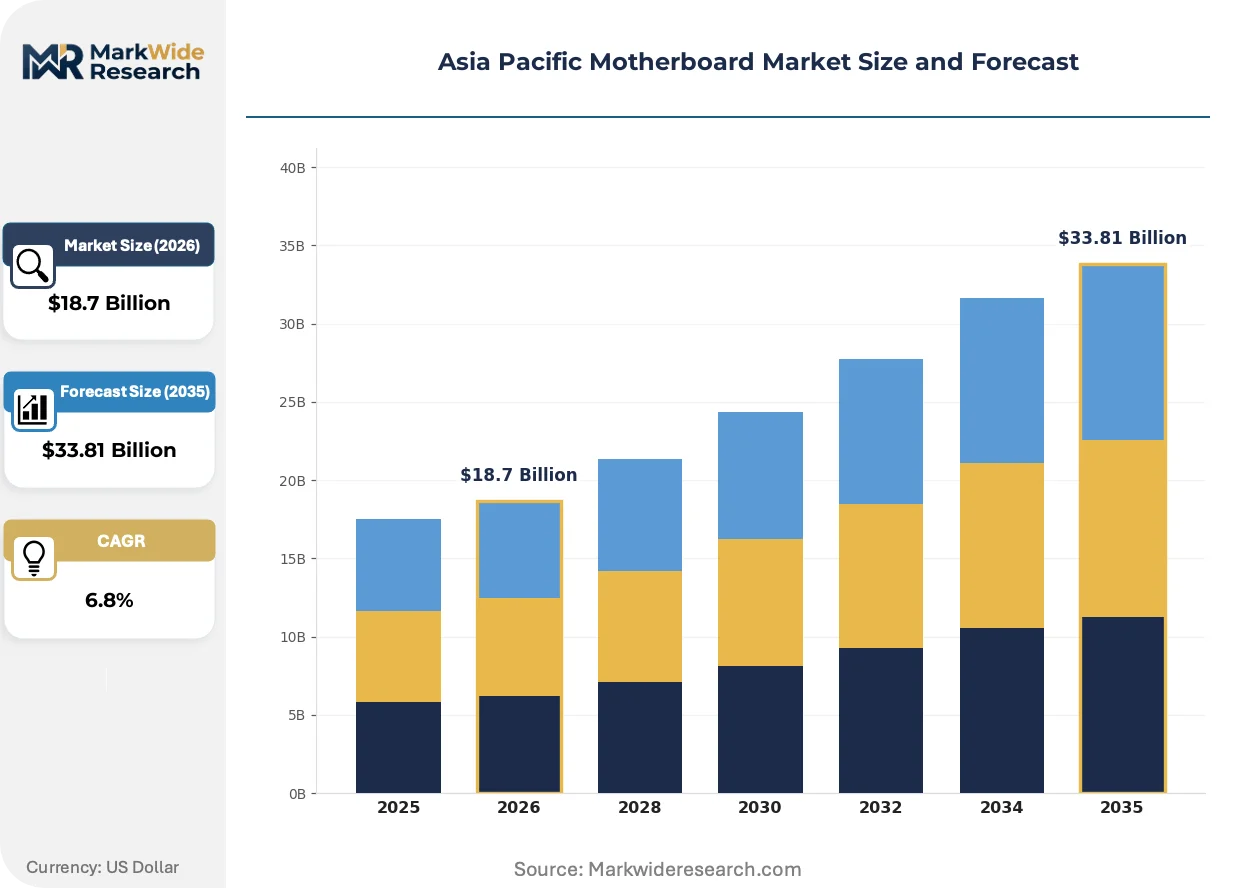
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATX, Micro ATX, Mini ITX, E-ATX End User: Gaming, Workstation, Server, Consumer Electronics Connectivity: USB-C, HDMI, Ethernet, SATA Form Factor: Standard, Custom, Embedded, Hybrid |
| Companies Covered | ASUSTeK Computer Inc., Gigabyte Technology Co., Ltd., Micro-Star International Co., Ltd. (MSI), ASRock Inc., Super Micro Computer Inc., Advantech Co., Ltd., Biostar Microtech International Corp., Intel Corporation, AMD (Advanced Micro Devices, Inc.), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Motherboard Market Strategic Shifts
Signal routing architectures and power delivery topologies are undergoing forced evolution as datacenter thermal budgets tighten and memory bandwidth demands scale nonlinearly with AI workload penetration.
High-density interconnect substrates are expanding into mainstream server deployments. These multi-layer structures with microvia stacking enable finer pitch BGA footprints essential for next-generation CPU packages. Hyperscale operators in Taiwan and South Korea are qualifying such designs for 2025 platform refreshes. The technology is expanding into mid-tier server segments previously served by standard HDI constructions.
China's GB 4943.1-2022 safety standard for electronic equipment is mandating reinforced insulation barriers and fire enclosure ratings that alter PCB stack-up designs. The regulation forces additional prepreg layers and modified copper weight specifications. Server-class boards destined for domestic Chinese deployment face the strictest compliance timelines.
Direct-to-datacenter channel models are displacing traditional distribution tiers. Hyperscale buyers in Guangdong province and Singapore are negotiating frame agreements that bypass regional distributors entirely. This pattern concentrates volume among vertically integrated contract manufacturers with captive motherboard design capabilities.
Asia Pacific Motherboard Market Segmentation
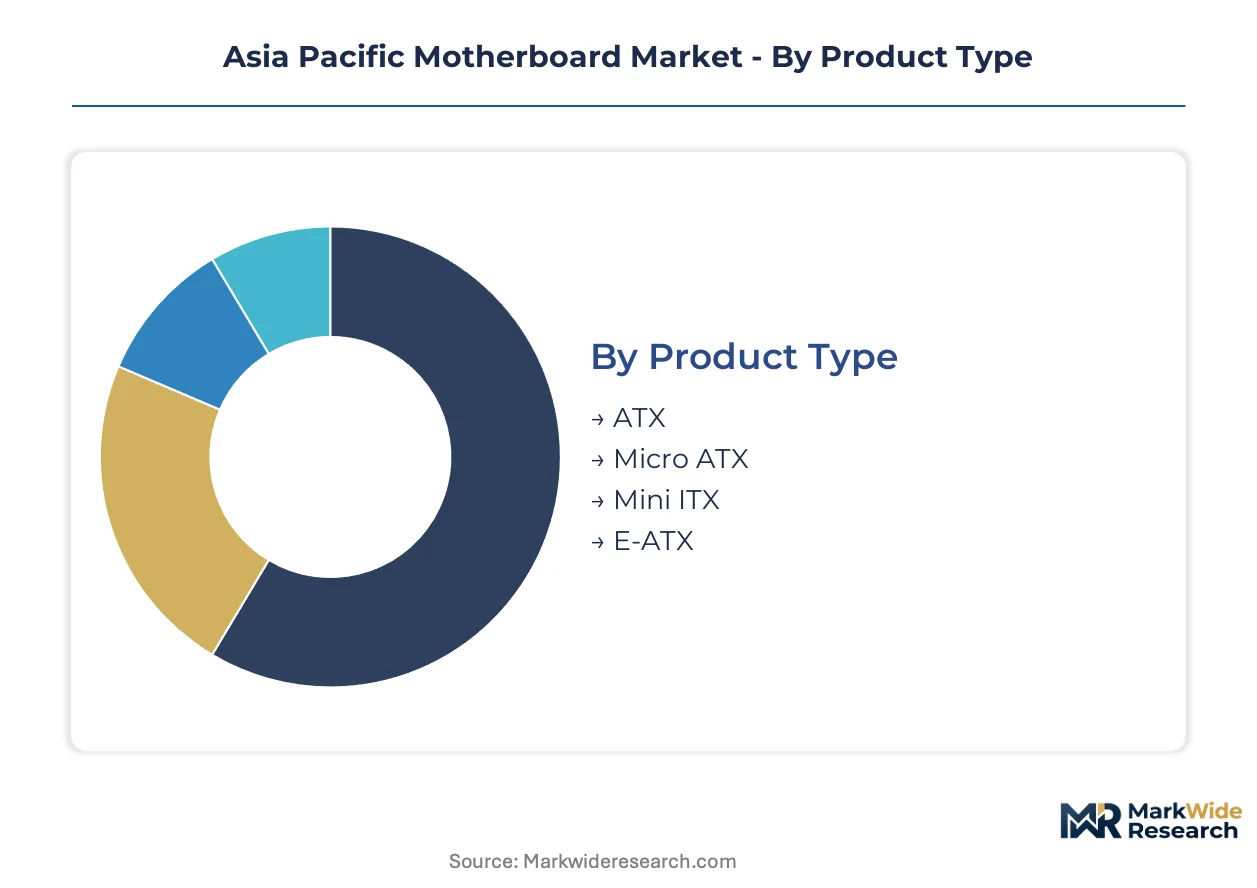
Motherboard segmentation in Asia Pacific reflects divergent thermal budgets, expansion requirements, and channel economics across computing tiers. Form factor and connectivity specifications determine chassis compatibility and signal integrity margins, while end-use differentiation drives power delivery topology selection.
Product Type:
Physical dimensions and expansion slot configurations anchor procurement decisions across consumer, commercial, and infrastructure tiers.
- ATX:Twelve-inch by 9.6-inch dimensions accommodate four memory slots and multiple PCIe expansion lanes. Volume concentrates in Guangdong province gaming system integrators where chassis ecosystem standardization reduces BOM validation overhead.
- Micro ATX:Compressed 9.6-inch square footprint retains dual-channel memory support while sacrificing expansion slots. Corporate desktop refresh cycles across Taiwan's Taichung manufacturing corridor favor this balance of cost and upgrade headroom.
- Mini ITX:6.7-inch square form factor with single expansion slot targets thermal-constrained deployments.
- E-ATX:Extended 12-inch by 13-inch dimensions serve multi-socket server configurations with enhanced power phase arrays.
Mature deployment sits with ATX. Newer deployment is concentrated in Mini ITX.
End User:
Workload intensity and uptime requirements differentiate power delivery, component durability, and validation rigor across buyer categories.
- Server:Multi-socket configurations with redundant power inputs and IPMI remote management interfaces. Hyperscale operators in Taiwan's Hsinchu Science Park corridor specify 24-phase voltage regulator modules for AI training workloads.
- Gaming:RGB header integration and enhanced VRM cooling distinguish premium SKUs. South Korean PC bang operators and Chinese streaming content creators drive refresh velocity through aesthetic differentiation.
- Workstation:ECC memory support and professional GPU certification dominate specification sheets.
- Consumer Electronics:Cost-optimized single-channel designs with minimal expansion capability.
Margin concentration sits with Gaming. Volume expansion is climbing fastest in Server.
Connectivity:
Interface bandwidth and protocol support determine peripheral compatibility and external display capability across deployment contexts.
- USB-C:Alternate Mode DisplayPort and power delivery up to 100W consolidate docking functionality. South Korean enterprise fleet managers specify this for hot-desking flexibility in Seoul financial district deployments.
- Ethernet:2.5GbE and 10GbE controllers differentiate workstation and server tiers. Taiwan's datacenter operators require dual-port configurations for link aggregation in Hsinchu server farms.
- HDMI:Consumer display connectivity with HDCP content protection.
- SATA:Legacy storage interface maintaining compatibility with installed hard drive populations.
Legacy retention sits with SATA. Capability expansion is gaining share fastest in USB-C.
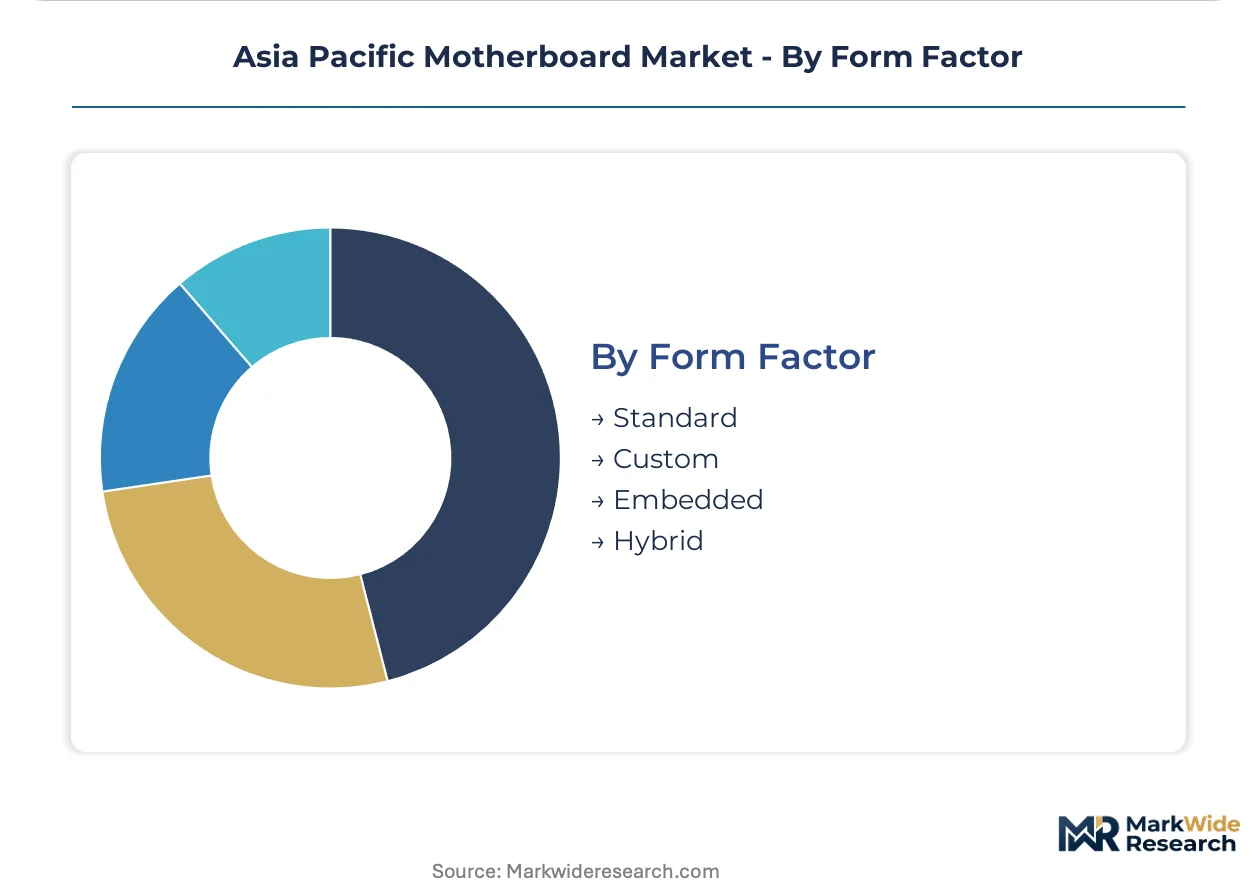
Form Factor:
Mechanical standardization versus application-specific optimization shapes manufacturing scale and design reuse economics.
- Standard:ATX, Micro ATX, and Mini ITX dimensions adhering to Intel and AMD reference specifications. China's Shenzhen assembly ecosystem achieves lowest unit costs through component commoditization and shared tooling across brands.
- Custom:Non-standard dimensions and proprietary mounting patterns. Taiwan's industrial automation OEMs commission these for compact controller enclosures in Taichung smart factory installations.
- Embedded:Soldered CPU configurations with passive cooling and extended temperature ratings.
- Hybrid:Modular baseboards with compute daughtercards enabling socket generation upgrades.
Volume concentration sits with Standard. Design flexibility is expanding most quickly in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade FR-4 resin and Ajinomoto Build-up Film supply from Japanese and Korean chemical suppliers anchors motherboard manufacturing economics across the Asia Pacific region. Taiwan's semiconductor fabrication dominance and China's Guangdong assembly ecosystem create interdependent production corridors. Regulatory divergence between MIIT's GB standards and Taiwan's IEC-aligned frameworks shapes cross-strait supply chain configurations.
China
Hyperscale data center operators in Guangdong province are consolidating server procurement around domestic vendors capable of GB 4943.1-2022 safety compliance. MIIT electromagnetic compatibility mandates are forcing additional prepreg layers in PCB stack-ups for boards destined for domestic deployment. Shenzhen's assembly ecosystem achieves lowest unit costs through shared tooling across brands, though dual carbon goals are pulling demand toward low-power chipset architectures.
Taiwan
Hsinchu Science Park corridor datacenter operators specify 24-phase voltage regulator modules for AI training workloads on multi-socket server configurations. The Bureau of Standards, Metrology and Inspection maintains IEC framework alignment for IT equipment safety, creating compliance overlap with cross-strait shipments. Taichung's manufacturing corridor favors Micro ATX corporate desktop refresh cycles that balance cost against upgrade headroom.
South Korea
5G base station and smart factory installations across manufacturing belts are driving Mini ITX form factor traction in thermal-constrained edge deployments. PC bang operators and streaming content creators generate refresh velocity through aesthetic differentiation in gaming-oriented SKUs. Seoul financial district enterprise fleet managers specify USB-C with Alternate Mode DisplayPort for hot-desking flexibility.
India
New Delhi's production-linked incentive framework for IT hardware is creating greenfield motherboard assembly capacity outside established China-Taiwan corridors. BIS mandatory registration schemes are extending market entry cycles by 4-6 months for imported boards, compressing product refresh windows for international suppliers. Domestic electronics manufacturing clusters in Karnataka and Tamil Nadu are absorbing transferred assembly operations.
Japan
METI industrial policy supports advanced substrate material development from domestic chemical suppliers including Ajinomoto Build-up Film producers. Signal integrity engineering talent pools in Tokyo and Osaka metropolitan areas service high-frequency routing requirements above 8 GHz for regional hyperscale projects. Yokohama-based industrial automation OEMs commission custom form factors for compact controller enclosures.
Asia Pacific Motherboard Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized server and edge computing configurations. The vendor base clusters around three distinct maturity tiers: vertically integrated contract manufacturers with captive design capabilities, R&D-intensive gaming and workstation specialists, and scale-driven server platform suppliers. Market structure reflects consolidation pressure from hyperscale direct procurement models that bypass traditional distribution tiers. Dominant competitive moves include frame agreement negotiations with datacenter operators and qualification of high-density interconnect substrates for 2025 platform refreshes.
Within the R&D-intensive tier, ASUSTeK Computer Inc. and Gigabyte Technology Co., Ltd. exemplify design leadership across gaming and cloud infrastructure segments. Super Micro Computer Inc. anchors the server segment through manufacturing scale and direct-to-datacenter channel control. These three companies represent divergent strategic archetypes: consumer-facing brand differentiation, hyperscale partnership execution, and vertical integration into enterprise platforms.
| Leading Market Players |
|---|
| ASUSTeK Computer Inc. |
| Gigabyte Technology Co., Ltd. |
| Micro-Star International Co., Ltd. (MSI) |
| ASRock Inc. |
| Super Micro Computer Inc. |
| Advantech Co., Ltd. |
| Biostar Microtech International Corp. |
| Intel Corporation |
| AMD (Advanced Micro Devices, Inc.) |
| Others |
Value Chain & Pricing Dynamics
Hyperscale data center operators in Taiwan's Hsinchu Science Park corridor and Guangdong province anchor procurement volume, compressing margins through frame agreements that bypass traditional distribution tiers and force suppliers into cost-absorption for validation cycles.
Pricing Analysis
Volume concentrates in standard ATX and Micro ATX tiers where Shenzhen assembly ecosystems achieve lowest unit costs through shared tooling, while premium positioning commands Mini ITX and E-ATX server configurations with 24-phase voltage regulator modules. Price differentiation hinges on certification grade for GB 4943.1-2022 safety compliance and volume scale in direct-to-datacenter contracts. Cost compression in standard tiers is intensifying because hyperscale buyers consolidate procurement among fewer vendors. Gaming-oriented buyers show least price sensitivity through aesthetic customization bundles, while corporate desktop refresh cycles in Taichung demonstrate highest sensitivity to per-unit economics.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Taipei operate hub-and-spoke patterns feeding Guangdong assembly plants and Hsinchu Science Park server farms. Manufacturing gravity centers on China, Taiwan, and South Korea, with substrate material supply drawing from Japanese and Korean chemical producers of Ajinomoto Build-up Film and high-grade FR-4 resin. Raw material dependencies include copper-clad laminates, microvia drilling equipment, and impedance-controlled prepreg layers. Single-source vulnerability concentrates in Taiwan Strait shipping lanes carrying motherboard volume. Distribution runs through vertically integrated contract manufacturers with captive design capabilities serving hyperscale direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific motherboard market sits in a technology-transition phase as PCIe 6.0 convergence with CXL memory pooling architectures displaces legacy socket designs and opens new platform refresh cycles.
For Market Incumbents: Extend qualification timelines for high-density interconnect substrates to anchor 2025 platform refresh contracts with Hsinchu hyperscale operators. Deepen backward integration into substrate material supply to offset Ajinomoto Build-up Film cost volatility from Japanese chemical suppliers. Consolidate frame agreement negotiations with Guangdong datacenter operators before India's PLI scheme matures competing assembly capacity.
For New Entrants and Emerging Players: Capture edge server deployments in South Korea's manufacturing belts where Mini ITX form factors penetrate 5G base station and smart factory installations with lower incumbent saturation. Target India's Karnataka and Tamil Nadu electronics clusters as greenfield assembly locations outside established China-Taiwan corridors. Pursue USB-C with Alternate Mode DisplayPort integration as the go-to-market angle for Seoul financial district hot-desking specifications.
For Investors and Strategic Acquirers: Distressed-cycle entries favor signal integrity engineering specialists in Taiwan and Japan where talent pools for impedance-controlled routing above 8 GHz remain thin relative to project pipelines. Long-term viability over the next decade hinges on qualification for next-generation datacenter socket designs rather than consumer gaming margin capture. Watch PCIe 6.0 adoption velocity among Hsinchu hyperscale operators as the inflection indicator for substrate technology upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Density Interconnect Substrate Qualification | Enables finer pitch BGA footprints essential for next-generation CPU packages in Hsinchu server farms. |
| GB 4943.1-2022 Safety Compliance Investment | Secures domestic Chinese deployment contracts requiring reinforced insulation barriers and fire enclosure ratings. |
| Direct-to-Datacenter Channel Bypass | Concentrates volume among vertically integrated manufacturers serving Guangdong hyperscale frame agreements. |
| India PLI Assembly Capacity Buildout | Creates greenfield motherboard production outside China-Taiwan corridors in Karnataka electronics clusters. |
| PCIe 6.0 with CXL Memory Pooling Integration | Opens socket design contracts for next-generation datacenter builds across Taiwan and South Korea. |
Study Parameters
Trade databases, customs filings, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with motherboard design engineers, datacenter procurement officers, substrate material suppliers, and Taiwan Bureau of Standards compliance specialists. Bottom-up assembly volume estimates from Shenzhen and Hsinchu manufacturing corridors were triangulated against top-down spending patterns from enterprise server refresh cycles.
Historical trendline analysis across shipment volumes and average selling prices established baseline growth trajectories, with analytical frameworks modeling form factor segmentation, end-use tier differentiation, and connectivity specification adoption across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating AI workload penetration and dual carbon goal compliance requirements. Forecast inputs included MIIT regulatory timeline assumptions and India BIS certification cycle extensions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-strait logistics friction, substrate material supply concentration, and signal integrity engineering talent scarcity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Europe Microcontroller (MCU) Market