
 Gallium Nitride (Gan) Semiconductor Devices Market | 2026-2036
Gallium Nitride (Gan) Semiconductor Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Nitride (Gan) Semiconductor Devices Market Foresight
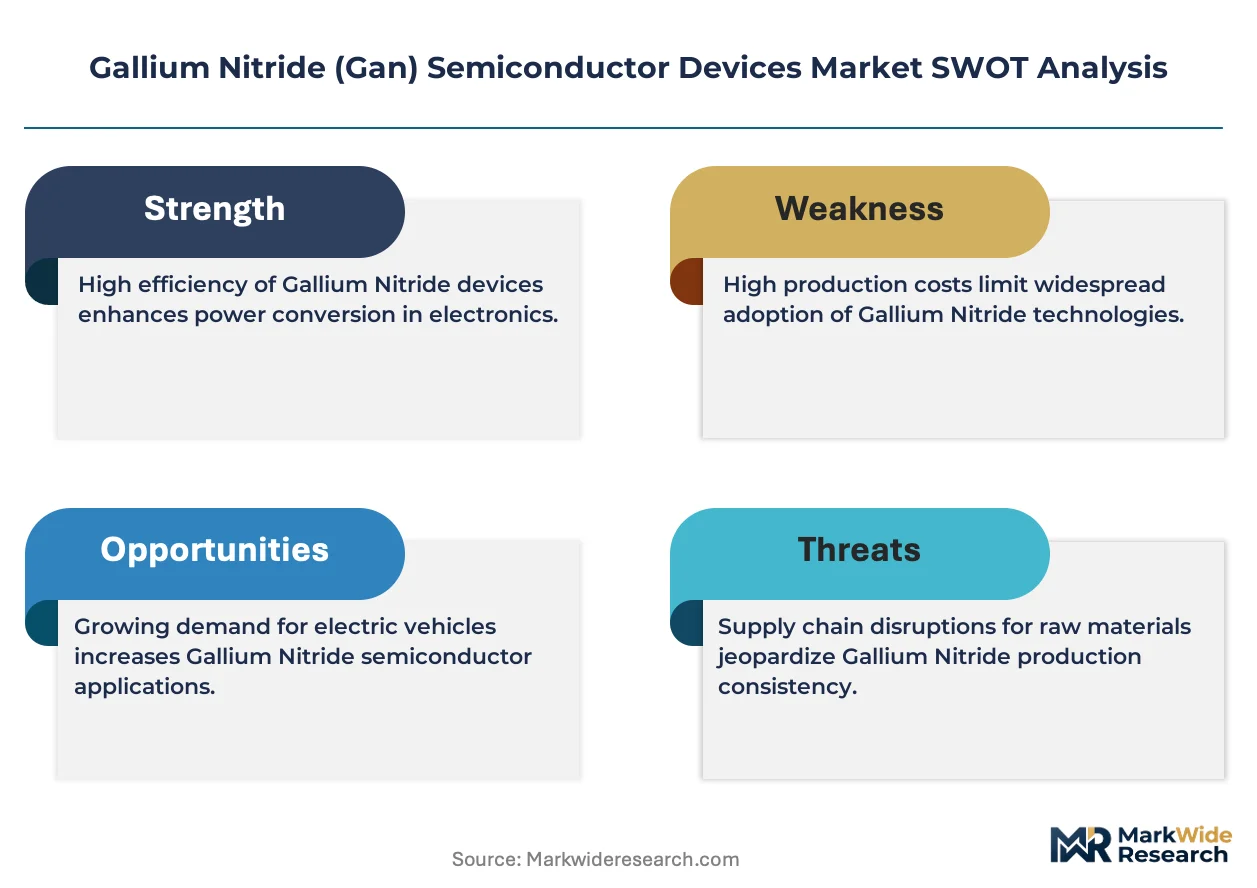
JEDEC qualification for wide-bandgap semiconductors is redrawing competitive entry barriers. Wolfspeed, Inc. leverages captive silicon carbide substrate expertise to anchor GaN-on-SiC supply chains. Infineon Technologies AG sustains European manufacturing scale through its Dresden and Villach fabs. Qorvo, Inc. specializes in defense-grade RF GaN for radar and electronic warfare applications.
Gallium Nitride semiconductor devices are wide-bandgap compound semiconductors fabricated on silicon, silicon carbide, or sapphire substrates via metal organic chemical vapor deposition, operating at switching frequencies above 1 MHz with breakdown voltages exceeding 600V for power conversion and RF amplification. High Electron Mobility Transistors dominate military and telecom applications where thermal performance justifies substrate cost. Power Amplifiers in wireless communication infrastructure represent the fastest-growing application segment as macro base stations transition to massive MIMO architectures. Data Centers are emerging as a concentrated margin pool where GaN power supplies reduce cooling loads and rack space requirements.
The U.S. CHIPS Act directs Department of Commerce funding toward domestic GaN fabrication, while the EU Chips Act coordinates member-state subsidies for wide-bandgap semiconductor capacity under the European Commission's industrial strategy. China's MIIT sets domestic content targets for base station power amplifiers through national 5G deployment mandates. Stakeholders must monitor how export control classifications for epitaxial growth equipment reshape substrate sourcing strategies and foundry partnerships.
Market Dynamics
The transition from silicon to wide-bandgap semiconductors is compressing power conversion efficiency thresholds across telecom infrastructure, defense systems, and data center operations, forcing foundries to recalibrate epitaxial growth capacity and substrate sourcing strategies.
Growth Catalysts
- 5G Massive MIMO Deployment:Telecom operators in China, Japan, and South Korea are replacing legacy LDMOS power amplifiers with GaN-on-SiC devices to achieve higher linearity and thermal efficiency in macro base stations.
- EU Chips Act Subsidies:Coordinated member-state funding under the European Commission's industrial strategy is expanding wide-bandgap semiconductor fabrication capacity at Dresden and Villach clusters.
- Defense Electronic Warfare Modernization:Pentagon procurement programs for phased-array radar systems are mandating GaN RF components for superior power density and frequency agility.
Market Restraints
- Silicon Carbide Substrate Scarcity:Six-inch SiC wafer supply concentrates among Japanese and US producers, creating input cost volatility for GaN-on-SiC device manufacturers.
- JEDEC Qualification Barriers:Extended reliability testing protocols for wide-bandgap semiconductors delay product commercialization timelines by 18-24 months versus silicon equivalents.
- Silicon Superjunction MOSFET Competition:Mature 600V-900V silicon power devices from established foundries retain cost advantages in consumer appliance and automotive auxiliary systems.
Strategic Opportunities
- Data Center Power Supply Retrofit:Hyperscale operators in Virginia, Frankfurt, and Singapore are replacing silicon-based server power supplies with GaN solutions to reduce cooling loads and rack density.
- Automotive On-Board Charging:Electric vehicle platforms above 400V architecture present unaddressed demand for GaN power devices in onboard chargers and DC-DC converters.
- US CHIPS Act Domestic Fab Incentives:Department of Commerce funding allocations for compound semiconductor manufacturing are attracting greenfield GaN epitaxy investments in Texas and Arizona.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Metal organic chemical vapor deposition expertise and device physics specialization remain concentrated among a limited pool of experienced engineers.
- Multi-Substrate Qualification Burden:Foundries must simultaneously validate GaN-on-Si, GaN-on-SiC, and GaN-on-sapphire process flows to serve divergent cost-performance requirements across end-use segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Nitride (Gan) Semiconductor Devices Market |
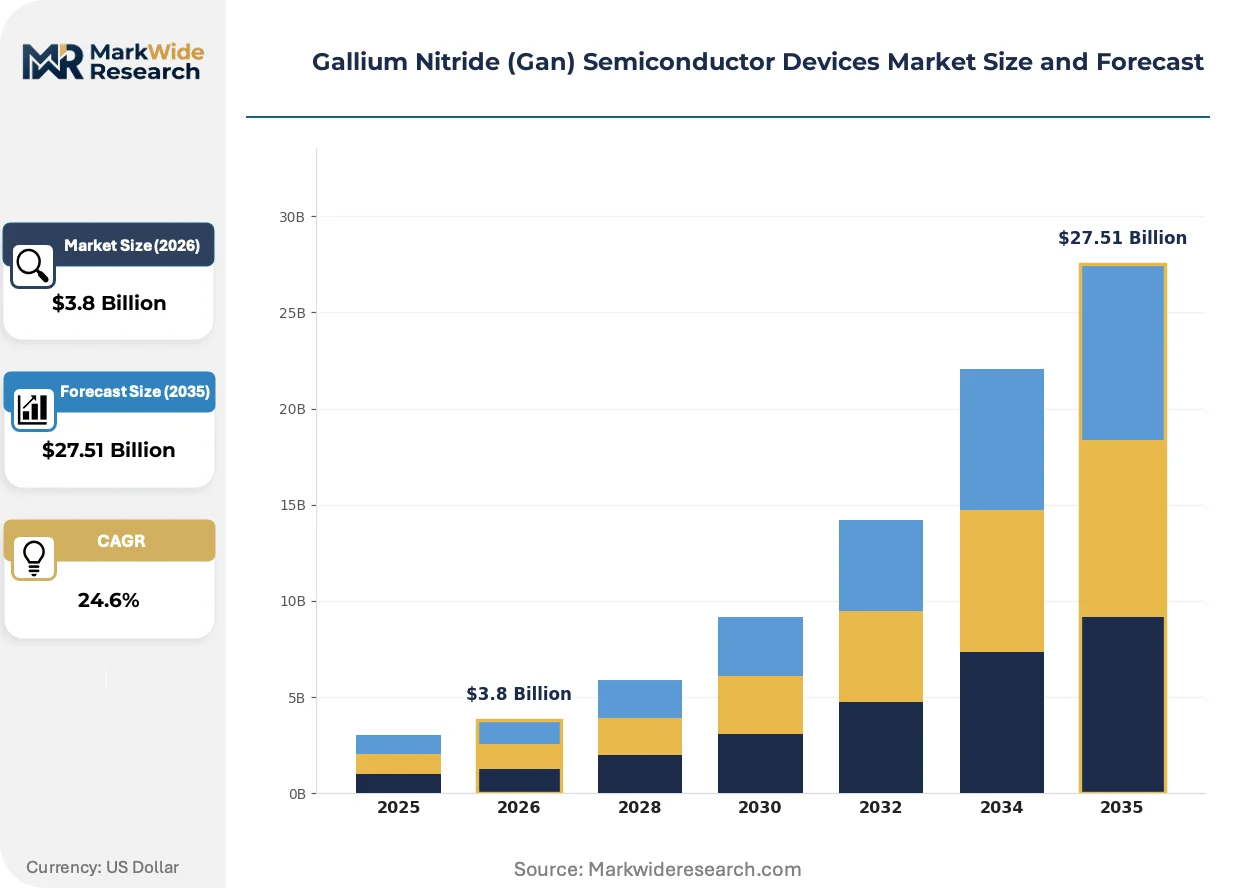
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: High Electron Mobility Transistor, Power Amplifier, Light Emitting Diode, Schottky Diode, Laser Diode Technology: Metal Organic Chemical Vapor Deposition, Molecular Beam Epitaxy, Hydride Vapor Phase Epitaxy, Sputter Deposition, Atomic Layer Deposition Application: Wireless Communication, Power Conversion, Radar Systems, Consumer Electronics, Data Centers End User Industry: Telecommunications Providers, Defense Contractors, Consumer Electronics Manufacturers, Renewable Energy Firms, Data Processing Companies |
| Companies Covered | Infineon Technologies AG, Qorvo, Inc., Texas Instruments Incorporated, Wolfspeed, Inc., NXP Semiconductors N.V., ROHM Co., Ltd., Navitas Semiconductor, GaN Systems, Transphorm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Nitride (Gan) Semiconductor Devices Market Shifts & Advancements
GaN device architectures are fragmenting across substrate platforms and voltage classes as end-use requirements diverge, while regulatory pressure on energy efficiency accelerates displacement timelines for legacy silicon power electronics.
GaN-on-silicon technology is bifurcating the power device landscape. This platform targets sub-650V applications in consumer chargers and industrial motor drives where cost sensitivity dominates. Consumer electronics OEMs in Shenzhen and Taipei are adopting 150W-300W GaN fast chargers at scale. The structural consequence is compressing margins for silicon superjunction MOSFET suppliers below 600V.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are tightening thermal management material specifications for power electronics. Manufacturers must reformulate packaging compounds and die-attach materials to maintain compliance. European industrial drive and renewable energy inverter producers are accelerating qualification of GaN modules to exploit higher efficiency and reduced cooling system requirements.
Hyperscale data center operators are unbundling power supply procurement from server OEM bundled contracts. Direct sourcing teams at Amazon Web Services, Microsoft Azure, and Google Cloud are establishing technical qualification programs for GaN-based 48V-to-12V intermediate bus converters. This pattern is most visible in Northern Virginia and Frankfurt hyperscale clusters where rack power densities exceed 30kW.
Gallium Nitride (Gan) Semiconductor Devices Market Segmentation
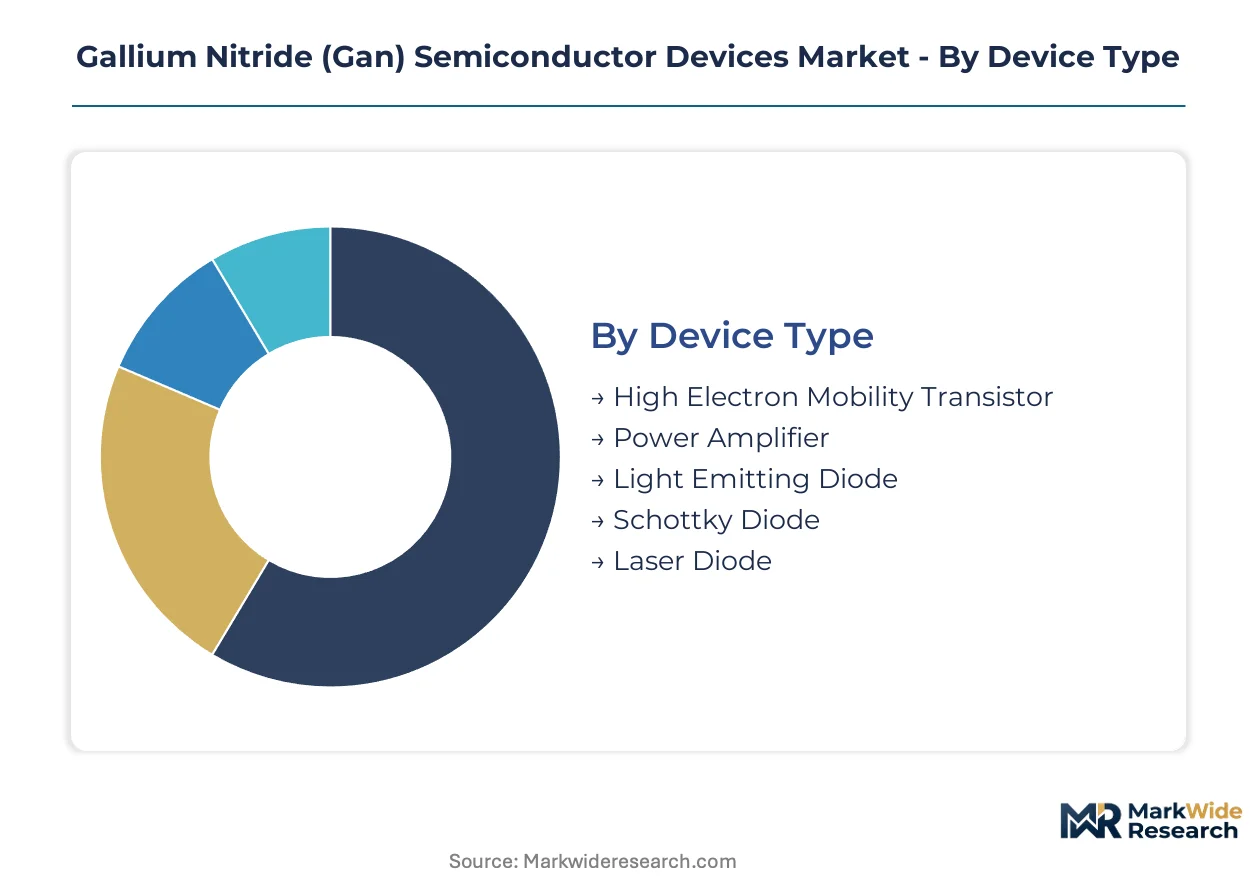
GaN device architectures fragment across substrate platforms, voltage classes, and fabrication methods as end-use requirements diverge sharply between cost-sensitive consumer electronics and performance-critical defense systems. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions will reshape competitive positioning.
Device Type:
Margin pools concentrate in RF power devices where thermal performance justifies premium substrate costs, while discrete power transistors compete on cost efficiency in high-volume consumer applications.
- High Electron Mobility Transistor:These devices exploit the two-dimensional electron gas at AlGaN/GaN heterojunctions to achieve electron mobility exceeding 2000 cm²/V·s. Defense procurement programs in the US and phased-array radar deployments in Japan anchor demand, with breakdown voltages above 600V enabling compact transmit-receive modules. Thermal management requirements favor GaN-on-SiC substrates despite cost premiums.
- Power Amplifier:Operating at frequencies from sub-6 GHz to mmWave bands, these devices deliver linear output power with efficiency above 60% in Class AB operation. China's MIIT-mandated 5G base station buildouts in Guangdong and Jiangsu provinces are absorbing massive volumes of macro cell amplifiers, displacing legacy LDMOS technology in massive MIMO architectures.
- Light Emitting Diode:Blue and UV emitters fabricated on sapphire substrates serve display backlighting and sterilization applications.
- Schottky Diode:Unipolar rectifiers with zero reverse recovery charge target high-frequency power conversion in telecom rectifiers.
- Laser Diode:Edge-emitting and VCSEL structures enable lidar systems and optical data transmission in automotive and communications equipment.
The dominant share belongs to High Electron Mobility Transistor, while Power Amplifier is closing the gap fastest.
Technology:
Epitaxial growth method selection determines defect density, throughput economics, and which substrate materials can be employed.
- Metal Organic Chemical Vapor Deposition:The industry-standard technique deposits AlGaN and GaN layers using trimethylgallium and ammonia precursors in horizontal or vertical reactor configurations. Dresden and Villach fabrication clusters in Europe sustain MOCVD capacity for automotive and industrial power devices, with reactor throughput exceeding 50 wafers per hour on 150mm silicon substrates.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition enables atomic-layer precision for defense-grade RF devices requiring minimal buffer trap densities. US Department of Defense trusted foundry programs specify MBE-grown material for satellite communications and electronic warfare systems where reliability margins override cost considerations.
- Hydride Vapor Phase Epitaxy:Chloride transport achieves growth rates tenfold faster than MOCVD for thick GaN templates.
- Sputter Deposition:Physical vapor deposition creates nucleation layers for GaN-on-silicon heteroepitaxy.
- Atomic Layer Deposition:Self-limiting surface reactions deposit gate dielectrics and passivation films with sub-nanometer uniformity.
MOCVD retains volume leadership, though MBE commands the steepest expansion trajectory in defense-qualified material.
Application:
Application segmentation tracks how voltage and frequency requirements map to substrate choices and packaging investments.
- Wireless Communication:Macro base stations and small cells consume GaN devices for final-stage amplification, with massive MIMO configurations requiring 64 or more transmit chains per antenna array. South Korean operators SK Telecom and KT Corporation have specified GaN-on-SiC for 28 GHz mmWave deployments in Seoul metropolitan infrastructure.
- Power Conversion:Totem-pole PFC and LLC resonant converters in server power supplies exploit GaN's figure-of-merit advantages. Northern Virginia hyperscale clusters are retrofitting 48V-to-12V intermediate bus architectures to reduce switching losses and magnetic component volume.
- Radar Systems:Active electronically scanned arrays for fighter aircraft and naval vessels mandate GaN transmit-receive modules.
- Consumer Electronics:65W-300W USB-C fast chargers from Shenzhen and Taipei OEMs adopt GaN-on-silicon for cost-sensitive portable power.
- Data Centers:Rack power densities above 30kW drive direct procurement of GaN-based server power supplies separate from server OEM bundles.
Wireless Communication holds the largest installed base, yet Data Centers are expanding most quickly as direct hyperscale procurement accelerates.
End User Industry:
Customer concentration and procurement sophistication vary dramatically across verticals, from defense program offices with multi-year qualification cycles to consumer electronics OEMs with six-month product lifecycles.
- Telecommunications Providers:China Mobile, China Telecom, and China Unicom collectively specify GaN power amplifiers through centralized procurement frameworks tied to MIIT 5G deployment mandates. Japanese operators NTT Docomo and KDDI specify GaN-on-SiC for sub-6 GHz macro coverage in Tokyo and Osaka metropolitan areas.
- Defense Contractors:Northrop Grumman, Raytheon, and Lockheed Martin integrate GaN RF components into phased-array radar and electronic warfare systems. Pentagon procurement programs mandate domestic sourcing through the Defense Production Act, channeling CHIPS Act funding toward trusted GaN foundry capacity.
- Consumer Electronics Manufacturers:Anker, Belkin, and Baseus volume-produce GaN fast chargers for retail distribution.
- Renewable Energy Firms:Solar inverter and wind turbine producers qualify GaN modules for DC-AC conversion efficiency gains.
- Data Processing Companies:Amazon Web Services, Microsoft Azure, and Google Cloud establish technical qualification programs for GaN power supplies through direct sourcing teams.
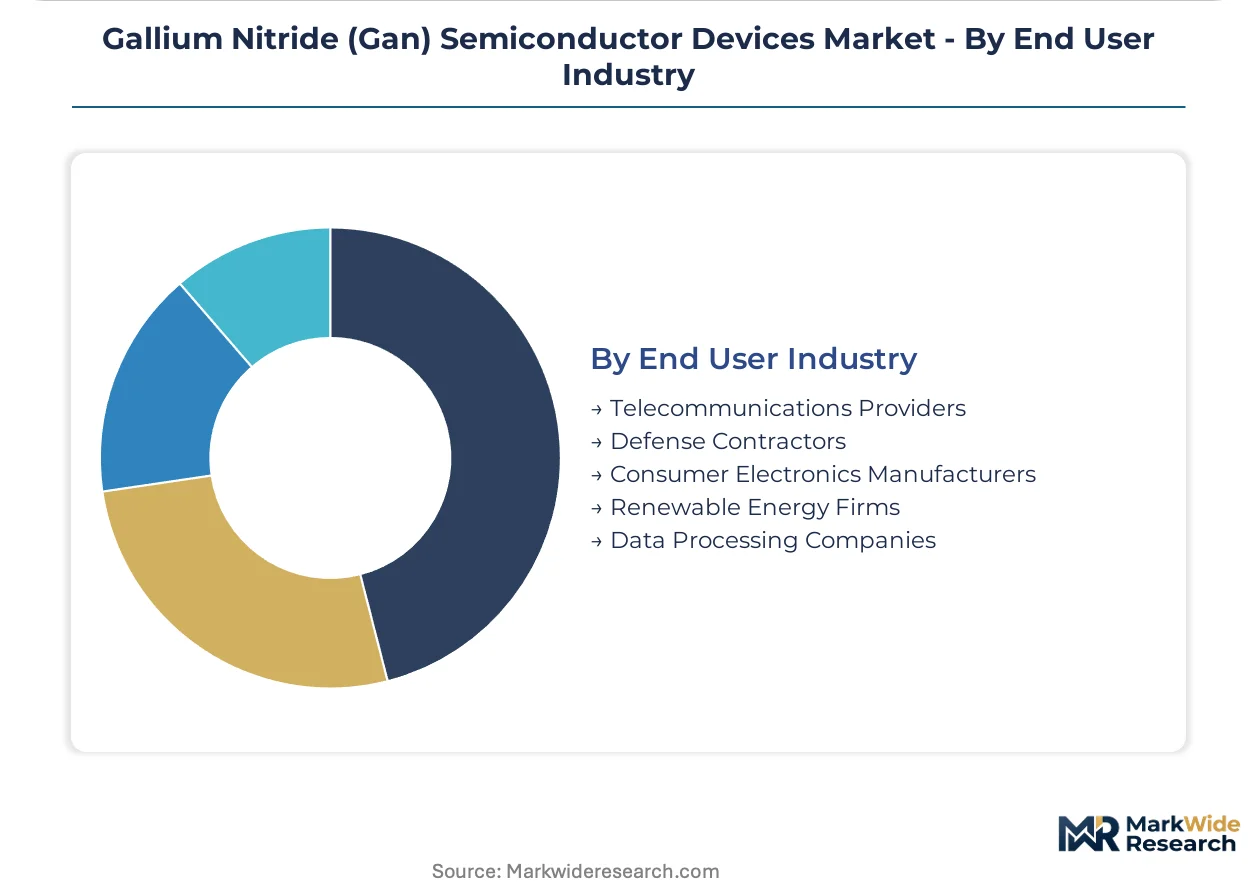
Telecommunications Providers command the dominant procurement volume, while Data Processing Companies are gaining share fastest through unbundled power supply sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and hyperscale data center operators concentrate purchasing power across three continents. Telecom infrastructure buildouts in East Asia and federal semiconductor subsidies in North America and Europe are redrawing regional supply chain maps.
United States
Pentagon electronic warfare programs and CHIPS Act funding are accelerating domestic GaN fabrication investments. The Department of Commerce directs subsidies toward compound semiconductor foundries in Texas and Arizona. Northern Virginia hyperscale clusters exceed 30kW rack densities, driving direct procurement of GaN server power supplies separate from OEM bundles.
China
MIIT-mandated 5G deployment timelines concentrate demand for base station power amplifiers in Guangdong and Jiangsu provinces. National content targets for domestic semiconductor procurement channel investment toward local GaN epitaxy capacity. Shenzhen consumer electronics OEMs volume-produce 150W-300W GaN fast chargers for retail distribution.
Germany
Industrial drive manufacturers and automotive suppliers qualify GaN modules for efficiency gains in motor control and onboard charging. EU Chips Act subsidies coordinate member-state funding for wide-bandgap capacity expansion. Dresden and Villach fabrication clusters sustain MOCVD throughput for automotive and industrial power devices.
Japan
NTT Docomo and KDDI specify GaN-on-SiC for sub-6 GHz macro coverage in Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic substrate and epitaxy equipment production. Phased-array radar deployments for maritime defense anchor demand for high-reliability RF components.
South Korea
SK Telecom and KT Corporation specify GaN-on-SiC for 28 GHz mmWave infrastructure in Seoul metropolitan networks. Government-backed semiconductor initiatives target compound semiconductor self-sufficiency. Samsung and LG electronics divisions integrate GaN power devices into consumer appliance and display product lines.
Gallium Nitride (Gan) Semiconductor Devices Market Competitive Landscape
Player mix skews toward integrated device manufacturers with captive substrate expertise and fabless specialists licensing process technology. Market structure concentrates around three tiers: diversified semiconductor conglomerates with compound semiconductor divisions, pure-play GaN device specialists, and RF-focused defense contractors. Consolidation pressures favor M&A between epitaxy equipment suppliers and device fabricators, while capacity expansion dominates capital allocation for qualifying new substrate formats.
Among European-integrated conglomerates, Infineon Technologies AG anchors industrial and automotive power device supply through its Dresden and Villach fabrication clusters. Wolfspeed, Inc. occupies a distinctive position through captive silicon carbide substrate production that secures GaN-on-SiC supply chain control. Qorvo, Inc. exemplifies the defense-specialist archetype, with its RF component focus aligning with Pentagon trusted foundry requirements and phased-array radar procurement programs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Qorvo, Inc. |
| Texas Instruments Incorporated |
| Wolfspeed, Inc. |
| NXP Semiconductors N.V. |
| ROHM Co., Ltd. |
| Navitas Semiconductor |
| GaN Systems |
| Transphorm Inc. |
| Others |
Supply & Pricing Matrix
Epitaxial reactor throughput exceeding 50 wafers per hour at Dresden and Villach fabrication clusters compresses unit economics for GaN-on-silicon power devices while sustaining price floors for GaN-on-SiC RF components where substrate scarcity limits scale. This capacity asymmetry concentrates margin capture among integrated device manufacturers with captive silicon carbide supply, forcing fabless competitors into cost-plus contract structures indexed to Japanese and US wafer pricing.
Pricing Analysis
Cost-plus contracts with silicon carbide wafer indexation dominate GaN-on-SiC procurement for defense and telecom applications, while spot-market spot pricing governs high-volume consumer charger segments. Price differentiation rests on JEDEC qualification tier and thermal performance grade, with defense-trusted foundry material commanding substantial premiums over commercial-grade equivalents. Pricing pressure stems from silicon superjunction MOSFET competition below 600V, compressing margins for GaN-on-silicon discrete transistors in appliance and automotive auxiliary markets. Consumer electronics OEMs exhibit highest price sensitivity, whereas Pentagon procurement offices prioritize reliability margins over unit cost.
Supply Chain Analysis
Inbound logistics costs through Yokohama and Busan port corridors fluctuate with container availability for epitaxial growth equipment and precursor chemical shipments from German chemical suppliers. Supply concentrates in Japan, the United States, and Germany for six-inch silicon carbide substrates, while China and Taiwan dominate sapphire and silicon wafer feedstocks. Raw material dependencies include trimethylgallium organometallic precursors, high-purity ammonia, and pyrolytic boron nitride crucibles. Single-source vulnerability characterizes advanced MOCVD reactor supply, with distribution running through authorized equipment distributors and direct foundry partnerships to defense contractors and telecom operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscale data center operators unbundling power supply procurement from server OEM contracts, fragmenting historical vendor relationships and forcing qualification transparency.
For Market Incumbents: Shield GaN-on-SiC margin pools through captive substrate supply and JEDEC qualification investment, as silicon superjunction MOSFET vendors encroach below 600V. Prioritize backward integration into silicon carbide crystal growth to secure input cost stability against Japanese wafer supply volatility. Defend defense-trusted foundry status through Pentagon procurement program alignment. For New Entrants and Emerging Players: Anchor in automotive onboard charging above 400V architecture, where incumbent qualification cycles have left demand unaddressed for GaN power devices in DC-DC converters. Target European industrial drive manufacturers accelerating GaN module adoption under EU F-Gas Regulation compliance pressure. Pursue direct technical qualification with hyperscale operators in Northern Virginia and Frankfurt bypassing server OEM bundled contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound semiconductor equipment suppliers with epitaxial growth reactor installed base and process IP licensing revenue. Long-term viability rests on substrate format transitions and defense procurement durability rather than consumer electronics volume exposure. Monitor CHIPS Act funding allocation velocity as inflection indicator for domestic fabrication capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Captive wafer supply secures GaN-on-SiC margin pools against Japanese producer concentration. |
| JEDEC Qualification Investment | Defense-trusted foundry status unlocks Pentagon phased-array radar procurement programs. |
| Hyperscale Direct Qualification Program | Amazon Web Services and Microsoft Azure unbundling creates bypass channel from server OEMs. |
| Automotive Platform Design Win | 400V+ electric vehicle architectures present unaddressed demand for onboard charging GaN devices. |
| EU Chips Act Funding Capture | Dresden and Villach cluster subsidies expand MOCVD throughput for industrial power device supply. |
Research Methodology
A standing panel of epitaxial growth process engineers, RF component procurement managers at defense contractors, telecom infrastructure planners, and hyperscale data center power architects provided ongoing calibration against secondary validation from SEC 10-K filings, Department of Commerce CHIPS Act disbursement records, MIIT 5G deployment mandates, and EU Chips Act member-state funding announcements. Bottom-up wafer throughput modeling and top-down end-use demand estimation were triangulated against trade data for organometallic precursor chemicals and silicon carbide substrate shipments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across device architecture, substrate platform, voltage class, and end-use vertical. CAGRs were derived from installed base replacement cycles and technology displacement curves, incorporating foundry capacity expansion timelines and defense procurement program visibility as industry-specific forecast inputs.
Material uncertainties — export control reclassification for epitaxial growth equipment, silicon carbide substrate supply disruptions, and hyperscale operator procurement centralization — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology transition velocity and regulatory subsidy durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Coated Silicon Wafer Market