
 Global ASIC Bitcoin Mining Hardware Market | 2026-2036
Global ASIC Bitcoin Mining Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global ASIC Bitcoin Mining Hardware Market Analysis
The transition from 7nm to 5nm and 3nm process nodes is unwinding older generation inventory and forcing fleet refresh cycles across the installed base. Bitmain leverages its foundry partnerships to secure priority wafer allocation at TSMC. MicroBT sustains engineering density in Shenzhen to compress design-to-tapeout timelines. Canaan anchors its position through captive ASIC design capabilities that reduce reliance on external semiconductor IP.
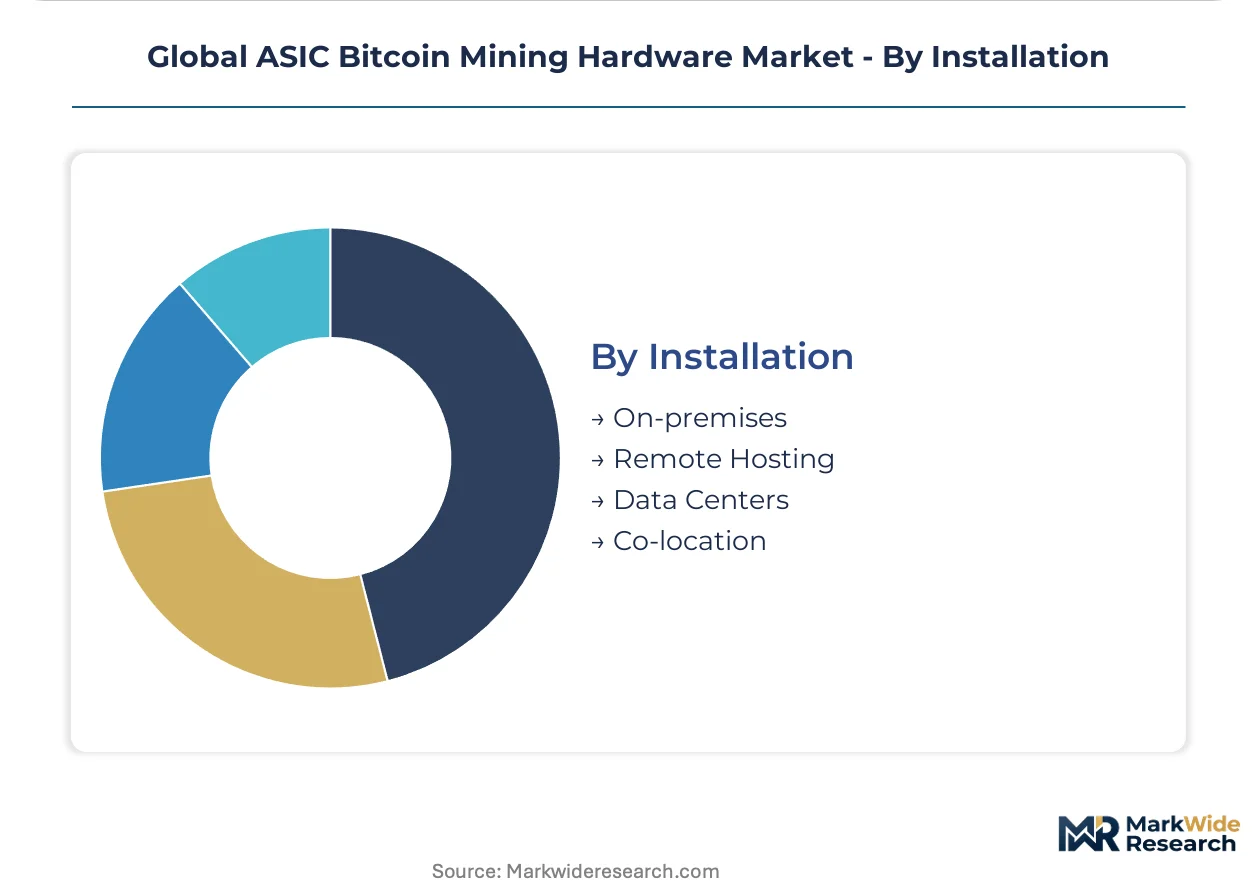
ASIC Bitcoin mining hardware comprises application-specific integrated circuits engineered exclusively to execute the SHA-256 hashing algorithm at maximum energy efficiency, measured in joules per terahash, with contemporary units fabricating on advanced FinFET processes to achieve hash rates exceeding 300 terahash per second. The product type dimension shows Antminer and Whatsminer lines commanding the bulk of deployed hash rate, while Avalon differentiates through integrated power supply designs that simplify farm construction. The end user segment reveals mining farms and enterprises capturing the fastest expansion as individual operators face capital barriers to acquiring latest-generation machines. Installation patterns favor co-location and remote hosting arrangements that pool electricity procurement and cooling infrastructure across multiple owners.
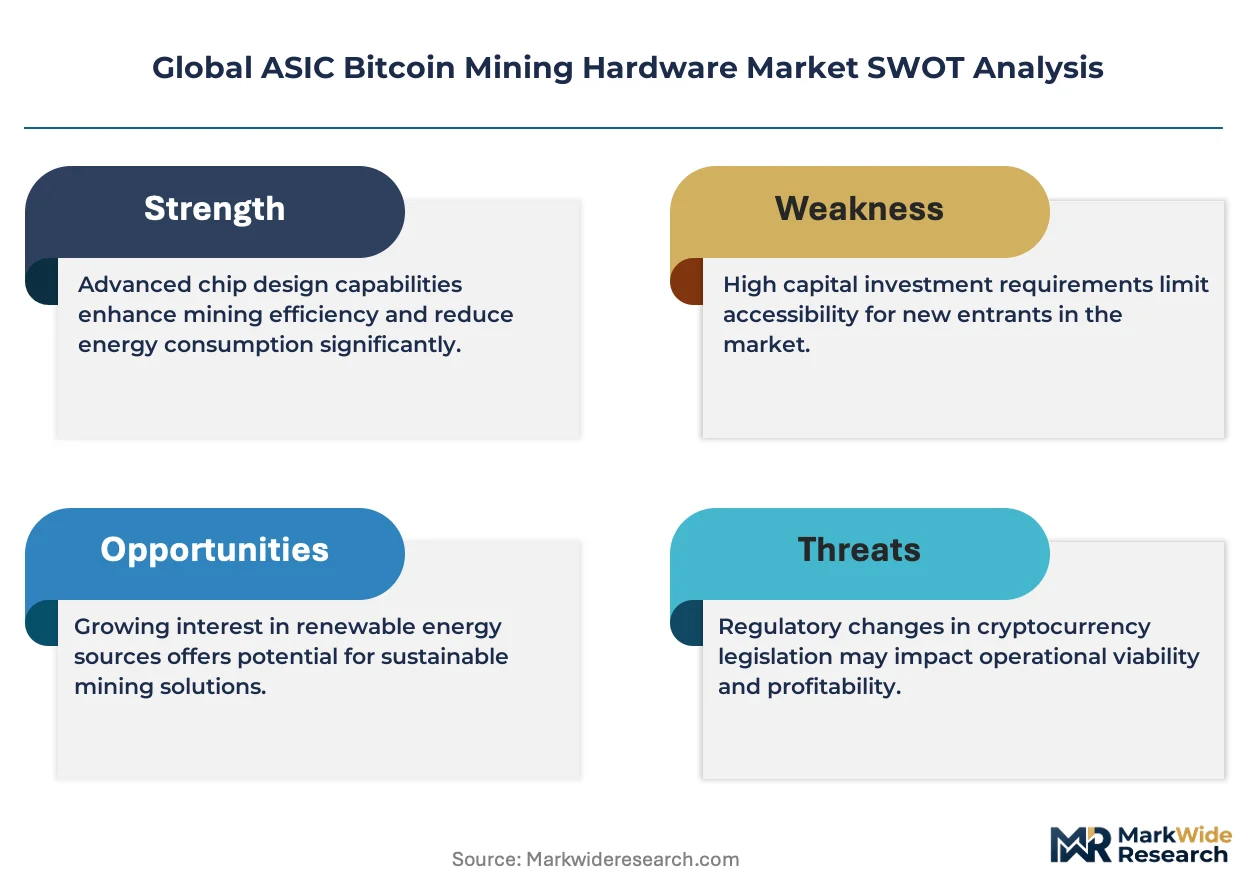
The United States EPA enforces stationary source emissions rules that constrain fossil-fuel-dependent mining operations in certain grid regions, while the EU Green Deal's corporate sustainability reporting requirements pressure European-located facilities to document carbon intensity per mined coin. China's SAMR and MEE maintain restrictive post-2021 postures on cryptocurrency mining that redirect supply chain flows and hash rate geography. Kazakhstan's central bank and energy ministry have implemented registration and power tariff regimes that filter operational entrants. Stakeholders must monitor regulatory arbitrage windows as jurisdictions recalibrate electricity pricing and environmental compliance burdens.
Market Dynamics
Process node transitions from 7nm to 5nm and 3nm are compressing equipment refresh cycles and stranding older generation inventory across the installed base. Foundry allocation constraints at TSMC and Samsung Foundry are concentrating supply-side leverage among vertically integrated hardware designers with multi-year wafer agreements.
Growth Catalysts
- EU Green Deal corporate sustainability reporting:European facilities must document carbon intensity per mined coin, creating certified low-carbon hardware demand that rewards efficiency-maximizing ASIC designs.
- Texas renewable portfolio standards:State-level mandates for clean electricity procurement are redirecting mining farm construction toward wind-rich West Texas grid zones with stranded renewable capacity.
- Stranded gas utilization:Flare gas capture projects in North Dakota and Alberta are pairing mobile mining containers with otherwise vented methane, creating off-grid demand for containerized ASIC deployments.
Market Restraints
- Wafer allocation concentration:TSMC advanced node capacity prioritizes smartphone and AI accelerator customers, constraining ASIC foundry access during supply crunches.
- China's SAMR and MEE restrictions:Post-2021 prohibitions on cryptocurrency mining redirect domestic manufacturing capacity toward export-only production, fragmenting supply chain visibility.
- Hash rate commoditization:Homogeneous SHA-256 performance eliminates product differentiation beyond joules per terahash, compressing margin structures across all tiers.
Strategic Opportunities
- Kazakhstan registration and tariff regimes:Central bank and energy ministry frameworks filter operational entrants, creating first-mover advantages for compliant facilities in Pavlodar and Ekibastuz.
- Liquid immersion cooling convergence:Integration of dielectric fluid systems with 3nm chip thermal profiles enables density multiples exceeding air-cooled designs in hyperscale deployments.
- Remote hosting channel expansion:Co-location arrangements pooling electricity procurement and cooling infrastructure are displacing self-operated facilities among capital-constrained individual operators.
Industry Challenges
- Semiconductor design talent scarcity:FinFET physical design expertise concentrates at TSMC partner firms and captive Silicon Valley teams, constraining new entrant engineering density.
- Capex intensity for fleet refresh:Full-generation upgrades require nine-figure capital deployments for industrial-scale farms, straining balance sheets during Bitcoin price drawdowns.
- Grid interconnection timelines:Utility-scale power delivery agreements in ERCOT and PJM regions face 18-36 month queue delays, mismatching equipment delivery with energization dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ASIC Bitcoin Mining Hardware Market |
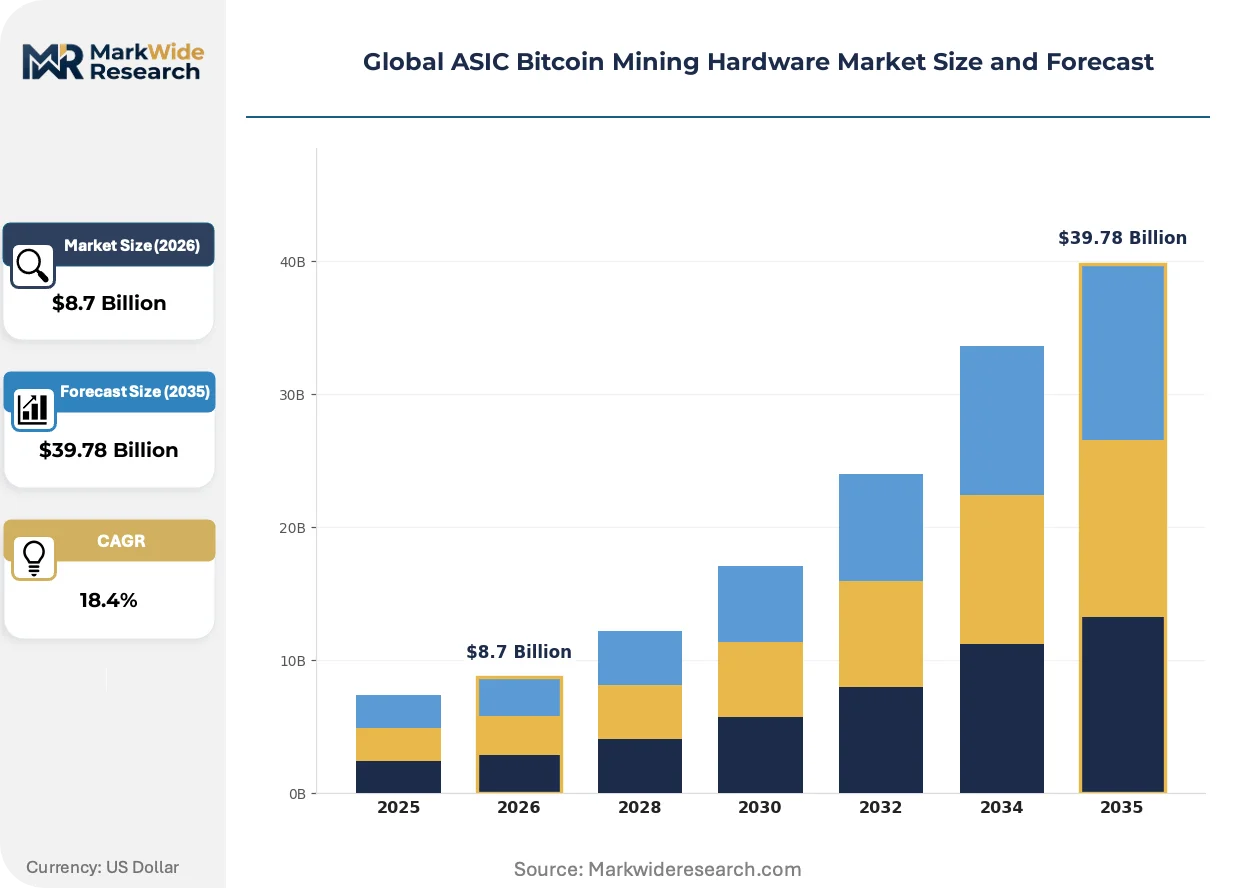
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antminer, Whatsminer, Avalon, Innosilicon Technology: SHA-256, Scrypt, X11, Ethash End User: Individual Miners, Mining Farms, Cloud Mining, Enterprises Installation: On-premises, Remote Hosting, Data Centers, Co-location |
| Companies Covered | Bitmain, MicroBT, Canaan, Bitdeer, Bitfury, D-Central Technologies, Fluminer, Bitaxe, Sazmining, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ASIC Bitcoin Mining Hardware Market Emerging Trajectories
Three forces are restructuring competitive positioning: semiconductor process leadership, environmental compliance integration, and procurement model consolidation. These shifts favor capital-heavy incumbents with foundry relationships and captive infrastructure.
Immersion cooling technology is fragmenting deployment architectures for high-density ASIC installations. Mining farms exceeding 100 megawatts are adopting single-phase dielectric fluid systems to manage 3nm chip thermal loads. This configuration compresses facility footprints by sixty percent versus air-cooled designs while enabling overclocking headroom that stranded air-cooled competitors cannot match.
The EPA's stationary source emissions rules under the Clean Air Act are constraining fossil-fuel-dependent operations in coal-heavy MISO grid regions. Facilities must document NOx and particulate thresholds or procure carbon offsets, increasing compliance overhead. Texas-based operators are responding by siting exclusively in wind-dominant zones with direct renewable energy credits.
Hash rate procurement is consolidating through vertically integrated hosting contracts that bundle machine supply, electricity, and maintenance under single-counterparty agreements. Individual operators and small funds are displacing self-managed fleets in favor of all-in rate-per-terahash structures. This behavior is most visible in Wyoming and Georgia, where tax-advantaged jurisdictions attract pooled capital vehicles seeking operational passivity.
Global ASIC Bitcoin Mining Hardware Market Segmentation
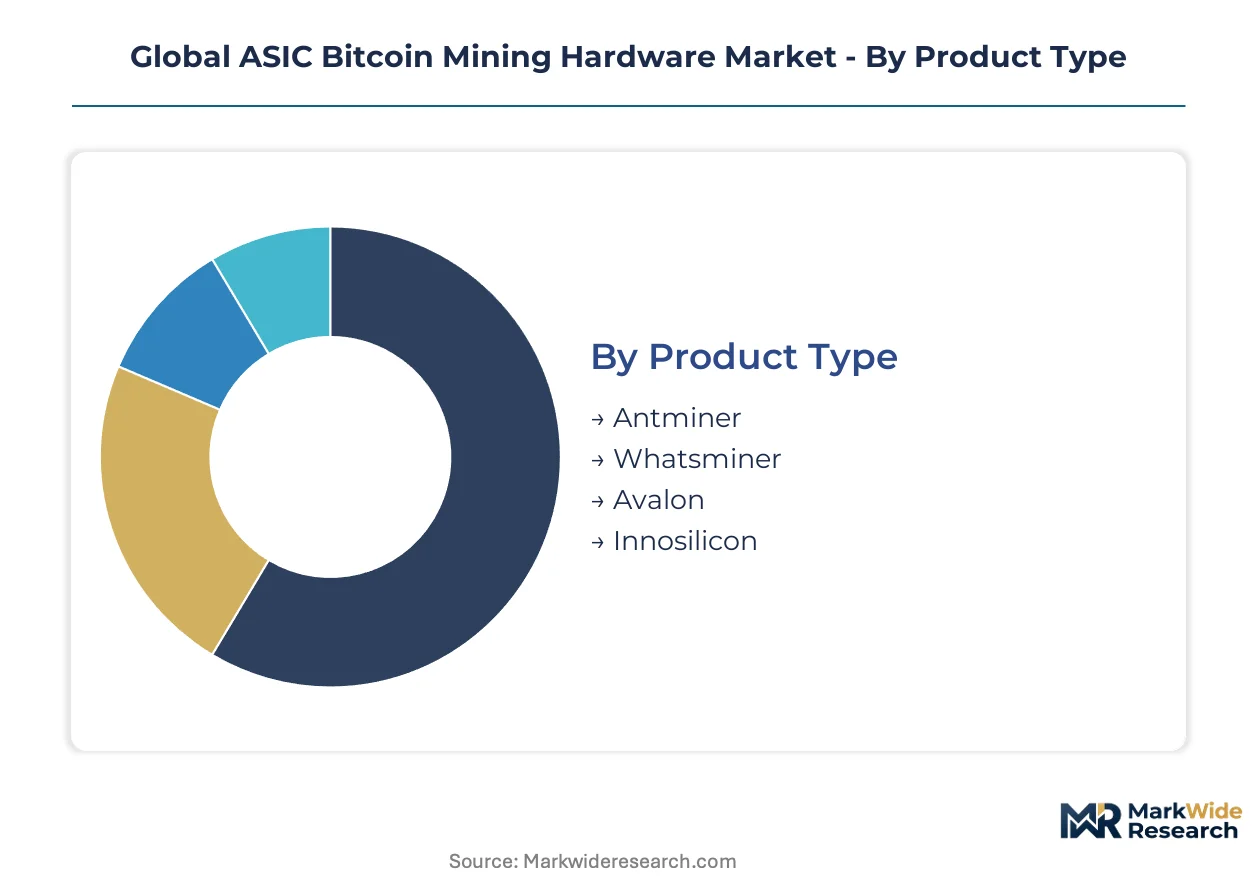
ASIC Bitcoin mining hardware segmentation reveals how capital intensity, regulatory compliance, and infrastructure access fragment purchasing behavior across operator types. Equipment procurement patterns diverge sharply between self-managed deployments and outsourced arrangements.
Product Type:
EU Green Deal carbon reporting requirements and Texas renewable portfolio standards are concentrating procurement toward machines with verified joules-per-terahash efficiency certifications.
- Antminer:Units leverage TSMC foundry partnerships to secure priority wafer allocation at advanced nodes. Demand concentrates in Wyoming and Georgia tax-advantaged jurisdictions where pooled capital vehicles seek operational passivity through bundled hosting contracts.
- Whatsminer:Engineering density in Shenzhen compresses design-to-tapeout timelines for rapid generational turnover. Kazakhstan's Pavlodar and Ekibastuz regions filter entrants through central bank registration frameworks, favoring compliant fleet operators with established logistics.
- Avalon:Integrated power supply designs simplify farm construction for capital-constrained entrants.
- Innosilicon:Niche positioning serves algorithm-diversified operators beyond pure SHA-256 deployments.
Established volume favors Antminer; emerging adoption favors Whatsminer.
Technology:
Process node transitions from 7nm to 5nm and 3nm are compressing equipment refresh cycles and stranding older generation inventory.
- SHA-256:Application-specific circuits execute Bitcoin's hashing algorithm at maximum energy efficiency, measured in joules per terahash. Mining farms exceeding 100 megawatts in West Texas wind-rich zones drive demand for 3nm FinFET implementations that satisfy EPA stationary source emissions constraints.
- Scrypt:Memory-hard algorithm designs require distinct memory controller architectures. North Dakota and Alberta flare gas capture projects create off-grid demand for containerized deployments utilizing this alternative hashing approach.
- X11:Chained hashing sequence serves privacy-focused blockchain networks with different consensus economics.
- Ethash:Memory-intensive proof-of-work design targets GPU-competitive mining segments.
Capital concentration favors SHA-256; algorithmic diversification favors Scrypt.
End User:
Balance sheet capacity determines whether operators self-manage fleets or outsource to pooled infrastructure arrangements.
- Individual Miners:Operators face capital barriers to acquiring latest-generation machines as full-generation upgrades require nine-figure deployments. Remote hosting channel expansion displaces self-operated facilities among this segment.
- Mining Farms:Enterprise-scale operations in the United States, Kazakhstan, and Russia are scaling capacity through co-location arrangements pooling electricity procurement. Grid interconnection timelines in ERCOT and PJM regions face 18-36 month queue delays.
- Cloud Mining:Hash rate procurement consolidates through vertically integrated contracts bundling machine supply, electricity, and maintenance.
- Enterprises:Corporate treasury strategies and vertically integrated energy producers are capturing fastest expansion as hash rate commoditization eliminates product differentiation beyond efficiency metrics.
Operational passivity favors Cloud Mining; infrastructure control favors Mining Farms.
Installation:
Thermal management requirements at 3nm process nodes are fragmenting deployment architectures toward liquid immersion systems.
- On-premises:Self-managed facilities retain direct control over electricity procurement and maintenance scheduling. Stranded gas utilization in North Dakota and Alberta pairs mobile containers with otherwise vented methane.
- Remote Hosting:Co-location arrangements pool cooling infrastructure across multiple owners. Wyoming and Georgia tax-advantaged jurisdictions attract pooled capital vehicles seeking all-in rate-per-terahash structures.
- Data Centers:Hyperscale designs integrate single-phase dielectric fluid systems compressing facility footprints by sixty percent versus air-cooled alternatives.
- Co-location:Shared facility arrangements displace self-operated deployments among capital-constrained individual operators.
Density optimization favors Data Centers; capital efficiency favors Co-location.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer allocation at TSMC and Samsung Foundry concentrates supply-side leverage among vertically integrated hardware designers with multi-year agreements, while jurisdictional arbitrage around electricity pricing and environmental compliance redistributes operational geography.
United States
Enterprise-scale mining farms are scaling capacity through co-location arrangements pooling electricity procurement. The EPA enforces stationary source emissions rules under the Clean Air Act that constrain fossil-fuel-dependent operations in coal-heavy MISO grid regions. West Texas wind-rich zones attract facility construction as operators site exclusively in areas with direct renewable energy credits.
Kazakhstan
Central bank registration frameworks and energy ministry power tariff regimes filter operational entrants, creating first-mover advantages for compliant facilities. Post-2021 prohibitions in neighboring China redirect supply chain flows and hash rate geography toward this jurisdiction. Pavlodar and Ekibastuz regions concentrate established logistics for fleet operators meeting compliance requirements.
Russia
Cold climate advantages reduce cooling infrastructure costs for large-scale deployments. The country's national energy regulator maintains frameworks for industrial electricity pricing that favor energy-intensive computing operations. Siberian regions with surplus hydroelectric capacity attract facility construction seeking low-cost, stable power supply.
Canada
Flare gas capture projects in Alberta pair mobile mining containers with otherwise vented methane, creating off-grid demand for containerized ASIC deployments. Provincial environmental regulations document carbon intensity thresholds for industrial operations. Northern Quebec and Manitoba hydroelectric zones attract hyperscale facility construction seeking renewable energy certification.
China
Post-2021 SAMR and MEE restrictions on cryptocurrency mining redirect domestic manufacturing capacity toward export-only production. Foundry partnerships with TSMC concentrate engineering density in Shenzhen for rapid design-to-tapeout timelines. Fragmented supply chain visibility results from prohibitions on domestic operational deployment.
Global ASIC Bitcoin Mining Hardware Market Vendor Landscape
Concentration sits with vertically integrated hardware designers possessing multi-year foundry agreements and captive ASIC design capabilities. The competitive structure tiers between capital-heavy incumbents with priority wafer allocation and emerging challengers competing on design-to-tapeout velocity. Dominant archetypes include foundry-partnered fabricators, engineering-density specialists, and integrated power-supply designers. Competitive moves center on securing advanced node capacity and compressing equipment refresh cycles through process node transitions.
Within the foundry-partnered tier, Bitmain and MicroBT exemplify archetypes securing priority wafer allocation through established semiconductor relationships. Canaan occupies a position representing captive design capabilities that reduce reliance on external IP. Among hosting-integrated operators, Bitdeer and Bitfury sit within the vertically integrated infrastructure tier bundling machine supply with electricity procurement. These five entities anchor the competitive landscape across hardware fabrication and operational deployment vectors.
| Leading Market Players |
|---|
| Bitmain |
| MicroBT |
| Canaan |
| Bitdeer |
| Bitfury |
| D-Central Technologies |
| Fluminer |
| Bitaxe |
| Sazmining |
| Others |
Supply Flow & Price Mechanics
Advanced node wafer allocation from smartphone and AI accelerator customers is displacing ASIC foundry access at TSMC, simultaneously compressing supply geography toward multi-year agreement holders and intensifying cost pass-through to mining farm operators without priority queue positions.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure through carbon intensity certification requirements that stratify hardware across premium efficiency-verified, standard compliance, and economy non-certified tiers. Price differentiation hinges on joules-per-terahash certification grade and bundled hosting service levels. Cost compression in economy tiers is intensifying because stranded inventory from 7nm process nodes floods secondary markets. Individual miners exhibit highest price sensitivity, while enterprise-scale mining farms prioritize efficiency metrics over unit acquisition cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced FinFET implementations, while China sustains backend assembly and testing capacity. Silicon wafer supply draws from Japanese and German chemical refinement operations, with rare earth element sourcing tethered to Chinese processing facilities. Single-source vulnerability concentrates at TSMC's leading-edge node allocation decisions. Distribution runs through vertically integrated hardware vendors with captive logistics networks serving Kazakhstan, Russia, and North American deployment zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proof-of-stake blockchain consensus mechanisms pose a substitution threat that ASIC hardware incumbents must navigate through efficiency-maximizing product roadmaps and carbon-neutral certification investments.
For Market Incumbents: Compound foundry relationship depth through multi-year wafer agreements that lock advanced node capacity before smartphone and AI accelerator customers absorb allocation. Secure captive immersion cooling IP to differentiate thermal management offerings as 3nm deployments density-multiply beyond air-cooled competitor capabilities. Hash rate commoditization demands backward integration into hosting infrastructure to capture margin pools beyond hardware fabrication. For New Entrants and Emerging Players: EU Green Deal carbon certification fast-tracks create white-space entry through efficiency-verified ASIC designs that command premium positioning in European-located facilities. Target Kazakhstan's Pavlodar and Ekibastuz regions where central bank registration frameworks filter established competitors and create compliance-barrier advantages for patient capital. Deploy containerized flare-gas capture solutions in North Dakota and Alberta as a go-to-market angle that bypasses grid interconnection queue delays constraining incumbent expansion. For Investors and Strategic Acquirers: The market sits at a process-node transition phase that favors vertically integrated infrastructure operators with captive electricity procurement and foundry-backed hardware supply. Long-term viability across a multi-decade horizon rests on exposure to jurisdictions with stable industrial electricity pricing and renewable energy certification pathways. Monitor TSMC advanced node allocation announcements as the critical signal for supply-side constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Multi-year wafer agreements at TSMC secure priority allocation ahead of AI accelerator demand surge. |
| Liquid Immersion Cooling Deployment | Single-phase dielectric systems enable 3nm chip density multiples exceeding air-cooled competitor footprints. |
| Carbon Certification Investment | EU Green Deal compliance documentation unlocks premium pricing from European-located mining facilities. |
| Flare Gas Capture Integration | Mobile container deployments in North Dakota and Alberta monetize otherwise vented methane emissions. |
| Vertically Integrated Hosting Buildout | Co-location arrangements in Wyoming and Georgia pool electricity procurement across capital-constrained operators. |
Methodological Framework
A standing panel of mining farm operations directors, semiconductor procurement leads, utility interconnection specialists, and immersion cooling system engineers provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from SEC hardware vendor filings, EIA electricity generation statistics, FERC interconnection queue databases, and customs import records. Bottom-up equipment deployment estimates triangulated against top-down hash rate geography models.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures and foundry capacity utilization reports across the projection horizon. Segmentation dimensions modeled include product type, process node technology, end user scale tier, and installation thermal architecture. CAGRs derived from equipment refresh cycle compression rates and jurisdictional hash rate migration patterns. Bitcoin network difficulty adjustments and regional electricity tariff regimes served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained proof-of-work consensus dominance and stable industrial electricity pricing in Kazakhstan, Russia, and Texas; material deviation toward proof-of-stake adoption or regulatory prohibition would warrant model refresh. Recalibration cycles align with material shifts in TSMC node allocation priorities and EPA stationary source emissions enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Global Zener Diode Market