
 Voltage Controlled Oscillators Market | 2026-2036
Voltage Controlled Oscillators Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Controlled Oscillators Market Analytics
Defense and satellite communications buyers are rotating toward radiation-hardened VCO suppliers as geopolitical tensions accelerate sovereign space programs. Analog Devices, Inc. leverages its portfolio of ultra-low-noise designs to anchor high-reliability contracts with aerospace prime contractors. SiTime Corporation competes through MEMS-based architectures that sustain frequency stability across temperature extremes. Qorvo, Inc. specializes in GaN-on-SiC VCO modules that dominate millimeter-wave radar and electronic warfare applications.
A voltage controlled oscillator generates an oscillating signal whose frequency shifts in proportion to an applied control voltage, typically achieving phase noise below minus 120 dBc per Hz at one megahertz offset in quartz-based designs. Engineers deploy these devices for frequency synthesis, clock recovery, and carrier modulation across RF communication chains. Quartz VCOs retain the largest installed base due to decades of manufacturing maturity and established supply chains, though MEMS variants are capturing share in portable and shock-prone environments where mechanical robustness outweighs absolute spectral purity. RF technology leads revenue contribution among technology segments because cellular base stations and radar systems require sub-microsecond frequency agility that analog-only architectures cannot deliver.
The FCC enforces stringent spurious emission limits under Title 47 that compel VCO makers to invest in electromagnetic interference shielding and harmonic suppression. ETSI harmonized standards across EU member states mandate coexistence testing that elevates barrier-to-entry for non-European suppliers seeking base-station qualification. China's MIIT issues type-approval certificates that restrict market access for timing components lacking domestic cybersecurity audit. Stakeholders must monitor how divergent national certification timelines reshape competitive positioning without assuming regulatory convergence.
Market Dynamics
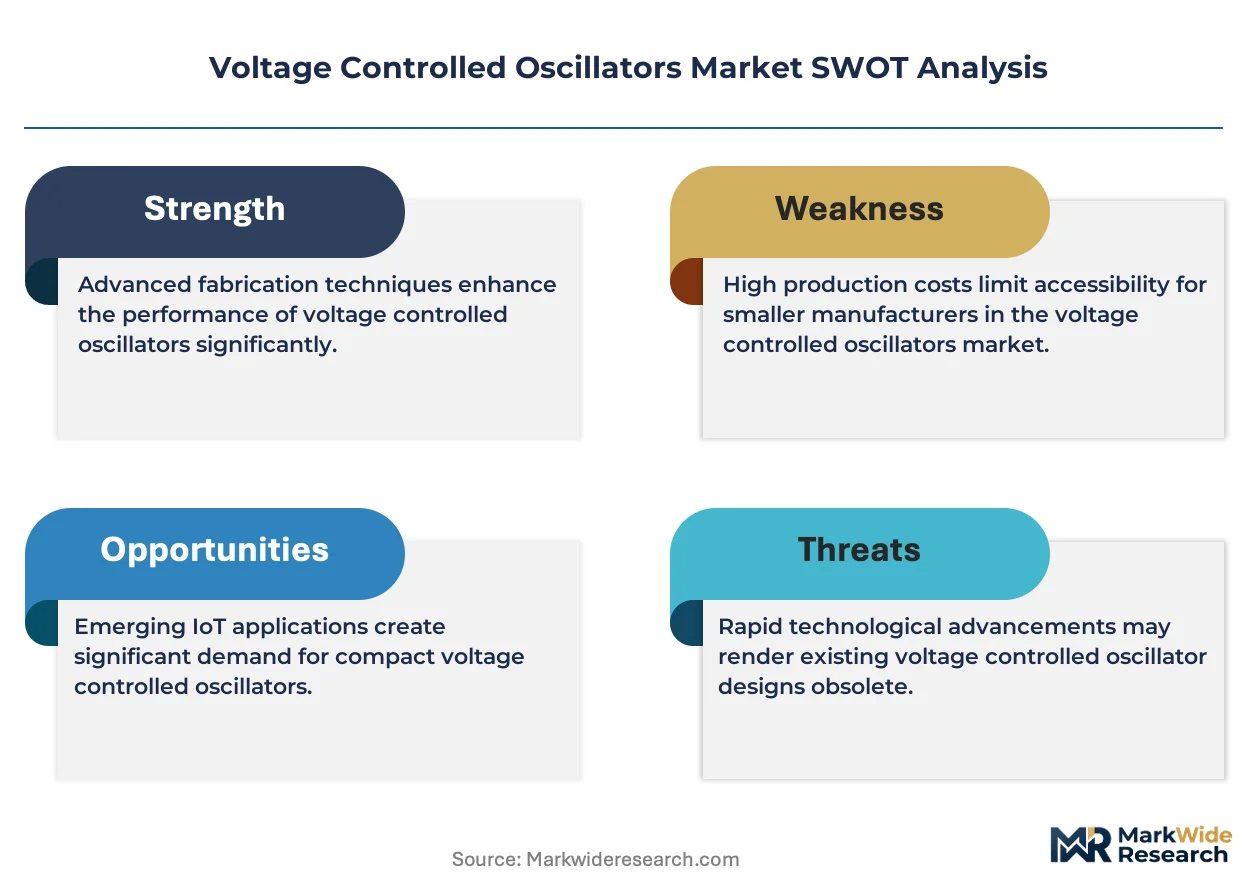
Phase-noise specifications from the FCC and ETSI are tightening simultaneously, forcing VCO manufacturers to redesign shielding architectures and harmonic suppression circuits across their entire product portfolios.
Growth Catalysts
- 5G infrastructure densification:South Korean base-station manufacturers are expanding procurement of precision timing devices as network rollouts deepen.
- ETSI harmonized standards:The EU's Radio Equipment Directive mandates coexistence testing that elevates qualification requirements for RF components.
- MEMS temperature resilience:Mechanical robustness across temperature extremes is displacing quartz in portable and shock-prone environments.
Market Restraints
- Quartz supply concentration:Decades of manufacturing maturity have locked supply chains into limited geographic clusters.
- MIIT type-approval barriers:China's cybersecurity audit requirements restrict market access for timing components lacking domestic certification.
- GaN-on-SiC input costs:Substrate scarcity and epitaxial processing complexity constrain millimeter-wave module scaling.
Strategic Opportunities
- Sovereign space programs:Geopolitical tensions are accelerating radiation-hardened VCO procurement for defense and satellite communications.
- Millimeter-wave radar convergence:Electronic warfare and automotive sensing applications are merging performance requirements.
- Modular frequency synthesis:Sub-microsecond agility demands are creating openings for digitally controlled analog architectures.
Industry Challenges
- Electromagnetic compatibility certification:Divergent national timelines for FCC Title 47, ETSI standards, and MIIT approvals fragment product development roadmaps.
- Legacy quartz integration:Decades of installed base inertia slows MEMS substitution despite mechanical advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Controlled Oscillators Market |
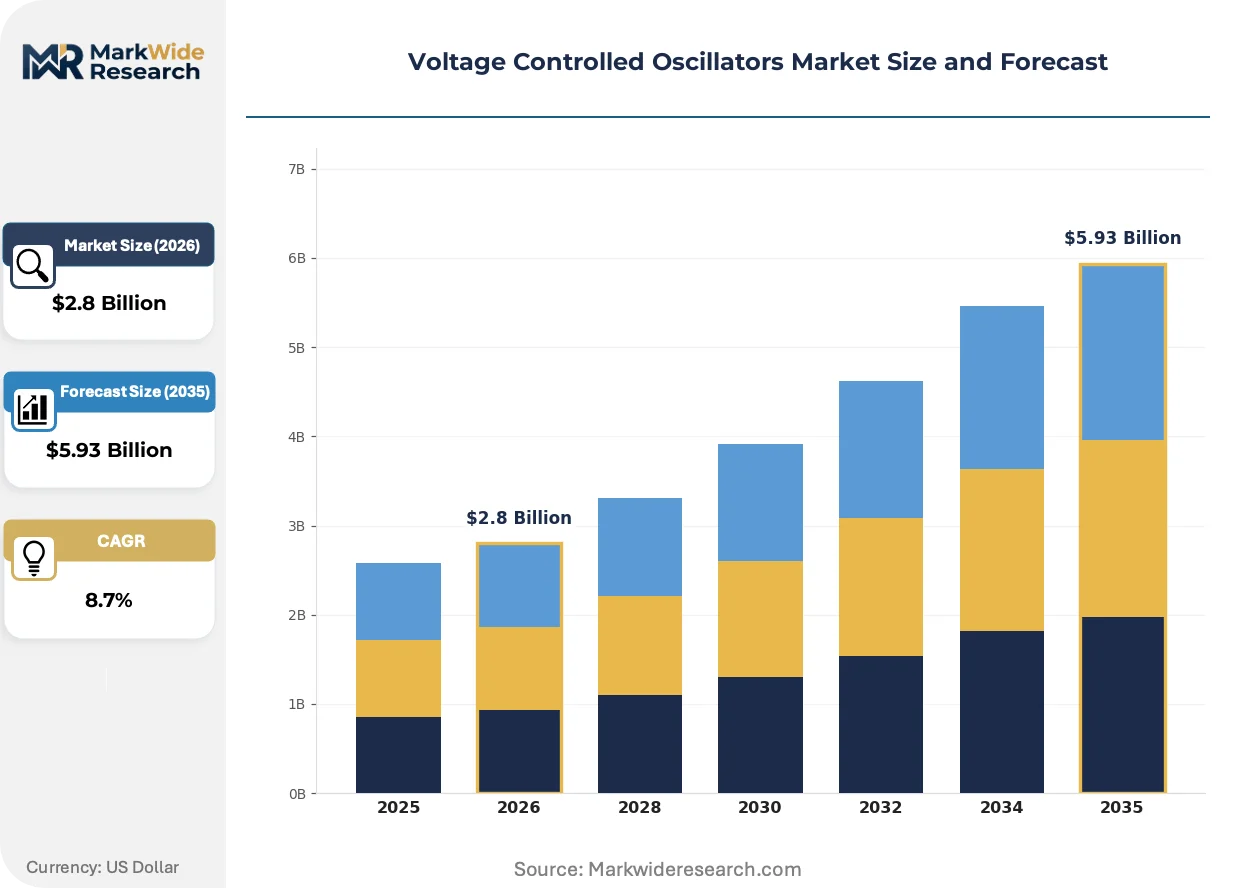
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz, MEMS, Relaxation, CMOS Technology: Analog, Digital, Hybrid, RF End User: Telecommunications, Automotive, Aerospace, Consumer Electronics Application: Signal Processing, Frequency Synthesis, Clock Generation, Modulation |
| Companies Covered | Analog Devices, Inc., SiTime Corporation, Texas Instruments, ON Semiconductor, Seiko Epson Corporation, MACOM, Crystek Corporation, Qorvo, Inc., Skyworks Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Controlled Oscillators Market Evolving Landscape
Frequency generation architectures are fragmenting across competing physical principles. Engineers now face choices between quartz stability, MEMS durability, and compound-semiconductor speed.
MEMS resonator technology is decomposing the traditional trade-off between spectral purity and mechanical resilience. Automotive radar suppliers are adopting silicon-based oscillators for under-hood environments where vibration tolerance outweighs absolute phase-noise performance. The shift is compressing addressable market share for conventional quartz designs in transportation and industrial applications.
ETSI's Radio Equipment Directive is mandating coexistence testing that elevates barrier-to-entry for non-European suppliers. Base-station qualification now requires demonstrated electromagnetic compatibility across harmonized EU frequency allocations. European prime contractors are consolidating supplier lists to reduce certification risk exposure.
Defense procurement officers are rotating toward radiation-hardened suppliers as sovereign space programs accelerate. Long-term service contracts with aerospace primes are displacing spot-market purchasing for high-reliability timing components. The shift is most visible in United States and South Korean satellite manufacturing clusters.
Voltage Controlled Oscillators Market Segmentation
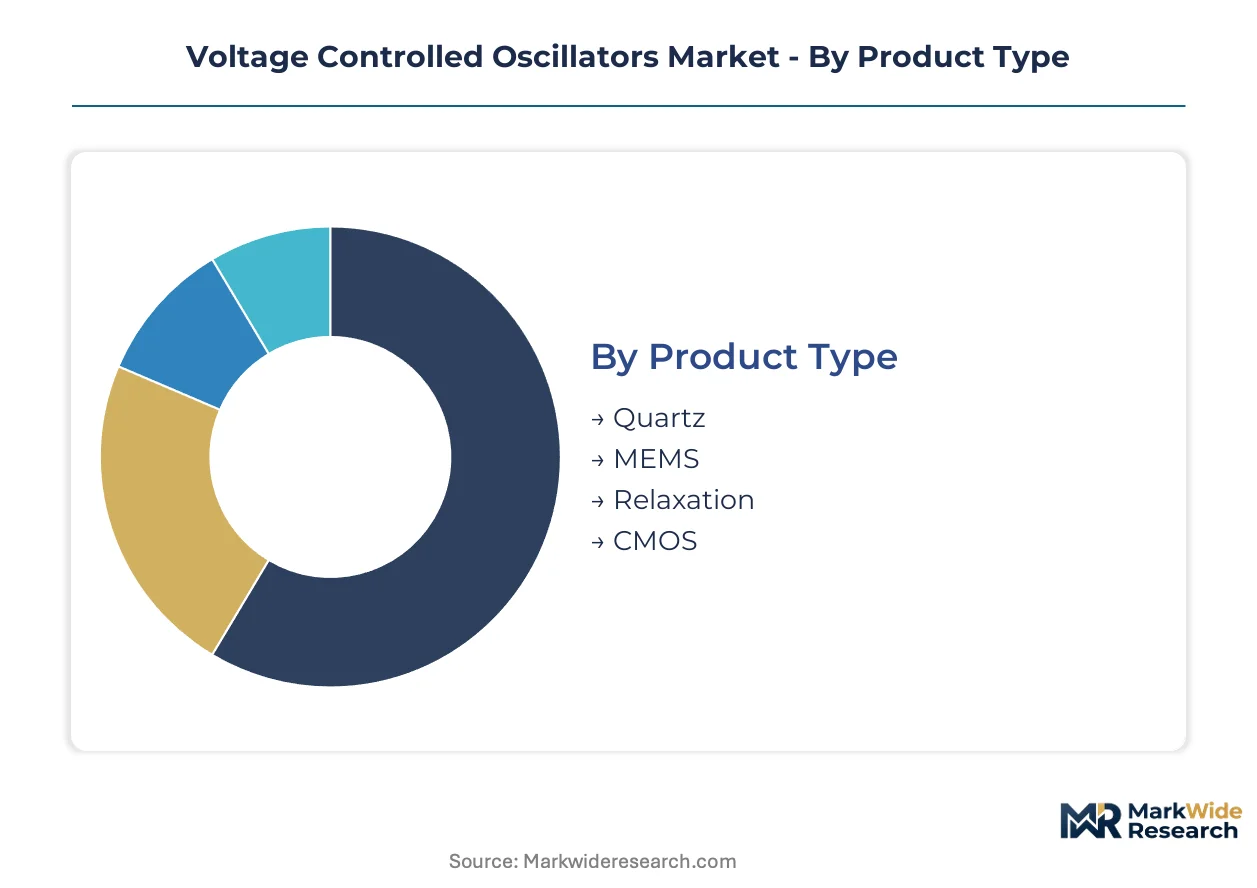
Voltage controlled oscillators serve fundamentally different performance requirements across quartz, MEMS, and semiconductor architectures. Segmentation reveals which technologies command premium positioning versus commodity substitution risk.
Product Type:
Quartz designs dominate domestic procurement in established telecom hubs, while MEMS variants travel further for automotive and portable electronics contracts.
- Quartz:Crystal-based resonators achieve phase noise below minus 120 dBc per Hz at one megahertz offset through decades of manufacturing refinement. South Korean base-station manufacturers anchor procurement volumes as 5G network densification accelerates precision timing requirements.
- MEMS:Silicon-based mechanical resonators sustain frequency stability across temperature extremes from minus 40 to 125 degrees Celsius. Automotive radar suppliers in Germany and Japan are displacing quartz in under-hood environments where vibration tolerance outweighs absolute spectral purity.
- Relaxation:RC-timed architectures enable low-cost integration in consumer electronics where jitter specifications remain relaxed.
- CMOS:Fully integrated ring oscillators serve system-on-chip clocking with minimal external component count.
Quartz holds the largest share; momentum sits with MEMS as mechanical robustness gains priority in transportation applications.
Technology:
Cost tiers separate analog simplicity from digital programmability, with hybrid architectures capturing mid-range positioning.
- Analog:Continuous voltage-to-frequency conversion delivers lowest power consumption for battery-operated devices. Portable equipment manufacturers in Japan favor analog-only designs where microampere-level current draw extends operational life.
- Digital:Numerically controlled oscillators enable software-defined frequency agility with register-based configuration. Telecommunications infrastructure builders in the United States require sub-microsecond switching that analog architectures cannot deliver.
- Hybrid:Analog core with digital calibration loops bridges performance and flexibility for industrial instrumentation.
- RF:Compound-semiconductor implementations using GaN-on-SiC substrates dominate millimeter-wave radar and electronic warfare frequency generation.
RF technology commands premium pricing; hybrid architectures are climbing fastest as equipment makers seek calibration without full digitization.
End User:
Application maturity determines whether customers prioritize established supply relationships or emerging technical specifications.
- Telecommunications:Base-station and small-cell deployments require precision timing for carrier aggregation and massive MIMO synchronization. FCC spectrum allocation frameworks and ETSI harmonized standards tighten phase-noise specifications simultaneously across United States and European procurement.
- Automotive:Radar and lidar sensing systems demand vibration immunity alongside frequency stability for adaptive cruise control and collision avoidance. German automotive Tier 1 suppliers are qualifying MEMS alternatives to quartz for engine-compartment mounting.
- Aerospace:Satellite and defense programs specify radiation-hardened designs with guaranteed performance across mission lifetimes.
- Consumer Electronics:Smartphones and wearables drive volume through integrated CMOS solutions with minimal bill-of-materials impact.
Telecommunications holds the largest share; automotive is expanding most quickly as advanced driver assistance systems proliferate across vehicle platforms.
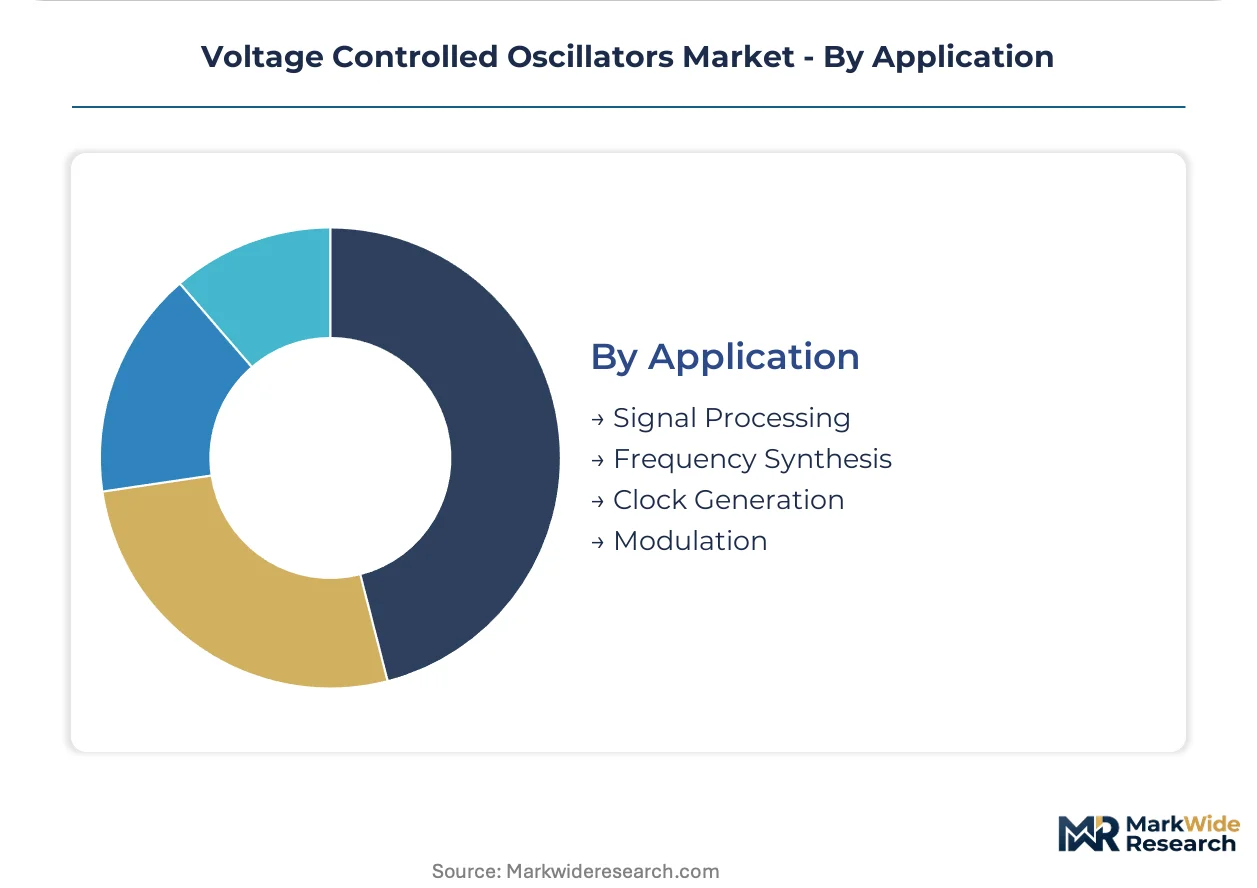
Application:
Customer type segmentation separates high-reliability buyers with long qualification cycles from volume purchasers with rapid product refresh rates.
- Signal Processing:Filtering and mixing operations in RF front-ends require low phase noise for adjacent channel selectivity. Defense electronics prime contractors in the United States specify ultra-low-noise designs for signals intelligence applications.
- Frequency Synthesis:Phase-locked loop reference generation demands stable tuning characteristics across temperature and supply variation. South Korean base-station manufacturers concentrate procurement for 5G macro cell deployment.
- Clock Generation:System timing distribution prioritizes low skew and jitter for synchronous digital logic.
- Modulation:Voltage-controlled frequency shift enables direct FM synthesis in software-defined radio architectures.
Frequency synthesis holds the largest share; signal processing shows the steepest expansion trajectory as electronic warfare investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors regional demand through its dense fiber-optic backbone and 5G infrastructure corridors, with regulatory frameworks simultaneously tightening electromagnetic compatibility requirements across multiple jurisdictions.
United States
Telecommunications infrastructure builders concentrate procurement in Texas and California corridor data centers as 5G network densification accelerates. FCC Title 47 spurious emission limits compel shielding investments across all qualified supplier portfolios. Defense electronics prime contractors in Arizona and Massachusetts sustain radiation-hardened VCO demand for satellite manufacturing clusters.
Germany
Automotive radar suppliers in Bavaria and Baden-Württemberg displace quartz with MEMS alternatives for under-hood mounting in electric vehicle platforms. ETSI Radio Equipment Directive coexistence testing elevates qualification barriers for non-European component vendors. Stuttgart-based Tier 1 suppliers consolidate approved vendor lists to reduce electromagnetic compatibility certification risk exposure.
South Korea
Samsung Electronics and domestic base-station manufacturers expand precision timing device procurement as 5G macro cell deployment deepens. National spectrum allocation frameworks align with ETSI harmonized standards for phase-noise specifications. Seoul Capital Area manufacturing clusters concentrate high-reliability VCO production for export to Southeast Asian network rollouts.
China
Domestic telecommunications equipment makers source timing components under MIIT type-approval certificate requirements that restrict uncertified foreign suppliers. Cybersecurity audit mandates for critical infrastructure components reshape competitive access conditions. Yangtze River Delta fabrication clusters advance CMOS-integrated oscillator production for consumer electronics volume contracts.
Japan
Portable equipment manufacturers favor analog-only VCO designs where microampere current draw extends battery operational life. METI industrial standards govern electromagnetic interference suppression for telecommunications and automotive applications. Nagoya and Osaka industrial corridors concentrate quartz crystal manufacturing heritage alongside emerging MEMS resonator development facilities.
Voltage Controlled Oscillators Market Competitive Landscape
Listed leaders compete with private specialists across technology architecture choices, with public semiconductor conglomerates holding scale advantages in RF compound-semiconductor implementations while private specialists anchor niche positions in MEMS resonator and radiation-hardened segments. Market structure exhibits tiered consolidation: a handful of diversified analog semiconductor houses control premium pricing in defense and satellite applications, mid-scale specialists compete on temperature resilience specifications, and commodity CMOS integrators serve consumer electronics volume. Three archetypes dominate: ultra-low-noise quartz traditionalists, MEMS-based mechanical robustness innovators, and GaN-on-SiC millimeter-wave speed leaders. Competitive moves center on backward integration into substrate supply and strategic partnerships for electromagnetic compatibility certification acceleration.
Within the diversified semiconductor house tier, Analog Devices, Inc. and Texas Instruments occupy positions representing ultra-low-noise design heritage and broad analog portfolio depth respectively. SiTime Corporation exemplifies the MEMS specialist archetype through silicon-based mechanical resonator architectures. Qorvo, Inc. anchors the compound-semiconductor velocity tier with GaN-on-SiC substrate implementations for millimeter-wave frequency generation.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| SiTime Corporation |
| Texas Instruments |
| ON Semiconductor |
| Seiko Epson Corporation |
| MACOM |
| Crystek Corporation |
| Qorvo, Inc. |
| Skyworks Solutions, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between South Korean base-station manufacturers and quartz crystal suppliers lock in supply access while anchoring price visibility across volatile raw material cycles. These contracts insulate procurement teams from spot-market swings in high-purity synthetic quartz feedstock while embedding volume-commitment penalties that reshape supplier selection criteria.
Pricing Analysis
Volume-discount tiering structures separate defense-grade radiation-hardened VCOs from automotive MEMS variants and consumer CMOS integrations. Pricing stratifies across military-aerospace certification tiers, commercial-industrial qualification levels, and unqualified commodity grades. Cost compression in consumer CMOS tiers is intensifying because Yangtze River Delta fabrication clusters are expanding captive oscillator production. Automotive radar suppliers show least price sensitivity due to qualification timelines that override component cost.
Supply Chain Analysis
Strait of Malacca transit underwrites quartz raw material flows from Southeast Asian mining operations to Japanese cutting and lapping facilities. Manufacturing concentrates in Japan, South Korea, and China, with compound-semiconductor substrate processing anchored in United States and European foundries. Raw material dependencies span high-purity synthetic quartz, GaN-on-SiC epitaxial wafers, and MEMS-grade silicon-on-insulator substrates. Single-source vulnerability in GaN substrate supply feeds from limited qualified vendors. Distribution runs through authorized distributor networks serving defense primes directly while channeling automotive and consumer volumes through regional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that cement incumbent positions. ETSI and FCC certification timelines extend qualification cycles beyond typical product refresh rates, embedding supplier relationships.
For Market Incumbents: Secure backward integration into GaN-on-SiC substrate supply to defend margin position against compound-semiconductor scarcity. Anchor certification investment in MIIT cybersecurity audit pathways to preempt Chinese market access restrictions for emerging MEMS competitors.
For New Entrants and Emerging Players: Anchor in automotive under-hood MEMS substitution where vibration tolerance specifications are displacing quartz faster than defense or telecom segments permit. Target German Tier 1 radar suppliers with temperature-extreme reliability data that accelerates qualification against established quartz vendors.
For Investors and Strategic Acquirers: Radiation-hardened VCO specialists with long-term aerospace service contracts represent the most defensible acquisition archetype. Monitor sovereign space program budget acceleration as the inflection signal for defense-timing component demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive GaN-on-SiC wafer sourcing insulates Qorvo and Analog Devices from epitaxial processing bottlenecks. |
| MIIT Cybersecurity Certification Investment | Domestic audit completion unlocks Chinese telecommunications infrastructure procurement for foreign timing component vendors. |
| Automotive MEMS Qualification Acceleration | German Tier 1 adoption of silicon-based oscillators for electric vehicle radar compresses quartz market share in transportation. |
| Radiation-Hardening Process Development | Aerospace prime contractor contracts displace spot-market purchasing for satellite mission-critical timing components. |
| Hybrid Analog-Digital Architecture Launch | Sub-microsecond frequency agility enables 5G base-station differentiation against pure analog competitors. |
Research Methodology
Initial hypotheses were tested against primary input from RF systems engineers, telecommunications procurement managers, defense electronics program officers, and automotive Tier 1 supplier quality directors and refined through secondary validation against FCC filing databases, ETSI harmonized standard documentation, MIIT type-approval registries, and semiconductor foundry capacity disclosures. Bottom-up segment sizing triangulated with top-down market envelope checks across quartz, MEMS, and compound-semiconductor technology categories.
Variance decomposition across product architecture, end-use qualification tier, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions spanned resonator technology type, frequency generation implementation, application performance requirement, and customer procurement pattern. CAGRs derived from segment-level volume trajectories and value-per-unit trends, with inputs including base-station deployment schedules, automotive radar content-per-vehicle curves, and satellite manufacturing order backlogs.
Material uncertainties — spectrum allocation delays, substrate supply disruptions, and cybersecurity audit timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding qualification cycle stability and foundry capacity expansion. Practitioners should keep alternative scenarios live as sovereign space program acceleration and automotive electrification penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Global Small Signal Diode Market