
 Silicon Dioxide Market | 2026-2036
Silicon Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Dioxide Market Intelligence
The capital-intensity divergence between integrated producers and merchant suppliers is reorganizing competitive tiers in the silicon dioxide landscape. Evonik Industries AG leverages its colloidal silica technology leadership to command premium positions in electronics polishing applications. Cabot Corporation sustains manufacturing scale advantages across multiple continents, while Sibelco N.V. anchors its position through deep backward integration into high-quality quartz deposits.
Silicon dioxide (SiO₂) is an inorganic compound occurring naturally as quartz or synthetically produced through thermal and wet chemical processes, with purity grades ranging from standard glass-making feedstocks to 99.999% semiconductor-grade material. Its primary industrial purpose spans from structural filler and desiccant functions to critical dielectric layers in microelectronic devices. Colloidal silica leads in electronics applications where nanoparticle size distribution controls polishing precision, while silica gel dominates desiccant markets with mature, cost-optimized supply chains. Crystalline silica faces structural pressure from regulatory reclassification, pushing margin pools toward synthetic fused silica alternatives.
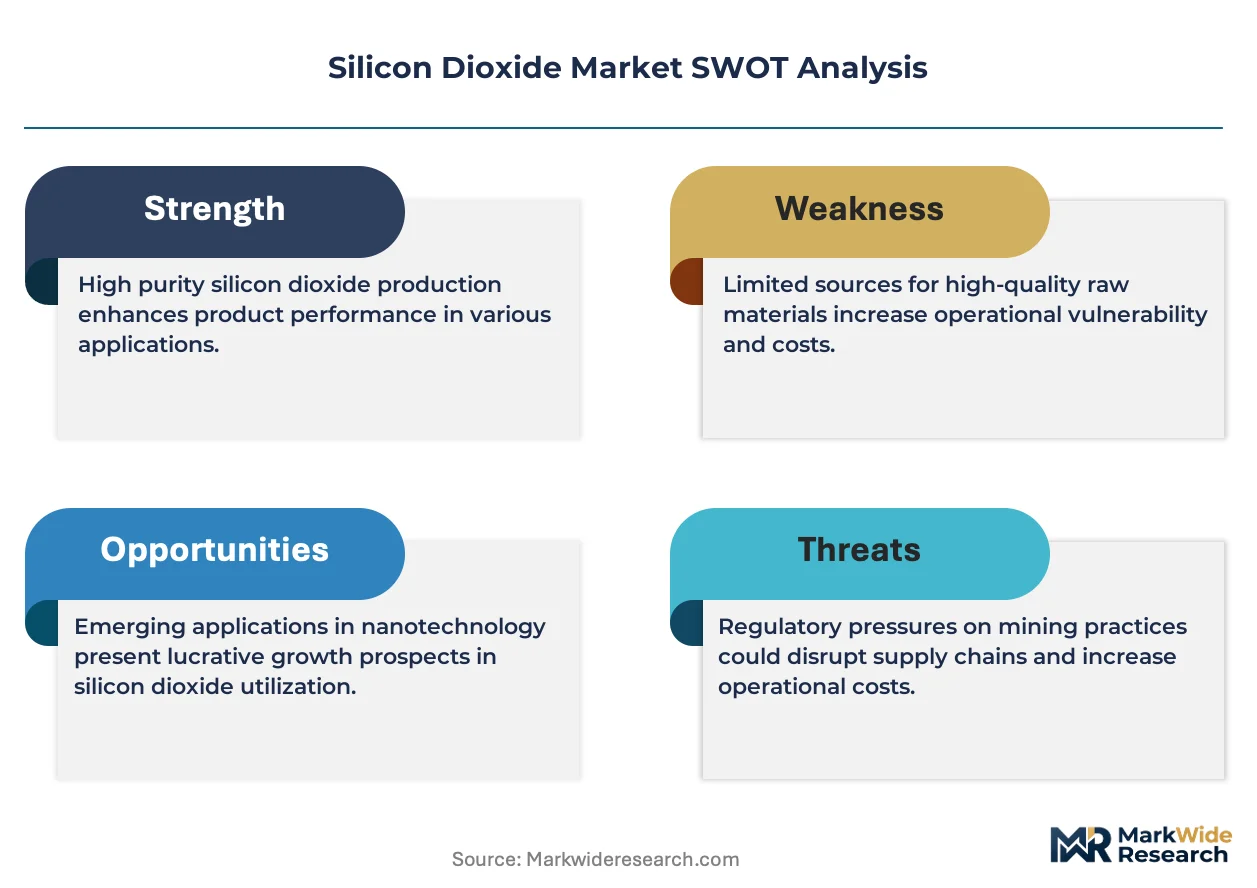
OSHA enforces permissible exposure limits for respirable crystalline silica in U.S. industrial settings, forcing producers to invest in surface-modified or encapsulated product forms. ECHA classifies certain crystalline silica grades under REACH carcinogen categories, restricting workplace handling protocols and import documentation across European manufacturing sites. Stakeholders must monitor the divergence between regulatory tightening on natural silica and the accelerating technical specifications from semiconductor customers demanding ever-higher synthetic purity.
Market Dynamics
Semiconductor fabrication nodes below 3nm are forcing silica suppliers to purify synthetic fused silica beyond 99.9999% while crystalline silica faces simultaneous regulatory pressure from OSHA and ECHA carcinogen reclassifications.
Growth Catalysts
- Semiconductor node shrinkage:Taiwan and South Korea foundries now specify ultra-low metal content silica for EUV lithography masks, pulling demand for synthetic fused silica grades that natural quartz cannot satisfy.
- OSHA silica rulemaking:Stricter respirable crystalline silica exposure limits in U.S. industrial settings are accelerating substitution toward surface-modified synthetic alternatives in construction and manufacturing applications.
- China captive consumption:Domestic wafer foundries and solar cell producers are scaling in-house silica processing, concentrating demand for specialized high-purity grades within vertically integrated supply chains.
Market Restraints
- Quartz deposit concentration:Premium high-purity natural silica reserves concentrate in limited geographies, creating supply security risks for merchant processors dependent on third-party feedstock.
- Energy input volatility:Synthetic fused silica production requires sustained high-temperature thermal processing, making margins vulnerable to natural gas and electricity price swings in Germany and the U.S. Gulf Coast.
- REACH documentation burden:ECHA carcinogen classification for certain crystalline silica grades imposes extensive workplace handling protocols and import documentation requirements across European manufacturing sites.
Strategic Opportunities
- India semiconductor subsidies:The country's PLI scheme for electronics manufacturing is attracting foundry investments that will require localized high-purity silica supply chains currently absent from the subcontinent.
- Colloidal silica-catalyst convergence:Nanoparticle size distribution control is enabling precision polishing applications in battery separator manufacturing, opening adjacent demand from electric vehicle cell producers.
- Solar ingot pulling:Photovoltaic-grade fused silica crucibles for monocrystalline silicon growth represent underpenetrated demand as wafer producers scale larger diameter ingots.
Industry Challenges
- Cleanroom certification timelines:Semiconductor-grade silica facilities require 18-24 month ISO 14644 cleanroom validation cycles that delay capacity expansion and lock working capital.
- Plasma etch compatibility testing:New synthetic silica formulations must undergo extensive qualification with lamina equipment from Applied Materials and Tokyo Electron, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Dioxide Market |
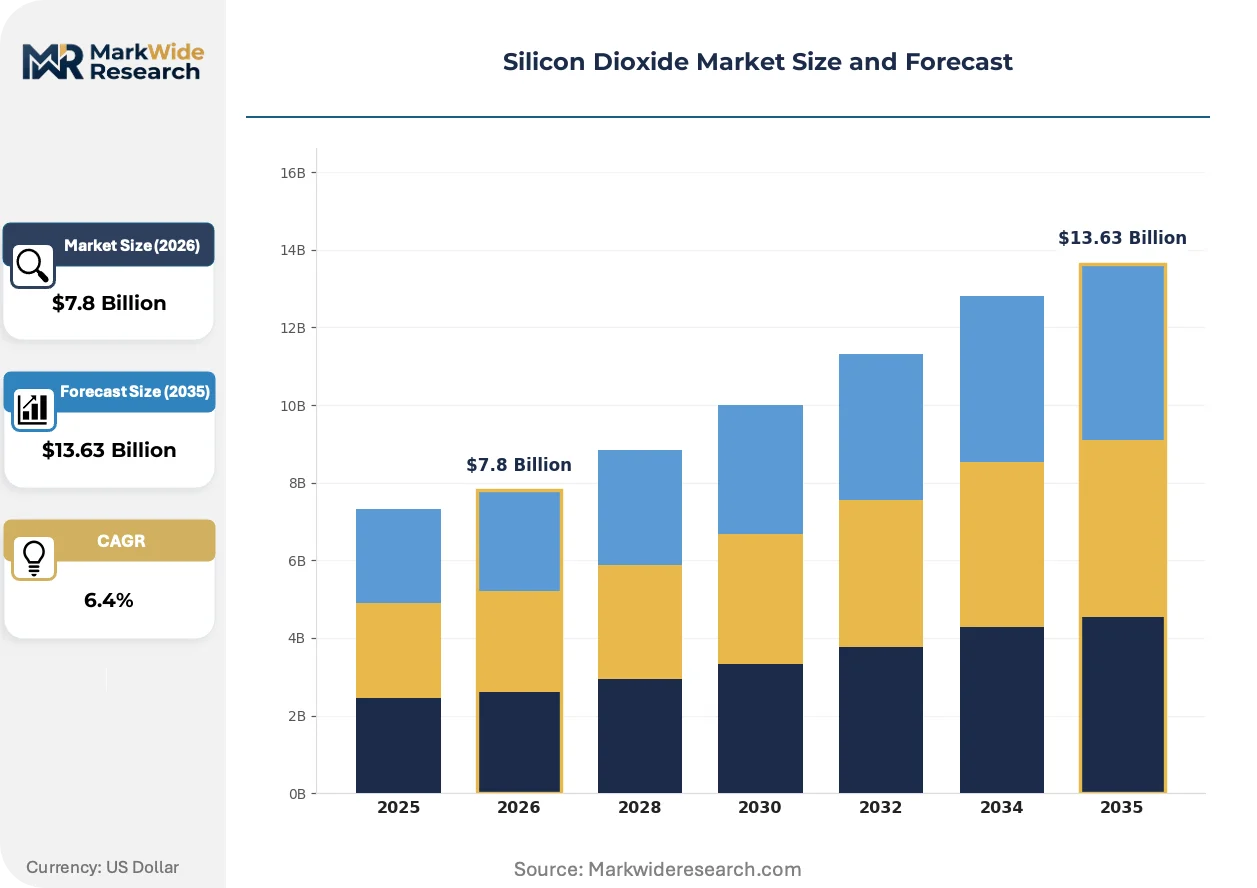
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Silica, Crystalline Silica, Colloidal Silica, Silica Gel End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Thickening Agent, Anti-Caking Agent, Desiccant, Insulating Material Form: Powder, Granules, Capsules, Suspension |
| Companies Covered | Solvay SA, PPG Industries, Inc., Evonik Industries AG, Tokuyama Corporation, Imerys SA, Cabot Corporation, Sibelco N.V., Heraeus Group, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Dioxide Market Strategic Shifts & Innovations
Process intensification in silica purification and surface functionalization is compressing the cost gap between synthetic and natural grades while regulatory pressure accelerates product-form innovation.
Sol-gel derived synthetic fused silica is decomposing the traditional hierarchy between premium natural quartz and standard synthetic grades. Memory chip manufacturers in South Korea and Taiwan are adopting sol-gel material for 3D NAND charge trap layers at volumes that natural suppliers cannot match. This synthetic route is decomposing regional supply advantages tied to quartz deposit geography.
REACH authorization requirements for crystalline silica are forcing European processors to reformulate surface coatings and particle encapsulation. Industrial abrasive and construction material suppliers must now document exposure mitigation measures or shift to engineered silica alternatives. German and French chemical processors are consolidating handling protocols to amortize compliance costs across product lines.
Direct procurement from silica gel and colloidal silica producers is displacing distribution intermediaries in desiccant and electronics polishing markets. Large semiconductor foundries and pharmaceutical packaging operations are establishing qualification programs that bypass regional chemical distributors. This channel compression is most visible in Japan and the Netherlands, where ASML and Tokyo Electron suppliers negotiate volume contracts directly with Evonik and Cabot manufacturing sites.
Silicon Dioxide Market Segmentation
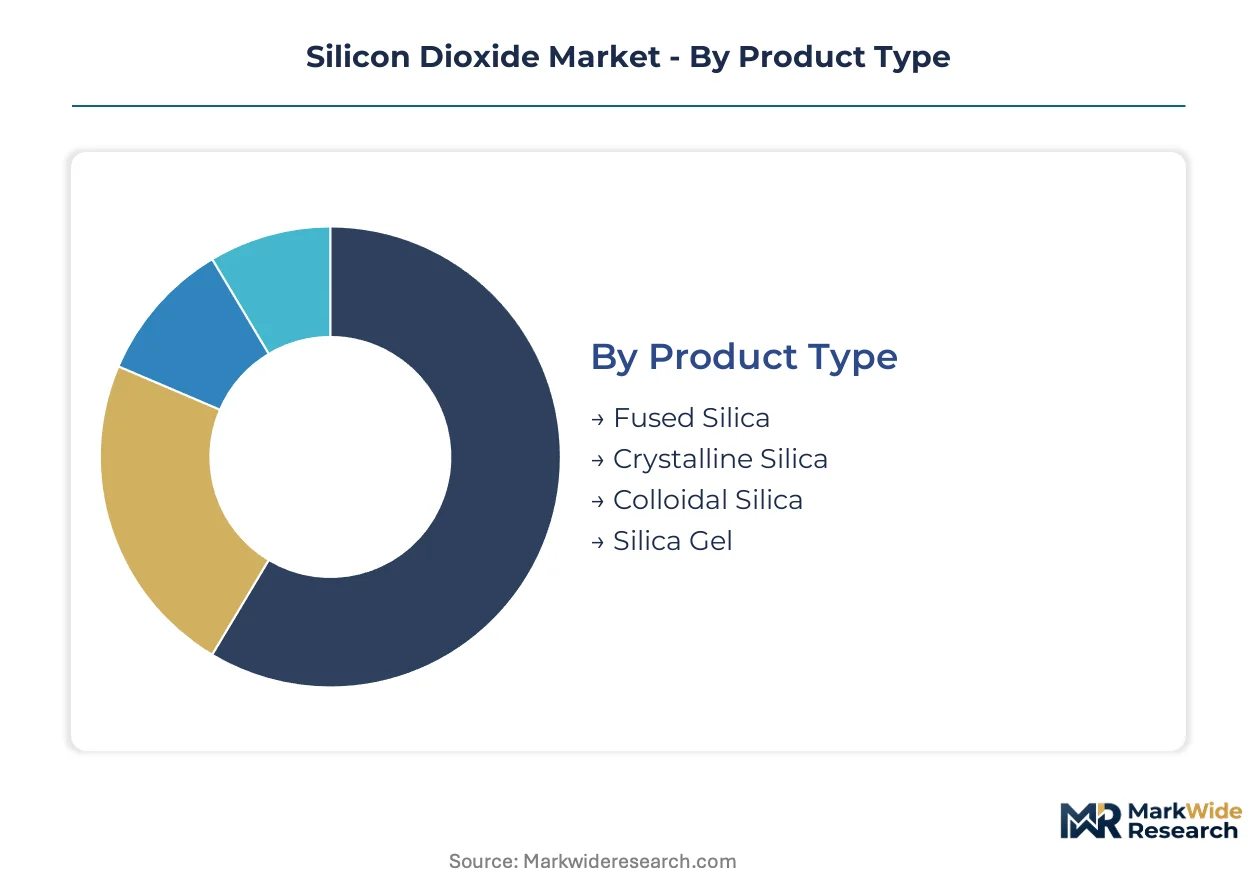
Silicon dioxide segmentation reveals how purity grades and physical forms dictate channel economics. Semiconductor-grade fused silica moves through direct procurement contracts, while commodity crystalline silica flows via distributors serving construction and industrial markets.
Product Type:
Channel concentration varies sharply by synthetic versus natural origin, with high-purity synthetic grades bypassing traditional chemical distribution entirely.
- Fused Silica:Synthetic amorphous silica produced through flame hydrolysis or electric arc melting achieves 99.999%+ purity. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify this grade for EUV lithography masks, pulling volume through direct long-term supply agreements rather than merchant channels.
- Colloidal Silica:Nanoparticle suspensions with controlled size distribution enable precision chemical-mechanical planarization in semiconductor wafer polishing. South Korean memory chip producers are expanding procurement of sub-50nm particle formulations for 3D NAND manufacturing, with Cabot and Evonik manufacturing sites negotiating directly with foundry procurement teams.
- Crystalline Silica:Naturally occurring quartz processed into sand and powder grades for glass, ceramics, and construction applications.
- Silica Gel:Mesoporous amorphous silica with high surface area serves desiccant and chromatography markets through established chemical distributor networks.
By volume, crystalline silica leads. By growth pace, fused silica is climbing the fastest.
End Use Industry:
Application maturity determines margin structure, with emerging electronics applications commanding premium pricing over established food and pharmaceutical uses.
- Electronics:Semiconductor fabrication, solar cell manufacturing, and display panel production consume ultra-high-purity synthetic grades. China domestic wafer foundries are scaling captive silica processing for 300mm wafer production, concentrating specialized grade demand within vertically integrated supply chains.
- Pharmaceuticals:Silica functions as glidant, anti-caking agent, and carrier in oral solid dosage forms. FDA IIG (Inactive Ingredient Guide) status and USP-NF compliance requirements lock supplier qualification timelines at 12-18 months, favoring incumbent producers with established drug master files.
- Food & Beverage:Anti-caking and free-flow applications in salt, seasonings, and powdered mixes represent mature demand with price-sensitive procurement.
- Cosmetics:Matting agents, thickeners, and sensory modifiers in skincare and color cosmetics utilize surface-treated silica grades.
Electronics generates the highest unit margins. Pharmaceuticals maintains the most stable contract volumes.
Application:
Functional performance requirements split the market between specification-driven semiconductor applications and cost-optimized industrial uses.
- Insulating Material:Fused silica's low thermal expansion and dielectric properties serve semiconductor packaging and high-voltage electrical insulation. Applied Materials and Tokyo Electron equipment qualification protocols extend sales cycles to 24+ months for new formulations.
- Desiccant:Silica gel moisture absorption protects pharmaceutical packaging, electronics, and industrial equipment. Mature manufacturing in China and India supplies global demand through established logistics networks with minimal product differentiation.
- Thickening Agent:Colloidal and fumed silica build viscosity in coatings, adhesives, and personal care formulations.
- Anti-Caking Agent:Precipitated silica maintains free-flow properties in hygroscopic powders across food and industrial applications.
Insulating material commands the steepest purity premiums. Desiccant operates on thinnest margins.
Form:
Physical state determines handling economics and regulatory classification, with powder forms facing stricter exposure controls than encapsulated alternatives.
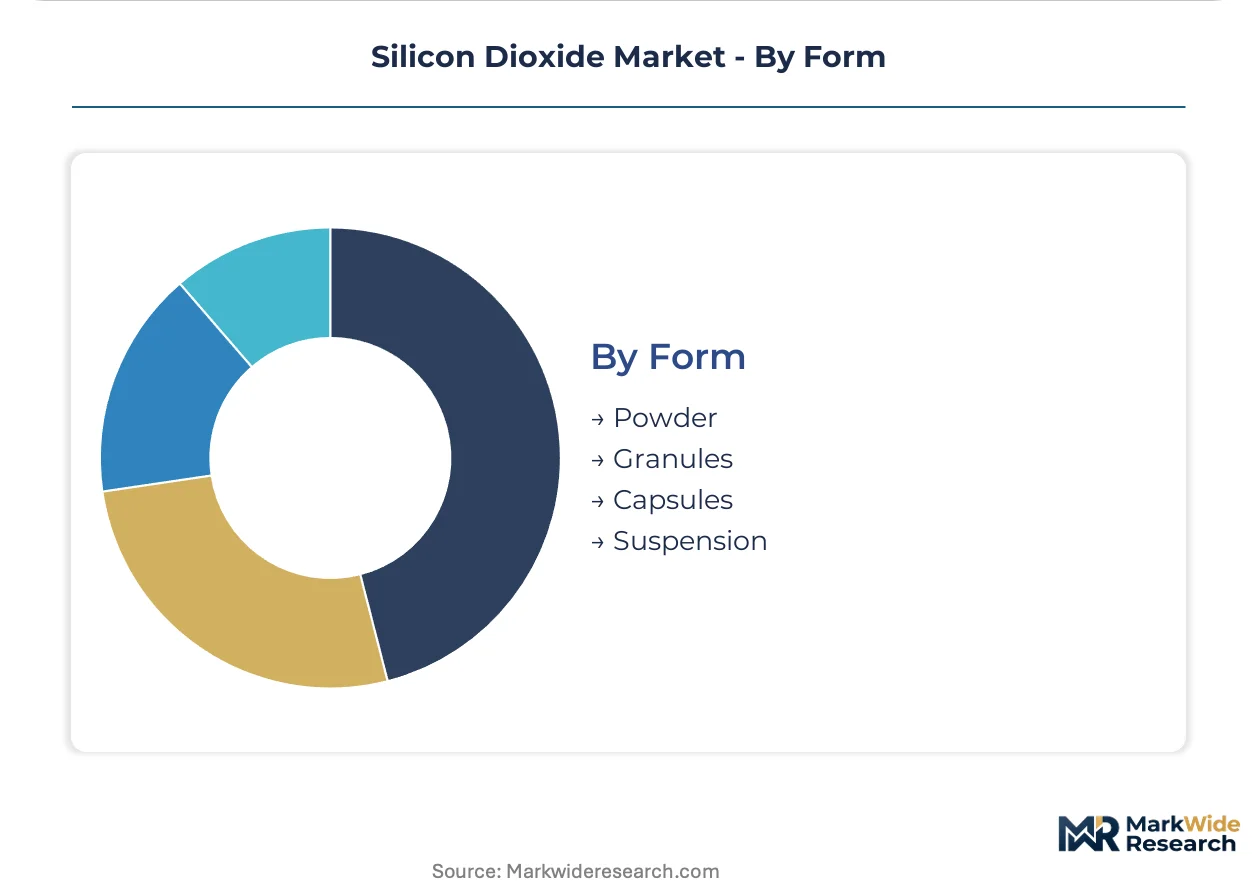
- Powder:Standard particulate form for industrial blending and processing. OSHA respirable crystalline silica exposure limits and ECHA carcinogen classifications are accelerating substitution toward surface-modified or granulated alternatives in European and U.S. manufacturing sites.
- Suspension:Colloidal silica in liquid carrier eliminates dust exposure and enables precision dispensing in semiconductor polishing. Tokyo Electron and ASML supplier qualification programs specify particle size distribution tolerances that only synthetic sol-gel producers consistently meet.
- Granules:Larger particle size reduces dust generation in construction and foundry applications.
- Capsules:Pre-measured desiccant packets serve pharmaceutical and electronics packaging with automated insertion compatibility.
Powder retains the largest installed base. Suspension is gaining share fastest in premium electronics channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in high-purity silicon dioxide tilt heavily toward East Asian fabrication hubs, while European and North American markets absorb specialized grades through direct procurement channels rather than spot trade.
China
Domestic wafer foundries and solar cell producers are scaling captive consumption of specialized silica grades. MIIT's dual carbon goals are tightening energy intensity standards for synthetic fused silica production in Jiangsu and Zhejiang provinces. The Yangtze River Delta cluster around Shanghai anchors the country's semiconductor-grade silica processing expansion.
United States
OSHA's stricter respirable crystalline silica exposure limits are accelerating substitution toward surface-modified synthetic alternatives in construction and manufacturing. The EPA maintains oversight of silica processing emissions under the Clean Air Act. Texas and Arizona host expanding solar ingot pulling operations that pull photovoltaic-grade fused silica demand.
Germany
ECHA's REACH carcinogen classification for certain crystalline silica grades imposes extensive workplace handling protocols across manufacturing sites. The EU Green Deal's industrial decarbonization targets are pressuring energy-intensive fused silica producers in Bavaria and North Rhine-Westphalia. The Eindhoven-Frankfurt corridor serves ASML supplier networks with precision colloidal silica formulations.
South Korea
Memory chip manufacturers specify ultra-low metal content silica for EUV lithography masks and 3D NAND charge trap layers. The MFDS regulates pharmaceutical-grade silica imports through drug master file requirements. The Seoul Capital Area and Busan-Ulsan corridor concentrate foundry procurement teams negotiating directly with synthetic silica producers.
Japan
Tokyo Electron and Applied Materials equipment qualification protocols extend sales cycles for new synthetic silica formulations to 24-plus months. METI's semiconductor supply chain resilience initiatives are subsidizing domestic high-purity silica stockpiling. The Kanto region around Tokyo hosts precision polishing compound formulators serving the country's display panel manufacturers.
Silicon Dioxide Market Key Industry Players
Concentration sits with integrated chemical conglomerates and specialized silica producers that command distinct technology positions. The vendor base organizes around three tiers: multinational diversified chemical groups with colloidal silica technology leadership, regional mining and processing specialists with quartz deposit control, and captive foundry processors building in-house purification capacity. Strategic moves center on backward integration into high-quality quartz reserves and direct procurement bypass of distribution intermediaries.
Within the technology-differentiated tier, Evonik Industries AG and Cabot Corporation exemplify premium positioning through nanoparticle size distribution control. Sibelco N.V. anchors the resource-backed segment with quarry-to-customer integration. Solvay SA and Wacker Chemie AG occupy positions bridging synthetic production scale with specialty chemical formulation expertise.
| Leading Market Players |
|---|
| Solvay SA |
| PPG Industries, Inc. |
| Evonik Industries AG |
| Tokuyama Corporation |
| Imerys SA |
| Cabot Corporation |
| Sibelco N.V. |
| Heraeus Group |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
Capacity utilization at synthetic fused silica plants in Germany and the United States shapes margin floors across the silicon dioxide landscape. High-purity grades command premium positions when energy costs spike, while crystalline silica processors absorb regulatory compliance burdens that compress price elasticity in construction channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium semiconductor-grade, standard industrial-grade, and economy construction-grade tiers. Price differentiation rests on purity certification levels and volume scale, with EUV lithography mask specifications from Taiwan Semiconductor Manufacturing Company commanding the widest spreads. Cost compression in commodity crystalline grades is intensifying because REACH documentation burdens and OSHA exposure compliance are layering fixed costs onto merchant processors. Pharmaceutical packaging operations exhibit the least price sensitivity due to locked supplier qualification timelines, while construction material distributors face the most acute pressure from substitute engineered minerals.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand that pulls synthetic fused silica through direct procurement channels bypassing traditional chemical distributors. China and the United States concentrate photovoltaic-grade crucible production that draws from high-purity quartz deposits in limited geographies. Single-source vulnerability concentrates around energy-intensive thermal processing capacity in Germany's industrial corridors. Distribution runs through qualified supplier networks for semiconductor grades and established logistics networks for desiccant and construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against engineered mineral substitutes in construction applications and synthetic sol-gel displacement of natural quartz in electronics channels. Substitution threats from surface-modified aluminosilicates and precision-ceramic alternatives are eroding crystalline silica's historical lock on industrial abrasive markets.
For Market Incumbents: Secure backward integration into high-quality quartz reserves in the Carolinas and Spruce Pine deposits to lock feedstock security against merchant supply volatility. Deepen ISO 14644 cleanroom certification pipelines to extend qualification moats around semiconductor foundry contracts. Synthetic sol-gel producers threaten natural quartz suppliers with superior purity consistency at volumes that memory chip manufacturers in South Korea now specify for 3D NAND charge trap layers.
For New Entrants and Emerging Players: Technical service gaps in colloidal silica formulation support present the most penetrable white-space target, as incumbent producers under-serve mid-tier foundries in India's PLI-subsidized electronics corridor. Battery separator manufacturing for electric vehicle cell producers offers adjacent demand with lower qualification barriers than semiconductor channels. A direct technical sales model bypassing regional distributors aligns with foundry procurement teams establishing volume contracts in Japan and the Netherlands.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized silica producers with demonstrated nanoparticle size distribution control and existing Tokyo Electron or Applied Materials equipment qualifications. Long-term viability over a five-to-ten-year window rests on synthetic purification capabilities that natural quartz processors cannot replicate. The signal to watch is ASML supplier network expansion timelines, which indicate inflection points for EUV lithography mask material demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Reserves | Spruce Pine and Carolina deposit control secures feedstock for high-purity synthetic processing. |
| Cleanroom Certification Pipeline Expansion | ISO 14644 validation cycles lock working capital but extend semiconductor foundry contract moats. |
| Direct Procurement Channel Development | Bypassing distributors aligns with TSMC and Samsung Foundry volume contract negotiation patterns. |
| Sol-Gel Synthetic Route Scale-Up | Flame hydrolysis capacity additions in Texas and Arizona serve solar ingot pulling demand growth. |
| Surface Modification Formulation Investment | Encapsulated crystalline silica grades mitigate OSHA and ECHA regulatory exposure liabilities. |
Research Approach
Desk research of trade flow databases, SEC 10-K filings, and ECHA REACH registration dossiers preceded structured interviews with plant managers at fused silica production facilities, procurement leads at semiconductor foundries, distribution channel partners in industrial chemicals, and technical R&D directors at colloidal silica formulators. Primary fieldwork combined with secondary validation from customs records and Cefic industry reports enabled bottom-up capacity modeling and top-down demand triangulation across electronics, pharmaceutical, and construction end-uses.
Variance decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, and regional production hub. The analytical framework models synthetic versus natural origin splits, purity certification levels, and channel concentration patterns. CAGRs were derived from installed base expansion rates and technology substitution curves, with semiconductor node shrinkage timelines and solar cell capacity buildouts serving as key forecast inputs.
Underlying assumptions cover energy price stability in German and U.S. Gulf Coast production corridors, with deviation risk concentrated in MIIT dual carbon policy enforcement timelines and OSHA rulemaking implementation pace. Forecasts reflect these conditions with recalibration cycles aligning with material shifts in foundry capital expenditure announcements and ECHA authorization requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Quartz Market
Semiconductor Material
Semiconductor PI Film Market