
 High Speed Data Converters Market | 2026-2036
High Speed Data Converters Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Data Converters Market Foresight
Asian foundry capacity for gallium nitride and silicon germanium processes is decoupling from legacy CMOS supply chains dedicated to consumer-grade converters. Texas Instruments Incorporated anchors North American supply through captive 300mm fabrication for precision SAR devices. Analog Devices, Inc. dominates high-performance pipeline segments for aerospace radar systems. Infineon Technologies AG extends its position in automotive-qualified converters through AEC-Q100 certified sigma-delta architectures.
High speed data converters are mixed-signal integrated circuits that translate between analog waveforms and digital bitstreams at sampling rates exceeding 10 MSPS, with resolution typically spanning 8 to 16 bits and interface standards including JESD204B/C serial links for deterministic latency in phased-array systems. Pipeline ADC technology leads military and communications applications where throughput demands exceed 500 MSPS, while sigma-delta architectures occupy precision industrial automation segments requiring 24-bit resolution at lower speeds. Flash converters sustain niche imaging systems roles where parallel conversion eliminates pipeline latency, though power dissipation constrains deployment density.
The Federal Communications Commission's spectrum auction rules in the United States mandate spurious-free dynamic range benchmarks that filter out non-compliant converter suppliers from 5G base station procurement. The European Telecommunications Standards Institute and the EU Radio Equipment Directive jointly enforce electromagnetic compatibility thresholds that shape product development roadmaps for software-defined radio manufacturers. Stakeholders must monitor foundry allocation priorities between defense-certified and commercial-grade process nodes as geopolitical export controls tighten.
Market Dynamics
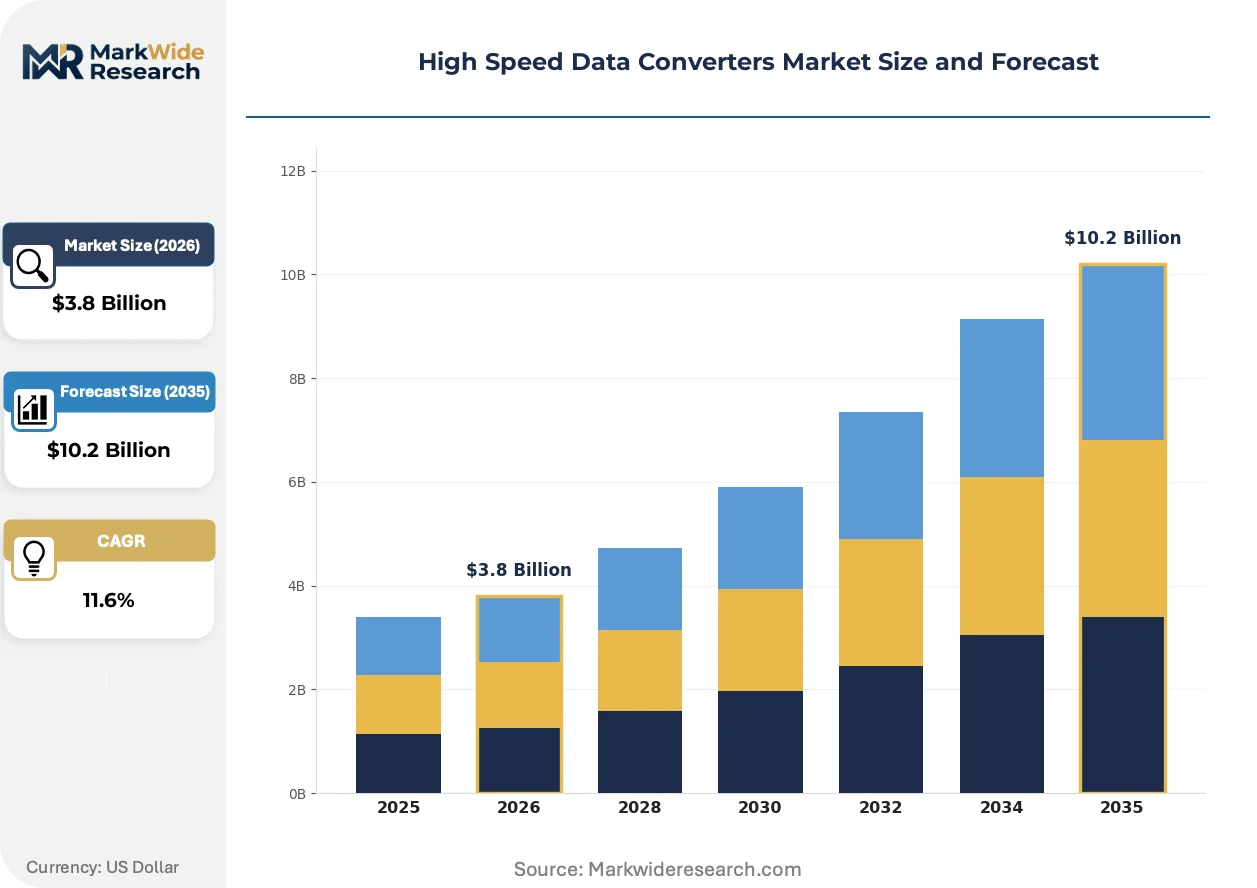
Pipeline ADC architectures are displacing successive-approximation designs in 5G massive MIMO arrays, while gallium nitride foundry allocation battles between defense and commercial buyers reshape supply security calculations for converter vendors.
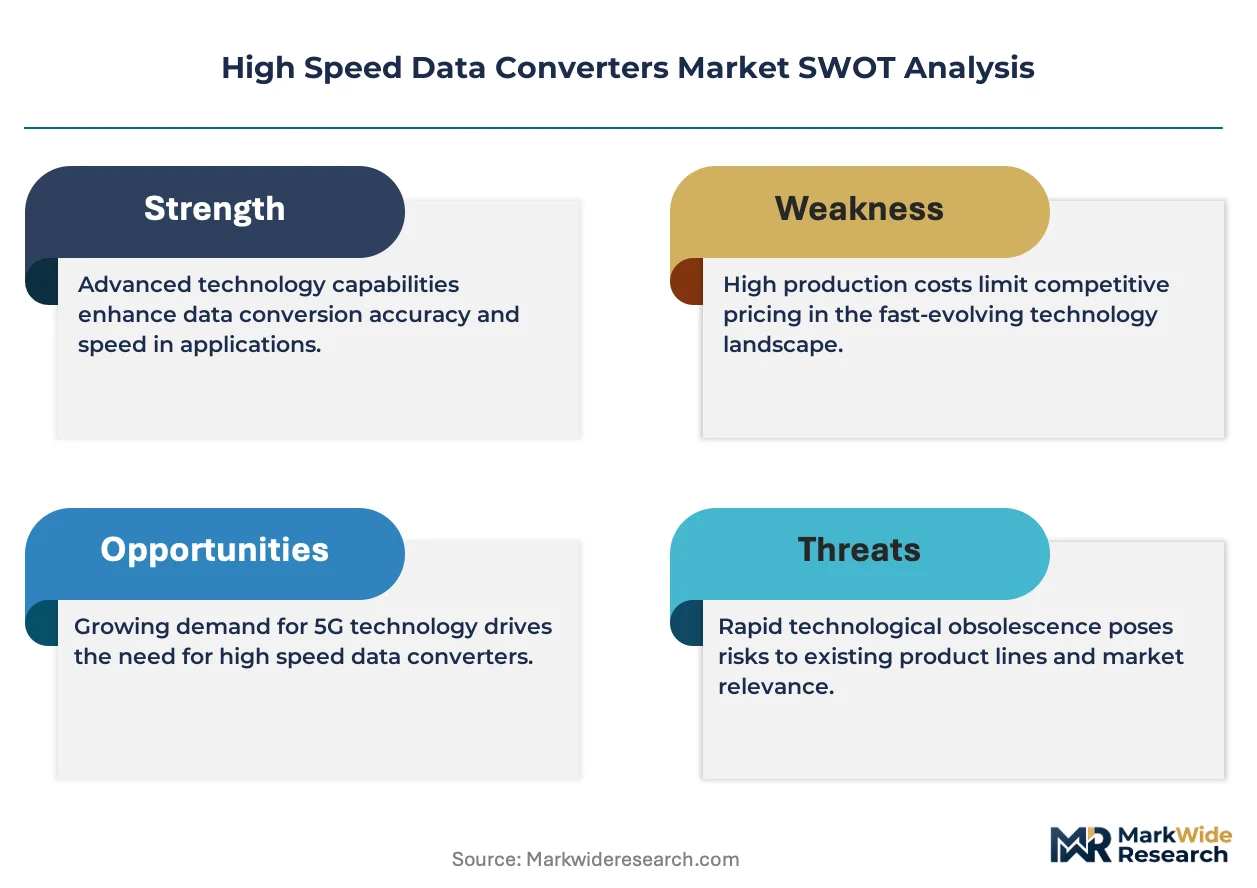
Growth Catalysts
- 5G Infrastructure Deployment:China's MIIT spectrum allocations for millimeter-wave bands drive base station densification programs requiring 500 MSPS+ converters. Korean and Japanese carriers mirror these procurement patterns.
- EU Radio Equipment Directive:Electromagnetic compatibility mandates for software-defined radio manufacturers create certified-product premiums that filter out non-compliant suppliers from European defense procurement channels.
- Silicon Germanium Process Maturation:Asian foundries are decoupling specialty SiGe capacity from legacy CMOS lines, enabling higher linearity converters for phased-array radar without consumer-grade process contamination risks.
Market Restraints
- Wafer Cost Volatility:300mm silicon germanium substrate prices fluctuate with defense foundry allocation priorities, compressing margins for precision SAR ADC suppliers without captive fabrication.
- Flash Converter Power Ceiling:Parallel conversion architectures dissipate heat densities that constrain deployment in portable imaging systems, limiting addressable market scope.
- Export Control Friction:Dual-use technology classifications under Wassenaar Arrangement protocols delay licensing timelines for radar-grade pipeline converters shipped to non-allied aerospace programs.
Strategic Opportunities
- Automotive Lidar Integration:AEC-Q100 certification pathways for sigma-delta architectures open design-in opportunities with tier-one sensor module suppliers serving German and Japanese vehicle programs.
- India Defense Modernization:Indigenous electronics procurement mandates under Make-in-India frameworks create joint-venture openings for converter vendors willing to transfer packaging and test operations to local facilities.
- JESD204C Convergence:Deterministic latency standards are integrating with ethernet-based fronthaul architectures, enabling converter suppliers to displace discrete clock distribution chips in distributed antenna systems.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Pipeline ADC layout expertise concentrates among senior designers at established IDMs, constraining fabless entrants seeking to compete in military-qualified segments.
- Defense Certification Timelines:MIL-STD-883 test protocols for radiation-hardened converters extend product development cycles to 36-48 months, freezing engineering resources across multiple program generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Data Converters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog-to-Digital Converter, Digital-to-Analog Converter, Mixed-Signal Converter, High-Speed ADC Technology: Successive Approximation, Sigma-Delta, Pipeline, Flash Converter End User: Aerospace, Telecommunications, Consumer Electronics, Industrial Automation Application: Signal Processing, Data Acquisition, Imaging Systems, Software Defined Radio |
| Companies Covered | Analog Devices, Inc., Texas Instruments Incorporated, Microchip Technology Inc., Infineon Technologies AG, Renesas Electronics Corporation, NXP Semiconductors N.V., STMicroelectronics N.V., Broadcom Inc., ON Semiconductor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Data Converters Market Shifts & Advancements
Deterministic latency requirements and power-density constraints are forcing architectural pivots across converter design teams. Three developments dominate competitive positioning.
Time-interleaved pipeline architectures are integrating calibration engines that correct gain and offset mismatches in real time. Base station OEMs in South Korea and Japan are adopting these devices for 64T64R massive MIMO configurations. The technology is compressing bill-of-materials counts by eliminating external calibration ASICs previously required for channel matching.
The FCC's spurious-free dynamic range benchmarks for C-band auction winners are mandating 14-bit effective resolution at 3.5 GHz input frequencies. Base station radio manufacturers must redesign signal chains to meet these thresholds or forfeit eligibility for rural deployment subsidies. Converter suppliers with pre-certified reference designs are capturing procurement preference at the expense of generic catalog vendors.
Defense primes are consolidating vendor lists around suppliers offering in-package digital downconversion. This behavior eliminates discrete FPGA resources from size-constrained airborne platforms. The shift is most visible in Swedish and Israeli radar programs, where payload volume constraints override legacy subsystem boundaries.
High Speed Data Converters Market Segmentation
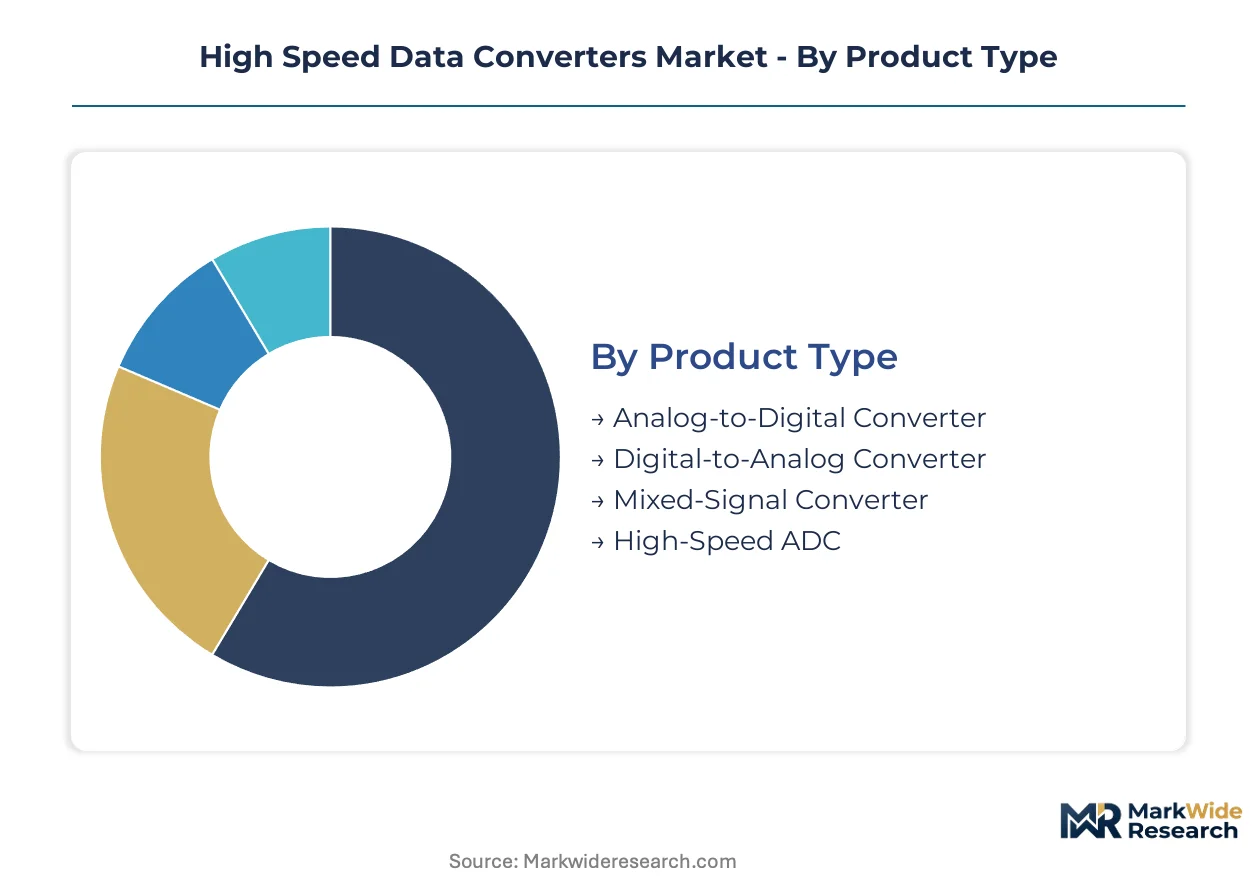
Converter procurement patterns diverge sharply across signal chain positions, with ADC suppliers capturing defense-grade premiums while DAC vendors compete on integration density for consumer applications. Architectural choices in each segment dictate foundry partnerships, certification pathways, and margin structures that resist cross-segment arbitrage.
Product Type:
Supply concentration tilts toward precision ADC suppliers with captive fabrication, while commodity DAC production fragments across Asian foundry networks.
- Analog-to-Digital Converter:Pipeline and SAR architectures dominate military and 5G base station deployments, with JESD204B/C interfaces mandatory for phased-array synchronization. China's MIIT spectrum allocations and Korean carrier densification programs drive demand for 14-bit resolution at 500 MSPS+ sampling rates.
- Digital-to-Analog Converter:High-speed current-steering designs serve software-defined radio transmitters, where spurious-free dynamic range thresholds set by the FCC's C-band auction rules filter out non-compliant vendors from rural deployment subsidies.
- Mixed-Signal Converter:Integrated transceivers reduce board space in portable instrumentation, though power dissipation constrains deployment density for battery-operated field equipment.
- High-Speed ADC:Time-interleaved architectures with embedded calibration engines compress bill-of-materials counts in 64T64R massive MIMO configurations, displacing external channel-matching ASICs.
ADC variants absorb the bulk of installed capacity; mixed-signal converters are expanding most quickly through baseband integration trends.
Technology:
Process node allocation battles between defense and commercial buyers reshape which architectures secure foundry priority.
- Pipeline:Multi-stage conversion with interstage amplifiers achieves throughput exceeding 1 GSPS for radar and 5G massive MIMO arrays. Asian foundries are decoupling specialty gallium nitride capacity from legacy CMOS lines to serve these linearity demands.
- Sigma-Delta:Oversampling with noise-shaping loops delivers 24-bit resolution at sub-MHz speeds for precision industrial automation, with AEC-Q100 certification opening automotive lidar design-ins.
- Successive Approximation:Binary-search architectures dominate medium-speed instrumentation where 16-bit resolution at 10-100 MSPS balances cost and performance for test equipment OEMs.
- Flash Converter:Parallel comparator banks eliminate pipeline latency for imaging systems, though heat densities restrict deployment in portable ultrasound and thermal cameras.
Pipeline designs command the dominant share of defense procurement; sigma-delta architectures are climbing the fastest through automotive qualification pathways.
End User:
Customer concentration varies by certification burden, with aerospace programs consolidating vendor lists while consumer electronics fragments across price tiers.
- Aerospace:MIL-STD-883 test protocols for radiation-hardened converters extend development cycles to 36-48 months, freezing engineering resources and favoring established IDMs with legacy program experience.
- Telecommunications:Base station OEMs in South Korea and Japan prioritize pre-certified reference designs that meet FCC spurious-free dynamic range benchmarks, displacing generic catalog vendors from rural deployment eligibility.
- Consumer Electronics:Smartphone and tablet integration demands drive cost-down pressure on 8-12 bit converters, with procurement shifting to Asian fabless suppliers without defense certification overhead.
- Industrial Automation:Precision motor control and process instrumentation require 20-24 bit resolution at modest speeds, with EU Radio Equipment Directive electromagnetic compatibility mandates filtering non-compliant suppliers from European procurement channels.
Telecommunications absorbs the bulk of high-volume procurement; aerospace is gaining share fastest through radar modernization programs.
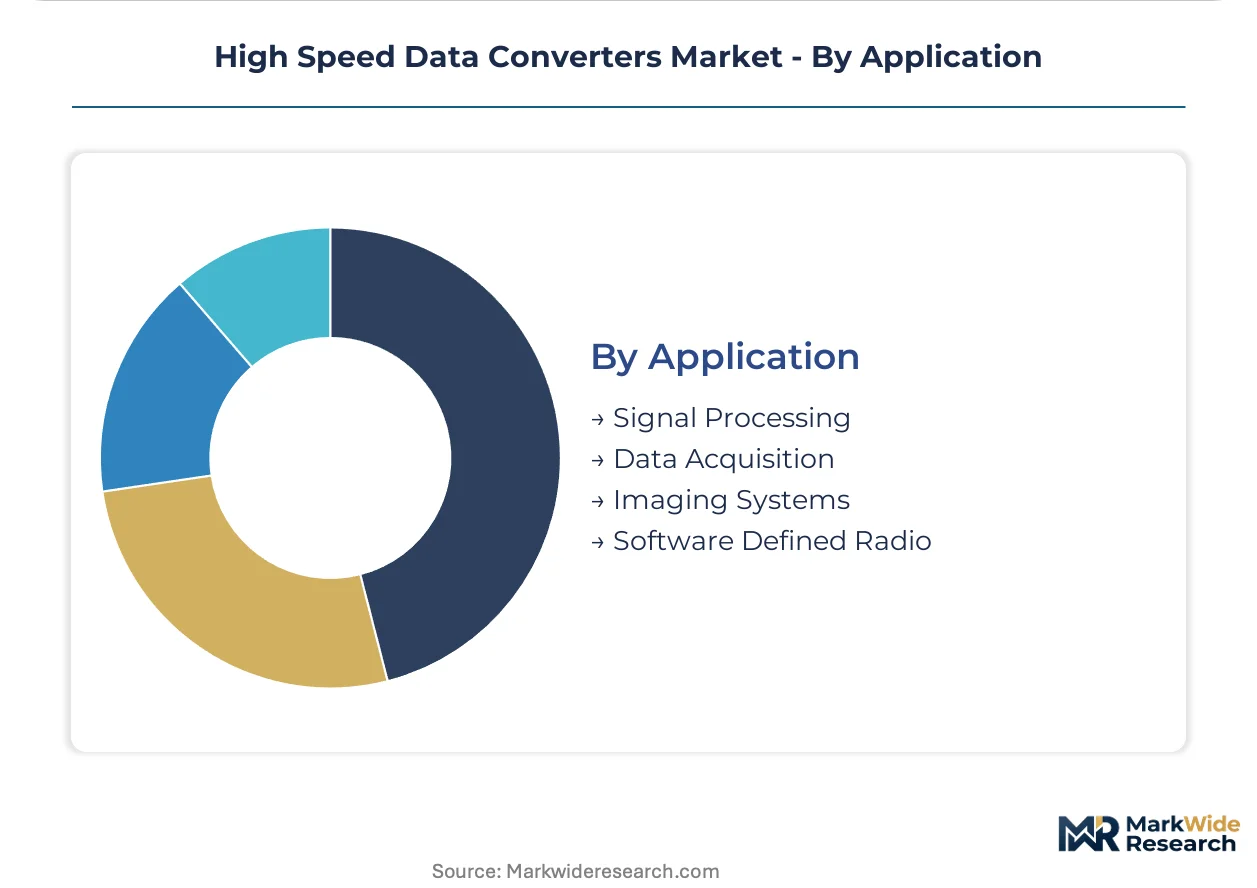
Application:
System-level integration trends are collapsing discrete converter boundaries into broader signal chain subsystems.
- Signal Processing:Real-time digital downconversion in packaged converters eliminates discrete FPGA resources from size-constrained Swedish and Israeli airborne radar platforms.
- Data Acquisition:Deterministic latency requirements for distributed antenna systems are integrating JESD204C standards with ethernet-based fronthaul architectures, displacing discrete clock distribution chips.
- Imaging Systems:Medical ultrasound and thermal cameras demand flash converter speeds without pipeline latency, though power dissipation limits channel density.
- Software Defined Radio:Reconfigurable front-ends for military and commercial communications must satisfy both FCC emission masks and EU Radio Equipment Directive electromagnetic compatibility thresholds.
Signal processing captures the dominant installed base; data acquisition is expanding most quickly through fronthaul integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate supply from Asian foundries anchors geographic demand distribution for high speed data converters. Defense procurement clusters and telecommunications infrastructure deployment create divergent regional growth patterns.
United States
5G base station densification and phased-array radar modernization drive converter procurement from defense primes and telecommunications OEMs. FCC spurious-free dynamic range benchmarks for C-band auction winners mandate 14-bit resolution at 3.5 GHz. Boston and Austin host design centers where pipeline ADC expertise concentrates for military-qualified segments.
China
MIIT spectrum allocations for millimeter-wave bands accelerate base station deployment requiring 500 MSPS+ converters. Dual-use technology export controls under Wassenaar Arrangement protocols complicate licensing for radar-grade components. Yangtze River Delta manufacturing clusters decouple specialty GaN capacity from legacy CMOS consumer lines.
Germany
Automotive lidar integration and industrial automation precision requirements expand sigma-delta converter demand. EU Radio Equipment Directive electromagnetic compatibility mandates filter non-compliant suppliers from defense procurement channels. Bavaria hosts AEC-Q100 certification facilities serving tier-one sensor module suppliers.
Japan
METI industrial policy prioritizes domestic converter supply security for telecommunications infrastructure. Korean and Japanese carriers mirror Chinese procurement patterns for massive MIMO configurations. Tokyo-Osaka corridor concentrates design expertise for time-interleaved pipeline architectures with embedded calibration engines.
South Korea
Carrier densification programs for 5G millimeter-wave deployment drive 64T64R massive MIMO converter demand. K-band spectrum allocation policies shape base station radio manufacturer qualification requirements. Seoul metropolitan area hosts base station OEMs adopting JESD204C deterministic latency standards for distributed antenna systems.
High Speed Data Converters Market Competitive Landscape
Global majors compete with regional champions across foundry access and defense certification pathways. The supplier base organizes into three tiers: IDMs with captive 300mm fabrication, fabless specialists leveraging Asian foundry partnerships, and diversified semiconductor conglomerates with automotive qualification portfolios. Strategic moves center on GaN process allocation security and MIL-STD-883 test protocol compliance acceleration.
Among North American IDMs, Analog Devices, Inc. and Texas Instruments Incorporated exemplify the captive-fabrication archetype for precision and high-performance segments. Infineon Technologies AG represents European diversification into automotive-qualified converter architectures through AEC-Q100 certification pathways. These three anchors illustrate how geographic process control and end-market specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Texas Instruments Incorporated |
| Microchip Technology Inc. |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| NXP Semiconductors N.V. |
| STMicroelectronics N.V. |
| Broadcom Inc. |
| ON Semiconductor Corporation |
| Others |
Supply & Pricing Matrix
300mm silicon germanium substrate price volatility cascades through converter supply chains into three distinct procurement tiers: defense-certified pipeline ADCs with bundled MIL-STD-883 testing, automotive-qualified sigma-delta devices with AEC-Q100 traceability, and unbundled catalog components for consumer electronics.
Pricing Analysis
Extended warranty and calibration-service bundling separates defense-grade pipeline ADC suppliers from commodity vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FCC pre-certified reference designs commanding procurement preference over generic alternatives. Cost compression in consumer-grade segments is intensifying because Asian fabless suppliers compete without defense certification overhead. Tier-one base station OEMs exhibit lowest price sensitivity; portable imaging system manufacturers face acute margin pressure from flash converter thermal constraints.
Supply Chain Analysis
Returns and refurbishment flows for radiation-hardened converters extend product lifecycles through defense aftermarket channels. Supply concentrates in Taiwan, South Korea, and the United States for specialty GaN and SiGe foundry capacity. Raw material dependencies include 300mm silicon germanium substrates, gallium nitride epitaxial wafers, and JESD204B/C interface IP cores. Single-source vulnerability in Asian GaN foundry allocation creates procurement risk for radar-grade pipeline architectures. Distribution runs through authorized distributors serving defense primes and direct OEM relationships for telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where time-interleaved pipeline architectures with embedded calibration engines displace external channel-matching ASICs across 5G massive MIMO deployments.
For Market Incumbents: To counter fabless entrants leveraging Asian foundry partnerships, Analog Devices and Texas Instruments should deepen captive 300mm fabrication for precision SAR devices while accelerating MIL-STD-883 test protocol compliance timelines to freeze engineering resources ahead of competitor qualification cycles.
For New Entrants and Emerging Players: Automotive lidar integration represents the most penetrable white-space target, with AEC-Q100 certification pathways opening design-in opportunities at tier-one sensor module suppliers serving German and Japanese vehicle programs through sigma-delta architecture specialization.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive GaN fabrication in the United States, positioned to capture defense procurement preference as Wassenaar Arrangement licensing delays constrain non-allied supply. Long-term viability hinges on foundry allocation security rather than design innovation alone. Monitor MIIT spectrum allocation announcements for millimeter-wave band expansion as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive gallium nitride fabrication secures linearity performance for phased-array radar programs in Sweden and Israel. |
| JESD204C Interface Certification | Deterministic latency standards enable displacement of discrete clock distribution chips in Korean distributed antenna systems. |
| AEC-Q100 Automotive Qualification | Sigma-delta certification opens design-ins with Bavaria-based tier-one sensor module suppliers. |
| India Joint Venture Localization | Make-in-India packaging and test transfers satisfy indigenous electronics procurement mandates for defense modernization. |
| In-Package Digital Downconversion | Integrated DDC eliminates discrete FPGA resources from size-constrained airborne radar platforms. |
Research Methodology
SEC 10-K filings, EIA semiconductor trade data, and FCC equipment authorization databases formed the secondary backbone, supplemented by primary interviews with base station OEM procurement directors, defense prime subsystem engineers, foundry capacity planners, and automotive tier-one sensor module suppliers. Bottom-up and top-down triangulation validated unit shipment estimates against process node allocation disclosures.
Historical trendline analysis across converter architecture transitions informed the analytical framework, with segmentation dimensions spanning product type, technology node, end-user certification tier, and regional regulatory cluster. CAGRs derived from foundry capacity expansion schedules and carrier densification program announcements, with GaN substrate supply elasticity and Wassenaar licensing velocity as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including abrupt export control reclassifications and foundry force majeure events. Forecasts reflect documented assumptions about spectrum allocation timing and defense budget authorization cycles. Practitioners should monitor MIIT millimeter-wave band announcements and EU Radio Equipment Directive enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
China MLCC Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Semiconductor Wafer Market