
 Underfill Market | 2026-2036
Underfill Market Size, Share, and Industry Trends Forecast 2026-2036
Underfill Market Outlook
JEDEC J-STD-020 moisture sensitivity qualification is unwinding the competitive landscape, forcing material suppliers to prove thermal cycling reliability before gaining design-in status at tier-one semiconductor packaging houses. Henkel AG & Co. KGaA leverages its captive epoxy resin formulation capabilities to anchor high-volume supply contracts with leading OSATs in Asia. H.B. Fuller Company competes through specialized low-alpha particle underfill grades tailored for memory stack applications where single-event upset tolerance is critical. NAMICS Corporation dominates niche ceramic-filled formulations for automotive power modules operating above 150°C junction temperatures.
Underfill denotes a liquid encapsulant dispensed beneath flip-chip die to mitigate solder bump fatigue caused by coefficient of thermal expansion mismatch between silicon and organic substrates, typically formulated from silica-filled bisphenol or cycloaliphatic epoxy resins with anhydride or amine curing agents. Capillary underfill continues to occupy the largest process share in high-density interposer-based packaging where precise gap control below 50 microns is essential. No-flow underfill is accelerating fastest in system-in-package modules where simultaneous reflow and underfill cure eliminates a dedicated dispense station, compressing assembly cycle time. Epoxy underfill technology leads margin pools due to proprietary catalyst packages that extend pot life without sacrificing cure speed at 165°C.
EPA TSCA Section 5 premanufacture notification requirements govern new epoxy resin introductions in the United States, while REACH Annex XIV authorization lists constrain bisphenol-A derivative use in European electronics supply chains. Japan's METI chemical substance evaluation framework adds a third compliance layer for suppliers serving Panasonic Holdings Corporation and other domestic assemblers. Semiconductor manufacturers must monitor evolving halogen-free mandates from IEC 61249-2-21 and align formulation roadmaps with substrate thinning trends that amplify stress on underfill interfaces.
Market Dynamics
Advanced packaging architectures are compressing bump pitches below 40 microns, forcing underfill suppliers to reformulate for sub-30 micron gap penetration without void entrapment.
Growth Catalysts
- 3D Chiplet Architectures:Stacked memory and logic dies in high-bandwidth modules multiply underfill volume per wafer, with South Korean fabs driving specification tightening.
- EPA TSCA Section 5:New chemical notification pathways for epoxy catalysts are accelerating compliant resin introductions in US semiconductor packaging supply chains.
- Automotive Power Modules:Junction temperatures above 150°C in silicon carbide inverters are pulling ceramic-filled formulations into electric vehicle traction inverter assembly.
Market Restraints
- High-Purity Silica Concentration:Synthetic fused silica feedstock for low-alpha particle grades concentrates among Japanese and German specialty chemical suppliers.
- REACH Annex XIV Authorization:Bisphenol-A derivative restrictions are forcing reformulation cycles that extend qualification timelines by 18-24 months for European-bound products.
- Cure Shrinkage Limitations:Epoxy-anhydride systems exhibit 2-4% volumetric shrinkage that stresses ultra-thin substrate interfaces below 100 microns.
Strategic Opportunities
- India Semiconductor Mission:Domestic OSAT buildout under PLI incentives creates first-mover positioning for underfill suppliers establishing local blending operations.
- Photonics Packaging:Co-packaged optics in AI accelerators require optically transparent underfill with matched refractive index, an unserved specification niche.
- Halogen-Free Mandates:IEC 61249-2-21 compliance requirements in consumer electronics are creating premium positioning for bromine-free epoxy formulations.
Industry Challenges
- JEDEC J-STD-020 Qualification:Moisture sensitivity level testing for MSL 1/260°C compatibility demands 1000+ hour thermal cycling validation that strains R&D throughput.
- Process Engineer Scarcity:Capillary flow modeling expertise for heterogeneous integration packaging is concentrating among senior technologists at Taiwanese and South Korean OSATs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underfill Market |
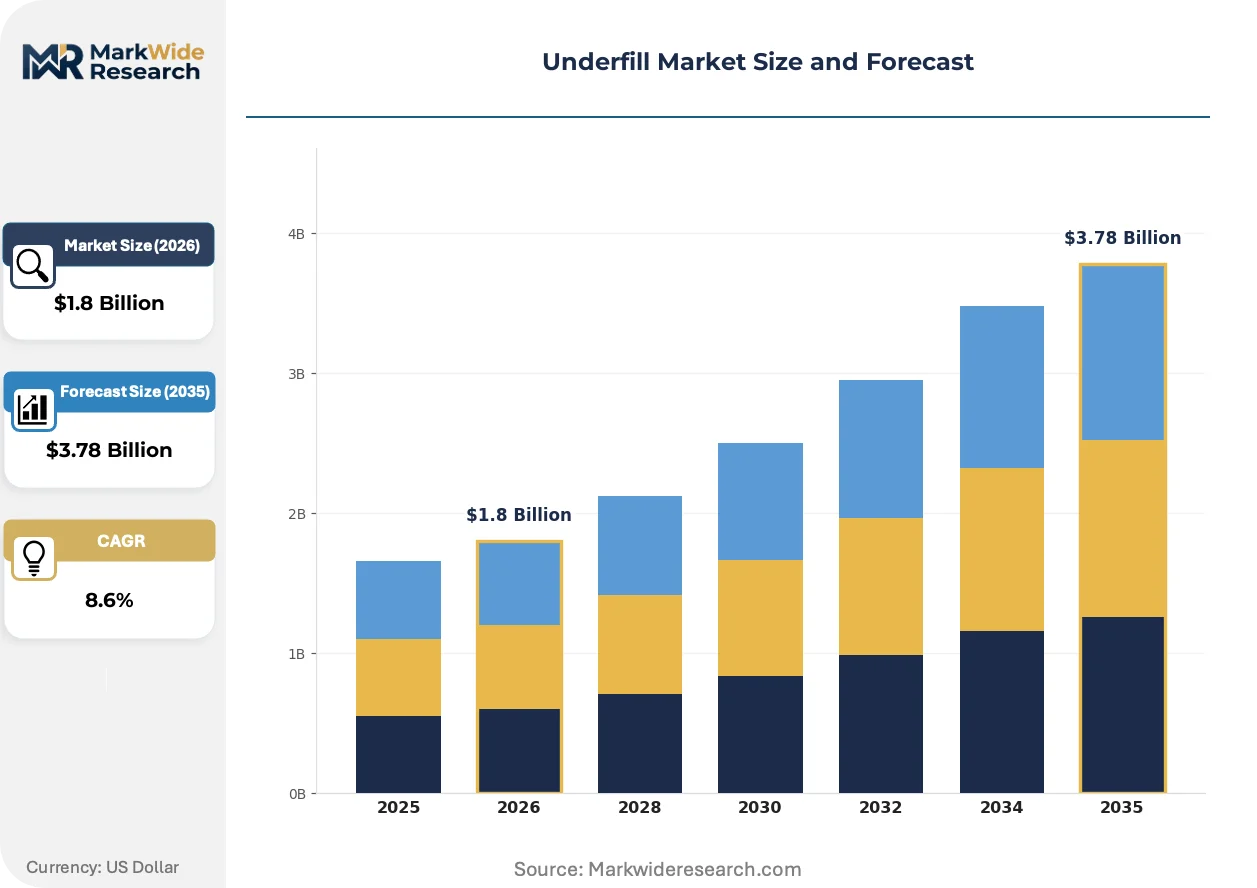
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Underfill, Non-Capillary Underfill, Advanced Underfill, Heat-Curable Underfill End User: Semiconductor Manufacturers, Electronics Assemblers, Automotive Suppliers, Consumer Electronics Technology: Liquid Underfill, Epoxy Underfill, No-Flow Underfill, Thermosetting Underfill Application: Electronics Packaging, LED Packaging, Power Modules, Microelectronics |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Nordson Corporation, Master Bond Inc., NAMICS Corporation, Panasonic Holdings Corporation, LORD Corporation, Won Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underfill Market Strategic Shifts
Materials innovation is pivoting from gap-fill optimization toward multifunctional integration, where underfill simultaneously manages thermal, mechanical, and electrical interface requirements.
Non-conductive film underfill is supplanting traditional capillary dispense in panel-level fan-out packaging, where Samsung Electro-Mechanics and ASE Group are qualifying dry-film lamination for 600mm x 600mm reconstituted wafer formats. This shift compresses material usage by eliminating edge bead formation and enabling 5-micron thickness control.
REACH authorization lists are tightening bisphenol-A derivative thresholds in European electronics supply chains, compelling Henkel and NAMICS to accelerate cycloaliphatic epoxy platform development. Automotive module suppliers serving Stuttgart and Munich clusters are now mandating full material disclosure to 0.1% weight thresholds.
Consolidated procurement at tier-one OSATs is compressing supplier bases from six qualified sources to two strategic partners per technology node. Memory packaging houses in Yongin and Taichung are unbundling material supply from equipment service contracts, forcing underfill vendors to compete on standalone formulation performance rather than integrated dispense system lock-in.
Underfill Market Segmentation
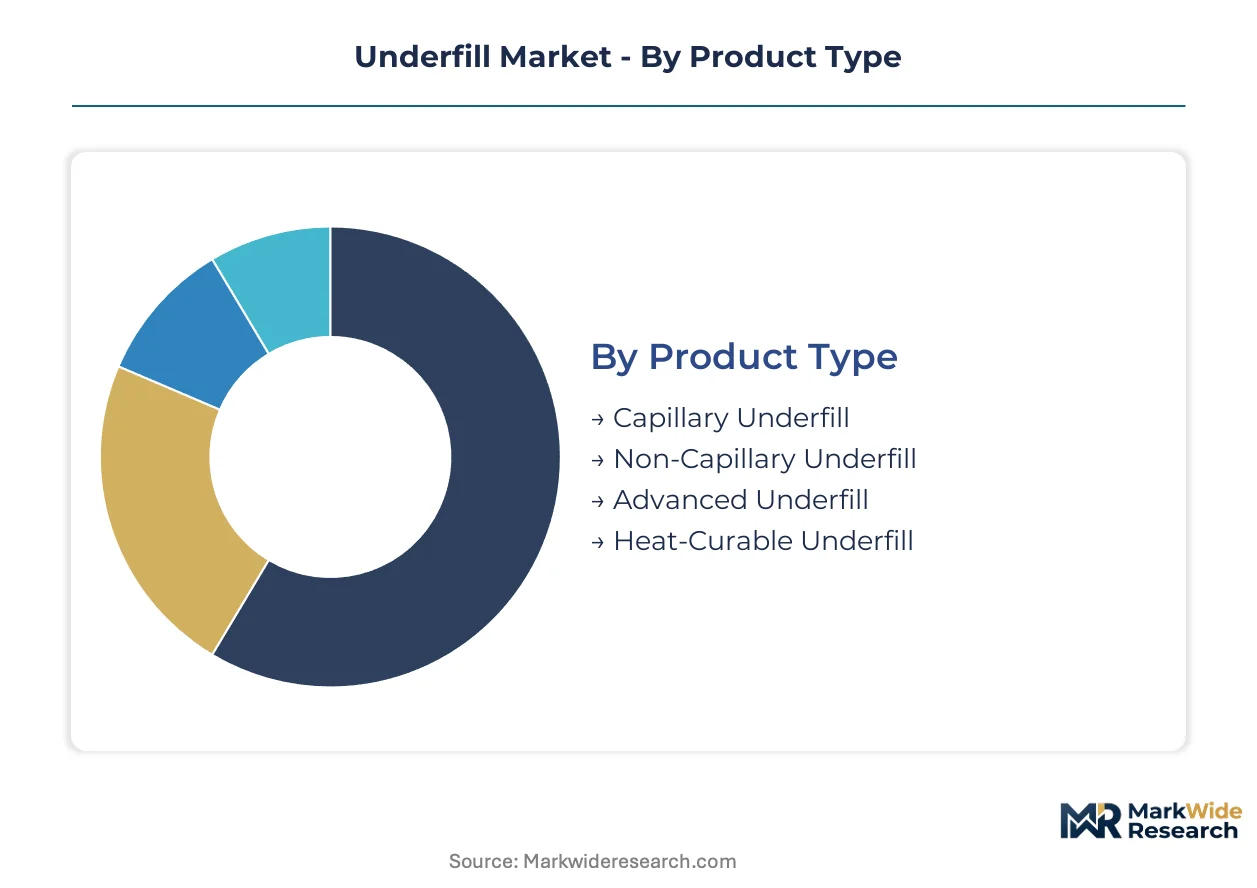
Underfill procurement patterns diver sharply across product architectures, with capillary formulations dominating high-density interposer packaging while no-flow chemistries capture system-in-package modules. Semiconductor manufacturers in South Korea and Taiwan drive specification tightening as bump pitches compress below 40 microns.
Product Type:
Channel distribution splits between direct supply to OSATs for high-volume capillary grades and specialty distributors for niche thermal-curable variants serving automotive module houses.
- Capillary Underfill:Silica-filled bisphenol epoxy formulations engineered for sub-50 micron gap penetration in flip-chip interconnects. Samsung and SK Hynix fabs in Yongin specify these grades for 3D chiplet architectures where void-free underfill is non-negotiable.
- No-Flow Underfill:Simultaneous reflow-and-cure chemistry eliminates dedicated dispense stations, compressing assembly cycle time in system-in-package modules. ASE Group in Taichung is accelerating qualification for heterogeneous integration packaging.
- Non-Capillary Underfill:Includes molded and wafer-level underfill formats for panel-level fan-out applications.
- Advanced Underfill:Ceramic-filled formulations for junction temperatures exceeding 150°C in silicon carbide power modules.
- Heat-Curable Underfill:Anhydride-cured systems with extended pot life for automotive suppliers requiring 165°C cure windows.
Capillary underfill dominates installed base. Advanced underfill is where expansion concentrates.
End User:
Cost tier stratification separates premium-qualified semiconductor manufacturers from price-sensitive consumer electronics assemblers sourcing through distributors.
- Semiconductor Manufacturers:Tier-one OSATs and IDMs in South Korea, Taiwan, and the United States consolidate procurement to two strategic partners per technology node. JEDEC J-STD-020 moisture sensitivity qualification gates design-in status.
- Automotive Suppliers:Stuttgart and Munich clusters mandate full material disclosure to 0.1% weight thresholds under REACH authorization pressure. Ceramic-filled grades from NAMICS dominate traction inverter assembly for electric vehicles.
- Electronics Assemblers:Mid-tier contract manufacturers serving industrial and communications equipment.
- Consumer Electronics:Halogen-free mandates per IEC 61249-2-21 drive bromine-free epoxy sourcing for smartphones and wearables.
Semiconductor manufacturers anchor volume demand. Automotive suppliers represent the steepest expansion trajectory as silicon carbide inverters proliferate.
Technology:
Margin concentration pools in proprietary catalyst packages that extend pot life without sacrificing cure speed, differentiating epoxy platforms from commodity liquid formulations.
- Epoxy Underfill:Cycloaliphatic and bisphenol resin platforms with anhydride or amine curing agents. Henkel leverages captive epoxy resin formulation capabilities to anchor high-volume supply contracts with leading OSATs.
- No-Flow Underfill:Flux-integrated chemistry enables simultaneous solder reflow and underfill cure. Memory packaging houses in Yongin unbundle material supply from equipment service contracts.
- Liquid Underfill:Traditional dispensed formats for legacy flip-chip and ball grid array packages.
- Thermosetting Underfill:Cross-linked polymer networks for permanent mechanical protection in harsh environments.
Epoxy underfill commands premium positioning. No-flow underfill is gaining share fastest in time-compressed assembly flows.
Application:
Geography-driven demand splits between Asia-Pacific electronics packaging concentration and emerging European automotive power module buildout.
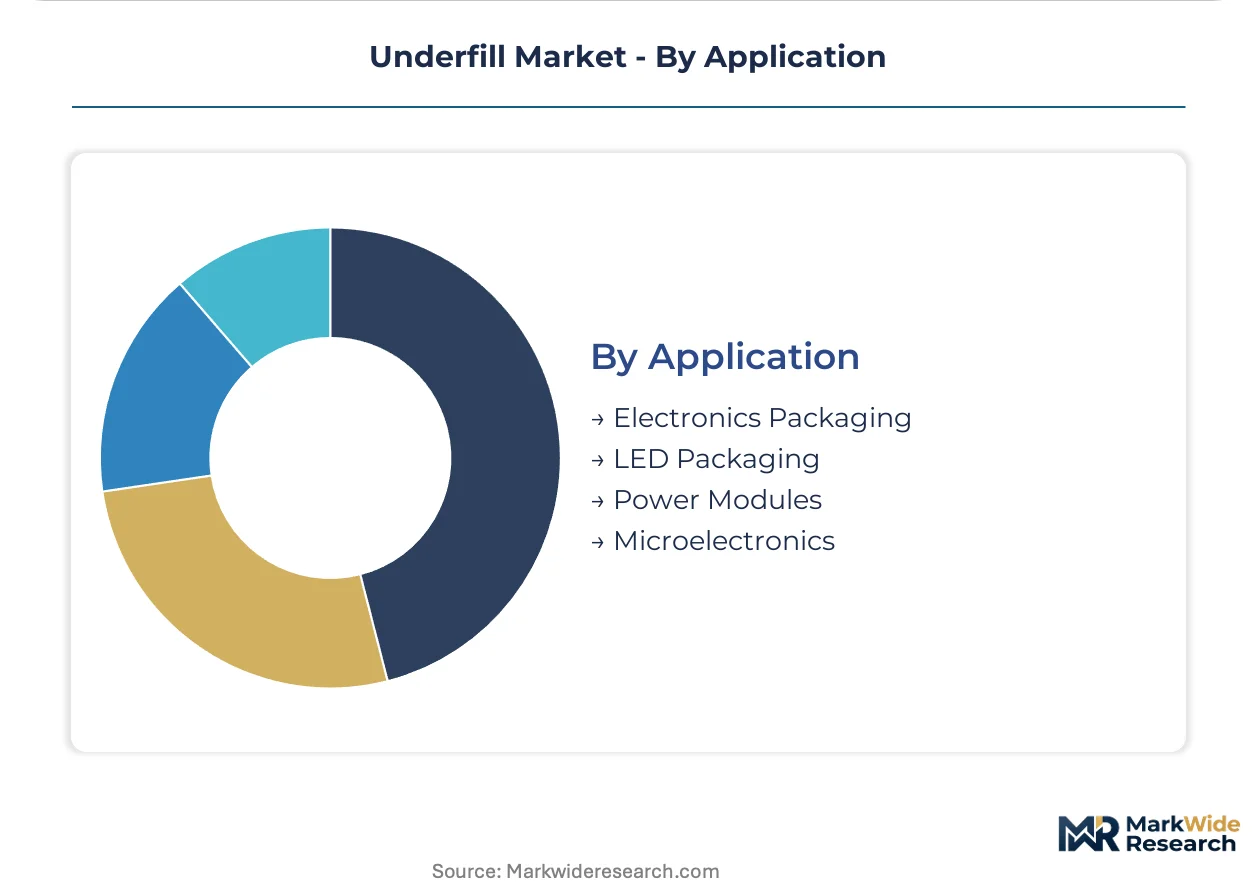
- Electronics Packaging:Flip-chip and 2.5D/3D interposer-based packaging where coefficient of thermal expansion mismatch drives underfill necessity. Samsung Electro-Mechanics qualifies non-conductive film underfill for 600mm x 600mm panel-level fan-out formats.
- Power Modules:Silicon carbide and IGBT packaging for electric vehicle traction inverters. Junction temperatures above 150°C pull ceramic-filled formulations from NAMICS into automotive qualification pipelines.
- LED Packaging:Chip-on-board and chip-scale package underfill for thermal management in solid-state lighting.
- Microelectronics:MEMS, sensors, and RF device packaging requiring precision gap control.
Electronics packaging holds installed base dominance. Power modules concentrate expansion as electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSAT procurement offices in South Korea and Taiwan concentrate the highest underfill specification authority, while automotive power module demand is pulling formulation development toward Germany and the United States.
South Korea
Samsung and SK Hynix fabs in Yongin are scaling 3D chiplet architectures that multiply underfill volume per wafer. The Korea MFDS chemical substance evaluation framework governs epoxy resin introductions for domestic electronics assemblers. Seoul Capital Area packaging houses are consolidating qualified suppliers to two strategic partners per technology node.
Taiwan
ASE Group in Taichung is accelerating no-flow underfill qualification for heterogeneous integration packaging. The Taiwan EPA toxic chemical substance control act constrains bisphenol-A derivative thresholds in electronics supply chains. Advanced packaging foundries in Hsinchu are compressing bump pitches below 40 microns, forcing sub-30 micron gap penetration requirements.
United States
EPA TSCA Section 5 premanufacture notification requirements govern new epoxy catalyst introductions for semiconductor packaging supply chains. The Inflation Reduction Act domestic content incentives are pulling automotive power module assembly toward Michigan and Ohio manufacturing clusters. Silicon carbide inverter suppliers in Detroit are mandating ceramic-filled formulations for junction temperatures above 150°C.
Germany
Stuttgart and Munich automotive clusters are mandating full material disclosure to 0.1% weight thresholds under ECHA REACH Annex XIV authorization pressure. The KBA type approval process for electric vehicle traction inverters is accelerating qualification of high-temperature underfill grades. Bavaria-based power module suppliers are unbundling material supply from equipment service contracts.
Japan
Panasonic Holdings Corporation and domestic assemblers are subject to METI chemical substance evaluation frameworks that add compliance layers beyond REACH. The Japan JIS standards for halogen-free electronics are constraining bromine-containing epoxy formulations. Kyushu-based OSATs are qualifying non-conductive film underfill for panel-level fan-out packaging formats.
Underfill Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive epoxy resin formulation capabilities. The supplier base concentrates around three tiers: multinational adhesive specialists with semiconductor packaging heritage, Japanese precision chemical manufacturers serving automotive power modules, and regional Korean formulators integrated with domestic OSAT supply chains. Strategic moves center on backward integration into synthetic fused silica feedstock and geographic expansion into India under PLI scheme incentives.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the premium-tier positioning anchored by proprietary catalyst packages. NAMICS Corporation occupies a specialist position within the Japanese precision chemical tier, representing the ceramic-filled formulation archetype for high-temperature automotive applications. These three companies illustrate the competitive structure: scale-driven resin formulation capabilities, application-specific thermal performance specialization, and regional integration with advanced packaging clusters.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Nordson Corporation |
| Master Bond Inc. |
| NAMICS Corporation |
| Panasonic Holdings Corporation |
| LORD Corporation |
| Won Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with Japanese synthetic fused silica suppliers lock in both feedstock access and price visibility for tier-one OSATs, insulating qualified underfill vendors from spot-market volatility while compressing margins for unqualified entrants.
Pricing Analysis
Cost-plus contracts with bisphenol-A epoxy indexation dominate procurement between Henkel and Korean packaging houses. Price differentiation separates JEDEC J-STD-020 qualified grades from unqualified alternatives, with volume scale and captive resin formulation as secondary tiering factors. Pricing pressure intensifies as memory packaging houses unbundle material supply from equipment service contracts. Consumer electronics assemblers exhibit highest price sensitivity; automotive power module suppliers show lowest sensitivity due to thermal performance mandates.
Supply Chain Analysis
Inbound logistics costs from Yokkaichi and Kobe ports to Yongin packaging clusters fluctuate with container availability on Asia-East Asia trade lanes. Synthetic fused silica feedstock concentrates in Japan and Germany; epoxy resin formulation anchors in South Korea and Taiwan. Supply chain risk centers on single-source vulnerability for low-alpha particle grades. Distribution runs through direct OSAT contracts for high-volume capillary grades and specialty distributors for automotive thermal-curable variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as semiconductor packaging capacity expansion resumes following the 2023 inventory correction, with AI accelerator demand as the named cyclical driver.
For Market Incumbents: Shield formulation margins by accelerating cycloaliphatic epoxy platform development ahead of REACH Annex XIV bisphenol-A restrictions. Deepen backward integration into synthetic fused silica feedstock to neutralize Japanese supplier concentration risk. Prioritize JEDEC qualification investment to maintain two-source status at consolidating OSATs.
For New Entrants and Emerging Players: JEDEC J-STD-020 certification fast-track through partnership with Taichung-based OSATs offers the most penetrable entry vector. Target India Semiconductor Mission PLI beneficiaries with local blending operations as white-space geography. Pursue photonics packaging applications for co-packaged optics as unserved specification niche.
For Investors and Strategic Acquirers: Ceramic-filled formulation specialists with automotive power module qualifications represent the priority acquisition archetype. Long-term viability hinges on thermal performance differentiation above 150°C junction temperatures. Watch silicon carbide inverter procurement acceleration at Detroit manufacturing clusters as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fused Silica | Captive feedstock supply neutralizes Japanese supplier concentration and secures low-alpha particle grade availability. |
| Cycloaliphatic Epoxy Platform Development | REACH Annex XIV compliance ahead of bisphenol-A restrictions defends European automotive module market access. |
| India Local Blending Operations | PLI scheme incentives under India Semiconductor Mission create first-mover positioning for domestic OSAT supply. |
| Non-Conductive Film Underfill Qualification | Panel-level fan-out adoption at Samsung Electro-Mechanics displaces traditional capillary dispense in advanced packaging. |
| JEDEC J-STD-020 Certification Investment | Moisture sensitivity qualification gates design-in status at consolidating tier-one packaging houses in Yongin and Taichung. |
Study Parameters
Cross-validation between primary interviews with OSAT procurement directors, epoxy resin formulators, and automotive power module engineers and secondary validation through EPA TSCA filings, Korea MFDS chemical substance registrations, and SEMI industry reports anchors the qualitative findings. Bottom-up triangulation against top-down semiconductor packaging equipment shipment data ensures segment-level consistency.
Sensitivity analysis around silicon carbide inverter adoption rates and 3D chiplet architecture penetration shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, and application with regional production cluster overlays. CAGRs derive from installed base expansion and content-per-wafer multiplication in high-bandwidth memory modules.
Decision-makers should treat outputs as directional under assumptions of sustained advanced packaging capital expenditure and stable epoxy resin feedstock availability; material deviation in semiconductor cycle timing or REACH authorization scope would warrant model refresh. Recalibration cycles align with material shifts in JEDEC qualification standards and automotive power module thermal specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Middle East Distribution Panel Market