
 Asia-Pacific Semiconductor (Silicon) Intellectual Property Market | 2026-2036
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market Outlook
Japan's METI semiconductor revitalization subsidy framework is recalibrating how IP vendors allocate R&D resources across the region. Arm Holdings plc anchors its Asia-Pacific presence through architecture licensing partnerships with Chinese smartphone chipset designers. Synopsys Inc. leverages EDA-integrated IP portfolios to sustain competitive differentiation in Taiwan's foundry ecosystem. eMemory Technology Incorporated specializes in embedded non-volatile memory IP for automotive-grade silicon nodes.
Asia-Pacific semiconductor silicon intellectual property encompasses licensable circuit designs, processor architectures, and verification environments fabricated on silicon substrates ranging from mature 28nm to advanced 3nm process nodes. These reusable IP blocks enable fabless semiconductor companies and system houses to accelerate system-on-chip development while reducing non-recurring engineering costs. Processor IP commands the largest value share as Chinese and South Korean OEMs pursue custom CPU and NPU designs for edge AI workloads. Interface IP for DDR5 and PCIe Gen5 protocols represents the fastest-expanding category, driven by data center buildouts in Singapore and Japan. Analog and mixed-signal IP retains margin concentration in industrial automation applications requiring extended temperature operation and radiation tolerance.
China's MIIT mandates GB standards compliance for domestic semiconductor IP used in government procurement, restricting market access for non-certified foreign suppliers. South Korea's MFDS and KOSHA frameworks govern functional safety requirements for automotive IP deployed in autonomous driving systems. Taiwan's NCC and ITRI standards shape 5G baseband IP certification protocols for regional telecom infrastructure. Stakeholders must monitor how divergent national security review mechanisms for semiconductor technology transfers will reshape cross-border licensing terms and royalty structures.
Market Dynamics
China's MIIT GB standards certification mandate for government procurement semiconductor IP is fragmenting vendor access and forcing foreign suppliers into joint-venture localization structures. This regulatory bifurcation compounds Taiwan's foundry concentration leverage.
Growth Catalysts
- Automotive ADAS chipset proliferation:Chinese and South Korean OEMs are expanding silicon content per vehicle. Functional safety IP demand accelerates under MFDS and KOSHA frameworks governing autonomous driving systems.
- MIIT domestic procurement mandates:China's government semiconductor procurement rules require GB-certified IP blocks. This creates captive demand pools for locally certified architecture and interface IP suppliers.
- Edge AI NPU customization:Fabless design houses around Shanghai and Shenzhen pursue bespoke neural processing unit architectures. Processor IP licensing volumes concentrate in these clusters.
Market Restraints
- Foundry capacity allocation rigidity:Taiwan's TSMC and UMC control advanced node access. IP vendors face tape-out queue uncertainty that delays customer revenue recognition.
- MIIT certification timeline friction:Foreign IP suppliers endure 18-24 month GB standards approval cycles. This structural lag advantages pre-certified domestic competitors in government tenders.
- 28nm node commoditization:Mature process IP margins compress as Chinese foundries expand 28nm capacity. Analog and mixed-signal IP suppliers face pricing pressure in industrial automation segments.
Strategic Opportunities
- Thailand and Vietnam fabless emergence:Southeast Asian electronics manufacturing clusters are incubating design capabilities. Early IP licensing relationships can anchor regional market position before competitor saturation.
- METI subsidy-driven R&D localization:Japan's semiconductor revitalization framework funds domestic IP development. Foreign vendors can access matched funding through joint laboratories with Japanese IDMs.
- Chiplets and 2.5D integration convergence:Die-to-die interconnect IP demand is accelerating as China and South Korea pursue advanced packaging strategies. Interface IP vendors can capture value from disaggregated silicon architectures.
Industry Challenges
- Verification engineer scarcity:Formal verification and physical design expertise concentrates in Taiwan and specific Chinese cities. IP vendors face recruitment competition from foundries offering equity compensation.
- Cross-border licensing complexity:Divergent national security review mechanisms for semiconductor technology transfers are extending contract negotiation timelines. Royalty structures now incorporate compliance risk premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor (Silicon) Intellectual Property Market |
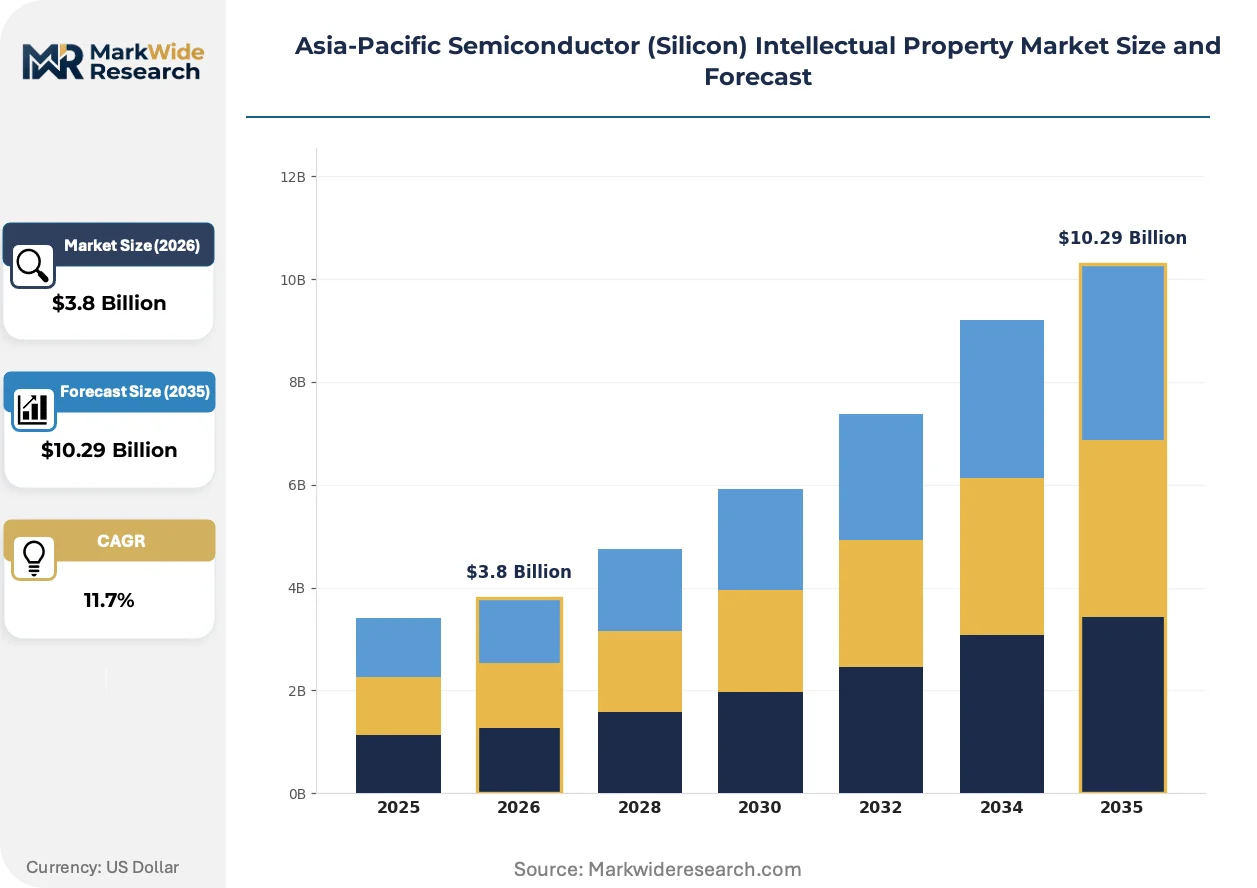
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design IP, Verification IP, Interface IP, Processor IP Technology: Analog, Digital, Mixed-Signal, RF Application: Consumer Electronics, Telecommunications, Automotive, Industrial Automation End User: OEMs, Startups, Research Institutions, Design Houses |
| Companies Covered | Imagination Technologies Group plc, eMemory Technology Incorporated, Arm Holdings plc, VeriSilicon Holdings Co. Ltd., Faraday Technology Corp., Synopsys Inc., CEVA Inc., M31 Technology Corporation, Cadence Design Systems Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market Strategic Shifts
Physical design automation and formal verification tools are compressing IP development cycles. Taiwan's foundry ecosystem and China's fabless clusters are adopting these capabilities at differential rates.
Machine learning-based place-and-route optimization is automating floorplan generation for complex SoC designs. Chinese smartphone chipset designers are deploying these tools aggressively to compress tape-out schedules. The technology is automating previously manual physical design tasks that consumed 40% of project timelines.
Japan's METI semiconductor revitalization subsidy framework is redirecting R&D investment toward domestic IP development. Japanese IDMs are expanding in-house architecture teams rather than licensing foreign cores. Automotive-grade silicon IP for 5nm and 3nm nodes receives priority funding allocation under this structure.
Chinese fabless houses are consolidating procurement around vertically integrated IP-EDA bundles. Synopsys and Cadence licensing models are displacing point-tool procurement that dominated prior procurement cycles. This concentration is most visible in Shenzhen's consumer electronics design cluster, where turnkey IP platforms accelerate time-to-revenue.
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market Segmentation
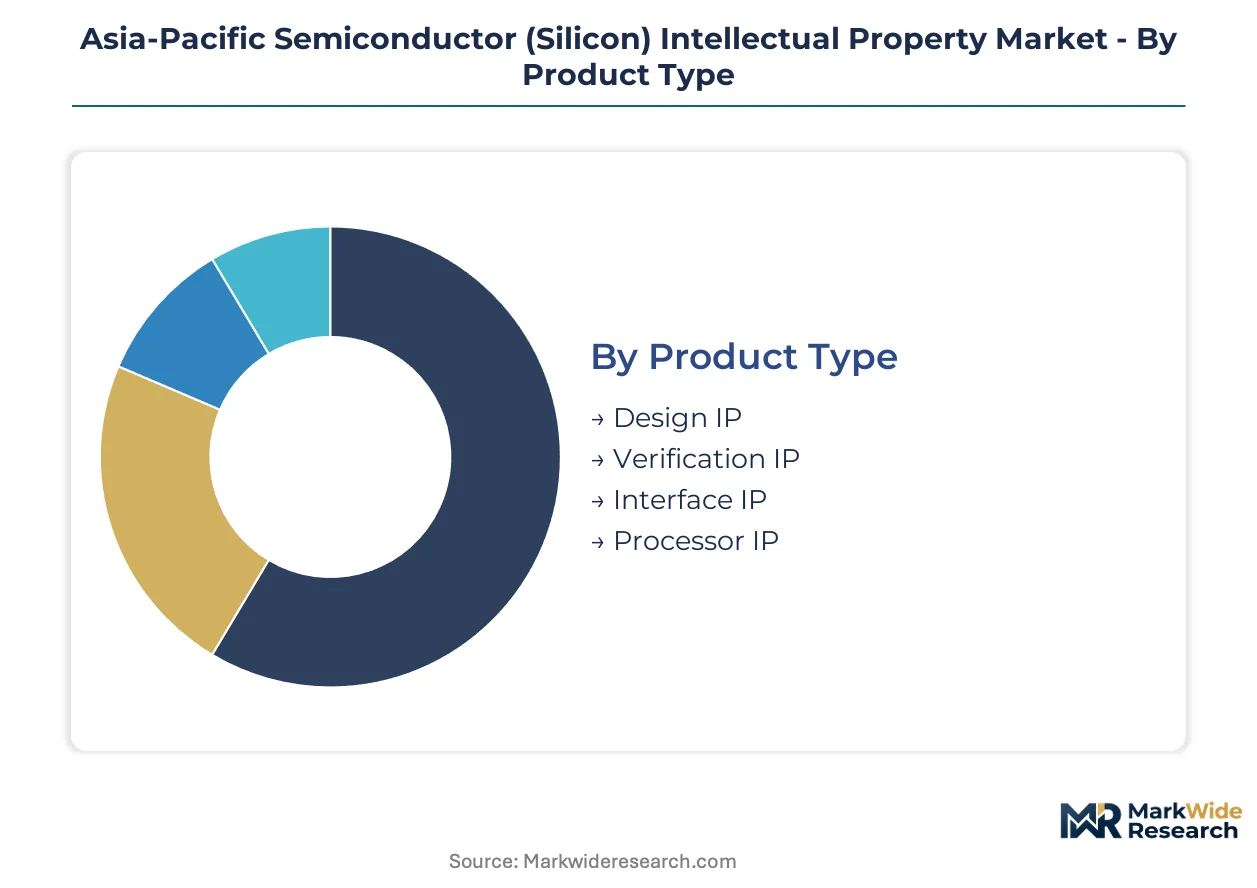
Segmentation in Asia-Pacific semiconductor IP reveals how customization depth varies across product architectures, process technologies, and end-use requirements. IP vendors calibrate licensing models against these dimensions to capture value from Taiwan's foundry concentration and China's fabless design clusters.
Product Type:
Standardization dominates at the architecture level while customization intensifies at the implementation layer across this category.
- Processor IP:CPU, GPU, and NPU core architectures licensable for modification. Chinese fabless houses around Shanghai and Shenzhen pursue bespoke neural processing unit designs for edge AI workloads, concentrating licensing volumes in these clusters.
- Interface IP:DDR5, PCIe Gen5, and die-to-die interconnect controllers. Demand concentrates in Singapore and Japanese data center buildouts, with protocol compliance requirements accelerating under divergent national certification timelines.
- Design IP:Reusable logic blocks and subsystem designs for SoC integration.
- Verification IP:Protocol checkers, assertion libraries, and simulation environments for pre-silicon validation.
Leading the category by volume: Processor IP. Expanding most quickly: Interface IP.
Technology:
Process node maturity creates divergent margin structures across analog precision, digital density, and signal integration challenges.
- Digital:Logic gates, memory arrays, and programmable fabrics implemented in CMOS. Taiwan's TSMC and Samsung Foundry anchor advanced node tape-outs at 5nm and 3nm, with Chinese fabless houses consuming capacity for smartphone chipset production.
- Mixed-Signal:Data converters, PLLs, and power management circuits combining analog and digital domains. Automotive-grade implementations for South Korean and Chinese OEMs face functional safety certification under MFDS and KOSHA frameworks.
- Analog:Amplifiers, references, and sensor interfaces requiring precise transistor matching.
- RF:Transceivers, modulators, and antenna tuning circuits for wireless protocols.
Highest margin concentration: Mixed-Signal. Steepest volume climb: Digital.
Application:
Safety-critical requirements fragment certification pathways while consumer volumes drive standardization economies.
- Automotive:ADAS chipsets, powertrain controllers, and infotainment SoCs requiring ISO 26262 functional safety compliance. Chinese and South Korean OEMs expand silicon content per vehicle, with IP vendors integrating MFDS and KOSHA certification into licensing packages.
- Telecommunications:5G baseband processors, network infrastructure accelerators, and optical transport silicon. Taiwan's NCC and ITRI standards shape certification protocols for regional telecom buildouts.
- Consumer Electronics:Smartphone application processors, wearable SoCs, and smart home controllers.
- Industrial Automation:Motor drives, programmable logic controllers, and robotics chipsets requiring extended temperature operation.
Dominant revenue share: Consumer Electronics. Gaining share fastest: Automotive.
End User:
Procurement scale and technical sophistication determine licensing terms, royalty structures, and support service bundling.
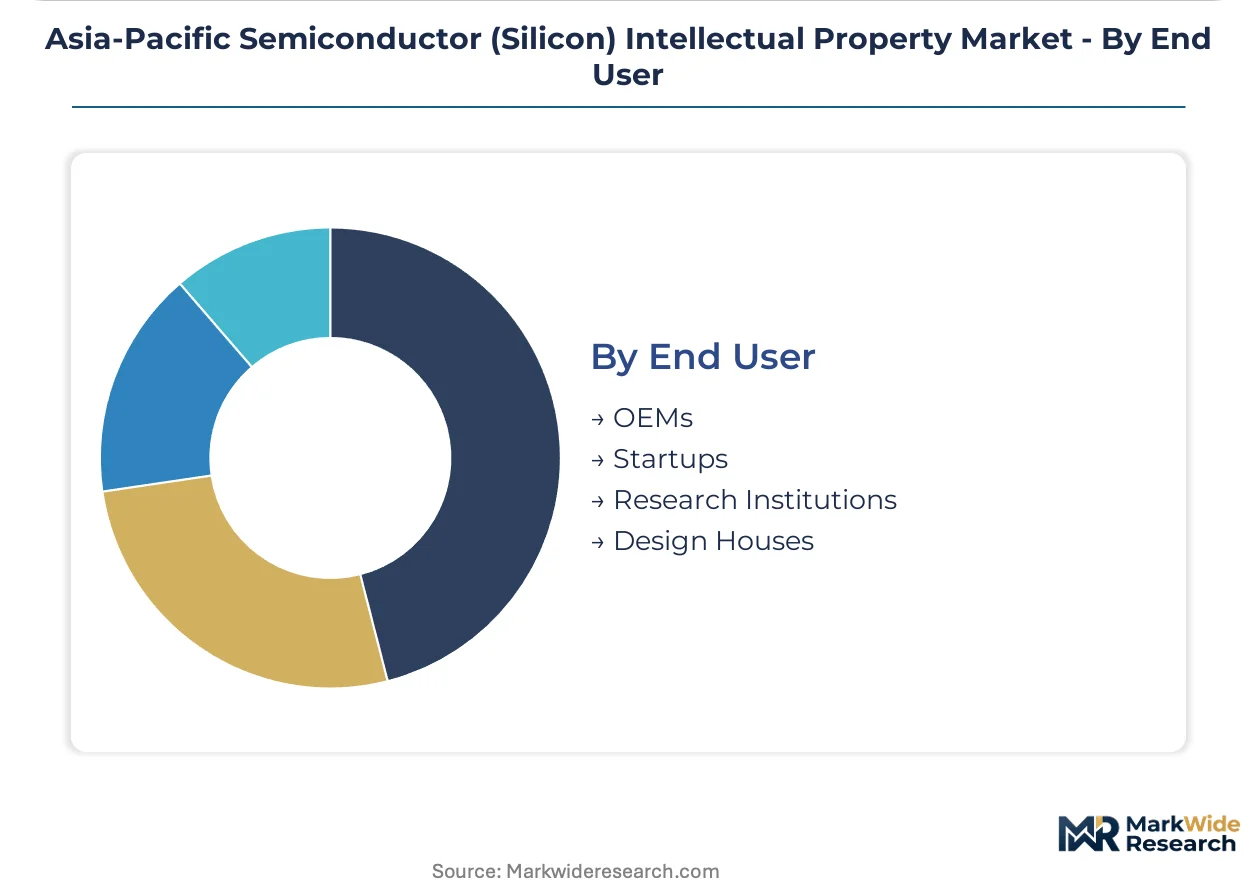
- Design Houses:Fabless semiconductor companies aggregating IP into commercial SoC products. China's MIIT GB standards certification mandate creates captive demand pools for locally certified suppliers in government procurement channels.
- OEMs:Vertically integrated electronics manufacturers developing captive silicon. Japanese automotive OEMs leverage METI subsidy frameworks to expand in-house architecture teams rather than license foreign cores.
- Startups:Early-stage companies licensing IP for initial tape-outs and proof-of-concept silicon.
- Research Institutions:Universities and national laboratories developing experimental architectures and educational implementations.
Primary volume driver: Design Houses. Fastest contract velocity: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Taiwan's foundry ecosystem while consumption fragments across China's fabless clusters, South Korea's automotive OEMs, and Japan's IDM revival. This mismatch shapes cross-border licensing terms and royalty structures throughout the region.
China
MIIT's GB standards certification mandate creates captive demand pools for locally certified architecture and interface IP suppliers. Foreign vendors endure 18-24 month approval cycles, advantaging pre-certified domestic competitors in government procurement channels. Shanghai and Shenzhen's fabless design houses concentrate processor IP licensing volumes for bespoke NPU development.
Taiwan
TSMC and UMC control advanced node access, creating tape-out queue uncertainty that delays customer revenue recognition for IP vendors. Foundry dominance reshapes how vendors allocate R&D resources across the region. Hsinchu Science Park anchors the ecosystem where EDA-integrated IP portfolios sustain competitive differentiation.
South Korea
Automotive OEMs expand silicon content per vehicle, accelerating functional safety IP demand under MFDS and KOSHA frameworks governing autonomous driving systems. Samsung Foundry anchors advanced node tape-outs alongside domestic consumption of DDR5 and PCIe Gen5 interface IP. Seoul's design clusters concentrate ADAS chipset development.
Japan
METI's semiconductor revitalization subsidy framework redirects R&D investment toward domestic IP development, with automotive-grade silicon for 5nm and 3nm nodes receiving priority funding. Japanese IDMs expand in-house architecture teams rather than licensing foreign cores. Tokyo and Nagoya anchor automotive-grade mixed-signal IP concentration.
Singapore
Data center buildouts accelerate demand for DDR5 and PCIe Gen5 protocol interface IP, with protocol compliance requirements tightening under divergent national certification timelines. The city-state's position as a regional telecom infrastructure hub shapes 5G baseband IP certification protocols. Design capabilities incubate within Southeast Asian electronics manufacturing clusters.
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market Competitive Environment
The competitive structure tilts toward architecture licensors with foundry-integrated verification environments. A concentrated tier of processor IP specialists anchors high-value licensing relationships, while interface and memory IP vendors fragment across protocol-specific niches. Two strategic archetypes dominate: EDA-integrated platform providers and specialized embedded memory architects. Competitive moves concentrate on joint-venture localization structures and R&D laboratory partnerships with subsidized domestic IDMs.
Within the architecture licensing tier, Arm Holdings plc and Imagination Technologies Group plc occupy positions as processor core originators for smartphone and automotive chipset designers. Synopsys Inc. exemplifies the EDA-integrated platform archetype, leveraging verification tool penetration to bundle IP portfolios. eMemory Technology Incorporated anchors the embedded non-volatile memory specialization, representing how niche IP vendors capture automotive-grade silicon node value.
| Leading Market Players |
|---|
| Imagination Technologies Group plc |
| eMemory Technology Incorporated |
| Arm Holdings plc |
| VeriSilicon Holdings Co. Ltd. |
| Faraday Technology Corp. |
| Synopsys Inc. |
| CEVA Inc. |
| M31 Technology Corporation |
| Cadence Design Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed foundry operators in Taiwan and subsidy-dependent Japanese IDMs anchor supply-side pricing discipline, while private-equity-rolled-up EDA platform vendors compress IP licensing margins through bundled procurement. This ownership-financing split concentrates advanced-node pricing power in Hsinchu Science Park while fragmenting mature-node IP value capture across China's fabless clusters.
Pricing Analysis
Margin tightening in processor IP reflects foundry tape-out queue premiums that vendors absorb to secure TSMC capacity allocations. Licensing models stratify across architecture royalties, per-use verification fees, and EDA-integrated subscription tiers. Price differentiation centers on ISO 26262 automotive certification grade and customization depth for edge AI workloads. Cost-down pressure on interface IP accelerates as Chinese foundries expand 28nm capacity and commoditize DDR5 controller margins. Design houses in Shenzhen exhibit highest price sensitivity, while Japanese automotive OEMs prioritize functional safety certification over unit cost.
Supply Chain Analysis
Direct-to-foundry licensing channels handle advanced-node IP demand from Shanghai and Shenzhen design clusters, while distributor-mediated routes serve Southeast Asian emerging fabless players. Supply concentrates in Taiwan, South Korea, and Japan, with TSMC and Samsung Foundry controlling 5nm and 3nm tape-out access. Raw material dependencies span EUV photoresist, high-purity silicon wafers, and specialized EDA compute infrastructure. Single-source vulnerability in advanced lithography equipment creates supply chain risk that extends IP development timelines. Distribution runs through foundry-integrated design service partnerships and EDA platform bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over verification engineer talent and foundry tape-out priority determines pricing power. Players are pursuing backward integration into formal verification automation and physical design services.
For Market Incumbents: Hedge against Chinese fabless consolidation by deepening EDA-integrated IP platform penetration in Thailand and Vietnam design clusters. Acquire specialized embedded memory IP architects to defend automotive-grade silicon node positions as Japanese IDMs expand in-house capabilities. Prioritize MIIT GB standards certification investment to maintain government procurement channel access despite 18-24 month approval friction.
For New Entrants and Emerging Players: Launch via die-to-die interconnect IP specialization targeting China's advanced packaging strategies and South Korean chiplet initiatives. Target automotive functional safety IP white space under MFDS and KOSHA frameworks where certification barriers slow incumbent response. Penetrate through joint-venture localization structures with METI-subsidized Japanese laboratories to access matched R&D funding.
For Investors and Strategic Acquirers: Distressed-cycle entries favor verification-automation specialists with foundry-integrated tool penetration in Taiwan's Hsinchu ecosystem. Long-term viability hinges on architectural licensing relationships that survive national security review fragmentation across the region. Monitor MIIT certification timeline compression as inflection indicator for foreign vendor competitive positioning recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint-Venture Localization Structure | MIIT GB standards compliance enables government procurement channel access for foreign IP vendors. |
| Foundry-Integrated Verification Platform | TSMC design service partnerships compress customer tape-out schedules and anchor recurring revenue. |
| Automotive Safety Certification Investment | ISO 26262 and KOSHA compliance differentiates IP offerings for South Korean ADAS chipset demand. |
| Die-to-Die Interconnect IP Development | Advanced packaging strategies in China and South Korea create protocol controller licensing opportunities. |
| Southeast Asian Design House Relationship | Thailand and Vietnam fabless emergence allows early market position before competitor saturation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with IP licensing executives, foundry design service managers, fabless procurement leads, and automotive semiconductor architects. SEC 10-K disclosures, MIIT certification registries, and Taiwan NCC equipment authorization databases provided demand-side validation. Bottom-up license transaction modeling and top-down foundry capacity allocation analysis were triangulated against METI subsidy disbursement records.
Data-stream reconciliation across the projection horizon employed segmentation by processor architecture, interface protocol, process node maturity, and end-use certification requirement. CAGRs were derived from license volume trajectories and royalty rate assumptions indexed to foundry wafer start forecasts. Automotive silicon content per vehicle, edge AI NPU customization intensity, and data center interface IP procurement cycles served as industry-specific forecast inputs.
Regulatory timeline slippage, foundry capacity reallocation, and national security review expansion are the dominant revision risks to base-case assumptions. Forecasts reflect documented assumptions regarding MIIT certification throughput, TSMC node transition pacing, and METI subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Silicon-Based Anode Market