
 Field-Effect Rectifier Diodes Market | 2026-2036
Field-Effect Rectifier Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
Field-Effect Rectifier Diodes Market Foresight
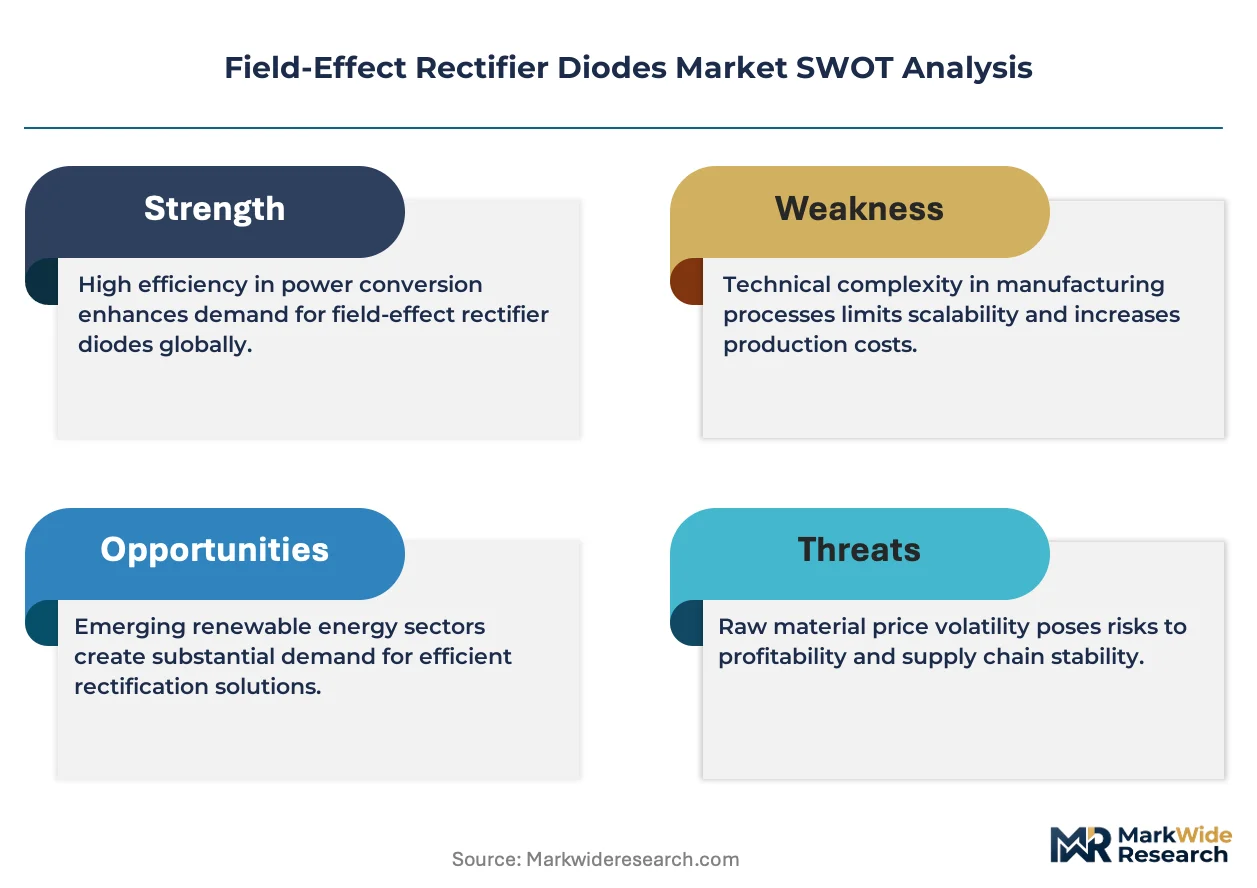
A chronic deficit of power semiconductor process engineers is unwinding foundry expansion plans across Asia-Pacific and Europe. STMicroelectronics leverages captive silicon carbide substrate growth to sustain vertical integration in automotive-grade rectifiers. Infineon Technologies anchors European supply security through its Dresden manufacturing complex. Vishay Intertechnology competes on discrete component breadth across industrial and consumer tiers.
Field-effect rectifier diodes are unipolar semiconductor devices that conduct current via majority-carrier injection, with Schottky variants achieving forward voltage drops below 0.45V and switching speeds exceeding 100kHz for high-frequency power conversion. Their primary purpose centers on minimizing conduction losses in switch-mode power supplies, solar inverters, and onboard EV chargers. Silicon-based junction diodes still occupy the highest volume tier in consumer power adapters, though silicon carbide MOSFETs represent the fastest-growing margin pool in electric vehicle traction inverters. Gallium nitride Schottky diodes differentiate premium segments where thermal density and switching frequency thresholds exceed silicon limits.
EU REACH substance restrictions and RoHS hazardous material directives constrain lead-frame plating chemistries and packaging materials across European supply chains. China's GB standards and MIIT energy-efficiency mandates enforce minimum conversion efficiency thresholds in power supply units sold domestically. The US EPA and FCC impose electromagnetic compatibility and standby power limits on imported rectifier-containing equipment. Stakeholders must monitor substrate material qualification timelines and regional carbon-border adjustment mechanisms to anticipate cost structure shifts.
Market Dynamics
Automotive electrification mandates are compressing qualification timelines for silicon carbide and gallium nitride rectifiers, forcing foundries to prioritize process engineering talent over capital equipment deployment.
Growth Catalysts
- EU Green Deal emission mandates:Binding CO2 reduction targets for passenger vehicles are mandating silicon carbide traction inverters, creating captive demand for high-voltage field-effect rectifiers in onboard chargers and DC-DC converters.
- China's EV manufacturing corridor:Shanghai, Shenzhen, and Xi'an cluster over sixty percent of domestic electric vehicle assembly capacity, concentrating procurement volumes for automotive-grade Schottky diodes.
- Gallium nitride epitaxy advances:Improved heterostructure fabrication is extending Schottky diode operating frequencies beyond silicon limits, unlocking server power supply and telecommunications rectifier applications.
Market Restraints
- Silicon carbide substrate cost volatility:Six-inch wafer supply shortages are inflating input costs for automotive-grade rectifiers, compressing margins for second-tier module assemblers.
- Foundry concentration in Taiwan:Advanced power semiconductor fabrication capacity clusters with TSMC and UMC, exposing supply security to geopolitical friction and export control risk.
- Junction diode substitution in consumer tiers:Silicon-based alternatives retain cost advantage in sub-100W power adapters, limiting addressable market expansion for premium Schottky variants.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives for compound semiconductor fabs are attracting substrate and epitaxy investments, creating localized rectifier manufacturing capacity.
- Grid-scale solar inverter deployment:Utility photovoltaic installations require high-reliability rectification at 1500V DC bus voltages, opening qualification pathways for silicon carbide Schottky devices.
- GaN-on-silicon convergence:Integrating gallium nitride epitaxy with standard silicon foundry processes is reducing capital intensity for high-frequency rectifier production.
Industry Challenges
- Power semiconductor process engineer scarcity:Foundry expansion timelines are unwinding across Asia-Pacific and Europe as talent pipelines fail to match capacity addition schedules.
- AEC-Q101 qualification duration:Automotive reliability testing for discrete semiconductors extends eighteen to twenty-four months, delaying revenue recognition for new rectifier designs.
- Legacy silicon supply chain reconfiguration:Existing junction diode manufacturing footprints require retooling for wide-bandgap materials, stranding depreciated equipment and retraining production workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field-Effect Rectifier Diodes Market |
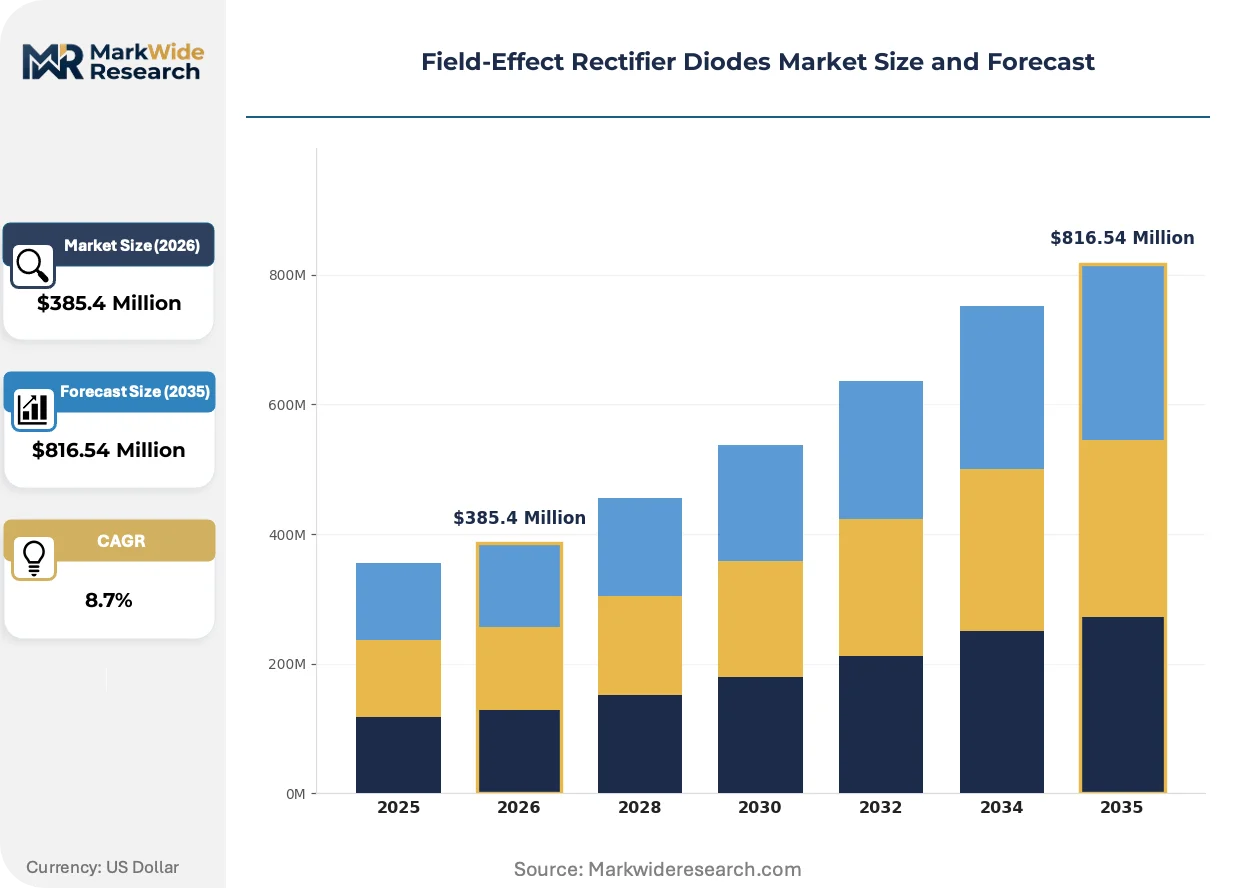
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schottky Diodes, Junction Diodes, MOSFETs, Others End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: Silicon, Gallium Nitride, Silicon Carbide, Bipolar Technology Application: Power Supply Units, Solar Inverters, LED Drivers, Electric Vehicles |
| Companies Covered | STMicroelectronics, NXP Semiconductors, Diodes Incorporated, ON Semiconductor, Infineon Technologies, Vishay Intertechnology, TE Connectivity, Electronic Devices, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field-Effect Rectifier Diodes Market Shifts & Advancements
Wide-bandgap semiconductor migration is redefining performance benchmarks across power conversion applications, compressing the viable window for conventional silicon rectification.
Silicon carbide Schottky barrier diodes eliminate reverse recovery charge in high-voltage switching circuits. Electric vehicle traction inverter manufacturers are adopting these devices at accelerated qualification paces. This technology is displacing ultrafast silicon junction diodes in 800V automotive architectures, collapsing switching loss budgets and enabling higher power density packaging.
REACH substance restrictions are constraining lead-frame plating chemistries and molding compound formulations across European supply chains. Power module assemblers must reformulate packaging materials to maintain CE marking compliance. Automotive-grade rectifier suppliers serving Stuttgart and Munich manufacturing clusters are absorbing qualification costs for halogen-free encapsulants.
Direct procurement from foundries is consolidating purchasing authority among tier-one automotive module manufacturers. Distributor inventory buffers are thinning as original equipment manufacturers negotiate long-term supply agreements for silicon carbide substrates. This pattern concentrates most visibly in Germany's automotive supply chain, where Volkswagen, BMW, and Mercedes-Benz have established captive rectifier sourcing teams.
Field-Effect Rectifier Diodes Market Segmentation
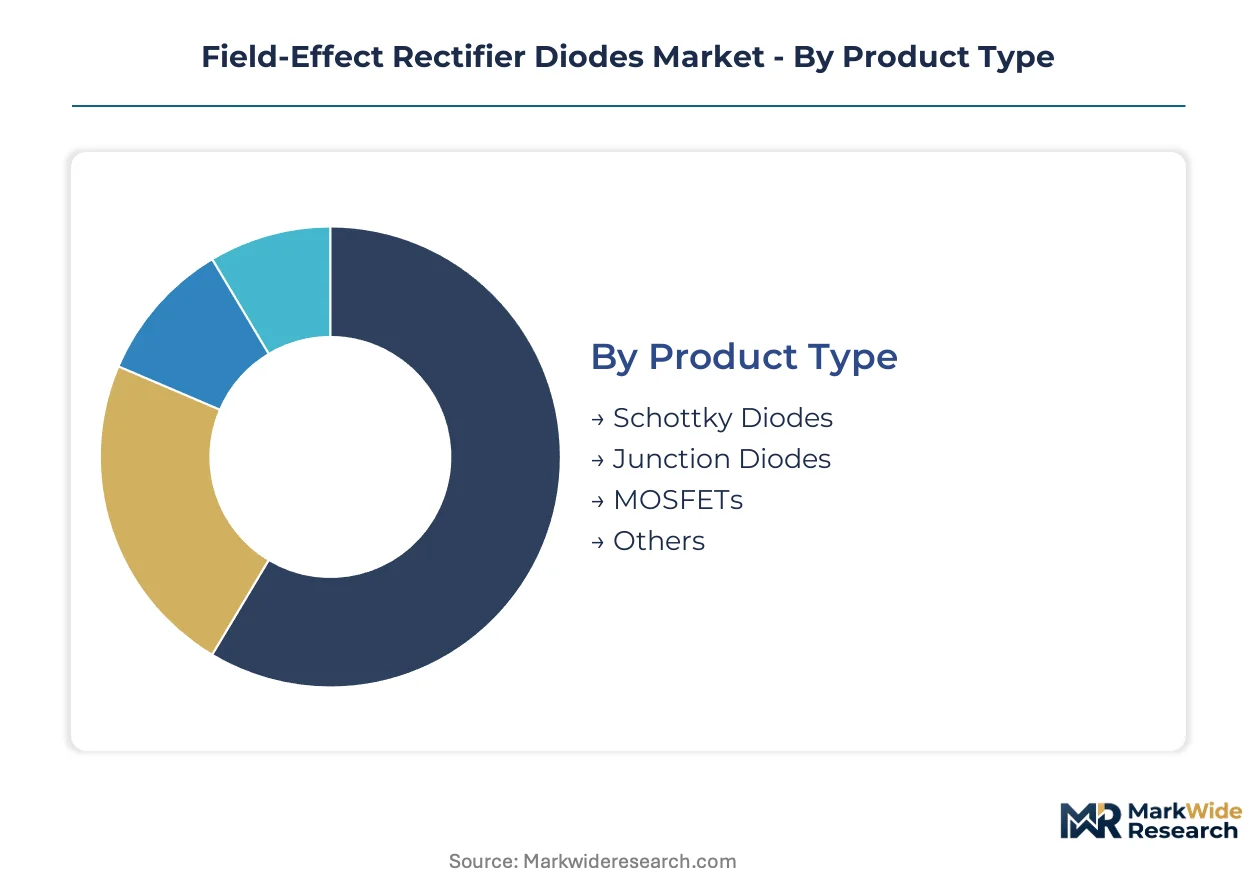
Field-effect rectifier diodes serve distinct performance tiers across power conversion applications. Segment boundaries reflect material physics limits, voltage handling requirements, and thermal density thresholds that channel procurement decisions through specialized distributor networks and direct foundry relationships.
Product Type:
Schottky variants move through high-volume electronics distributors serving consumer adapter manufacturers, while automotive-grade silicon carbide devices flow through authorized distribution with AEC-Q101 traceability requirements.
- Schottky Diodes:Metal-semiconductor junctions achieve forward voltage drops below 0.45V with switching speeds exceeding 100kHz. Demand concentrates in Shanghai and Shenzhen manufacturing corridors for laptop and smartphone power adapters under China's GB energy-efficiency mandates.
- MOSFETs:Voltage-controlled majority-carrier devices integrate gate isolation for high-frequency switching circuits. Expansion concentrates in 800V electric vehicle traction inverters serving Stuttgart and Munich automotive clusters under EU Green Deal emission deadlines.
- Junction Diodes:Silicon-based bipolar structures retain cost advantage in sub-100W consumer applications with established supply chains through broadline distributors.
- Others:Specialized variants including PIN diodes and tunnel diodes address radar systems and microwave applications with limited volume throughput.
Schottky diodes dominate installed base across consumer and industrial tiers. MOSFETs are where expansion concentrates in automotive electrification applications.
End User:
Cost tier stratification separates premium automotive qualification requirements from price-sensitive consumer electronics procurement patterns.
- Automotive:Onboard chargers and DC-DC converters require AEC-Q101 qualified devices with temperature cycling validation. Procurement flows through tier-one module manufacturers with direct foundry agreements for silicon carbide substrates.
- Consumer Electronics:Smartphone and laptop adapters prioritize forward voltage efficiency at minimum cost. Junction diodes from Taiwan-based foundries serve this segment through electronics distributors in Shenzhen and Dongguan.
- Industrial Equipment:Motor drives and welding equipment demand robust thermal performance with extended operating temperature ranges.
- Telecommunications:Base station power supplies require high-reliability rectification with MTBF specifications exceeding consumer tiers.
Consumer electronics commands volume leadership. Automotive is climbing the fastest on electrification mandates.
Technology:
Volume concentration favors mature silicon processes, while margin expansion tracks wide-bandgap material adoption in premium thermal density applications.
- Silicon:Established planar and trench process technologies supply cost-optimized rectification for sub-200V applications. Maturity enables multi-source procurement through distributed foundry networks.
- Silicon Carbide:Wide-bandgap substrates enable 1200V+ operation with zero reverse recovery charge. Qualification timelines concentrate in Dresden manufacturing complexes serving European automotive module assemblers.
- Gallium Nitride:Heterostructure epitaxy extends switching frequencies beyond silicon limits for server power supplies and telecommunications rectifiers.
- Bipolar Technology:Insulated-gate bipolar transistor structures hybridize MOSFET input characteristics with bipolar conduction for medium-frequency industrial drives.
Silicon retains installed base dominance. Silicon carbide is gaining share fastest in high-voltage automotive architectures.
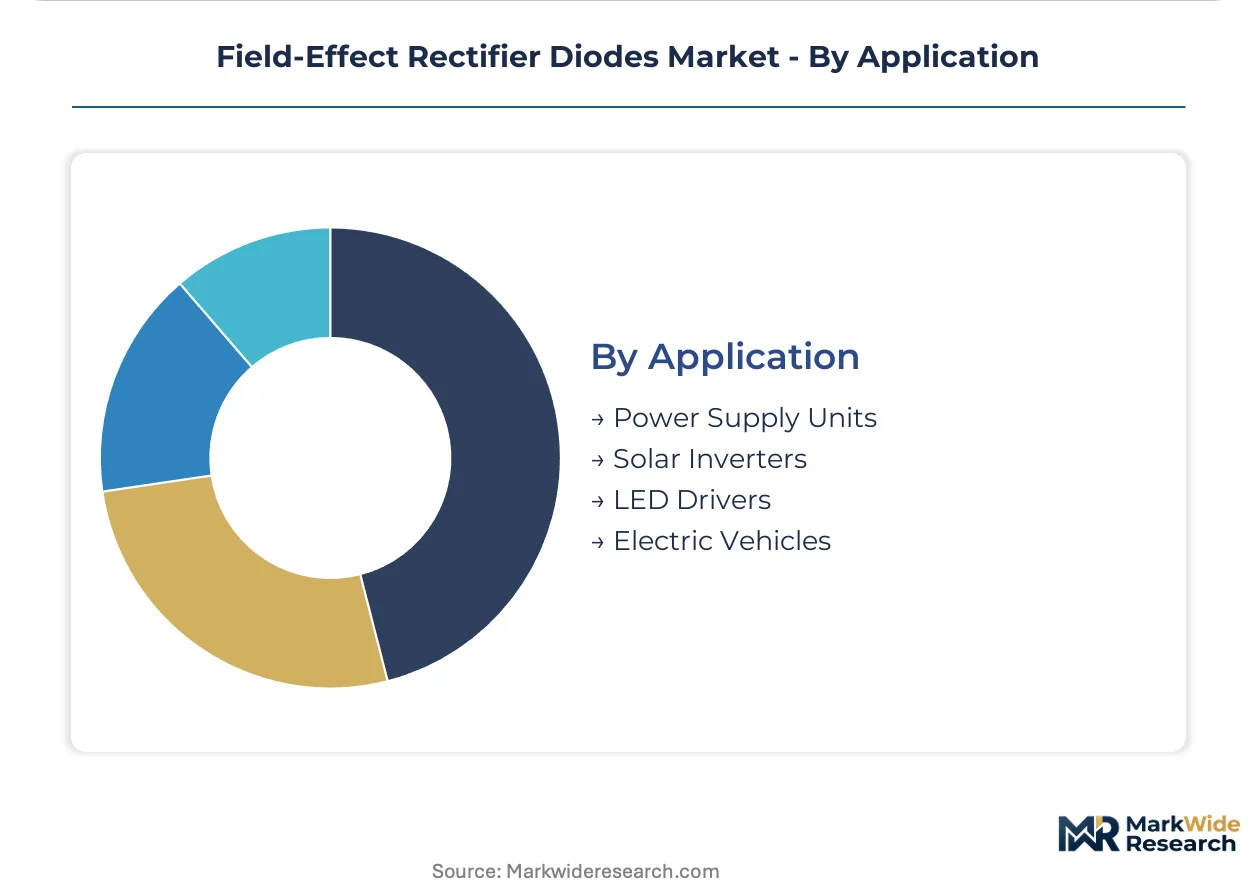
Application:
Customer type segmentation separates utility-scale procurement with extended qualification cycles from consumer electronics with compressed design-to-production timelines.
- Electric Vehicles:Onboard chargers, traction inverters, and DC-DC converters demand automotive-grade Schottky and MOSFET devices with substrate traceability. Procurement concentrates through captive sourcing teams at Volkswagen, BMW, and Mercedes-Benz.
- Power Supply Units:Adapter and server power applications span junction diodes in entry-level consumer tiers to gallium nitride Schottky devices in premium enterprise equipment.
- Solar Inverters:Utility photovoltaic installations at 1500V DC bus voltages require high-reliability silicon carbide rectification with extended warranty terms.
- LED Drivers:Solid-state lighting power conversion operates at moderate voltages with efficiency targets enforced by EU Ecodesign regulations.
Power supply units command volume leadership. Electric vehicles represent the steepest expansion trajectory on binding emission reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German automotive module assemblers while Chinese foundries compete on cost leadership for consumer-grade junction diodes. This asymmetry channels margin capture toward European qualification-heavy tiers and volume throughput toward Asia-Pacific manufacturing corridors.
Germany
Stuttgart and Munich automotive clusters drive silicon carbide rectifier procurement for 800V traction inverters under EU Green Deal emission deadlines. The KBA enforces AEC-Q101 traceability standards for onboard power electronics. Infineon Technologies anchors supply security through its Dresden manufacturing complex serving Volkswagen, BMW, and Mercedes-Benz captive sourcing teams.
China
Shanghai, Shenzhen, and Xi'an concentrate over sixty percent of domestic electric vehicle assembly capacity, creating dense procurement corridors for automotive-grade Schottky diodes. MIIT energy-efficiency mandates enforce minimum conversion efficiency thresholds in power supply units sold domestically. GB standards compliance shapes supplier qualification protocols across the Yangtze River Delta and Pearl River Delta manufacturing belts.
United States
Server power supply and telecommunications infrastructure demand high-frequency gallium nitride rectifiers for data center expansion. The EPA imposes standby power limits on imported rectifier-containing equipment while the FCC regulates electromagnetic compatibility. Texas and California technology corridors host qualification laboratories for wide-bandgap semiconductor deployment in grid-scale solar inverters.
Japan
Industrial motor drives and robotics power electronics sustain demand for high-reliability rectification with extended MTBF specifications. METI oversees national energy-efficiency roadmaps that channel R&D investment toward silicon carbide substrate development. The Kansai and Chubu manufacturing regions maintain precision fabrication capabilities for automotive and industrial tier suppliers.
India
Production-linked incentives for compound semiconductor fabs are attracting substrate and epitaxy investments under the PLI scheme. The CEA mandates domestic content requirements for solar inverter deployments exceeding certain capacity thresholds. Gujarat and Karnataka are emerging as localized rectifier manufacturing capacity hubs serving renewable energy and electric vehicle assembly operations.
Field-Effect Rectifier Diodes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the field-effect rectifier diodes market. European and Japanese incumbents anchor premium automotive tiers through captive silicon carbide substrate growth and AEC-Q101 qualification depth, while Taiwan-based foundries and Chinese assemblers dominate cost-optimized consumer electronics procurement. Three strategic archetypes define competitive positioning: vertically integrated substrate-to-device manufacturers, fabless design houses with foundry partnerships, and broadline discrete component suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as talent shortages unwind foundry deployment timelines.
Among European-based integrated manufacturers, STMicroelectronics and Infineon Technologies exemplify the substrate-captive archetype with in-house silicon carbide growth capabilities. Vishay Intertechnology occupies a position within the broadline discrete supplier tier competing on component breadth across industrial and consumer market segments. These three companies represent divergent strategic postures: captive vertical control versus distributed manufacturing scale versus portfolio diversification across voltage and frequency tiers.
| Leading Market Players |
|---|
| STMicroelectronics |
| NXP Semiconductors |
| Diodes Incorporated |
| ON Semiconductor |
| Infineon Technologies |
| Vishay Intertechnology |
| TE Connectivity |
| Electronic Devices |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Gallium nitride epitaxy replacing silicon in server power supplies simultaneously redraws procurement geography toward Taiwan-based foundries and compresses margin structures for legacy junction diode assemblers. This substitution dynamic channels automotive-grade silicon carbide premiums toward Dresden and Stuttgart while consumer-tier pricing collapses under Chinese foundry output.
Pricing Analysis
Geographic price spreads exceed three-to-one between automotive-grade silicon carbide rectifiers qualified to AEC-Q101 standards and commodity junction diodes from Shenzhen distributors. Pricing stratifies across automotive certification tiers, substrate traceability requirements, and volume commitment scales. Cost compression in consumer adapters intensifies as Chinese foundries expand six-inch silicon wafer output. Smartphone and laptop adapter manufacturers exhibit highest price sensitivity, while German automotive module assemblers accept premium positioning for substrate-provenance documentation.
Supply Chain Analysis
Six-inch silicon carbide substrate growth capacity acts as the decisive chokepoint constraining automotive rectifier output expansion. Supply concentrates in Taiwan, China, and Germany, with raw material dependencies spanning high-purity silicon carbide boules, gallium nitride epitaxy wafers, and specialized lead-frame copper alloys. Single-source vulnerability runs through TSMC's advanced power semiconductor foundry allocations. Distribution runs through authorized channels for automotive tiers and electronics distributors for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal emission mandates are compressing qualification timelines and forcing capital reallocation toward wide-bandgap semiconductor capacity, creating a high-growth disruption window for positioned suppliers.
For Market Incumbents: Consolidate substrate supply security through captive silicon carbide growth investments in Dresden or equivalent European manufacturing complexes. Deepen AEC-Q101 qualification pipelines to defend against fabless design houses attacking automotive electrification budgets. Prioritize process engineering talent retention as foundry expansion timelines unwind across Asia-Pacific. For New Entrants and Emerging Players: Aftermarket rectifier refurbishment and circular supply services represent underserved white-space where incumbents lack service infrastructure. Target India's PLI-supported compound semiconductor fabs for localized manufacturing entry. Pursue direct procurement relationships with Gujarat-based solar inverter assemblers as the most penetrable demand cluster. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component suppliers holding AEC-Q101 certification depth but lacking wide-bandgap substrate integration. Long-term viability favors upstream control over silicon carbide boule growth or gallium nitride epitaxy capabilities. Monitor MIIT energy-efficiency mandate enforcement intensity as the inflection signal for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Carbide Substrate Growth | Infineon's Dresden complex secures automotive supply security under EU Green Deal deadlines. |
| AEC-Q101 Qualification Pipeline Expansion | Eighteen-month validation cycles create defensive moats against unqualified competitors. |
| GaN-on-Silicon Process Convergence | TSMC's standard foundry integration reduces capital intensity for high-frequency rectifiers. |
| India PLI Scheme Localization | Gujarat and Karnataka fabs capture CEA-mandated domestic content for solar inverters. |
| Direct Automotive OEM Procurement | Volkswagen and BMW captive sourcing teams disintermediate traditional distribution buffers. |
Research Methodology
A spread of perspectives from power semiconductor process engineers, automotive Tier 1 procurement directors, foundry operations managers, and solar inverter system architects converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, MIIT energy-efficiency enforcement notices, and EU Ecodesign regulatory updates. Bottom-up demand modeling from application-specific consumption rates triangulated against top-down substrate supply forecasts.
Segmentation dimensions modeled include material technology tier, voltage handling class, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base turnover rates and technology substitution curves. Forecast inputs incorporate silicon carbide wafer supply expansion schedules and automotive electrification mandate compliance trajectories.
Underlying assumptions cover stable geopolitical access to Taiwan-based foundry capacity, with deviation risk concentrated in export control expansion or substrate supply disruption. Practitioners should keep alternative scenarios live as REACH substance restriction enforcement and carbon-border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Gan Transistor Market