
 North America Ultra-Low-Power Microcontroller Market | 2026-2036
North America Ultra-Low-Power Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ultra-Low-Power Microcontroller Market Analytics
Market Context
Medical wearable deployment is realigning North American demand toward 32-bit architectures with integrated wireless stacks. Texas Instruments leverages its MSP430 portfolio to dominate precision sensing applications in continuous health monitors. Microchip Technology anchors the mid-tier 16-bit segment through proprietary picoPower工艺 families optimized for battery-operated endpoints. Silicon Labs competes aggressively on radio coexistence, positioning its Series 2 EFM32 devices as the default for multi-protocol smart home hubs.
Technical Definition and Segment Structure
Ultra-low-power microcontrollers are integrated processing units engineered to operate below one microampere in sleep modes, typically fabricated on 40nm to 90nm process nodes with multiple autonomous peripheral states to minimize CPU wake cycles. These devices serve as the computational backbone for battery-constrained endpoints requiring months to years of unattended operation, from implantable medical sensors to distributed environmental monitors. The 32-bit segment leads absolute dollar volume as ARM Cortex-M33 and M4 cores displace 8-bit alternatives in wearable devices requiring floating-point DSP for biometric algorithms. Mixed Signal variants capture disproportionate margin pools by embedding 16-bit ADCs and programmable gain amplifiers that eliminate external analog front-ends in health monitoring applications. Bluetooth connectivity dominates unit shipments, though LoRa is accelerating in remote monitoring deployments across agricultural and utility infrastructure.
Regulatory Framework and Outlook
The FCC governs radio emissions and spectrum allocation for all wireless-enabled microcontrollers sold in the United States, while Health Canada and the FDA impose electromagnetic compatibility and biocompatibility standards on devices entering medical end-use channels. NHTSA's evolving cybersecurity guidelines for connected vehicles are beginning to shape microcontroller selection in aftermarket telematics modules. Stakeholders must monitor how the EPA's emerging e-waste reporting requirements affect chip-scale packaging choices and extended temperature grade certifications across the North American supply base.
Market Dynamics
Medical wearable OEMs in California and Texas are compressing development cycles for continuous glucose monitors, forcing microcontroller suppliers to pre-integrate Bluetooth Low Energy stacks and FDA-compliant firmware architectures before silicon tape-out.
Growth Catalysts
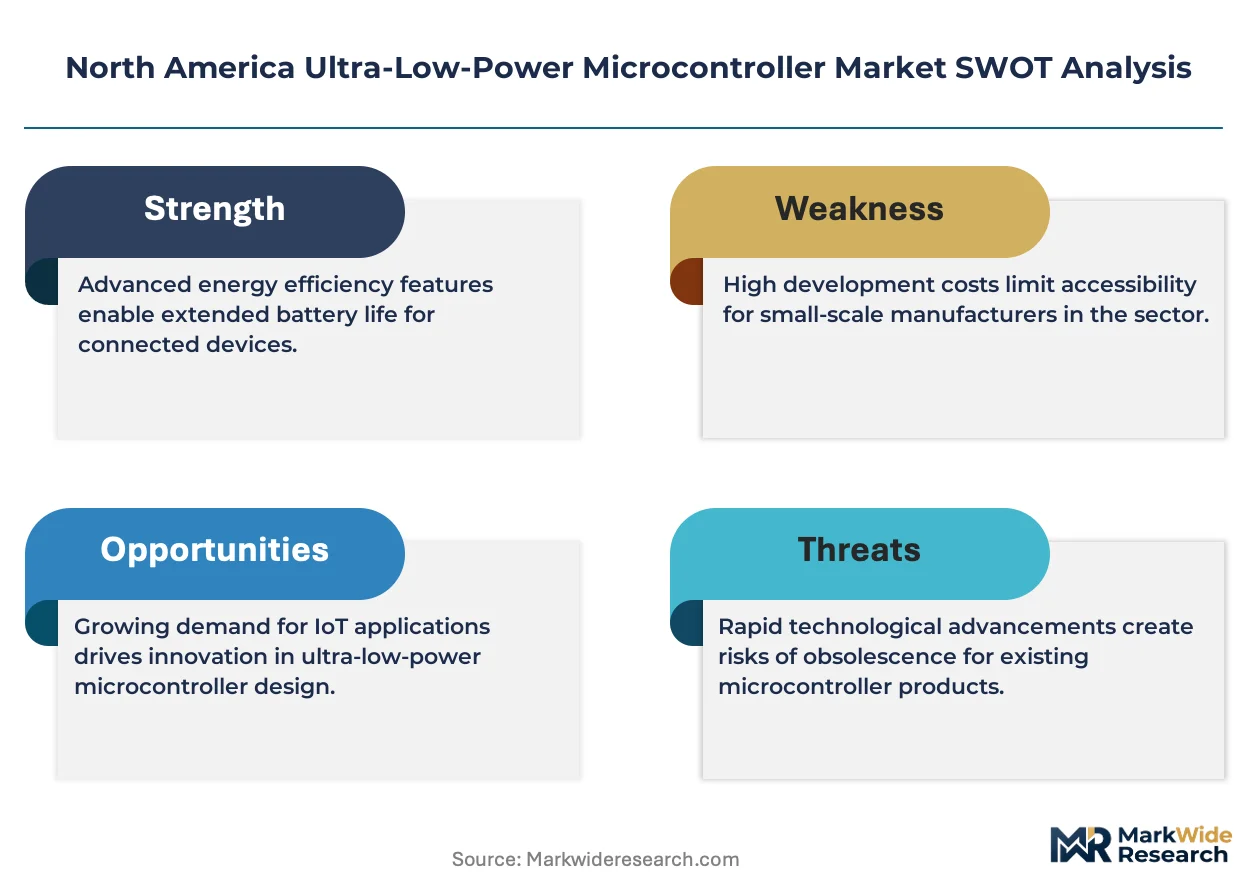
- FDA 510(k) pathway streamlining:Accelerated clearances for Class II medical devices are pulling 32-bit units into disposable health patches faster than traditional industrial qualification timelines.
- Silicon Valley hardware startup density:Venture-backed ventures in San Jose and Mountain View are prototyping at volumes that sustain dedicated ultra-low-power SKU lines from major suppliers.
- Sub-threshold circuit design:Advances in near-threshold voltage operation are extending coin-cell battery life beyond three years in unattended environmental sensors.
Market Restraints
- 40nm wafer allocation constraints:Foundry capacity at mature nodes remains bottlenecked by automotive MCU demand, stretching lead times for mixed-signal variants.
- Bluetooth SIG certification costs:End-product qualification fees for proprietary protocol stacks consume disproportionate budget share for sub-million-unit OEMs.
- Legacy 8-bit firmware inertia:Embedded software teams in industrial automation verticals resist migrating toolchain investments to ARM Cortex-M architectures.
Strategic Opportunities
- Texas Austin semiconductor corridor expansion:Foundry and test facility investments in Travis County are creating captive supply options for fabless designers targeting medical channels.
- Energy harvesting integration:Photovoltaic and thermoelectric scavenging circuits are converging with sub-microamp sleep states to enable battery-free endpoint designs.
- IRA domestic manufacturing incentives:Clean energy tax credits for semiconductor fabrication equipment are offsetting capital intensity for 90nm line upgrades serving automotive-qualified parts.
Industry Challenges
- RF coexistence engineering scarcity:Specialists capable of mitigating 2.4 GHz interference between Bluetooth and Wi-Fi in compact wearable layouts command premium compensation packages.
- ISO 13485 medical device quality system audits:Certification timelines for microcontroller suppliers without existing healthcare vertical exposure extend 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ultra-Low-Power Microcontroller Market |
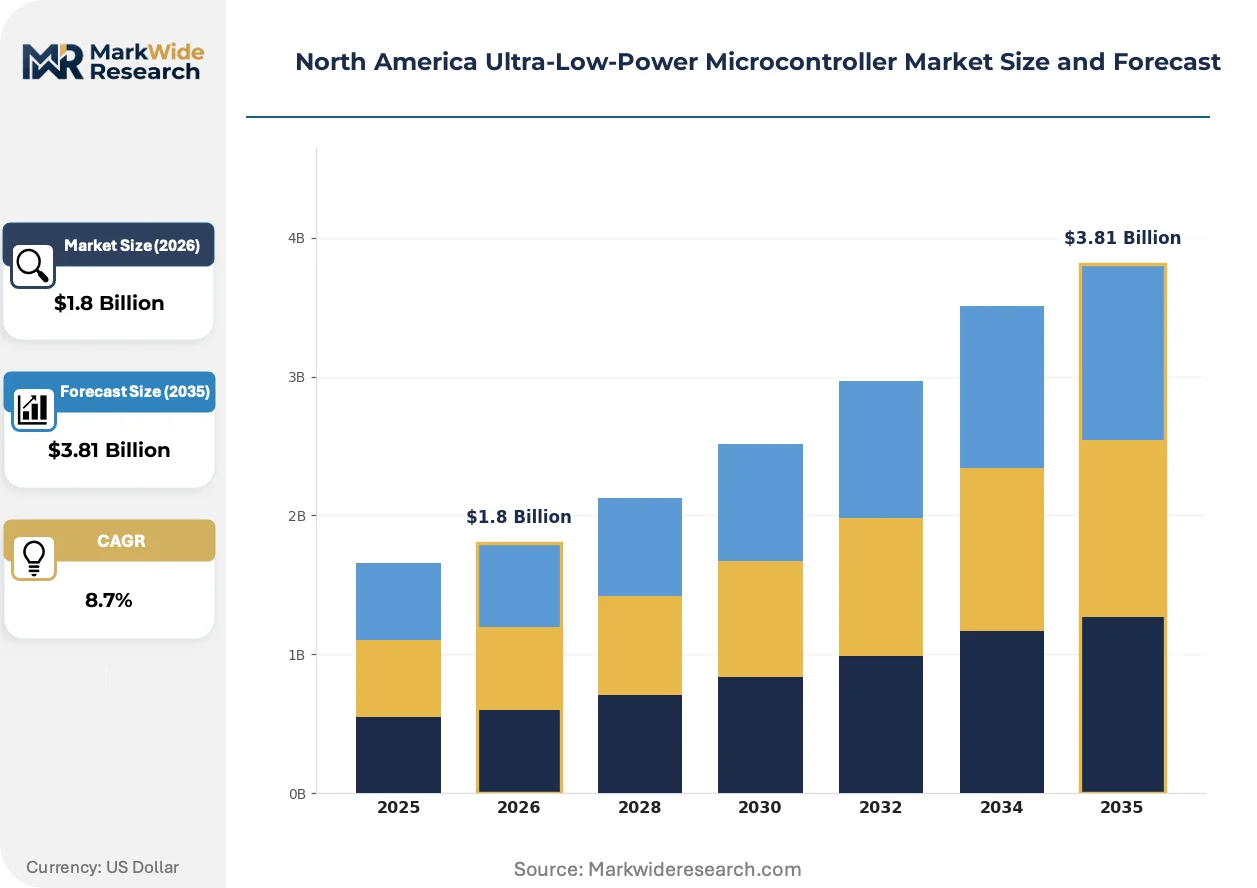
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, Mixed Signal End User: Consumer Electronics, Industrial Automation, Health Monitoring, Smart Home Devices Connectivity: Bluetooth, Wi-Fi, Zigbee, LoRa Application: Wearable Devices, Smart Sensors, Home Appliances, Remote Monitoring |
| Companies Covered | Texas Instruments, Microchip Technology, NXP Semiconductors, Infineon Technologies, STMicroelectronics, Renesas Electronics, Analog Devices, Silicon Labs, Nordic Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ultra-Low-Power Microcontroller Market Evolving Landscape
Radio integration and autonomous peripheral architectures are compressing bill-of-materials counts while FDA cybersecurity guidance is rewriting firmware validation requirements for connected health endpoints.
ARM TrustZone-M hardware security extensions are consolidating root-of-trust implementations into single-core designs previously requiring discrete secure elements. Medical OEMs in Minneapolis and Boston are adopting these configurations for insulin pump controllers ahead of NHTSA-influenced automotive telematics adoption. The consolidation is collapsing two-chip security architectures into standard microcontroller SKUs.
FCC Part 15 unlicensed device rules are tightening spurious emission limits for wearable transmitters operating near aircraft navigation bands. Hardware teams in San Diego and Raleigh are redesigning matching networks and shielding layouts to preempt certification failures. The rule evolution is favoring pre-certified module suppliers over discrete RF design approaches.
Contract manufacturers in Mexico's Baja California corridor are absorbing final test and programming steps previously executed by semiconductor distributors. OEM procurement teams in Arizona and Southern California are qualifying these facilities for HIPAA-compliant firmware loading. The geographic proximity is compressing logistics cycles for FDA-regulated device launches.
North America Ultra-Low-Power Microcontroller Market Segmentation
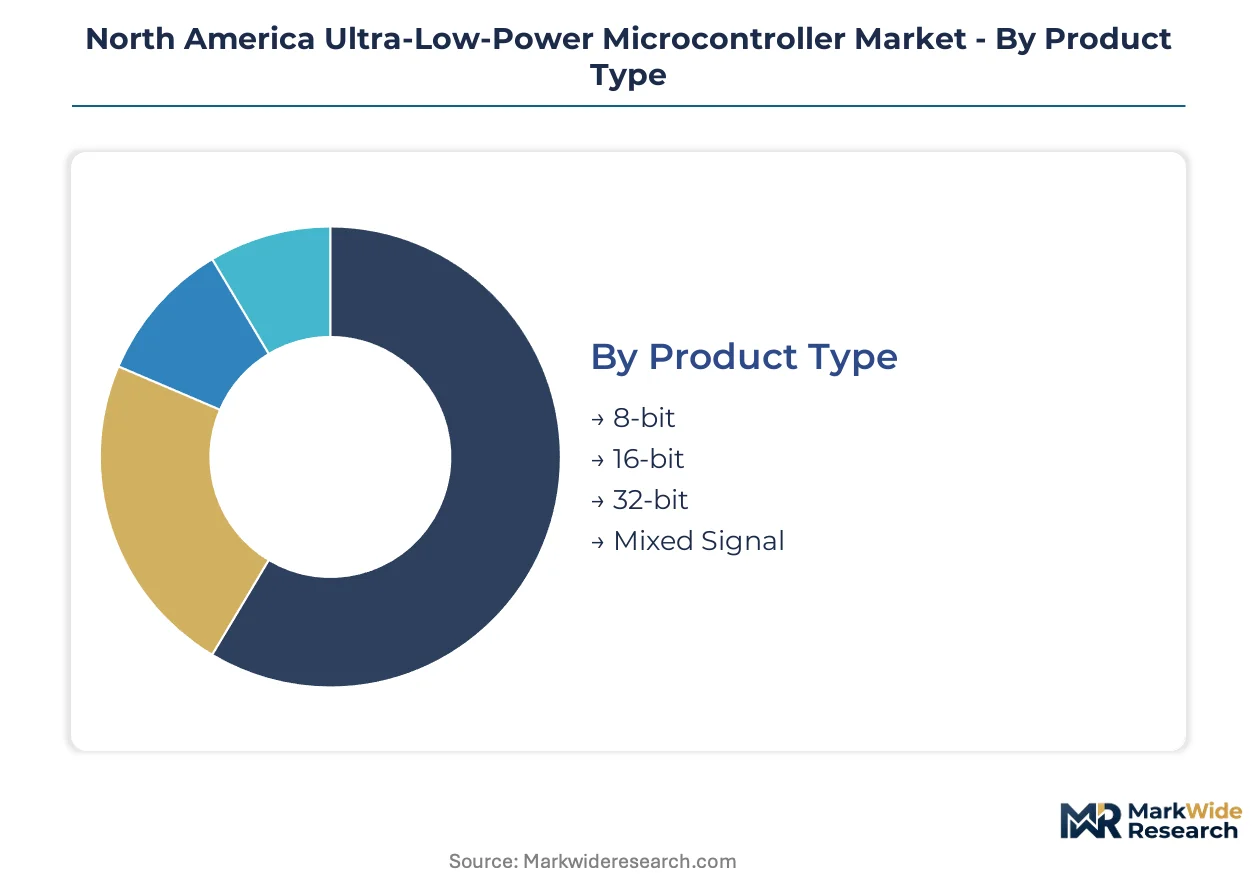
Ultra-low-power microcontroller procurement patterns diverge sharply across bit-width architectures, connectivity protocols, and end-use certification requirements. Suppliers must maintain parallel SKU strategies serving FDA-regulated health channels alongside unlicensed consumer electronics deployments.
Product Type:
Standardization dominates at the 8-bit and 16-bit tiers where ARM Cortex-M0+ and proprietary cores ship in million-unit volumes with minimal customization, while 32-bit and mixed-signal variants demand extensive analog front-end tuning and firmware co-development for specific sensing applications.
- 8-bit:Legacy Harvard-architecture cores operate at sub-1MHz clock speeds with sub-microamp sleep currents, serving cost-constrained industrial sensor nodes in Michigan automotive supplier parks where firmware teams resist toolchain migration.
- 16-bit:Texas Instruments MSP430 and Microchip PIC24 families anchor mid-tier battery-operated endpoints, with proprietary picoPower工艺 variants capturing procurement contracts for Minnesota-based medical device subcontractors requiring 10-year product longevity commitments.
- 32-bit:ARM Cortex-M33 and M4 cores with floating-point DSP units displace narrower architectures in California wearable startups prototyping continuous glucose monitors requiring real-time biometric algorithm execution.
- Mixed Signal:Embedded 16-bit ADCs and programmable gain amplifiers eliminate external analog front-ends, commanding premium pricing in FDA-regulated insulin pump controllers manufactured in Massachusetts medical device corridors.
Leading the category by volume: 8-bit. Growing fastest: Mixed Signal.
End User:
Margin structures invert across this dimension, with health monitoring applications absorbing 40-60% gross margins for qualified suppliers while consumer electronics procurement drives ruthless cost-down cycles on 32-bit Bluetooth-enabled units.
- Consumer Electronics:Fitness trackers and wireless earbuds in Shenzhen-to-Los Angeles supply chains prioritize pre-certified modules over discrete RF design, compressing development cycles to 8-12 months for holiday retail windows.
- Industrial Automation:Programmable logic controllers and distributed sensor networks in Ohio and Pennsylvania manufacturing belts demand extended temperature grades and 15-year availability guarantees, locking in 16-bit architectures with legacy peripheral sets.
- Health Monitoring:FDA 510(k) pathway requirements for Class II devices in Minnesota and California corridors mandate ISO 13485-certified suppliers with pre-validated firmware architectures, extending qualification timelines to 18-24 months.
- Smart Home Devices:Multi-protocol hubs in Austin and San Diego hardware clusters require radio coexistence engineering for 2.4GHz spectrum management, favoring Silicon Labs Series 2 EFM32 platforms with integrated Zigbee and Thread stacks.
Highest margin concentration: Health Monitoring. Steepest expansion trajectory: Smart Home Devices.
Connectivity:
Certification cost tiers separate this category, with Bluetooth SIG qualification fees consuming disproportionate budget share for sub-million-unit OEMs while LoRa deployments bypass proprietary stack royalties through open-source firmware foundations.
- Bluetooth:Low Energy 5.3 stacks dominate unit shipments in wearable and hearable applications, with FCC Part 15 pre-certified modules from Nordic Semiconductor and Texas Instruments accelerating time-to-market for Arizona-based hardware startups.
- Wi-Fi:802.11ax-enabled microcontrollers penetrate smart home hub applications requiring TCP/IP offload, though power budgets restrict deployment to mains-connected endpoints in Texas residential automation installations.
- Zigbee:Mesh networking protocols sustain utility-scale smart meter deployments across Ontario and Quebec provincial grids, with Thread 1.3 interoperability emerging as a migration path for Matter-compatible device ecosystems.
- LoRa:Sub-GHz unlicensed spectrum access enables 10km-range environmental monitors in California Central Valley agricultural corridors and Alberta oilfield infrastructure, bypassing cellular subscription costs for decade-long unattended operation.
Widest deployment base: Bluetooth. Gaining share fastest: LoRa.
Application:
Physical form factors and power scavenging requirements differentiate procurement specifications, with wearable devices demanding sub-2mm chip-scale packages while remote monitoring applications prioritize energy harvesting integration over size constraints.
- Wearable Devices:Continuous glucose monitoring patches and smartwatch subsystems in San Jose design houses require 40nm process nodes with integrated Bluetooth radios, driving procurement toward single-die system-in-package solutions.
- Smart Sensors:Distributed air quality and vibration monitors in Pacific Northwest industrial facilities leverage sub-threshold voltage operation to extend coin-cell life beyond three years, favoring Ambiq Apollo4 Blue implementations.
- Home Appliances:White goods manufacturers in Wisconsin and Tennessee appliance corridors specify 5V-tolerant GPIO and motor control peripherals, sustaining 8-bit and 16-bit architectures with legacy 5V CMOS compatibility.
- Remote Monitoring:Photovoltaic-powered agricultural soil sensors and thermoelectric pipeline monitors in Permian Basin oilfields converge energy harvesting front-ends with sub-microamp sleep states, eliminating battery maintenance for decade-long deployments.
Largest absolute volume: Wearable Devices. Expanding most quickly: Remote Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CHIPS Act tax credits and IRA domestic manufacturing incentives are concentrating ultra-low-power microcontroller design and test capacity in federally designated semiconductor corridors across the United States, Canada, and Mexico.
United States
FDA 510(k) pathway streamlining for Class II medical devices is pulling 32-bit units into disposable health patches faster than traditional industrial timelines. FCC Part 15 rules for unlicensed radio devices push developers toward pre-certified Bluetooth Low Energy modules. California's Silicon Valley hardware startup cluster sustains dedicated ultra-low-power SKU lines from major suppliers at prototyping volumes.
Canada
Health Canada electromagnetic compatibility standards shape microcontroller selection for devices entering medical end-use channels across Ontario and Quebec. The country's national pharmaceutical regulator imposes biocompatibility requirements on implantable sensor designs. Toronto and Vancouver hardware clusters are qualifying Mexican contract manufacturers for HIPAA-compliant firmware loading to compress logistics cycles.
Mexico
Baja California corridor contract manufacturers absorb final test and programming steps previously executed by semiconductor distributors serving Arizona and Southern California OEMs. The country's proximity to US medical device launch markets enables rapid turnaround for FDA-regulated production. Monterrey and Tijuana assembly facilities specialize in chip-scale packaging for sub-2mm wearable form factors.
North America Ultra-Low-Power Microcontroller Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers commanding premium positioning in FDA-regulated health channels while fabless designers capture smart home hub applications. The vendor base concentrates around three strategic archetypes: diversified analog-semiconductor conglomerates with captive fabrication, pure-play ultra-low-power specialists with radio integration expertise, and emerging fabless ventures leveraging CHIPS Act foundry access. Dominant competitive moves include strategic partnerships for pre-certified module supply and backward integration into 40nm test capacity.
Among diversified semiconductor conglomerates, Texas Instruments and Microchip Technology exemplify the integrated-manufacturer archetype with established medical-channel qualification. Silicon Labs occupies a position within the radio-specialist tier, competing aggressively on multi-protocol coexistence engineering for smart home applications. These three anchors represent distinct competitive vectors: precision sensing dominance, mid-tier battery-operated endpoint anchoring, and wireless stack integration leadership.
| Leading Market Players |
|---|
| Texas Instruments |
| Microchip Technology |
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Renesas Electronics |
| Analog Devices |
| Silicon Labs |
| Nordic Semiconductor |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot prices cascade through North American ultra-low-power microcontroller supply chains, compressing margins on 40nm mixed-signal variants while amplifying pricing power for integrated manufacturers with captive fabrication. Contract-based long-term offtake agreements now dominate procurement between medical OEMs and qualified suppliers, insulating FDA-regulated channels from spot-market volatility that erodes consumer electronics pricing.
Pricing Analysis
Lead-time-driven pricing separates urgent orders from scheduled deliveries, with 32-week lead times commanding premium positioning for automotive-qualified parts while spot inventory clears at discounted rates. Three-tier pricing structure across FDA-certified, industrial-grade, and consumer-tier levels reflects ISO 13485 audit investments. Pricing pressure stems from foundry capacity competition with automotive MCUs. Consumer electronics buyers exhibit highest price sensitivity; medical device OEMs absorb certification-embedded premiums.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while 300mm silicon wafer fabrication concentrates in Taiwan and South Korea. Mature-node foundry capacity draws from constrained 40nm-90nm equipment availability, with noble metal sputtering targets sourcing from South African and Russian suppliers. Single-source vulnerability persists in EUV lithography components. Distribution runs through authorized distributors serving Arizona and Southern California OEMs with HIPAA-compliant programming services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) cybersecurity guidance operates as a cost-of-compliance moat, elevating barrier-to-entry economics for entrants lacking pre-validated firmware architectures and ISO 13485 certification infrastructure.
For Market Incumbents: Anticipate fabless startup encroachment on smart home hub applications by deepening backward integration into 40nm test capacity in Travis County. Prioritize RF coexistence engineering talent retention against Silicon Labs and Nordic Semiconductor poaching. Defensive consolidation through pre-certified module partnerships with Mexican contract manufacturers compresses competitor time-to-market advantages. For New Entrants and Emerging Players: Energy harvesting integration offers a technology-first wedge into California Central Valley agricultural monitoring deployments underserved by battery-dependent incumbents. Target Alberta oilfield infrastructure for LoRa-enabled pipeline sensors requiring decade-long unattended operation. Pursue hospital-at-home device OEMs in Minneapolis corridor seeking second-source qualified suppliers for insulin pump controllers. For Investors and Strategic Acquirers: Distressed-cycle entries favor radio-specialist fabless designers with FDA channel exposure in Massachusetts medical device corridors. Long-term viability hinges on CHIPS Act foundry access maturation across the analysis window. Monitor Bluetooth SIG certification backlog duration as inflection indicator for module supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Test Capacity | Captive 40nm qualification lines in Austin insulate medical-channel suppliers from foundry allocation bottlenecks. |
| Pre-Certified Module Partnership | FCC Part 15 pre-certified Bluetooth stacks accelerate Arizona hardware startup FDA submission timelines. |
| Energy Harvesting Platform Development | Photovoltaic-thermoelectric convergence enables battery-free endpoints in Permian Basin pipeline monitoring. |
| ISO 13485 Quality System Investment | Medical-device certification infrastructure locks in 40-60% gross margin pools for qualified microcontroller suppliers. |
| RF Coexistence Engineering Acquisition | 2.4GHz spectrum management specialists command premium compensation in San Diego smart home hub clusters. |
Research Methodology
SEC 10-K filings, FCC equipment authorization databases, and FDA 510(k) clearance records formed the secondary backbone, supplemented by customs trade data tracking silicon wafer and noble metal sputtering target flows. Primary interviews with biomedical engineers at Minnesota medical device OEMs, GPO contracts managers in California hospital systems, and fabless design house CTOs in Austin and San Jose validated demand assumptions. Bottom-up and top-down triangulation cross-checked unit shipment estimates against foundry capacity disclosures.
Bottom-up modeling aggregated segment-level demand across bit-width architectures, connectivity protocols, and end-use certification requirements, while top-down analysis anchored total addressable market sizing to CHIPS Act incentive disbursement patterns. Segmentation dimensions included process node tier, FDA regulatory pathway, and geographic manufacturing cluster. CAGRs derived from regression analysis against medical wearable deployment trajectories and automotive MCU demand spillover effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry allocation shocks or Bluetooth SIG certification timeline extensions. Forecasts reflect documented assumptions on CHIPS Act facility commissioning schedules and IRA domestic manufacturing credit utilization rates. A small set of named triggers—NHTSA cybersecurity rule finalization, EPA e-waste reporting requirements, and Health Canada biocompatibility standard updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Laneth-16 Market