
 Foundry Binders Market | 2026-2036
Foundry Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Foundry Binders Market Analysis
Automotive end-use demand is shifting toward investment casting grades that accommodate turbocharger housings and electric motor stator frames. ASK Chemicals GmbH specializes in alkali phenolic binder systems for complex core production. Huntsman Corporation leverages polyurethane cold box technology across European OEM supply chains. Mitsubishi Chemical Corporation anchors Asian demand with furan resin formulations optimized for high-volume gray iron foundries.
Foundry binders are adhesive formulations—typically phenolic, furan, or urethane-based resins—that bond sand particles into molds and cores capable of withstanding molten metal temperatures exceeding 1,500°C. These systems cure through chemical reaction (acid-catalyzed or gas-hardened) to produce dimensional stability during pouring, shakeout, and reclamation cycles. Organic binder chemistry dominates current revenue pools due to established performance in ferrous casting, though inorganic binder development accelerates as foundries face stricter emissions protocols on volatile organic compound release. Cold box technology leads volume deployment in high-throughput automotive operations, while 3D printing binder jetting represents the fastest-expanding segment as digital foundries prototype complex geometries without hard tooling investment.
EPA air toxics standards shape North American product development timelines, forcing reformulation of traditional phenolic and urethane systems. REACH registration requirements in Europe constrain raw material sourcing for formaldehyde-based binders, redirecting R&D expenditure toward silicate and geopolymer alternatives. ECHA substance evaluation further tightens allowable emissions from core-making processes. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and ensure cross-border mold and core supply compatibility.
Market Dynamics
Automotive lightweighting mandates and REACH chemical restrictions are forcing simultaneous reformulation of phenolic binder systems and accelerated adoption of inorganic alternatives across European and Asian foundry clusters.
Growth Catalysts
- Automotive Lightweighting Programs:Turbocharger housings and electric motor stator frames in Germany and Japan require precision investment casting binders with dimensional stability at elevated temperatures.
- REACH Chemical Restrictions:ECHA substance evaluation is accelerating R&D expenditure toward bio-based phenolic systems and silicate alternatives in European core-making operations.
- Integrated Foundry Clusters:Demand concentrates in China's Hebei and Shandong provinces where captive supply chains serve domestic heavy machinery and export casting operations.
Market Restraints
- Formaldehyde Sourcing Constraints:REACH registration requirements constrain raw material availability for traditional phenolic binders across EU member states.
- Performance Gap in Ferrous Casting:Inorganic geopolymer alternatives currently lack the established thermal shock resistance of organic binder chemistry in gray iron applications.
- Emissions Compliance Costs:EPA air toxics standards in the United States force capital-intensive reformulation of urethane cold box systems.
Strategic Opportunities
- 3D Printing Binder Jetting:Digital foundries in Germany and Japan prototype complex geometries without hard tooling investment, representing the fastest-expanding technology segment.
- Bio-Based Phenolic Development:EU Green Deal funding streams support lignin-derived resin research for core production with reduced volatile organic compound profiles.
- Aftermarket Reclamation Services:Sand reclamation chemistry providers can capture value from foundries facing rising disposal costs under tightening waste directives.
Industry Challenges
- Cross-Border Formulation Compatibility:Regulatory divergence between EPA, REACH, and China's GB standards creates stranded investment risk for multinational binder suppliers.
- Cold Box Process Expertise Shortage:Gas-hardened polyurethane system operation requires specialized technicians increasingly scarce in aging European foundry workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundry Binders Market |
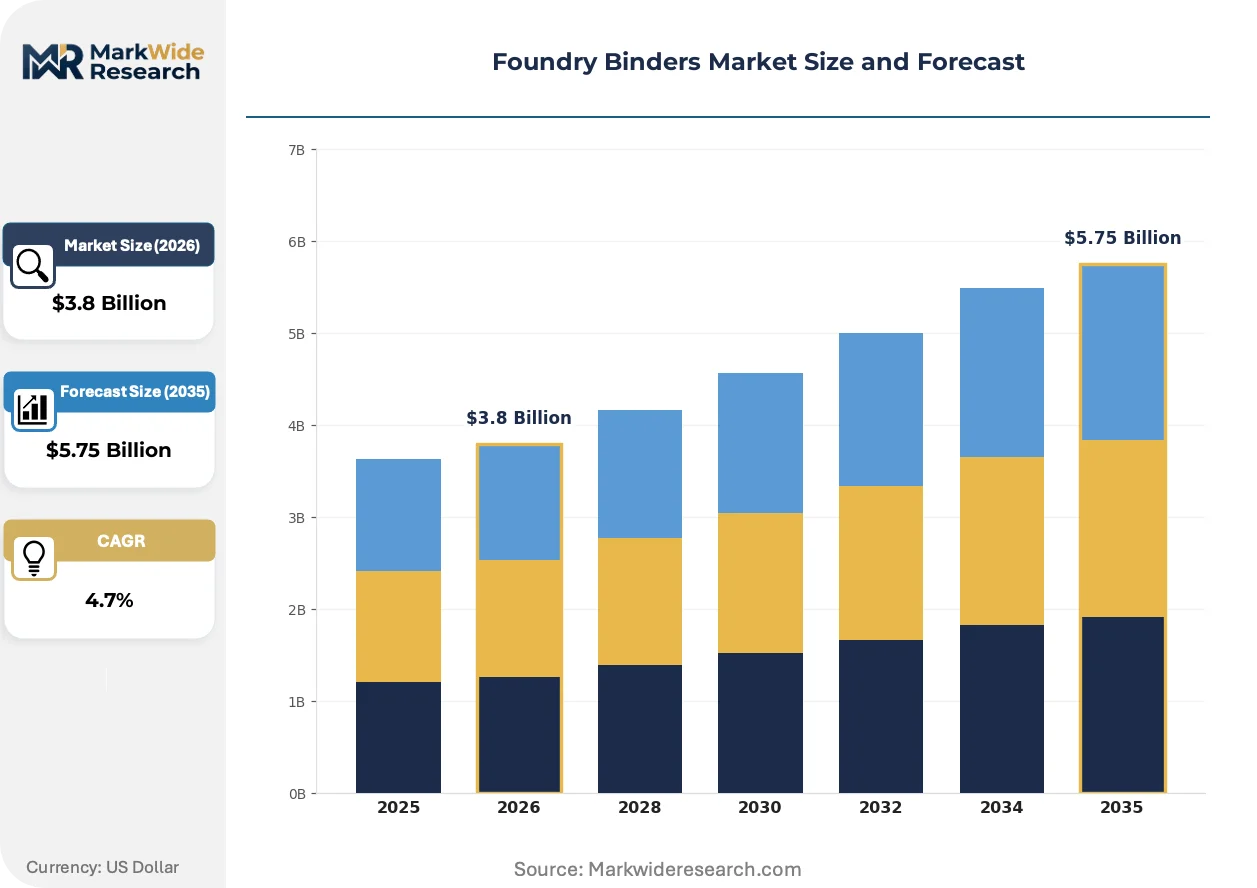
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Binders, Inorganic Binders, Synthetic Binders, Water-Soluble Binders Application: Metal Casting, Sand Casting, Investment Casting, Permanent Mold Casting End User: Aerospace, Automotive, Heavy Machinery, Consumer Goods Technology: 3D Printing, Cold Box, Hot Box, Shell Molding |
| Companies Covered | Kao Corporation, Huntsman Corporation, ASK Chemicals GmbH, Ashland Global Holdings Inc., Evonik Industries AG, BASF SE, Foseco (Vesuvius Group), Mitsubishi Chemical Corporation, Imerys S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundry Binders Market Emerging Trajectories
Digital manufacturing architectures and emissions compliance frameworks are reshaping how binder systems are formulated, cured, and deployed across ferrous and non-ferrous casting operations.
Silicate-based inorganic binder chemistry is integrating sodium silicate and geopolymer formulations into high-throughput automotive core production. German OEM supply chains are piloting these systems for aluminum engine block casting. The technology is integrating emissions reduction mandates with existing cold box infrastructure through hybrid curing processes.
REACH authorization procedures are tightening allowable formaldehyde release thresholds from phenolic resin curing. European foundries must reformulate acid-catalyzed systems or shift to furan alternatives. Core-making operations in Poland and the Czech Republic face compressed compliance timelines through 2027.
Automotive procurement departments now mandate cradle-to-gate emissions documentation for mold and core materials. Tier-1 casting suppliers in Japan and Germany are unbundling traditional chemical supply contracts to favor regional formulators with certified carbon accounting. This pattern concentrates specification authority with OEM sustainability teams rather than foundry floor managers.
Foundry Binders Market Segmentation
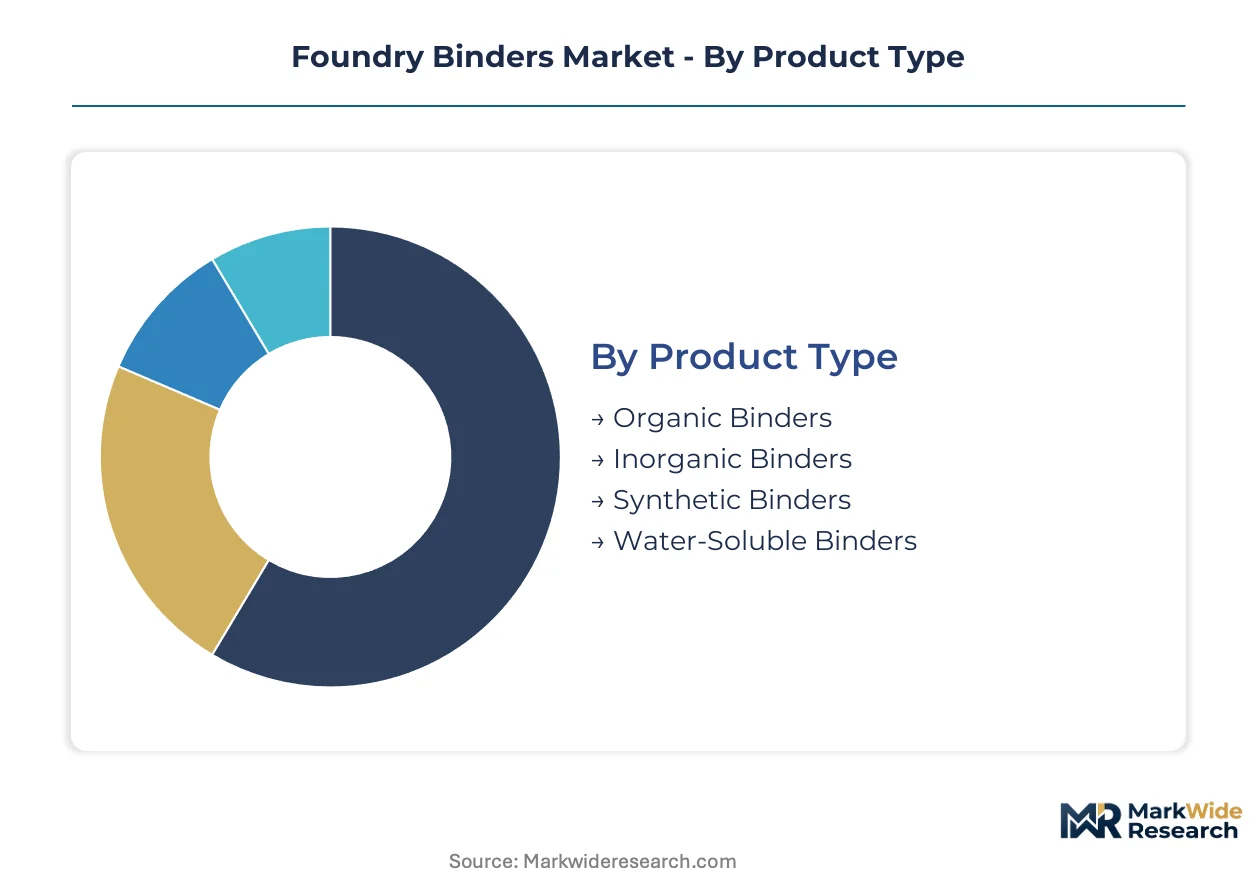
Foundry binder specifications diverge sharply across casting temperatures, metal alloy types, and emissions compliance requirements. Product selection directly determines mold integrity, shakeout efficiency, and sand reclamation economics. Each segmentation axis captures distinct procurement patterns and reformulation pressures.
Product Type:
Replacement cycles for organic binder systems are compressing as foundries face simultaneous REACH deadlines and performance upgrade demands.
- Organic Binders:Phenolic, furan, and urethane resin formulations dominate ferrous casting through acid-catalyzed or gas-hardened curing mechanisms. German automotive foundries in Baden-Württemberg specify these grades for turbocharger housing production despite formaldehyde sourcing constraints under ECHA substance evaluation.
- Inorganic Binders:Sodium silicate and geopolymer systems eliminate volatile organic compound emissions during core-making. Japanese OEM supply chains in Aichi Prefecture pilot these alternatives for aluminum engine block casting where thermal shock requirements are less severe than gray iron applications.
- Synthetic Binders:Engineered polymer formulations bridge performance gaps between organic and inorganic chemistry. These systems target precision investment casting operations requiring dimensional stability at elevated temperatures.
- Water-Soluble Binders:Starch and dextrin-based adhesives serve low-temperature non-ferrous applications with simplified reclamation chemistry. Consumer goods casting in China's Guangdong province consumes these grades for cost-sensitive zinc and aluminum components.
Volume placements concentrate in organic binder chemistry; the faster expansion belongs to inorganic alternatives.
Application:
Process selection correlates with part complexity, surface finish requirements, and tooling investment horizons across end-use sectors.
- Metal Casting:The umbrella category spans ferrous and non-ferrous production where binder systems must withstand pouring temperatures exceeding 1,500°C. Heavy machinery manufacturers in China's Hebei province specify high-strength phenolic grades for crane component production.
- Sand Casting:Green sand and chemically bonded systems produce over 70% of global casting tonnage. Cold box polyurethane technology dominates high-throughput automotive operations in Germany and Japan where dimensional repeatability is critical.
- Investment Casting:Ceramic shell systems use colloidal silica and ethyl silicate binders for turbine blade and medical implant production. Aerospace procurement in France and the United States mandates cradle-to-gate emissions documentation for these materials.
- Permanent Mold Casting:Gravity and low-pressure die casting of aluminum components uses minimal binder content. Italian automotive suppliers in Emilia-Romagna favor this approach for wheel and suspension bracket production.
Revenue pools favor sand casting chemistry; investment casting binders command the steepest expansion trajectory.
End User:
Customer sophistication and specification authority vary dramatically across sectors, with OEM sustainability teams increasingly overriding foundry floor preferences.
- Aerospace:Investment casting for turbine blades, structural components, and landing gear demands ceramic shell systems with traceable thermal expansion coefficients. French and American OEMs now require certified carbon accounting from material suppliers.
- Automotive:Turbocharger housings, electric motor stator frames, and engine blocks drive demand for precision core production. German and Japanese procurement departments unbundle traditional chemical supply contracts to favor regional formulators with documented emissions profiles.
- Heavy Machinery:Mining equipment, construction vehicles, and agricultural machinery casting prioritizes cost efficiency over surface finish. China's Shandong province anchors this demand through integrated foundry clusters serving domestic and export markets.
- Consumer Goods:Plumbing fixtures, hardware, and decorative casting tolerates lower specification grades. Water-soluble and synthetic binder systems dominate this price-sensitive segment.
Automotive specifications concentrate procurement volume; aerospace qualification requirements are climbing the fastest.
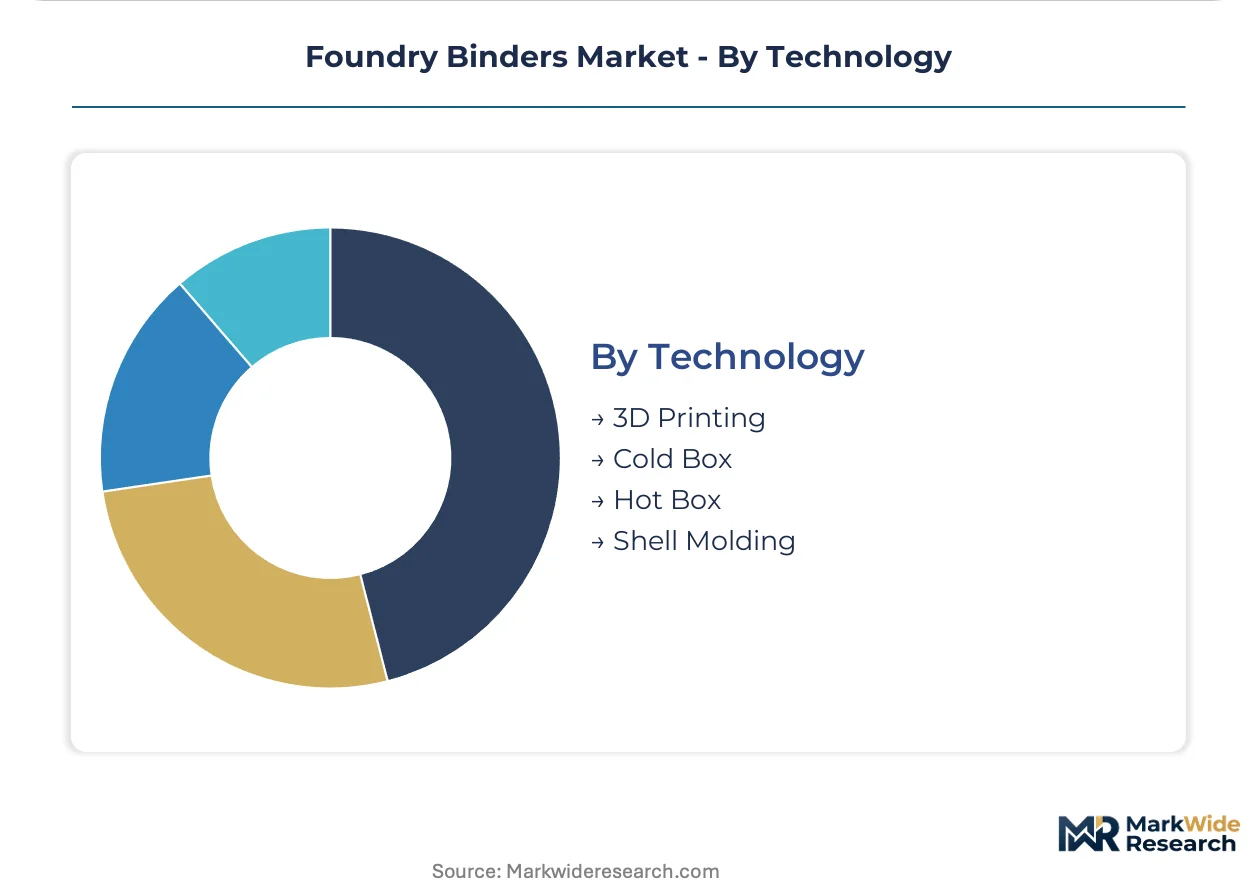
Technology:
Capital intensity and workforce skill requirements shape adoption curves across curing methodologies.
- 3D Printing:Binder jetting systems deposit liquid adhesive onto sand layers to prototype complex geometries without hard tooling investment. German and Japanese digital foundries are expanding this capability fastest.
- Cold Box:Gas-hardened polyurethane and phenolic systems cure at ambient temperature through amine or SO₂ catalysis. This technology leads volume deployment in European OEM supply chains despite technician scarcity.
- Hot Box:Heated core boxes accelerate phenolic resin curing for high-volume production. Italian and Spanish foundries maintain this equipment for automotive and plumbing component manufacturing.
- Shell Molding:Resin-coated sand preheated against metal patterns produces smooth surface finishes for steel casting. French and American operations use this process for valve and fitting production.
Equipment installations concentrate in cold box infrastructure; 3D printing capacity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hebei and Shandong provinces anchor foundry binder demand through integrated industrial zones serving heavy machinery and export casting operations. Germany's Baden-Württemberg automotive cluster and Japan's Aichi Prefecture precision manufacturing corridor concentrate premium-grade consumption. Regulatory divergence across EPA, REACH, and China's GB standards shapes regional formulation strategies.
China
Hebei and Shandong provinces host captive supply chains for domestic heavy machinery and export casting operations. GB standards on industrial emissions tighten allowable volatile organic compound release from core-making processes. Foundry clusters in Tangshan and Weifang pivot toward silicate-based alternatives to maintain export compliance with EU REACH requirements.
Germany
Baden-Württemberg automotive foundries specify precision investment casting binders for turbocharger housings and electric motor stator frames. ECHA substance evaluation accelerates reformulation timelines for acid-catalyzed phenolic systems through 2027. Core-making operations in Stuttgart and Mannheim pilot hybrid curing processes integrating emissions reduction with existing cold box infrastructure.
Japan
Aichi Prefecture OEM supply chains pilot sodium silicate and geopolymer alternatives for aluminum engine block casting. METI industrial decarbonization programs fund lignin-derived resin research for reduced volatile organic compound profiles. Digital foundries in Nagoya expand binder jetting capacity for complex geometry prototyping without hard tooling investment.
United States
EPA air toxics standards force capital-intensive reformulation of urethane cold box systems across Midwest automotive supply chains. Foundries in Michigan and Ohio face compressed compliance timelines for traditional phenolic chemistry. Aftermarket sand reclamation services capture value from operations facing rising disposal costs under tightening state waste directives.
France
Aerospace procurement mandates cradle-to-gate emissions documentation for ceramic shell investment casting binders. ANSM and CNIL oversight extends to industrial chemical traceability for turbine blade and medical implant production. Foundry operations in Lyon and Toulouse qualify regional formulators with certified carbon accounting to meet OEM sustainability team specifications.
Foundry Binders Market Vendor Landscape
Top-tier vendors anchor European and Asian chemical supply chains, while mid-tier regional formulators capture specification authority through localized emissions certification. Market structure tilts toward consolidation among multinational resin producers with integrated R&D and captive foundry relationships. Two dominant archetypes emerge: diversified chemical conglomerates with cross-sector binder portfolios, and specialized foundry chemical houses with process-specific expertise. Competitive moves concentrate on backward integration into raw material sourcing and technology licensing for 3D printing binder jetting systems.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify scale-driven positions spanning organic and inorganic formulation platforms. Specialized foundry chemical houses include ASK Chemicals GmbH, which occupies a position within the European alkali phenolic segment, and Mitsubishi Chemical Corporation, which anchors Asian demand through furan resin expertise. These named entities represent archetypal competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Kao Corporation |
| Huntsman Corporation |
| ASK Chemicals GmbH |
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| BASF SE |
| Foseco (Vesuvius Group) |
| Mitsubishi Chemical Corporation |
| Imerys S.A. |
| Others |
Supply Flow & Price Mechanics
Cold box polyurethane system adoption across German and Japanese automotive foundries simultaneously compresses per-unit chemistry costs and concentrates specification authority among regional formulators with certified emissions documentation. This production-method transition rewards suppliers with backward integration into formaldehyde-free resin precursors while penalizing distributors dependent on spot-market phenolic feedstocks.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent spot orders for REACH-compliant phenolic alternatives from contracted annual volumes of conventional furan systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic delivery cost differentials. Price erosion runs through economy-tier water-soluble binders as Chinese provincial foundries absorb margin compression to maintain export competitiveness. Heavy machinery casting operations in Hebei province exhibit highest price sensitivity, while aerospace ceramic shell procurement in France demonstrates lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
China's GB standards on industrial emissions and domestic content requirements reshape sourcing patterns for European binder suppliers seeking Hebei and Shandong market access. Raw material dependencies center on phenol derivatives from South Korea, formaldehyde precursors from Germany, and lignin feedstocks from Nordic pulp operations. Single-source vulnerability concentrates in acid catalyst supply for cold box systems, where Japanese and Belgian producers dominate technical-grade manufacturing. Distribution runs through captive supply chains serving integrated foundry clusters, with spot-market distributors losing share to direct OEM contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with integrated R&D and captive foundry relationships, as REACH authorization timelines and EPA air toxics compliance costs force sub-scale formulators into distressed exit scenarios.
For Market Incumbents: Hedge against silicate-based displacement by securing lignin-derived resin supply agreements with Nordic pulp processors before EU Green Deal funding channels close to late entrants. Deepen backward integration into acid catalyst production to reduce Belgian and Japanese supplier dependency. Prioritize certification investment for cradle-to-gate carbon accounting to meet Stuttgart and Nagoya OEM sustainability team specifications. For New Entrants and Emerging Players: EPA air toxics standards in the United States open a window for regional formulators offering urethane cold box reformulation services to Michigan and Ohio foundries facing compressed compliance timelines. Target aftermarket sand reclamation chemistry in France and Germany where tightening waste directives concentrate disposal cost pressure. Pursue joint development agreements with digital foundries expanding binder jetting capacity in Aichi Prefecture to secure technology licensing revenue without capital-intensive resin manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking European automotive specification authority. Long-term viability favors targets with demonstrated ECHA pre-registration dossiers and active pilot programs for geopolymer alternatives. Watch for inflection when German OEM procurement departments mandate unbundled chemical supply contracts with certified emissions documentation as standard tender requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Lignin-derived resin sourcing secures EU Green Deal funding eligibility for core production. |
| Hybrid Curing Process Development | Stuttgart foundries pilot silicate-phenolic systems integrating emissions reduction with cold box infrastructure. |
| 3D Printing Binder Jetting Licensing | Technology transfer agreements with Nagoya digital foundries capture fastest-expanding segment growth. |
| Aftermarket Reclamation Service Buildout | Sand chemistry recovery operations capture value from French foundries under tightening waste directives. |
| Regional Formulator Certification Investment | Carbon accounting accreditation meets Baden-Württemberg OEM sustainability team procurement mandates. |
Methodological Framework
Document review covered ECHA substance evaluation dossiers, EPA air toxics standard comment filings, and METI industrial decarbonization program disclosures, complemented by interviews with foundry plant managers, OEM procurement leads, resin R&D directors, and sand reclamation service operators. Secondary validation drew from customs trade data, Cefic chemical industry reports, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates across organic, inorganic, and synthetic binder chemistry platforms.
Output modeling generated product-level, application-specific, and technology-disaggregated forecasts across the projection horizon. Segmentation dimensions included binder chemistry family, curing methodology, end-use casting process, and regional regulatory cluster. CAGRs derived from regression analysis against automotive production indices, foundry investment cycles, and emissions compliance timeline shocks. Industry-specific inputs incorporated REACH authorization procedure progress, GB standard implementation schedules, and cold box equipment installation rates.
Caveats apply where ECHA substance evaluation timeline acceleration, EPA enforcement discretion shifts, or Chinese dual carbon goal recalibration could materially shift the outlook for phenolic versus inorganic binder substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Sol-Gel Products Market