
 Global Electrolytic Copper Foil Market | 2026-2036
Global Electrolytic Copper Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrolytic Copper Foil Market Analysis
Project finance tied to battery gigafactory buildouts is reshaping which electrolytic copper foil suppliers can secure long-term offtake contracts. Mitsui Mining & Smelting Co., Ltd. leverages captive copper smelting to anchor its foil cost structure against raw material volatility. ILJIN Materials Co., Ltd. specializes in ultra-thin foil geometries for high-energy-density cells, competing primarily in South Korean and Chinese battery supply chains. Kingboard Copper Foil Holdings Limited controls substantial PCB-oriented foil capacity in Guangdong Province, extending its geographic dominance across Asia-Pacific electronics manufacturing.
Electrolytic copper foil is a rolled or electrodeposited copper sheet, typically manufactured through acid copper electroplating onto rotating titanium drums, with thicknesses ranging from one micron to seventy microns depending on end-use performance requirements. Its primary commercial purpose is to serve as conductive current collectors in lithium-ion battery anodes and as signal layers in printed circuit boards. Standard foil and thick foil categories remain mature margin pools serving established PCB and capacitor applications, while ultra-thin foil segments are capturing the fastest growth trajectory as battery cell energy density targets intensify. The battery application dimension now commands disproportionate capital allocation from producers, with electromagnetic shielding and traditional capacitor uses occupying stable but slower-expanding demand channels.
China's SAMR enforces GB standards governing copper foil purity and dimensional tolerances for domestic battery supply chains, while the EU's Battery Regulation through ECHA mandates recycled content disclosure and carbon footprint labeling that directly shapes import qualification criteria for Asian foil exporters. Japan's METI coordinates national R&D consortia advancing next-generation foil substrates through PMDA-aligned materials science programs. Stakeholders must monitor how divergent purity certifications between Chinese GB standards and European REACH compliance protocols will influence cross-border qualification timelines and capital deployment decisions.
Market Dynamics
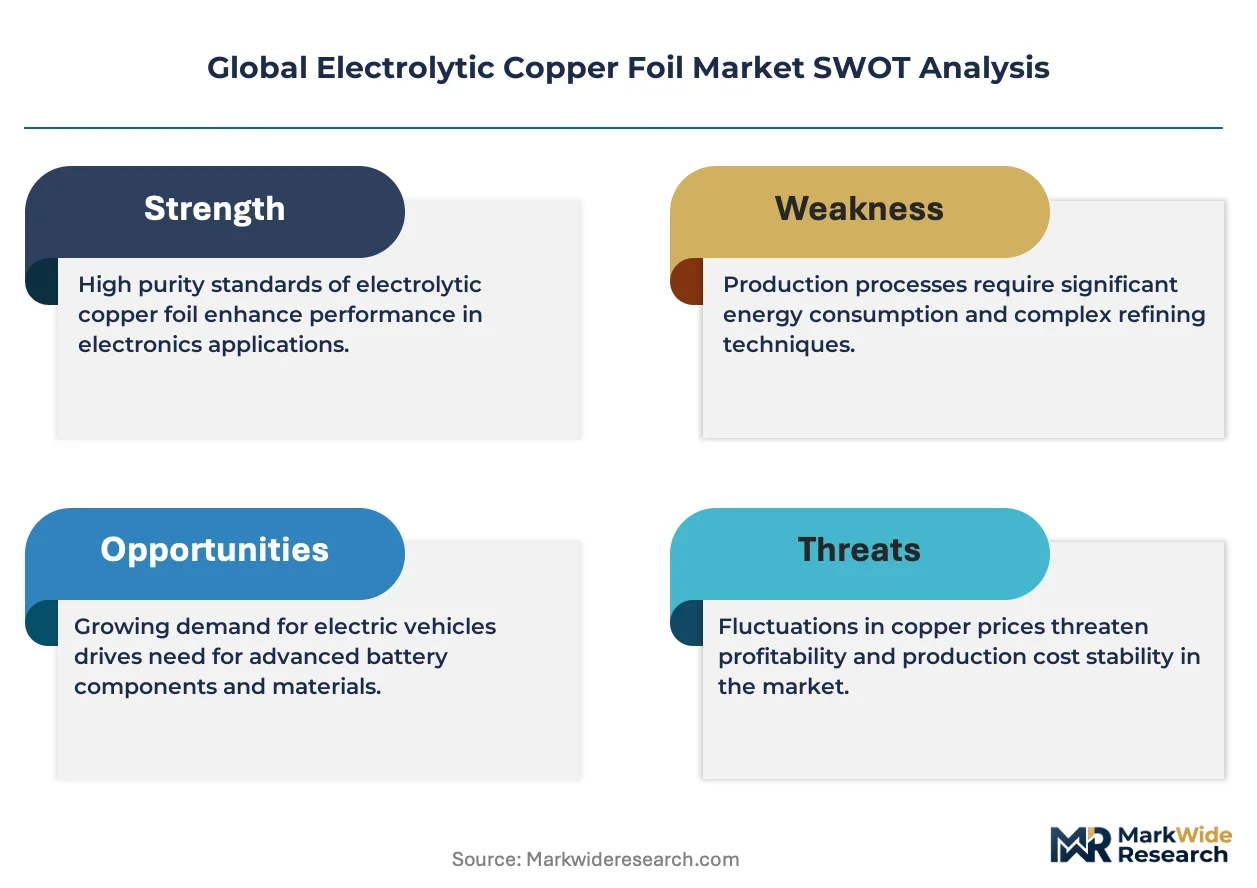
Ultra-thin foil specifications for high-nickel battery chemistries are compressing manufacturing tolerances and forcing capital retooling across electrodeposition lines. This dimensional race concentrates procurement power among cell makers capable of certifying sub-six-micron geometries at scale.
Growth Catalysts
- EU Battery Regulation carbon footprint mandates:ECHA's recycled content disclosure rules are accelerating qualification of closed-loop copper recovery systems among Asian foil exporters seeking European battery supply chain access.
- High-energy-density cell architectures:Silicon-anode chemistries from South Korean and Chinese manufacturers demand thinner current collectors to offset volumetric expansion, pulling ultra-thin foil capacity expansion.
- Shenzhen-Gumi-Nagoya battery cluster concentration:Geographic clustering of gigafactory buildouts enables just-in-time foil delivery logistics and reduces working capital requirements for anode material integrators.
Market Restraints
- Copper cathode price volatility:London Metal Exchange copper price swings transmit directly into foil cost structures, compressing margins for non-integrated producers lacking captive smelting capacity.
- East Asian supply concentration:Over three-quarters of ultra-thin foil production capacity sits within China and South Korea, creating single-source vulnerability for European and North American battery manufacturers.
- Electrodeposition thickness floor:Physical limits of acid copper plating onto titanium drums constrain sub-four-micron foil yields, capping energy density gains for next-generation solid-state designs.
Strategic Opportunities
- North American battery supply chain localization:IRA domestic content incentives are creating qualification pathways for foil producers establishing electrodeposition capacity near Detroit and Nevada gigafactory sites.
- Solid-state battery substrate compatibility:Lithium-metal anode architectures require modified foil surface treatments, opening technical differentiation opportunities beyond commodity current collector supply.
- Direct-to-cellmaker digital procurement platforms:B2B marketplaces for spot foil purchasing are disintermediating traditional distributor networks and compressing quote-to-delivery cycles for mid-tier battery manufacturers.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in acid copper bath chemistry and drum surface engineering commands premium compensation, constraining production line expansion timelines.
- Cross-certification timeline compression:Divergent GB standard purity protocols and REACH compliance documentation requirements force parallel qualification tracks, extending customer onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrolytic Copper Foil Market |
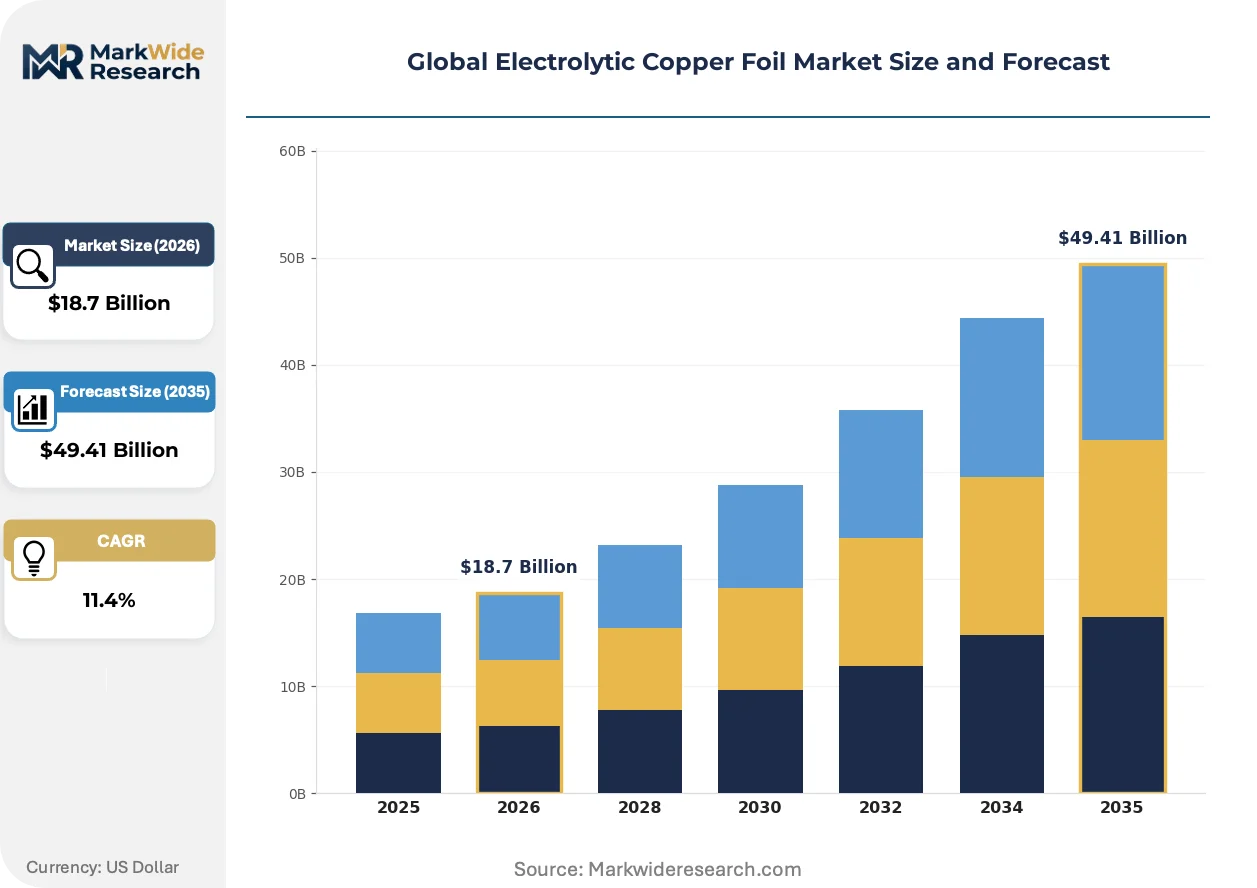
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Foil, High-Quality Foil, Ultra-Thin Foil, Thick Foil End User: Consumer Electronics, Automotive, Renewable Energy, Telecommunications Application: Battery, PCB, Capacitor, Electromagnetic Shielding Thickness: 1um, 5um, 10um, 20um |
| Companies Covered | Chang Chun Group, Kingboard Copper Foil Holdings Limited, Mitsui Mining & Smelting Co., Ltd., ILJIN Materials Co., Ltd., Circuit Foil Luxembourg, Furukawa Electric Co., Ltd., Nan Ya Plastics Corporation, LS Mtron Ltd., JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrolytic Copper Foil Market Emerging Trajectories
Electrodeposition process control is virtualizing through sensor arrays and machine learning, compressing defect detection cycles from hours to seconds. This shift is redrawing competitive boundaries between integrated smelter-foil producers and standalone electrodeposition specialists.
Advanced surface treatment chemistries are virtualizing the interface between copper foil and silicon-active anode materials. Battery cell manufacturers in South Korea are adopting plasma-enhanced coating protocols to reduce delamination failure rates. This convergence is virtualizing traditional commodity foil margins into performance-premium pricing tiers tied to cycle life guarantees.
ECHA's Battery Regulation recycled content disclosure mandates are forcing supply chain documentation upgrades across Asian foil exporters. The regulation requires mass-balance accounting for copper scrap inputs, compelling electrodeposition plants to integrate with certified recycler networks. European battery manufacturers are responding by pre-qualifying foil suppliers with verified closed-loop material flows ahead of 2027 enforcement deadlines.
Consolidated procurement by top-five cell makers is compressing supplier negotiation leverage and standardizing foil specifications across competing battery platforms. Long-term offtake contracts with minimum volume guarantees are displacing spot market purchases for ultra-thin foil categories. This concentration is most visible in China's Yangtze River Delta, where CATL and BYD procurement teams coordinate quarterly price benchmarks with approved foil vendor pools.
Global Electrolytic Copper Foil Market Segmentation
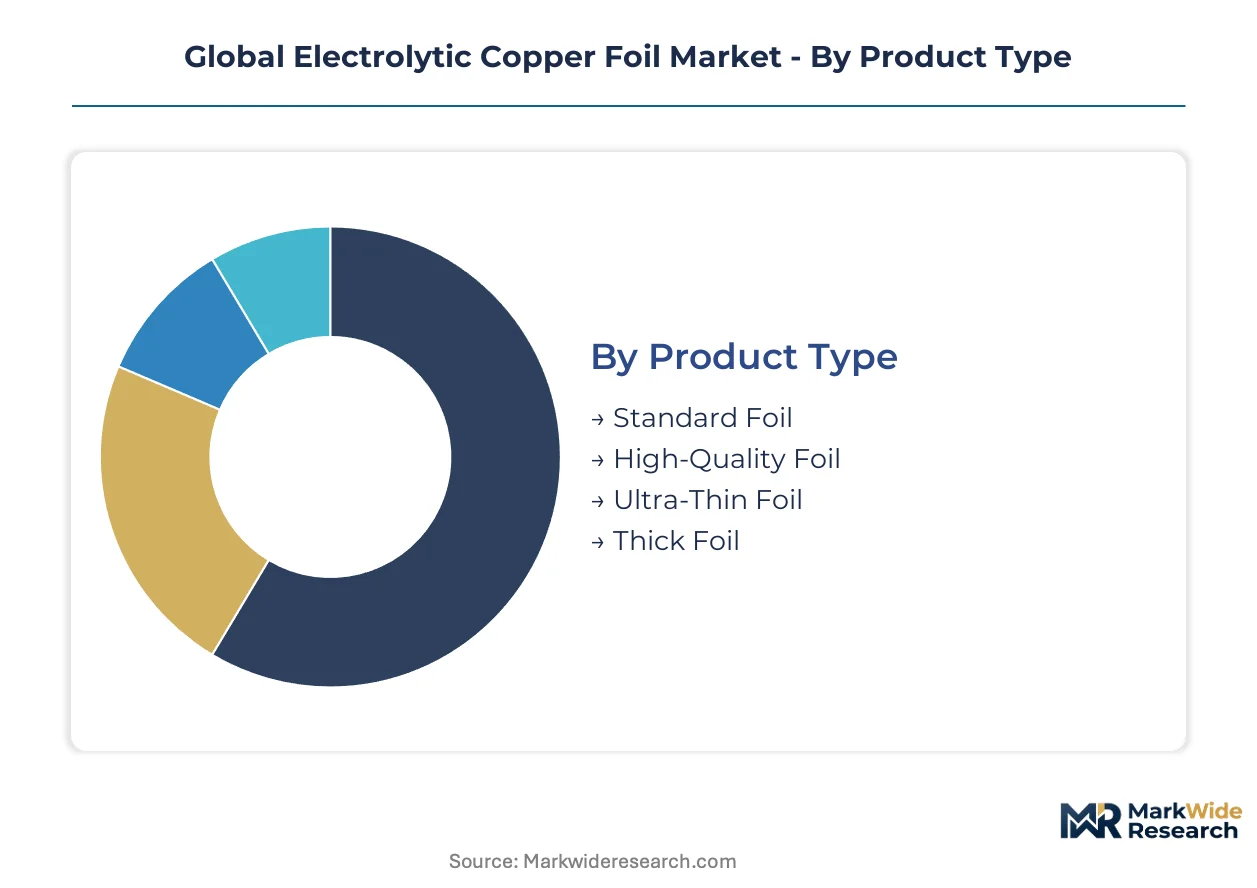
Segmentation in electrolytic copper foil reveals how technology specialization and end-use performance requirements create distinct margin pools. Product thickness and surface treatment specifications determine which suppliers qualify for battery versus electronics applications, while procurement concentration among top cell makers compresses negotiation leverage across tiers.
Product Type:
Thickness specifications divide the market into performance tiers with divergent capital intensity and qualification barriers.
- Ultra-Thin Foil:Sub-six-micron electrodeposited sheets serve lithium-ion battery anode current collectors where silicon-anode chemistries from South Korean and Chinese manufacturers demand maximum volumetric efficiency. Shenzhen and Gumi gigafactory clusters concentrate procurement of these geometries, with acid copper bath chemistry expertise constraining qualified supplier counts.
- Standard Foil:Mid-range thicknesses dominate printed circuit board signal layers across Guangdong Province electronics manufacturing corridors. Mature margin pools here reflect established JIS and GB certification requirements rather than technology differentiation.
- High-Quality Foil:Enhanced surface roughness profiles target high-frequency PCB applications and premium capacitor electrodes.
- Thick Foil:Heavy-gauge electrodeposited copper serves power electronics and electromagnetic shielding with stable but slower-expanding demand channels.
Standard foil holds installed capacity. Ultra-thin foil is rotating up the share rankings.
End User:
Customer concentration patterns concentrate pricing power among battery-scale buyers versus fragmented electronics OEMs.
- Automotive:Electric vehicle cell manufacturers in China's Yangtze River Delta and South Korea's Gumi region drive qualification of sub-six-micron geometries at volume. IRA domestic content incentives are creating North American qualification pathways near Detroit and Nevada production sites.
- Consumer Electronics:Smartphone and laptop battery demand pulls ultra-thin foil through Shenzhen-area pack integrators, with specifications standardizing across competing OEM platforms.
- Renewable Energy:Grid-scale storage installations in China and Europe require thick foil for power conditioning equipment.
- Telecommunications:5G infrastructure PCB demand concentrates in Nagoya and Taipei manufacturing clusters.
Automotive commands disproportionate capital allocation from producers. Consumer electronics maintains volume stability.
Application:
Functional use cases determine surface treatment requirements and certification complexity.
- Battery:Anode current collectors require plasma-enhanced surface coatings to reduce delamination failure rates in silicon-anode cells. ECHA's Battery Regulation recycled content disclosure mandates are forcing mass-balance accounting upgrades across Asian electrodeposition plants.
- PCB:Signal layer applications in Guangdong and Nagoya electronics corridors favor mature foil geometries with established GB and JIS certification tracks.
- Capacitor:Energy storage components use etched foil with high surface area-to-volume ratios.
- Electromagnetic Shielding:Conductive barriers for electronic enclosures occupy stable demand channels with limited technology differentiation.
PCB holds installed capacity. Battery is climbing the fastest.
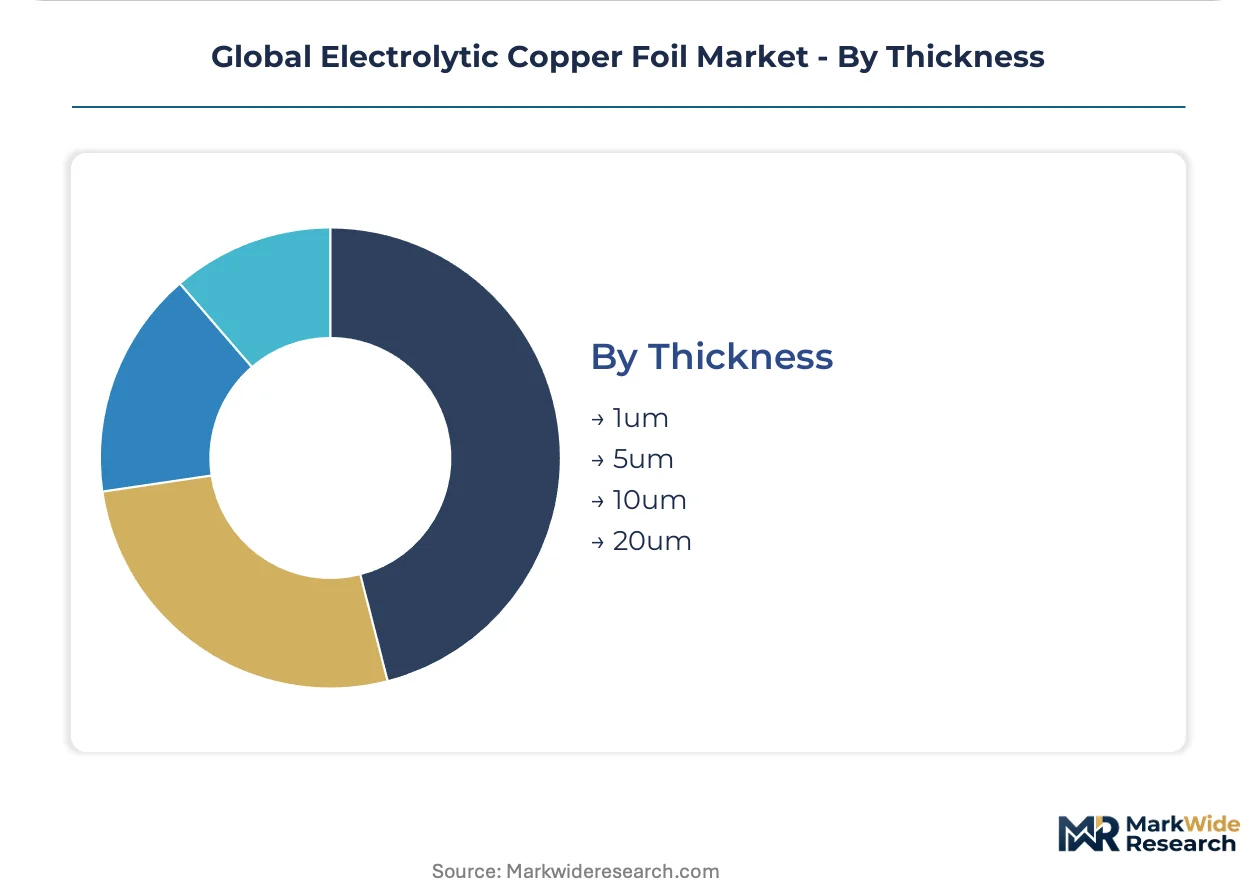
Thickness:
Dimensional specifications map directly to energy density targets and manufacturing yield constraints.
- 5um:The practical floor for high-volume acid copper electrodeposition onto titanium drums, serving current-generation high-nickel battery chemistries from CATL and BYD supply chains. Physical plating limits constrain sub-four-micron yields for solid-state designs.
- 1um:Experimental geometries for next-generation lithium-metal anode architectures requiring modified surface treatments beyond commodity current collector supply.
- 10um:Standard PCB signal layer thickness with mature electrodeposition process control.
- 20um:Power electronics and capacitor applications with relaxed dimensional tolerances.
10um holds installed capacity. 5um is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese electrodeposition plants command pricing leverage through captive smelting integration, while European battery manufacturers absorb premium qualification costs to secure ECHA-compliant supply chains. This asymmetry concentrates procurement power in Shenzhen and Gumi clusters while forcing dispersion investments near Detroit and Nevada.
China
CATL and BYD procurement teams coordinate quarterly price benchmarks with approved foil vendor pools across the Yangtze River Delta. SAMR enforces GB standards governing copper foil purity and dimensional tolerances for domestic battery supply chains. Shenzhen-area pack integrators pull ultra-thin foil through just-in-time delivery logistics serving consumer electronics OEMs.
South Korea
Silicon-anode chemistries from cell manufacturers demand thinner current collectors to offset volumetric expansion, pulling capacity toward sub-six-micron geometries. The national industrial regulator coordinates R&D consortia advancing next-generation foil substrates through materials science programs. Gumi's gigafactory cluster concentrates procurement power among cell makers certifying ultra-thin specifications at scale.
Japan
High-frequency PCB applications in Nagoya manufacturing corridors favor mature foil geometries with established JIS certification tracks. METI aligns national materials programs with PMDA-coordinated substrate development for solid-state battery architectures. Tokyo-based trading houses intermediate long-term offtake contracts between domestic electrodeposition specialists and Southeast Asian battery manufacturers.
United States
IRA domestic content incentives create qualification pathways for foil producers establishing electrodeposition capacity near Detroit and Nevada gigafactory sites. EPA and NHTSA compliance documentation requirements extend customer onboarding cycles for Asian exporters seeking North American supply chain access. Michigan-based automotive cell manufacturers pre-qualify suppliers with verified material flow documentation ahead of production ramp schedules.
Germany
ECHA's Battery Regulation recycled content disclosure mandates force mass-balance accounting upgrades across Asian electrodeposition plants serving European battery manufacturers. The KBA coordinates vehicle-level certification requirements that cascade into foil purity specifications for anode current collectors. Stuttgart-area automotive engineering clusters demand sub-six-micron geometries with carbon footprint labeling compliant with EU Green Deal implementation timelines.
Global Electrolytic Copper Foil Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream feeding standardized geometries into captive supply chains. The vendor base stratifies across integrated smelter-foil producers, standalone electrodeposition specialists, and diversified materials conglomerates with cross-divisional copper exposure. Three archetypes dominate: backward-integrated mining-smelting operators, technology-focused thin-foil specialists, and PCB-anchored diversified producers. Competitive moves concentrate on capacity expansion near battery cluster zones and strategic partnerships locking long-term offtake with top-five cell makers.
Among Asia-Pacific-based operators, Mitsui Mining & Smelting Co., Ltd. and Kingboard Copper Foil Holdings Limited occupy positions reflecting divergent integration strategies, while ILJIN Materials Co., Ltd. exemplifies the thin-foil specialist archetype competing in high-energy-density supply chains. These three entities represent distinct competitive vectors: captive smelting cost control, geographic dominance across electronics manufacturing corridors, and technology specialization for silicon-anode compatibility. European qualification requirements and North American localization incentives are reshaping which archetypes can secure cross-regional supply contracts.
| Leading Market Players |
|---|
| Chang Chun Group |
| Kingboard Copper Foil Holdings Limited |
| Mitsui Mining & Smelting Co., Ltd. |
| ILJIN Materials Co., Ltd. |
| Circuit Foil Luxembourg |
| Furukawa Electric Co., Ltd. |
| Nan Ya Plastics Corporation |
| LS Mtron Ltd. |
| JX Nippon Mining & Metals Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals in China's Guangdong electrodeposition corridor are compressing spot pricing for standard foil grades while tightening ultra-thin specifications command premium stability. This utilization divergence rewards integrated producers with captive smelting and punishes standalone operators exposed to London Metal Exchange volatility.
Pricing Analysis
The customization-premium spread between plasma-enhanced surface-treated foil and commodity electrodeposited sheet runs three-to-one across battery supply chains. Contract-based long-term offtake dominates procurement for sub-six-micron geometries, with price differentiation anchored in GB standard certification tiers and silicon-anode compatibility guarantees. Cost compression in standard PCB foil is intensifying because Chinese capacity additions outpace demand growth in mature electronics corridors. Automotive cell manufacturers exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics pack integrators in Shenzhen drive aggressive spot-market negotiation.
Supply Chain Analysis
Extended payment terms from South Korean battery manufacturers are forcing electrodeposition specialists to access supply-chain finance facilities for working capital coverage. Raw material flows draw from Chilean copper concentrate, Australian cathode, and Chinese sulfuric acid reagents. Geographic supply concentration in China, South Korea, and Japan creates single-source vulnerability for European and North American battery manufacturers seeking ECHA-compliant qualification. Distribution runs through just-in-time logistics corridors linking Gumi and Nagoya gigafactory clusters with approved vendor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to battery gigafactory buildout cadence in North America and Europe. Capital deployment timing hinges on IRA domestic content incentive qualification windows and EU Battery Regulation enforcement milestones.
For Market Incumbents: Pre-empt margin erosion in standard foil by accelerating backward integration into certified copper scrap recovery networks ahead of ECHA mass-balance mandates. Lock long-term offtake with Detroit-area automotive cell manufacturers before electrodeposition capacity localizes under IRA incentives. Defensive consolidation around plasma-enhanced surface treatment IP separates premium-tier suppliers from commodity current collector competition. For New Entrants and Emerging Players: North American underpenetration in ultra-thin foil qualification creates white-space opportunity near Nevada and Michigan gigafactory sites. Solid-state battery substrate development offers technical differentiation entry path beyond commodity supply. Direct procurement platform partnerships with mid-tier cell manufacturers bypass entrenched distributor relationships in Asian supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-six-micron electrodeposition capacity due to titanium drum surface engineering and acid bath chemistry specialization. Five-to-ten year viability favors acquisition targets with verified closed-loop material flows and dual GB-REACH certification tracks. Monitor South Korean silicon-anode adoption rates as inflection signal for ultra-thin foil demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Smelting | Mitsui Mining's cost structure insulation demonstrates margin defense against LME copper volatility. |
| Plasma-Enhanced Surface Treatment Scale-Up | ILJIN Materials' silicon-anode compatibility commands performance-premium pricing in South Korean supply chains. |
| North American Electrodeposition Capacity Buildout | IRA domestic content incentives are reshaping supplier qualification near Detroit and Nevada gigafactory clusters. |
| Closed-Loop Copper Recovery Certification | ECHA mass-balance mandates force electrodeposition plant integration with verified recycler networks. |
| Direct-to-Cellmaker Digital Procurement Platform | B2B marketplaces disintermediate distributor networks and compress quote-to-delivery cycles for mid-tier manufacturers. |
Methodological Framework
Cross-validation between primary interviews with electrodeposition plant managers and secondary trade data anchors the qualitative findings. Battery cell procurement executives, acid copper bath chemists, titanium drum surface engineers, and ECHA compliance officers provided operational perspective. Bottom-up capacity assessments triangulated against top-down demand modeling from customs records, SEC filings by listed foil producers, and Yangtze River Delta industrial park development databases.
Calibration against historical capacity utilization patterns and announced expansion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include thickness specification tiers, surface treatment categories, end-use application clusters, and regional regulatory compliance tracks. CAGRs derived from supply-demand balance iterations incorporating silicon-anode chemistry adoption curves and solid-state battery substrate development timelines.
Macroeconomic conditions sit as an overlay; deviation in London Metal Exchange copper pricing, battery cell production ramp schedules, or EU Battery Regulation enforcement timing would shift the trajectory. Forecasts incorporate documented assumptions regarding qualification timeline compression and cross-certification burden. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Silver-Platinum Paste Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Stainless Steel Market
Metals
US Ferrochrome Market
Metals
Stainless Steel Round Bar Market
Metals
Aluminum Welding Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Electrodeposited Copper Foil Market
Metals
Transition Metals Market
Metals
Nickel Foam Market
Metals
Global Titanium Metal Market
Metals
Ore Metals Market
Metals
Cerium Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Metal Finishing Market
Metals
Beryllium Copper Plate Market