
 Manganese Market | 2026-2036
Manganese Market Size, Share, and Industry Trends Forecast 2026-2036
Manganese Market Analysis
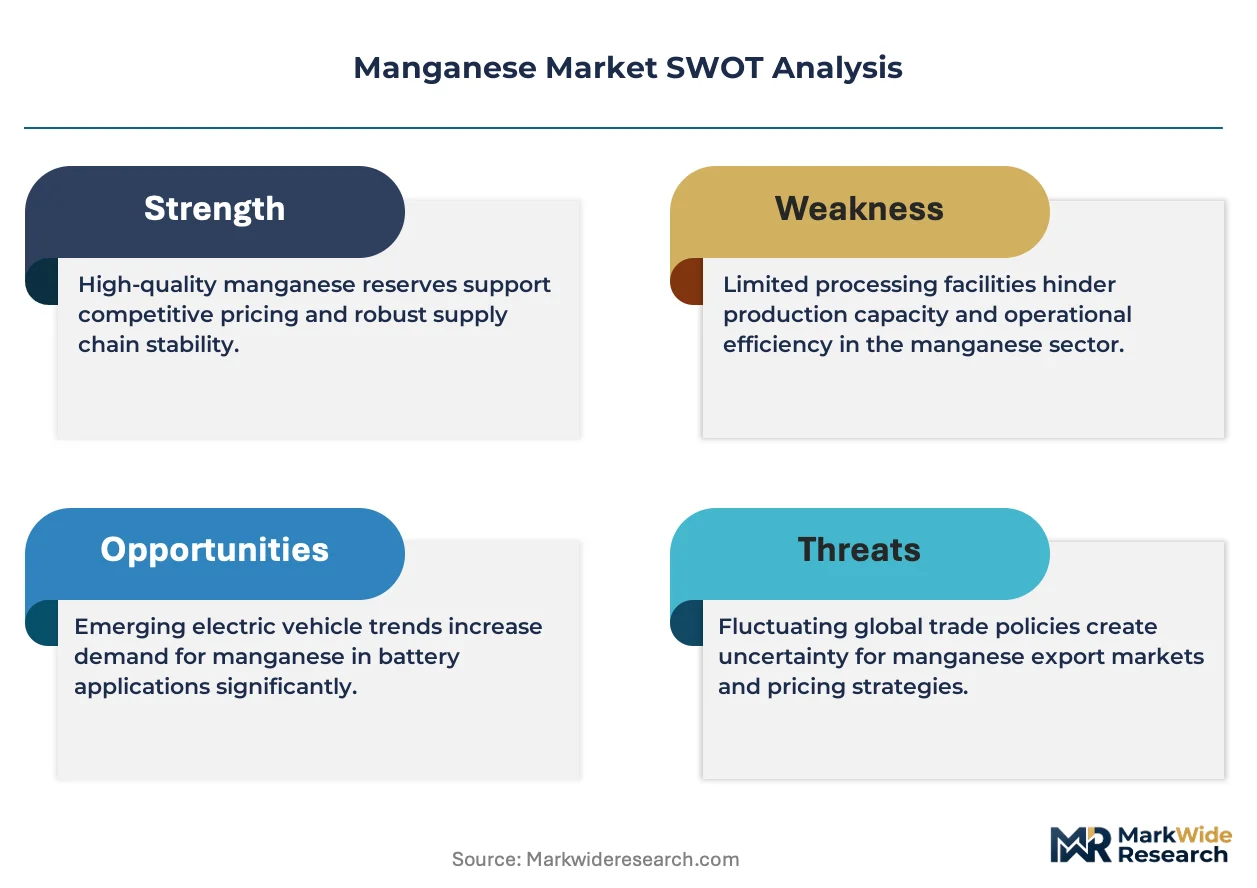
Project finance tied to offtake agreements is fragmenting competitive access to manganese ore reserves. Anglo American leverages captive logistics infrastructure to sustain cost advantages across its South African operations. South32 anchors its position through integrated port-to-mine rail networks serving Asian steel mills. Vale competes via deep-sea port access and high-grade lump ore from its Brazilian Carajás complex.
Manganese is a transition metal with atomic number 25, typically refined to 99.7% purity for electrolytic applications and alloyed with iron to improve tensile strength and workability in steel production. Silicomanganese dominates volume flows into steel manufacturing, where it functions as a deoxidizer and sulfur fixer in long-product and flat-rolled mills. Battery-grade manganese sulfate is the fastest-expanding segment, as cathode-active-material plants in South Korea and Japan qualify high-purity specifications for nickel-manganese-cobalt formulations. Technical-grade powder retains mature, price-sensitive demand from chemical processing and agricultural micronutrient applications.
South Africa's Department of Mineral Resources and Energy enforces mining charter requirements that shape local beneficiation mandates and export licensing conditions. China's Ministry of Ecology and Environment applies emissions intensity caps on ferroalloy smelters through its dual carbon policy framework. The EU Battery Regulation mandates recycled-content thresholds and supply-chain due diligence that will restructure qualification criteria for material entering European cell plants. Stakeholders must track how carbon-border adjustments and evolving purity specifications redefine contract terms between miners and cathode producers.
Market Dynamics
Battery-grade manganese qualification timelines are compressing as cathode producers accelerate supplier audits, while South Africa's beneficiation mandates and China's dual carbon caps simultaneously reshape cost structures across mining and smelting operations.
Growth Catalysts
- EU Battery Regulation:Recycled-content thresholds and due diligence mandates are forcing cathode plants to qualify new sulfate suppliers, expanding the addressable supplier base for compliant miners.
- Nickel-manganese-cobalt cathode chemistry:OEMs are locking in high-purity manganese sulfate contracts to secure non-Chinese supply chains for mid-range electric vehicle platforms.
- Groote Eylandt ore concentration:Australia's high-grade oxide reserves are attracting direct shipping ore investments that bypass traditional ferroalloy processing steps.
Market Restraints
- Power cost volatility:South African smelters face Eskom tariff escalations and load-shedding that erode silicomanganese margin structures.
- Seaborne freight concentration:Cape Town and Port Elizabeth bulk terminals create single-point bottlenecks for Northern Cape ore exports to Asian steel mills.
- Sulfuric acid supply tightness:Manganese sulfate purification depends on acid availability from copper smelter off-gas, linking battery-grade output to unrelated mining cycles.
Strategic Opportunities
- Indonesia's nickel-cobalt-manganese integration:Vertically integrated HPAL projects are creating captive sulfate demand that bypasses traditional merchant market structures.
- Direct recycling feedstock:Spent lithium-ion black mass is emerging as an alternative manganese source for cathode remanufacturing, reducing primary ore dependence.
- US Inflation Reduction Act:Critical mineral domestic content bonuses are incentivizing North American sulfate purification investments to serve Michigan and Tennessee cell plants.
Industry Challenges
- Metallurgical testwork bottlenecks:Cathode producer qualification protocols require 18-24 month pilot campaigns that strain junior miners' working capital.
- ISO 14064 carbon accounting:Scope 3 emissions verification for mine-to-cathode supply chains demands new data infrastructure that most traders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manganese Market |
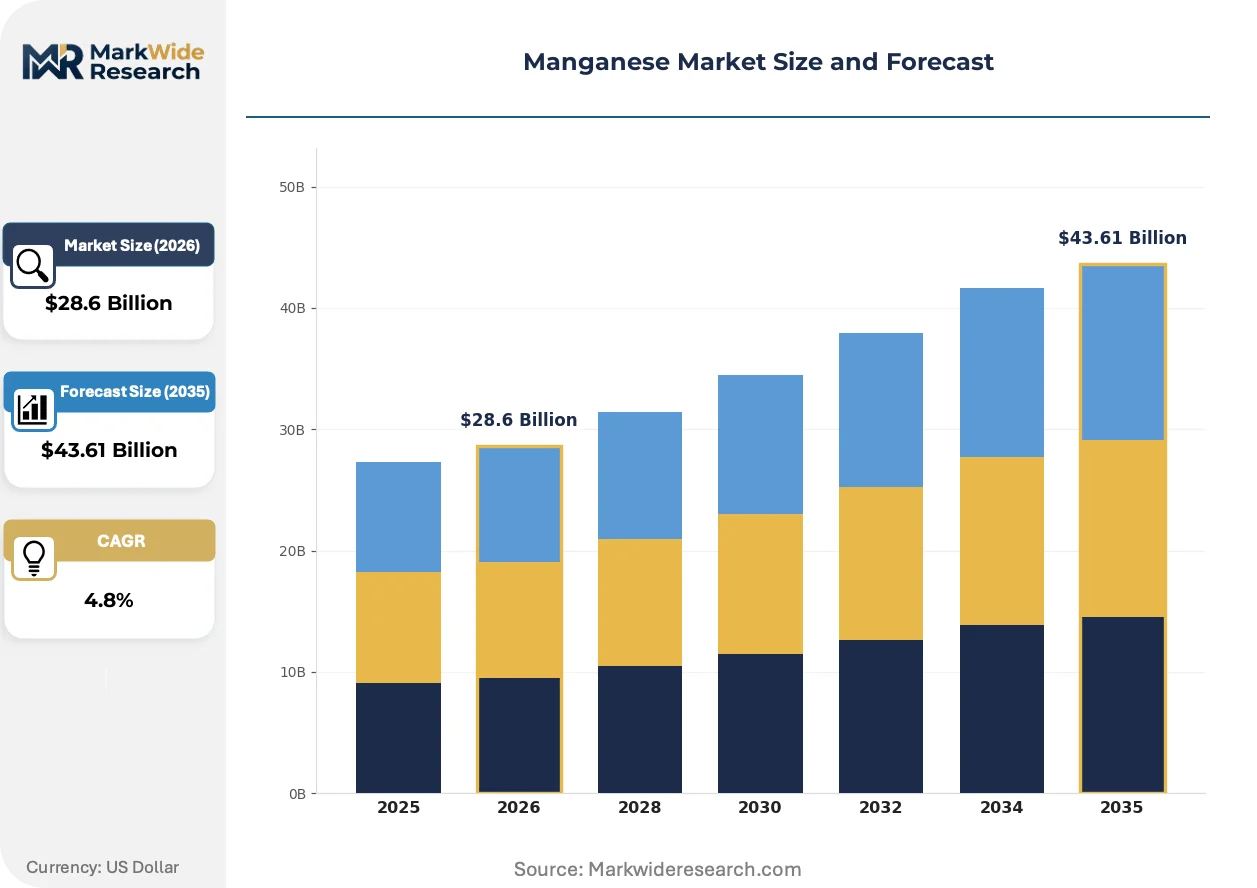
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Manganese Metal, Manganese Dioxide, Manganese Sulfate, Silicomanganese End Use Industry: Steel Manufacturing, Battery Production, Chemical Processing, Agriculture Form: Powder, Granules, Pellets, Lump Grade: High Purity, Technical Grade, Battery Grade, Feed Grade |
| Companies Covered | Anglo American, Consolidated Minerals, South32, Lhg Mining, Vale, Eramet, MOIL, Buritirama Mining, Jupiter Mines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manganese Market Emerging Trajectories
Electrolytic metal production and sulfate purification are converging with carbon accounting automation, while procurement teams rewrite supplier scorecards to weight emissions intensity alongside assay consistency.
Solvent extraction-electrowinning circuits for battery-grade manganese sulfate are collapsing the traditional pyrometallurgical intermediate steps that fed stainless steel mills. Korean cathode material plants are adopting these hydrometallurgical flowsheets to meet automaker carbon disclosure requirements. The technology is collapsing capital recovery periods for greenfield projects by eliminating sinter plant and submerged arc furnace investments.
China's Ministry of Ecology and Environment is capping ferroalloy smelter emissions intensity through its dual carbon policy framework, forcing capacity consolidation in Ningxia and Inner Mongolia. Surviving producers must install baghouse upgrades and shift power sourcing to provincial renewable portfolios. Battery-grade sulfate plants in Guangxi are most affected, as they compete for grid allocation with steel and cement sectors.
Long-term offtake contracting is displacing spot market purchasing for high-purity sulfate as cathode producers seek supply security ahead of European cell capacity ramp-ups. Tier-one material plants are locking in five-year fixed-volume agreements with Australian and South African miners, squeezing merchant traders from premium tier supply chains. This pattern is most visible in South Korean procurement offices, which are abandoning quarterly tender processes in favor of direct negotiation.
Manganese Market Segmentation
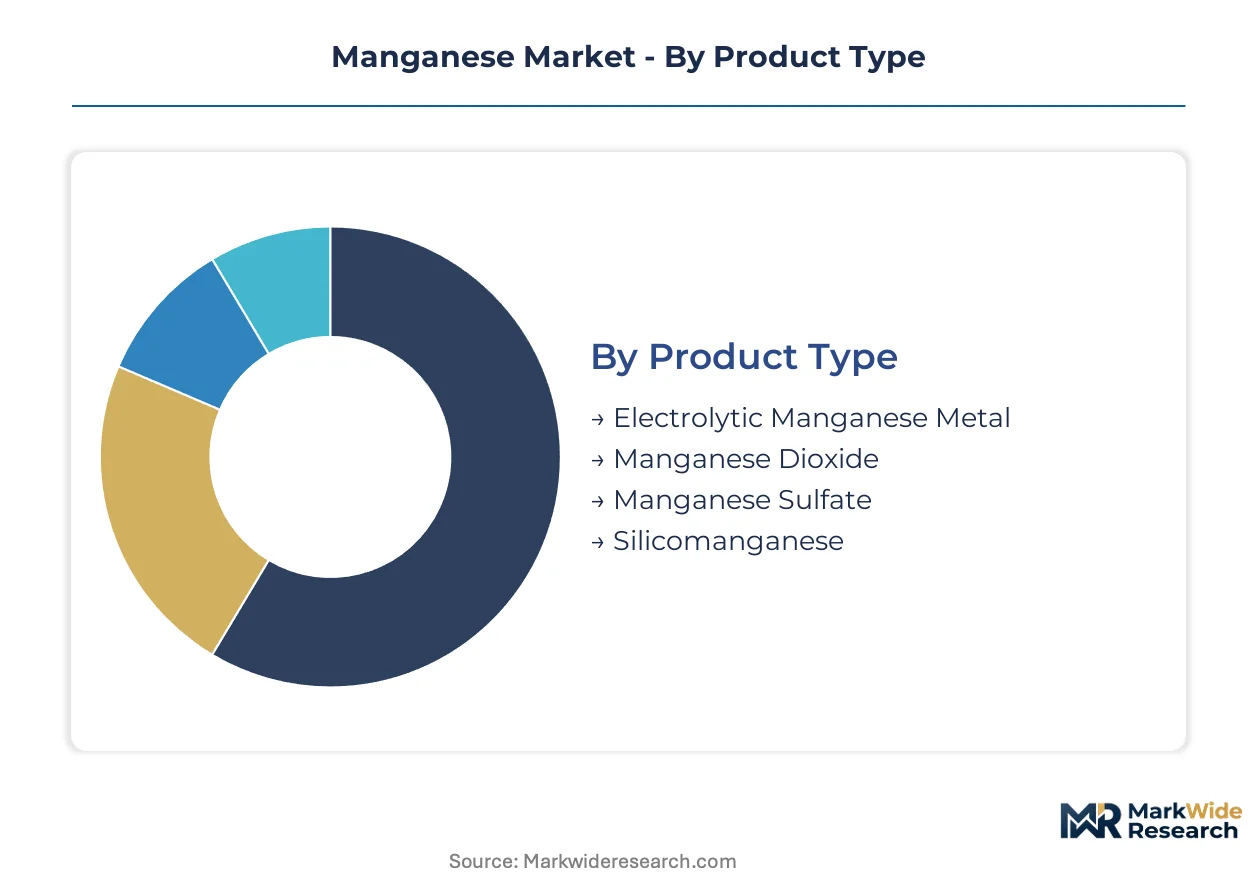
Manganese segmentation reveals divergent margin structures across product tiers. Steel-grade material commands volume dominance but faces compressed returns from energy-intensive smelting. Battery-grade sulfate attracts premium pricing tied to cathode qualification timelines and carbon-accounting compliance.
Product Type:
After-sales service intensity varies sharply across manganese product tiers, with battery-grade sulfate demanding continuous technical support for cathode qualification while silicomanganese requires minimal post-sale engagement beyond logistics coordination.
- Electrolytic Manganese Metal:Refined to 99.7% purity through sulfate electrolysis, this form serves specialty stainless steel mills and aluminum alloys. Demand concentrates in Japanese specialty steel producers seeking precise sulfur control in austenitic grades. Carbon-border adjustments from the EU Battery Regulation are redirecting procurement toward South African sources with verified Scope 3 data.
- Manganese Dioxide:Synthetic and natural variants power primary alkaline batteries and water treatment catalysts. Dry cell manufacturers in Indonesia and Vietnam dominate consumption, though lithium-ion substitution is eroding growth in consumer electronics. The material retains defensive demand from municipal water infrastructure upgrades across Southeast Asia.
- Manganese Sulfate:High-purity monohydrate and tetrahydrate crystals serve nickel-manganese-cobalt cathode precursors. Korean and Japanese material plants are locking in five-year offtake agreements to secure non-Chinese supply chains.
- Silicomanganese:Ferroalloy containing 65-68% manganese and 18-25% silicon functions as deoxidizer and desulfurizer in long-product steel mills. Chinese blast furnace operators absorb half of seaborne trade, though domestic ferroalloy smelter consolidation is capping import growth.
By volume, silicomanganese leads. By growth pace, manganese sulfate is ahead.
End Use Industry:
Cost tier stratification separates mature commodity applications from emerging premium segments, with battery production commanding three-to-four-fold price multiples over steel manufacturing on a contained-manganese basis.
- Steel Manufacturing:Long-product and flat-rolled mills consume silicomanganese and ferromanganese for deoxidation and sulfur fixation. Indian integrated steelworks are expanding manganese alloy inventories ahead of infrastructure build-outs. MEE emissions intensity caps on Chinese ferroalloy smelters are reshaping regional supply availability.
- Battery Production:Cathode-active-material plants qualify high-purity sulfate for lithium-ion chemistries. OEMs are auditing Australian and South African miners to meet EU Battery Regulation due diligence mandates.
- Chemical Processing:Technical-grade dioxide and sulfate feed pigment manufacturing, ceramics, and glass decolorization. Brazilian ceramic tile producers anchor Latin American demand.
- Agriculture:Feed-grade oxide and sulfate correct manganese deficiency in cereal and oilseed crops. Australian wheatbelt farmers drive seasonal procurement patterns tied to soil testing cycles.
Steel manufacturing retains volume dominance. Battery production exhibits the steepest expansion trajectory.
Form:
Application requirements dictate physical specifications, with powder forms serving chemical dissolution processes while lump material minimizes handling losses in submerged arc furnace operations.
- Powder:Finely ground material below 150 microns serves chemical synthesis and battery precursor production. Japanese cathode material plants specify narrow particle distributions for consistent dissolution kinetics.
- Granules:Agglomerated fines improve flow characteristics for fertilizer blending and water treatment applications. Southeast Asian compound fertilizer manufacturers prefer this form for mechanical handling compatibility.
- Pellets:Sintered or briquetted material reduces dust generation in electric arc furnace charging. European stainless steel mills are qualifying pelletized feeds to meet workplace exposure limits.
- Lump:Sized ore above 10mm bypasses sintering steps in ferroalloy smelting. Australian Groote Eylandt direct shipping ore commands premium valuations for its high-grade, low-phosphorus chemistry.
Lump material dominates seaborne ore trade. Powder forms are climbing fastest on battery-grade demand.
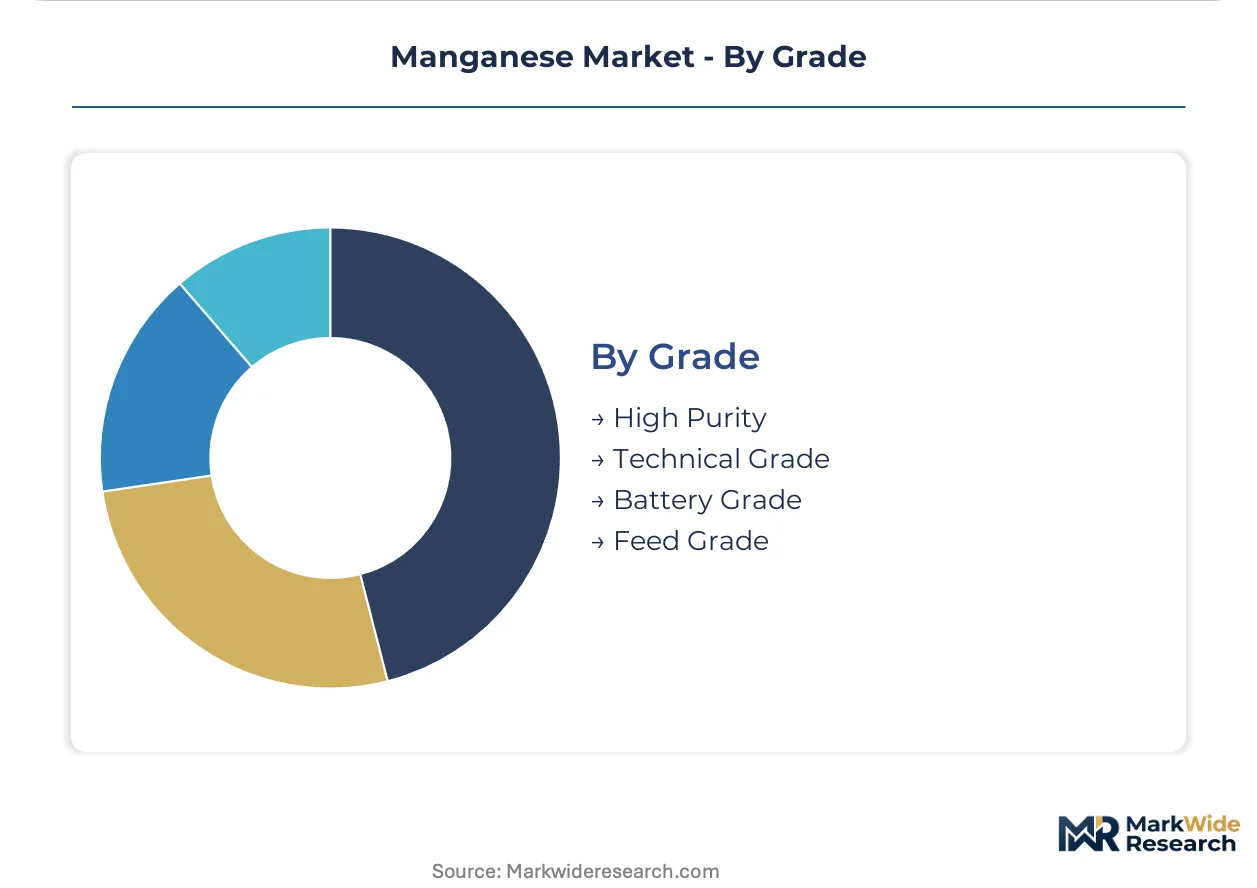
Grade:
Customer type stratification separates specification-intensive cathode producers from price-sensitive commodity buyers, with certification and traceability requirements creating divergent qualification barriers.
- High Purity:Electrolytic metal exceeding 99.9% manganese content serves aerospace alloys and electronics. Specialty steel mills in Germany and Japan absorb limited volumes at substantial premiums.
- Technical Grade:Standardized oxide and sulfate specifications meet industrial chemical and ceramic applications. Price sensitivity limits supplier margins to single-digit percentages.
- Battery Grade:Stringent impurity limits on sodium, potassium, and heavy metals qualify material for cathode production. Korean material plants are rejecting Chinese sulfate that fails updated automaker specifications.
- Feed Grade:Agricultural oxide and sulfate with controlled heavy metal content serves livestock and crop nutrition. Brazilian soybean producers drive seasonal import patterns through Paranaguá port.
Technical grade leads by volume. Battery grade is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across manganese-producing jurisdictions, with ore-rich Southern Hemisphere nations supplying Asian steel mills and battery material plants while import-dependent manufacturing economies compete for sulfate qualification. Freight differentials and carbon-border compliance are redrawing traditional trade corridors.
Australia
Groote Eylandt high-grade oxide exports anchor seaborne supply to Korean and Japanese cathode producers. The country's Clean Energy Finance Corporation directs capital toward mine-site solar arrays that reduce Scope 3 emissions for EU-bound material. Port of Darwin bulk terminals are expanding capacity to bypass traditional Queensland coal port congestion.
South Africa
The Northern Cape mining belt supplies silicomanganese to Indian integrated steelworks and lump ore to Chinese ferroalloy smelters. The Department of Mineral Resources and Energy enforces beneficiation mandates that require local processing before export licensing. Transnet's Sishen-Saldanha rail corridor remains the critical bottleneck for Northern Cape ore reaching Atlantic shipping lanes.
China
Domestic ferroalloy smelters in Ningxia and Inner Mongolia absorb Australian lump ore while Guangxi sulfate plants serve domestic cathode material producers. The Ministry of Ecology and Environment applies dual carbon emissions intensity caps that force capacity consolidation among smaller smelters. Battery-grade sulfate purification clusters concentrate in Guangxi Zhuang Autonomous Region near manganese carbonate reserves.
Brazil
Vale's Carajás complex exports high-grade lump ore through deep-sea port access at São Luís to European stainless steel mills. The National Mining Agency oversees licensing conditions that shape export volumes from Pará state operations. Sinter plant investments in Maranhão are positioning Brazilian material to bypass traditional ferroalloy processing steps for direct shipping ore markets.
South Korea
Cathode-active-material plants in Ochang and Gumi are locking in five-year offtake agreements with Australian and South African miners to secure non-Chinese sulfate supply chains. The Ministry of Trade, Industry and Energy coordinates critical mineral stockpiling programs that buffer against supply disruption. POSCO's integrated steelworks at Pohang retain substantial silicomanganese demand for specialty stainless grades.
Manganese Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ore extraction and concentrate supply. The manganese competitive structure concentrates around diversified mining conglomerates with captive logistics infrastructure, integrated trading houses with offtake financing capabilities, and pure-play explorers seeking qualification with cathode producers. Strategic moves center on securing port-to-mine rail concessions and locking in multi-year sulfate supply agreements ahead of European cell capacity ramp-ups.
Among diversified mining conglomerates, Anglo American and South32 occupy positions that exemplify infrastructure-anchored competitive advantage, while Vale represents the deep-sea port access archetype for high-grade lump ore export. These players anchor tier-one supply chains through integrated logistics networks that junior miners cannot replicate without substantial capital deployment.
| Leading Market Players |
|---|
| Anglo American |
| Consolidated Minerals |
| South32 |
| Lhg Mining |
| Vale |
| Eramet |
| MOIL |
| Buritirama Mining |
| Jupiter Mines |
| Others |
Supply Flow & Price Mechanics
Groote Eylandt's high-grade oxide export capacity anchors battery-grade sulfate premiums, with Australian miners leveraging direct shipping ore chemistry to command price premiums over South African silicomanganese producers facing Eskom tariff escalations. China's dual carbon emissions caps on Ningxia ferroalloy smelters are compressing merchant market margins while Korean cathode plants absorb contracted sulfate volumes at fixed premiums.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting, with battery-grade sulfate commanding premium-mid-economy pricing differentiation based on cathode qualification status and carbon-accounting certification tier. Steel mills exhibit highest price sensitivity on silicomanganese spot purchases, while automaker audit requirements for EU Battery Regulation compliance intensify pricing pressure on unqualified merchant traders lacking Scope 3 verification infrastructure.
Supply Chain Analysis
Export licensing restrictions under South Africa's beneficiation mandates limit Northern Cape lump ore flows to Atlantic shipping lanes, creating single-point vulnerability at Transnet's Sishen-Saldanha rail corridor. Raw material dependencies center on Australian Groote Eylandt oxide, South African Kalahari basin reserves, and Brazilian Carajás lump, with sulfuric acid supply from copper smelter off-gas anchoring sulfate purification economics. Distribution runs through Korean and Japanese cathode material plants locking in captive supply chains ahead of European cell capacity ramp-ups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-grade manganese sulfate demand is accelerating through cathode chemistry shifts, with the EU Battery Regulation's recycled-content thresholds and due diligence mandates creating qualification barriers that favor integrated miners with verified Scope 3 data infrastructure.
For Market Incumbents: Build logistics infrastructure moats by securing port-to-mine rail concessions at Port of Darwin and Saldanha Bay before junior miners deploy capital. Anglo American and South32 should consolidate Northern Cape processing capacity to defend against Indonesian HPAL projects integrating captive sulfate supply, while investing in ISO 14064 carbon accounting systems to meet Korean automaker disclosure requirements. For New Entrants and Emerging Players: North American sulfate purification capacity represents the most penetrable white-space target, with US Inflation Reduction Act domestic content bonuses incentivizing Michigan and Tennessee cell plant feedstock investments. Pure-play explorers should pursue direct recycling feedstock partnerships with lithium-ion black mass processors to bypass traditional ore qualification timelines, targeting cathode remanufacturing as an alternative manganese source. For Investors and Strategic Acquirers: Long-term, this sits as a critical mineral infrastructure play because battery-grade sulfate qualification creates durable supplier switching costs across 18-24 month pilot campaigns. Acquisition targets should display integrated logistics networks or hydrometallurgical flowsheets eliminating pyrometallurgical intermediates. The signal to watch is Korean procurement office abandonment of quarterly tenders in favor of direct five-year negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfate Purification | Eliminates pyrometallurgical steps to meet Korean cathode plant carbon disclosure requirements. |
| Long-term Supply Agreement | Locks in five-year offtake volumes with POSCO and LG Chem ahead of European cell ramp-ups. |
| Green Certification Program | Secures EU Battery Regulation compliance through mine-site solar arrays and Scope 3 verification. |
| Joint Venture | Combines Australian oxide reserves with Korean hydrometallurgical expertise for integrated sulfate output. |
| Capacity Expansion | Adds Port of Darwin bulk terminal throughput to bypass Queensland coal port congestion. |
Methodological Framework
A standing panel of mine operations directors, cathode material plant procurement managers, ferroalloy smelter technical leads, and port logistics coordinators provided ongoing calibration across primary interview cycles. Secondary validation drew from South African Department of Mineral Resources and Energy licensing records, Australian Bureau of Statistics export data, Chinese Ministry of Ecology and Environment emissions filings, and Korean Ministry of Trade, Industry and Energy critical mineral stockpile disclosures. Bottom-up volume modeling triangulated against top-down value chain analysis.
Scenario bracketing anchored low-case assumptions on Chinese ferroalloy smelter consolidation pace and high-case assumptions on European cell capacity commissioning timelines across the projection horizon. Segmentation dimensions spanned product grade tier, end-use industry, physical form specification, and regional production hub. CAGRs derived from electrolytic metal demand elasticity and sulfate qualification velocity, with forecast inputs incorporating Eskom tariff trajectory and sulfuric acid market tightness from copper smelter cycle timing.
Practitioners should monitor EU Battery Regulation implementation delays and Indonesian HPAL project commissioning rates for early signals of supply-demand rebalancing. Forecasts reflect documented assumptions on cathode chemistry adoption curves and carbon-border adjustment enforcement timing. Material shifts in Chinese dual carbon policy stringency or Transnet rail corridor reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Selenium Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Selenium Mining Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Chromite Market