
 North America and EMEA Ferrosilicon Market | 2026-2036
North America and EMEA Ferrosilicon Market Size, Share, and Industry Trends Forecast 2026-2036
North America and EMEA Ferrosilicon Market Intelligence
Canada's emerging ferrosilicon capacity build-out is reshaping Atlantic supply routes for North American buyers. Elkem leverages its integrated smelting network to sustain long-term electrode supply security. Ferroglobe anchors Mediterranean distribution through Spanish and French port infrastructure. RFA International competes on specialized particle-size grades for precision foundry applications.
Ferrosilicon denotes an iron-silicon alloy typically containing 15-90% silicon by weight, produced via carbothermic reduction of quartz in submerged arc furnaces. Its primary function serves as a deoxidizer and alloying agent in steelmaking and as an inoculant in cast iron production. Ferrosilicon 75 occupies the dominant volume position across both regions due to its versatility in carbon steel refining. Steel Production commands the largest application share, while Aluminum Alloys represent the fastest-growing consumption segment driven by lightweighting mandates. Automotive Manufacturers concentrate the highest-value end-user demand, particularly for electrical steel laminations in traction motors.
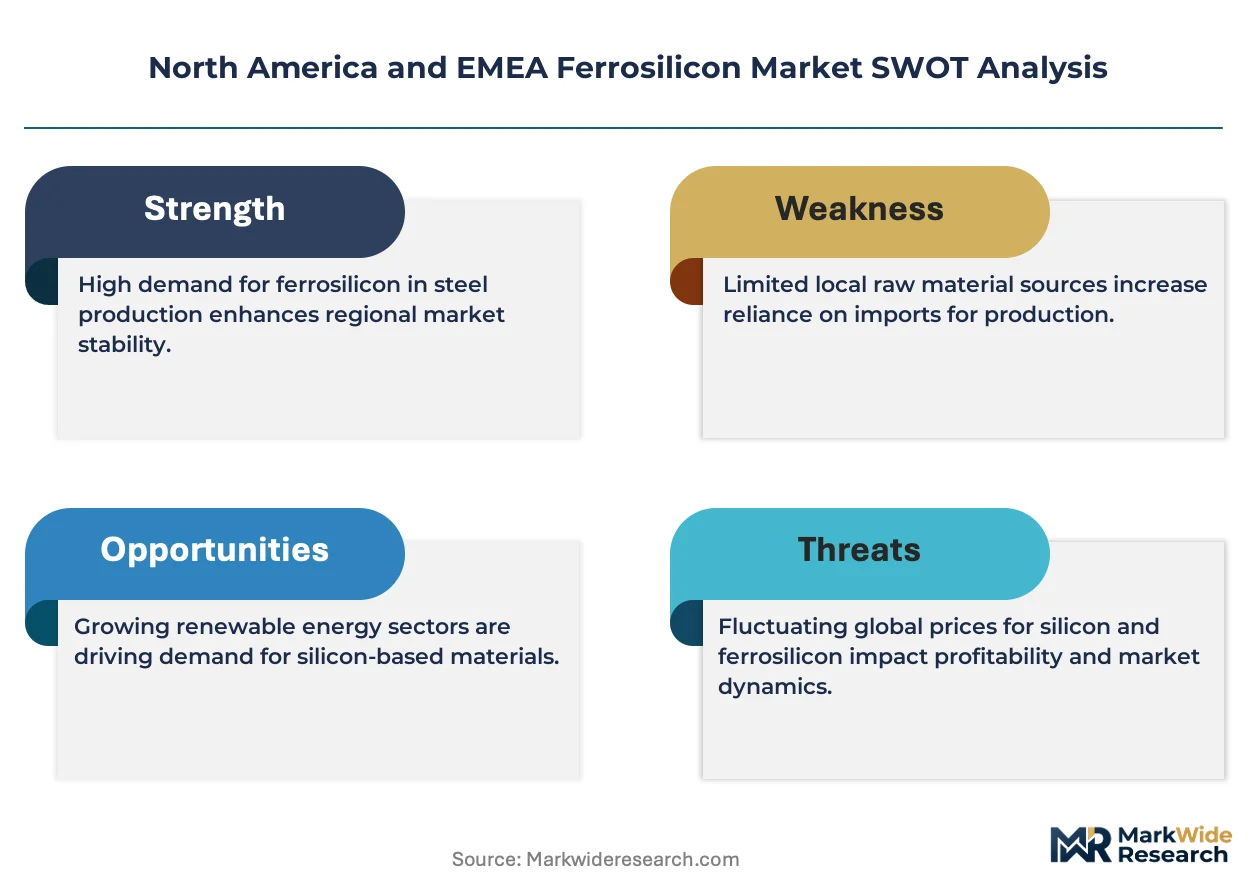
EPA emissions standards and the EU Green Deal's carbon border mechanism jointly elevate low-carbon ferrosilicon premiums across the trade corridor. REACH compliance and OSHA silica exposure limits further tighten product specifications and workplace handling protocols. Stakeholders must evaluate smelter power-source certifications and traceability systems ahead of evolving procurement criteria on both sides of the Atlantic.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is redirecting sourcing patterns across the Atlantic trade corridor, forcing buyers to requalify suppliers based on power-source certifications and embodied emissions traceability.
Growth Catalysts
- Electrical steel demand:Automotive manufacturers expanding traction motor production require high-grade ferrosilicon for grain-oriented steel laminations. This specification pull is accelerating through Germany's industrial belt.
- REACH compliance premiums:The EU's chemical registration framework is creating tiered pricing for low-impurity ferrosilicon grades, rewarding producers with certified clean production pathways.
- Aluminum alloying expansion:Lightweighting mandates in North American transportation are displacing traditional deoxidizer applications with specialized silicon content specifications for cast aluminum components.
Market Restraints
- Quartz supply concentration:High-purity silica deposits cluster in limited geographies, exposing smelters to freight cost volatility and geopolitical friction on critical raw material access.
- Energy cost asymmetry:Submerged arc furnace operations face divergent power pricing between Nordic hydroelectric-sourced capacity and continental European grid-dependent smelters.
- Silica fume substitution:Microsilica recovered from ferrosilicon off-gas competes with alternative pozzolanic materials in cement applications, compressing byproduct revenue streams.
Strategic Opportunities
- Canadian capacity expansion:Quebec's hydroelectric surplus supports low-carbon ferrosilicon production targeting US buyers seeking IRA-compliant clean manufacturing credits.
- Precision foundry particle engineering:Specialized size-graded ferrosilicon for inoculation applications commands premium positioning in automated pouring systems.
- OSHA silica rule alignment:Tighter workplace exposure limits in US foundries are creating pull for pre-packaged, low-dust ferrosilicon product formats with integrated handling systems.
Industry Challenges
- Electrode supply security:Graphite electrode availability constrains furnace utilization rates, requiring smelters to secure long-term offtake agreements with carbon product manufacturers.
- Cross-border certification lag:Divergent EPA and ECHA testing protocols for ferrosilicon impurities create dual compliance burdens for transatlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and EMEA Ferrosilicon Market |
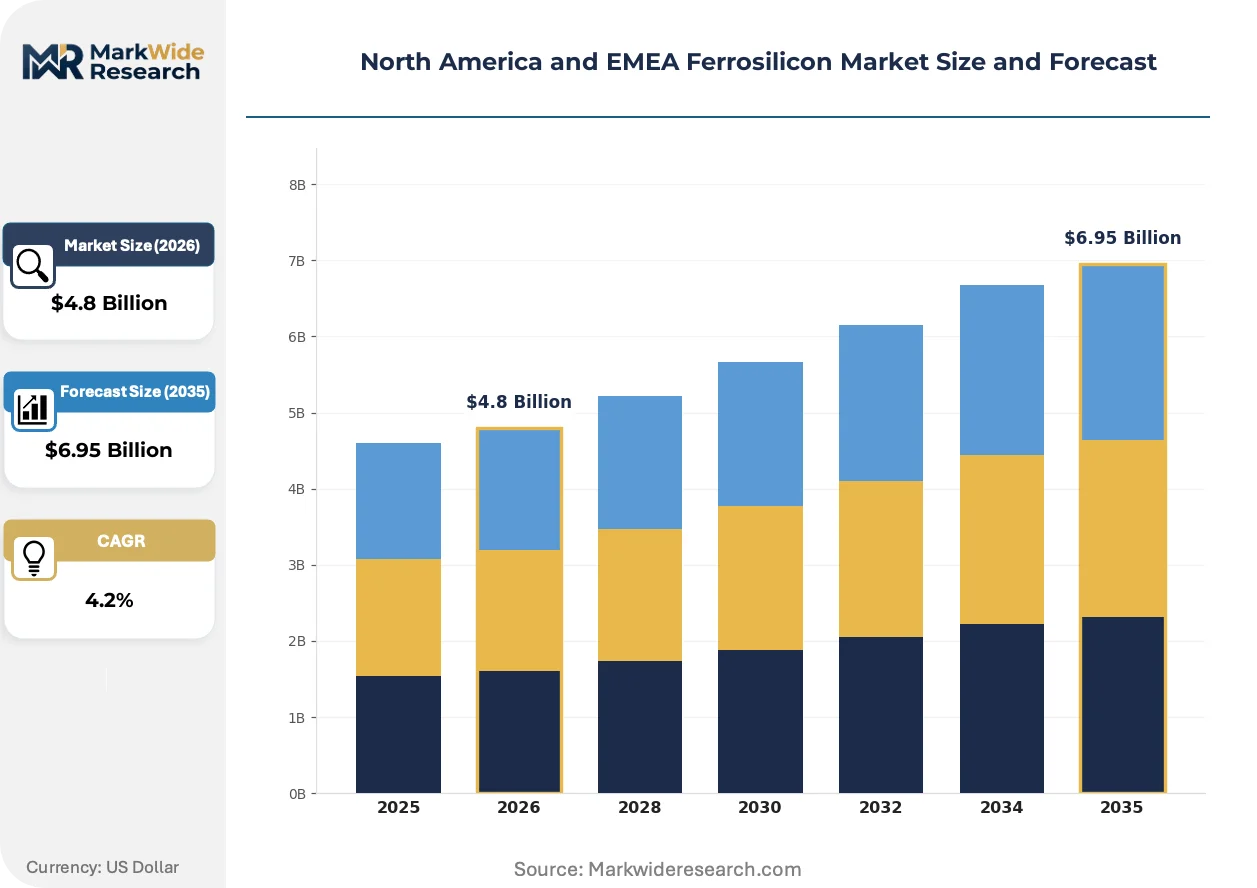
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Metal, Ferrosilicon 75, Ferrosilicon 50, Ferrosilicon 90 Application: Steel Production, Aluminum Alloys, Ductile Iron Casting, Deoxidizer End User: Automotive Manufacturers, Construction Firms, Foundries, Chemical Industries Distribution Channel: Wholesale Distributors, Direct Sales, Online Retailers, Industrial Suppliers |
| Companies Covered | Eurasian Resources Group, RFA International, Elkem, CC Metals & Alloy, DMS Powders, Ferroglobe, OM Holdings Ltd, Mechel PAO, Finnfjord AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and EMEA Ferrosilicon Market Strategic Shifts & Innovations
Smelting technology and product specification standards are converging around decarbonization imperatives, with power sourcing transparency becoming a competitive differentiator alongside traditional chemistry metrics.
Ternary ferrosilicon-magnesium alloys are migrating from conventional foundry inoculation toward automated nodularization systems in high-volume automotive casting operations. Tier-1 suppliers in Germany's Ruhr region are adopting these grades for consistent spheroidization control. The specification shift is compressing demand for standard ferrosilicon 75 in favor of engineered dissolution-rate products.
The EU Green Deal's carbon border mechanism is imposing emissions documentation requirements on ferrosilicon imports entering European customs territories. Smelters must now verify power-source mixes and process emissions through third-party audit trails. North American exporters to the Netherlands and Belgium are restructuring logistics to consolidate shipments through Rotterdam's certified green corridor.
Buyers are consolidating supplier panels around dual-qualified Atlantic sources capable of serving both EPA-regulated US foundries and REACH-compliant EU steelmakers. Large steel groups in the US Great Lakes region are reducing vendor counts from six to three qualified sources. This concentration pattern is most visible among integrated mills seeking simplified audit overhead for cross-border material flows.
North America and EMEA Ferrosilicon Market Segmentation
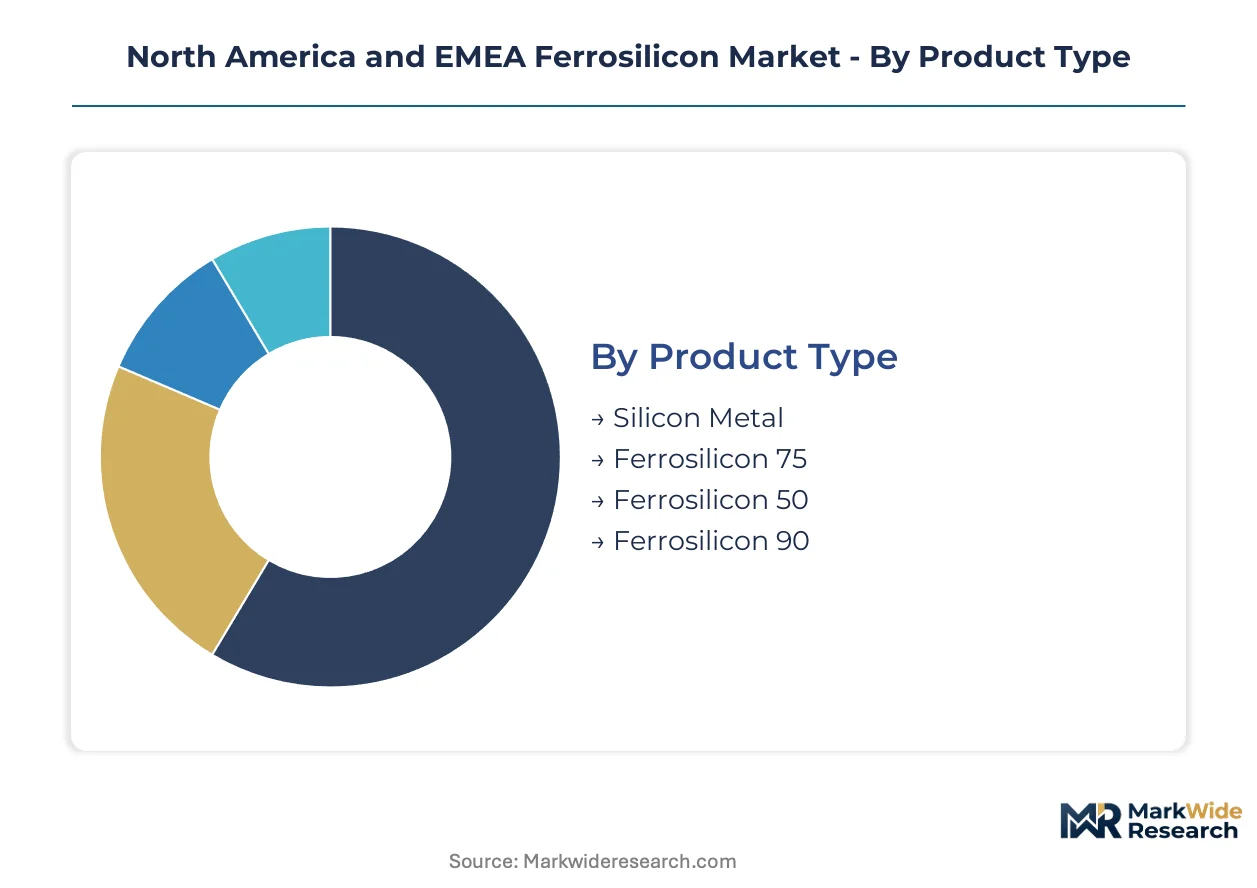
Ferrosilicon procurement patterns diverge sharply across product grades and end-use specifications, with steel mills demanding long-term contract stability while foundries chase spot-market flexibility for inoculant blends. Understanding these segment dynamics reveals where margin compression concentrates and where premium positioning endures.
Product Type:
Inventory velocity varies dramatically across silicon content tiers, with standardized grades turning faster than specialty alloys requiring custom specifications.
- Ferrosilicon 75:The iron-silicon alloy containing 74-79% silicon serves as the workhorse deoxidizer across carbon steel refining operations. Demand concentrates in Germany's Ruhr industrial belt, where integrated mills anchor regional offtake volumes and specification consistency drives repeat procurement.
- Ferrosilicon 50:This mid-range grade with 47-52% silicon content finds primary application in foundry inoculation where controlled dissolution rates matter. North American ductile iron producers in Ohio and Pennsylvania favor this specification for automated pouring line compatibility.
- Silicon Metal:Metallurgical-grade silicon at 98.5%+ purity feeds aluminum alloying and chemical synthesis pathways rather than steelmaking.
- Ferrosilicon 90:High-silicon content at 87-95% serves niche applications in specialty steel and magnesium ferrosilicon precursor production.
Ferrosilicon 75 dominates installed base. Ferrosilicon 50 is where expansion concentrates.
Application:
Margin structure inverts across these use cases, with commodity steel applications compressing returns while precision foundry and aluminum specifications sustain premium capture.
- Steel Production:Deoxidation and alloying in basic oxygen and electric arc furnaces consumes the largest volume share of ferrosilicon across both regions. EAF operators in the US Great Lakes region and integrated mills in Germany's industrial belt drive specification standardization around FeSi 75 chemistry.
- Aluminum Alloys:Silicon addition to wrought and cast aluminum for automotive lightweighting commands the steepest expansion trajectory. Michigan and Ontario-based tier-1 suppliers are displacing traditional deoxidizer applications with specialized silicon content specifications for structural cast components.
- Ductile Iron Casting:Nodularization via magnesium ferrosilicon alloys requires precise particle size distribution for consistent spheroidization.
- Deoxidizer:Ladle metallurgy applications in secondary steel refining represent mature, price-sensitive demand.
Steel Production anchors volume commitments. Aluminum Alloys is where margin expansion concentrates.
End User:
Procurement sophistication tiers separate long-term contract negotiators from spot-market buyers, with automotive OEMs driving the tightest certification requirements.
- Automotive Manufacturers:Electrical steel laminations for traction motors demand ultra-low-carbon ferrosilicon with traceable power-source documentation. German OEMs and their North American transplant operations are consolidating supplier panels around dual-qualified Atlantic sources capable of serving both EPA-regulated US foundries and REACH-compliant EU steelmakers.
- Foundries:Ductile iron producers require engineered particle-size grades for automated inoculation systems, with Ohio and Pennsylvania operations leading adoption of pre-packaged low-dust product formats.
- Construction Firms:Rebar and structural steel applications represent price-elastic demand with minimal specification differentiation.
- Chemical Industries:Silicones and semiconductor feedstock applications pull high-purity silicon metal rather than ferrosilicon grades.
Automotive Manufacturers concentrate the highest-value demand. Foundries is where technical differentiation concentrates.
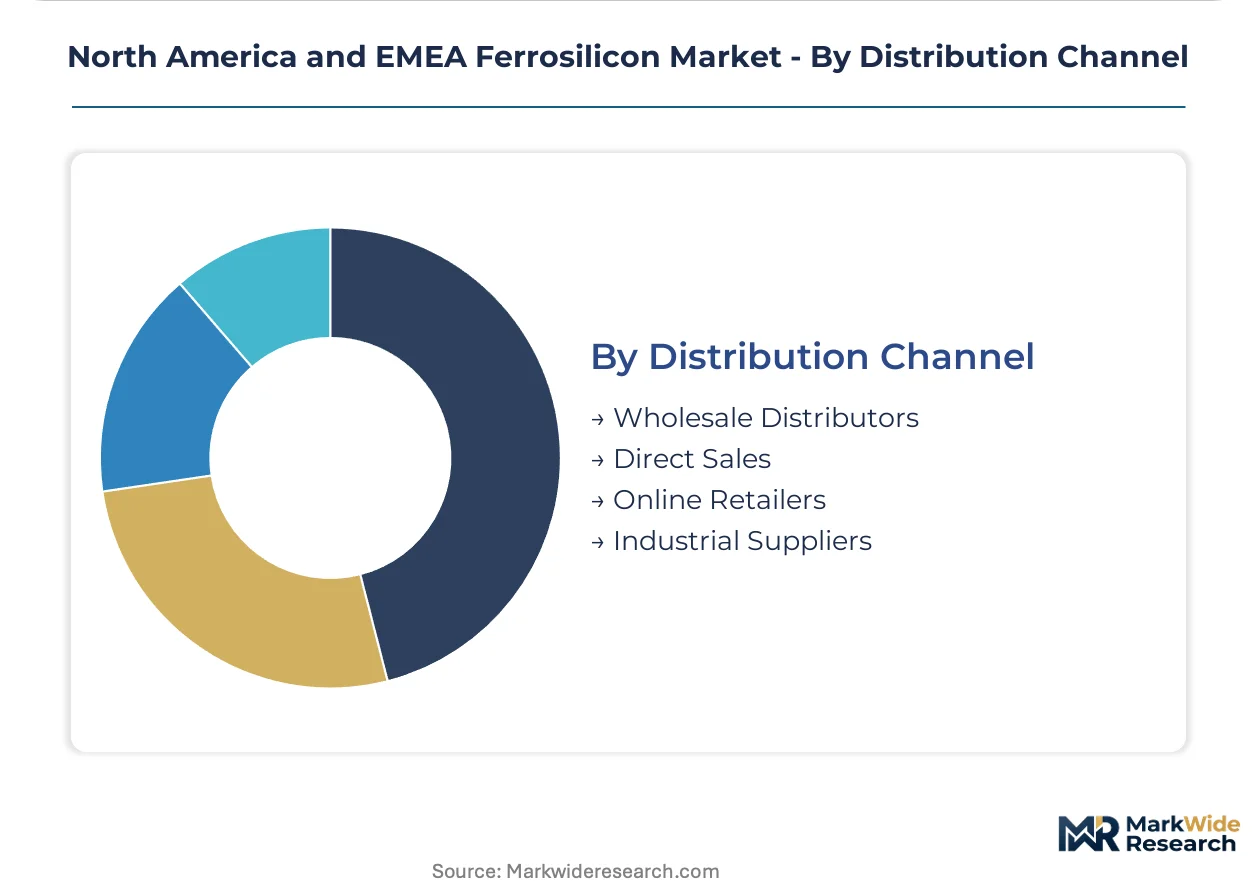
Distribution Channel:
Channel selection tracks customer scale and specification complexity, with bulk consumers bypassing intermediaries while specialized grades flow through technical distributors.
- Wholesale Distributors:Regional stockists in the US Midwest and German industrial corridors maintain FeSi 75 inventory for spot purchases by medium-scale foundries and steel service centers. Rotterdam's port infrastructure anchors Mediterranean distribution through consolidated warehousing.
- Direct Sales:Integrated steel groups and large automotive OEMs negotiate long-term offtake agreements directly with Elkem, Ferroglobe, and emerging Canadian producers, securing volume commitments and power-source certification transparency.
- Industrial Suppliers:Technical distributors serve precision foundries requiring specialized particle-size engineering and just-in-time delivery.
- Online Retailers:Digital channels capture minimal ferrosilicon volume given bulk material handling requirements and hazardous material shipping constraints.
Direct Sales dominates contract value. Wholesale Distributors is where spot-market liquidity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and the EU Green Deal's carbon border mechanism jointly elevate low-carbon ferrosilicon premiums across the Atlantic trade corridor. Stakeholders must evaluate smelter power-source certifications and traceability systems ahead of evolving procurement criteria on both sides of the Atlantic.
United States
Automotive manufacturers expanding traction motor production require high-grade ferrosilicon for grain-oriented steel laminations. OSHA silica exposure limits tighten product specifications and workplace handling protocols in foundries. Ohio and Pennsylvania operations anchor regional offtake for ductile iron producers favoring mid-range silicon grades.
Canada
Quebec's hydroelectric surplus supports low-carbon ferrosilicon production targeting US buyers seeking IRA-compliant clean manufacturing credits. The country's national emissions regulator enforces documentation requirements on smelter power-source mixes. Atlantic supply routes are reshaping as capacity build-out redirects North American buyer sourcing patterns.
Germany
Integrated mills in the Ruhr industrial belt drive specification standardization around FeSi 75 chemistry for carbon steel refining. REACH compliance creates tiered pricing for low-impurity ferrosilicon grades, rewarding producers with certified clean production pathways. Tier-1 suppliers in the Ruhr region are adopting ternary ferrosilicon-magnesium alloys for automated nodularization systems.
Spain
Mediterranean distribution infrastructure anchors supply consolidation through Spanish and French port facilities serving EMEA buyers. The EU Green Deal's carbon border adjustment mechanism forces requalification of suppliers based on embodied emissions traceability. Foundry clusters in the Basque Country and Catalonia concentrate precision inoculant demand.
Netherlands
Rotterdam's certified green corridor consolidates shipments from North American exporters seeking EU market access under carbon border documentation requirements. ECHA testing protocols for ferrosilicon impurities create dual compliance burdens for transatlantic suppliers. The port's warehousing infrastructure enables just-in-time delivery to German industrial belt consumers.
North America and EMEA Ferrosilicon Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The North America and EMEA ferrosilicon market structures around integrated smelters with captive power arrangements and specialized distributors serving precision foundry niches. Three archetypes dominate: Nordic hydroelectric-powered producers, Mediterranean logistics-anchored suppliers, and emerging Canadian low-carbon capacity builders. Competitive moves concentrate on securing long-term electrode offtake agreements and consolidating supplier panels around dual-qualified Atlantic sources.
Among Nordic integrated producers, Elkem and Finnfjord AS exemplify the hydroelectric-sourced capacity archetype with power-source certification transparency. Ferroglobe occupies a position within the Mediterranean distribution tier, leveraging Spanish and French port infrastructure. RFA International represents the specialization vector, competing on engineered particle-size grades for precision foundry applications.
| Leading Market Players |
|---|
| Eurasian Resources Group |
| RFA International |
| Elkem |
| CC Metals & Alloy |
| DMS Powders |
| Ferroglobe |
| OM Holdings Ltd |
| Mechel PAO |
| Finnfjord AS |
| Others |
Cost & Logistics Intelligence
Quartz deposit concentration in Norway, China, and Brazil anchors raw material access costs for Atlantic smelters, concentrating margin capture with Nordic hydroelectric-powered producers while grid-dependent continental European operators absorb power price volatility. Long-term contract premiums for low-carbon ferrosilion now separate qualified suppliers from spot-market sellers.
Pricing Analysis
Atlantic price spreads widen between Nordic hydroelectric-sourced material and continental European grid-dependent output, with the former commanding certification-linked premiums under EU Green Deal carbon border documentation. Three-tier pricing structure across low-carbon certified, standard industrial, and unqualified spot grades reflects power-source transparency and REACH compliance tiers. Cost compression in standard FeSi 75 is intensifying because automotive OEMs consolidate supplier panels around dual-qualified sources. Construction-grade buyers in rebar applications show highest price sensitivity, while electrical steel laminations for traction motors tolerate steepest premiums.
Supply Chain Analysis
Extended payment terms from integrated steel groups are squeezing working capital for Mediterranean distributors serving mid-tier foundries through Rotterdam's warehousing infrastructure. Supply concentrates in Norway, Spain, and Quebec, with emerging Canadian capacity drawing from Quebec's hydroelectric surplus to serve IRA-compliant US buyers. Graphite electrode availability, high-purity silica freight costs, and magnesium alloying precursors constitute critical input dependencies. Single-source vulnerability runs through Chinese quartz processing for ultra-high-purity grades. Distribution runs through direct long-term offtake agreements for integrated mills and wholesale distributors for spot-market foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smelter power-source certification and electrode supply security constitute the binding constraints separating viable long-term suppliers from margin-compressed commodity sellers. Technical differentiation in particle-size engineering offers escape velocity from standard-grade price wars.
For Market Incumbents: Insulate margin position by securing captive graphite electrode offtake agreements with carbon product manufacturers and accelerating backward integration into quartz beneficiation capacity in Norway or Quebec. Silica fume substitution in cement applications threatens byproduct revenue streams, requiring investment in microsilica purification for higher-value pozzolanic markets. For New Entrants and Emerging Players: Build out precision foundry particle engineering capabilities for automated inoculation systems in Ohio and Pennsylvania ductile iron operations, where OSHA silica rule alignment creates pull for pre-packaged low-dust formats. The most penetrable white space sits in ternary ferrosilicon-magnesium alloys for automotive nodularization, with German Ruhr tier-1 suppliers leading specification adoption. Go-to-market through technical distributors serving automated pouring line retrofits. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Mediterranean logistics-anchored suppliers lacking power-source certification transparency for EU Green Deal compliance. Long-term viability hinges on 5-10 year power purchase agreement structures and carbon border documentation infrastructure. Watch for electrode supply contract renewals as inflection indicator for furnace utilization rate sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Beneficiation | Captive high-purity silica supply secures margin capture for Nordic hydroelectric producers against freight volatility. |
| Green Manufacturing Transition | Quebec hydroelectric-powered smelters qualify for IRA clean manufacturing credits targeting US automotive OEMs. |
| Long-term Supply Agreement | Integrated steel groups in Germany's Ruhr belt consolidate supplier panels around dual-qualified Atlantic sources. |
| Capacity Expansion | Canadian build-out redirects North American sourcing patterns away from traditional Atlantic shipping routes. |
| Joint Venture | Electrode manufacturers and smelters co-locate carbon product capacity to secure furnace utilization rates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, ECHA registration dossiers, and power-grid operator disclosures. Primary interviews engaged smelter operations directors, foundry procurement managers at Ohio and Pennsylvania ductile iron producers, automotive OEM electrical steel sourcing leads, and Rotterdam port logistics coordinators. Secondary validation drew from SEC filings of listed ferroalloy producers, EU TRANSIT customs documentation, and Nordic grid operator generation mix disclosures. Bottom-up capacity utilization modeling triangulated against top-down end-use demand aggregation across steelmaking, aluminum alloying, and foundry inoculation segments.
Forecast inputs incorporate silicon content grade tiering, end-use industry specification requirements, and regional power-source certification clusters across the analysis window. Modeled dimensions span FeSi 75 versus FeSi 50 versus specialty magnesium alloy grades, steel production versus aluminum alloying versus ductile iron casting applications, and hydroelectric-sourced versus grid-dependent versus emerging low-carbon capacity production hubs. CAGRs derive from segment-level demand elasticity coefficients applied to automotive electrical steel laminations and lightweighting-driven aluminum alloying expansion trajectories. Forecast sensitivity tests electrode supply constraints and carbon border mechanism implementation timing.
Practitioners should monitor EU Green Deal carbon border documentation enforcement thresholds, Quebec hydroelectric capacity commissioning schedules, and OSHA silica exposure rule implementation pace for early signals of supply requalification urgency. Forecasts reflect assumptions on power price parity between Nordic and continental European smelters and sustained automotive electrical steel demand growth. Macroeconomic steel production contraction, abrupt electrode supply disruption, or regulatory deviation in carbon border scope would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market