
 Global Noble Ferroalloys Market | 2026-2036
Global Noble Ferroalloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Noble Ferroalloys Market Intelligence
The rise of specialized project financing for resource extraction and processing is fragmenting the competitive landscape for noble ferroalloys. This allows smaller, focused producers to secure capital for specific high-value alloy projects. AMG Advanced Metallurgical Group N.V. leverages its technological expertise in specialty metals like ferrovanadium. Essel Mining & Industries Limited (EMIL) sustains its position through large-scale mining and integrated production capabilities.
Noble ferroalloys are master alloys containing elements like vanadium, molybdenum, or nickel, which are added to molten steel to impart specific properties. These materials possess high melting points and are critical for deoxidation and enhancing strength, corrosion resistance, and heat resistance. Within product types, ferrovanadium is essential for high-strength low-alloy (HSLA) steels. The steel production application continues to dominate consumption, particularly for specialized alloy steel grades used in demanding environments.
Market access and production costs are shaped by a complex web of international regulations. The EU's REACH framework governs chemical safety, while China's Ministry of Ecology and Environment (MEE) imposes strict emissions standards on smelters. In the United States, OSHA standards dictate workplace safety around heavy metals. Stakeholders must now navigate the challenge of securing stable, ethically sourced raw material supplies while meeting increasingly stringent environmental performance criteria.
Market Dynamics
The central tension shaping the noble ferroalloys market is the conflict between escalating demand for high-performance materials from heavy industry and the rising compliance costs imposed by global environmental regulations like the EU Green Deal, which directly target energy-intensive smelting operations.
Growth Catalysts
- High-Performance Steel Demand:The aerospace and defense industries require advanced steels with superior strength-to-weight ratios, directly driving consumption of ferrovanadium and ferromolybdenum for critical structural components and engine parts.
- Infrastructure Investment Programs:Large-scale public works projects, particularly in North America and Asia, necessitate specialized alloy steels for constructing resilient bridges, pipelines, and power generation facilities, bolstering demand for master alloys.
- Renewable Energy Expansion:The construction of wind turbines and geothermal power plants uses significant quantities of high-strength, corrosion-resistant steels, creating a consistent demand stream for noble ferroalloys in green energy infrastructure.
Market Restraints
- Volatile Input Costs:The market is exposed to sharp price fluctuations for raw materials like vanadium and molybdenum ores, which are influenced by mining output disruptions and geopolitical instability in key producing nations like China and Chile.
- Intensive Energy Consumption:Ferroalloy production via submerged arc furnaces is extremely energy-intensive, making producers highly vulnerable to volatile electricity pricing and carbon taxes under frameworks such as the EU Emissions Trading System.
- Substitution from Other Alloys:In certain less-demanding steel applications, there is a persistent threat of substitution from lower-cost bulk ferroalloys like ferromanganese or alternative strengthening agents, which can cap price ceilings for noble variants.
Strategic Opportunities
- Circular Economy Integration:Developing advanced hydrometallurgical processes to recover valuable elements like vanadium and nickel from steel slag and industrial catalysts presents a significant opportunity to create secondary, more sustainable supply streams.
- Hydrogen Infrastructure Materials:The build-out of a global hydrogen economy requires specialized alloys for pipelines and storage vessels that can resist hydrogen embrittlement, opening a new, high-performance application segment.
- Additive Manufacturing Powders:Manufacturing spherical ferroalloy powders tailored for 3D printing applications allows for the creation of complex, lightweight components for the aerospace and medical implant industries, representing a high-value niche.
Industry Challenges
- Capital-Intensive Emissions Control:Meeting stringent air pollution standards from regulators like the US EPA and China's MEE requires substantial capital investment in furnace upgrades, gas scrubbing systems, and continuous emissions monitoring equipment.
- Workplace Safety Mandates:Strict adherence to occupational health regulations, including OSHA standards for managing worker exposure to metallic dust and fumes, demands continuous investment in ventilation systems, training, and health monitoring programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Noble Ferroalloys Market |
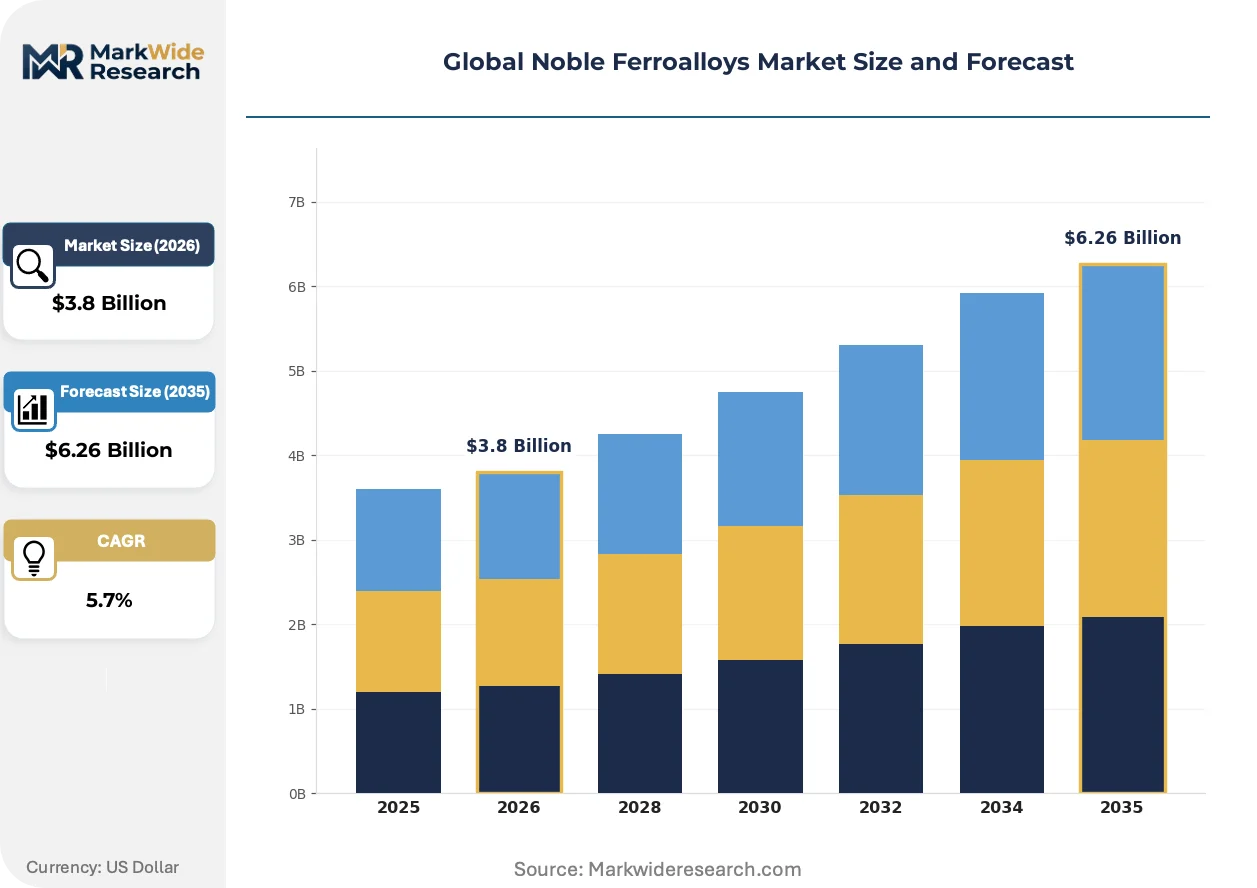
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferromanganese, Ferrochromium, Ferrosilicon, Ferrovanadium, Ferronickel Application: Steel Production, Castings, Welding Electrodes, Chemical Manufacturing, Alloy Steel End User Industry: Foundries, Construction, Shipbuilding, Heavy Machinery, Electrical Equipment Form: Granules, Powder, Lumps, Briquettes, Pellets |
| Companies Covered | Shanghai Shenjia Ferroalloys Co. Ltd., FE Mottram Ltd, Essel Mining & Industries Limited (EMIL), Nortech Ferro Alloys Pvt. Ltd., Global Titanium Inc., D S Alloyd Pvt Ltd, LekonGermess Ltd, Team Ferroalloys Pvt. Ltd., AMG Advanced Metallurgical Group N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Noble Ferroalloys Market Strategic Shifts & Innovations
The noble ferroalloys sector is undergoing a fundamental transformation driven by the twin imperatives of decarbonizing production and engineering materials for extreme environments. This is compelling producers to re-evaluate everything from raw material sourcing and processing technology to final product certification.
Advanced gas atomization processes are creating highly uniform, spherical ferroalloy powders for specialized applications. The aerospace and medical device industries are early adopters of these materials for additive manufacturing. This technological shift is hybridizing traditional bulk alloy production with precision powder metallurgy, enabling the fabrication of components with optimized internal structures that were previously unachievable through casting or forging.
Regulatory frameworks focused on carbon leakage are altering trade dynamics. The EU's Carbon Border Adjustment Mechanism (CBAM) imposes a tariff on carbon-intensive imports, directly affecting ferroalloy producers outside the bloc. This policy forces manufacturers in regions with lower environmental standards to either accelerate their decarbonization efforts or risk losing access to the lucrative European market, with ferromolybdenum and ferrovanadium producers being most exposed.
A notable behavioral shift is the elevation of supply chain transparency as a critical procurement factor. Major end-users in the automotive and electronics sectors are increasingly prioritizing suppliers who can provide certified, ethically sourced raw materials, moving beyond decisions based solely on price. This trend is most pronounced in North America and Europe, where corporate ESG commitments are influencing purchasing strategies for critical inputs like ferronickel.
Global Noble Ferroalloys Market Segmentation
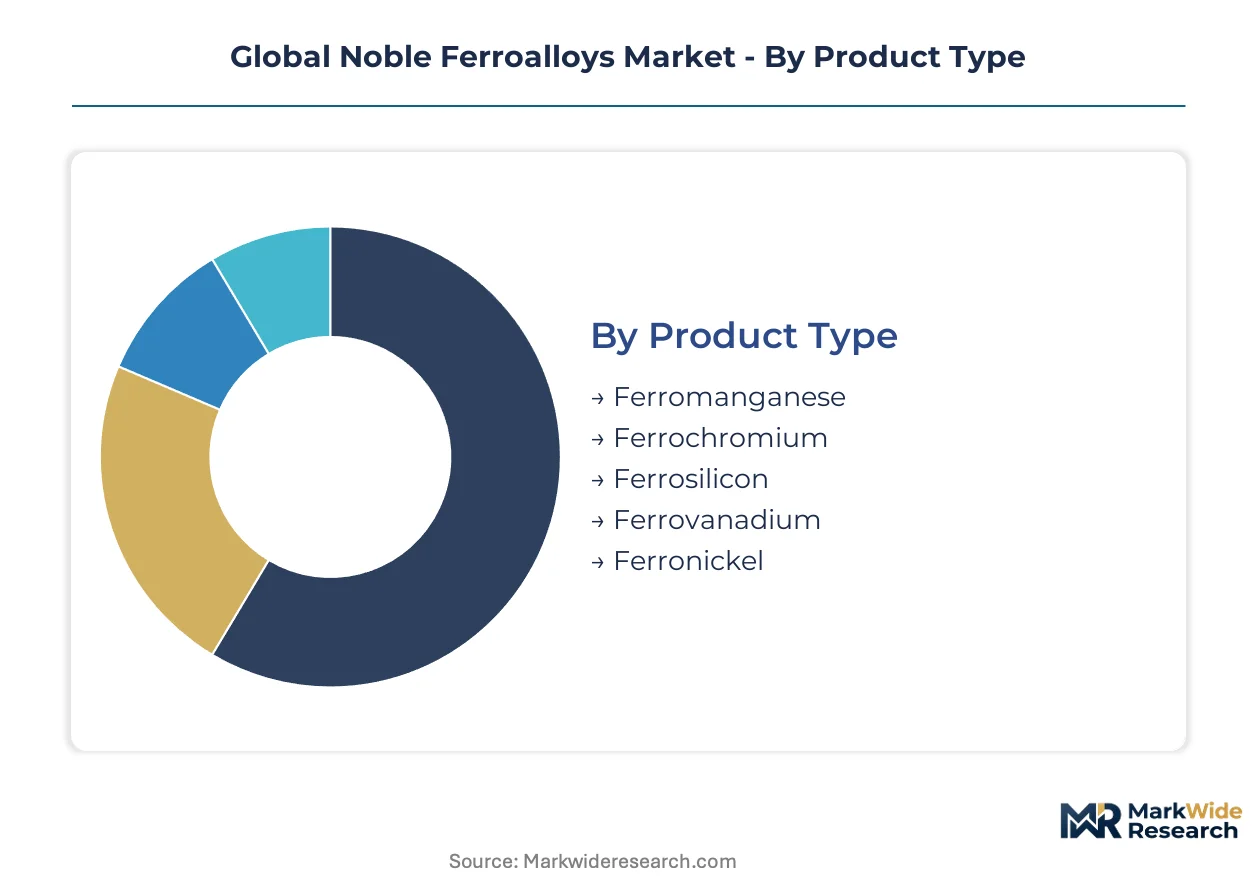
The global noble ferroalloys market segments reveal distinct value propositions and operational complexities across various product forms and applications. Understanding these classifications is essential for producers optimizing processes and for end-users seeking specialized materials. Each segment addresses specific industrial requirements.
Product Type:
The after-sales-service intensity for noble ferroalloys varies by product type, reflecting the precision and criticality of application. Specialized alloys require extensive technical support for integration into complex manufacturing processes, ensuring optimal performance and adherence to standards.
- Ferrovanadium:This master alloy strengthens steel and improves fatigue resistance. Demand concentrates in aerospace and defense sectors, where its role in high-strength low-alloy (HSLA) steels is critical for structural integrity.
- Ferronickel:An alloy of iron and nickel, ferronickel is used in stainless steel production for corrosion resistance. Procurement in North America and Europe prioritizes ethically sourced material, driven by corporate ESG commitments.
- Ferromanganese:This alloy deoxidizes and desulfurizes steel, enhancing its workability.
- Ferrochromium:Used to produce stainless steel, ferrochromium provides corrosion resistance and a lustrous finish.
- Ferrosilicon:Ferrosilicon acts as a deoxidizer and alloying agent, improving steel strength and elasticity.
Ferromanganese holds the largest share; momentum sits with Ferrovanadium due to its critical role in high-performance steels.
Application:
The cost tier for noble ferroalloy applications reflects the value added and performance criticality required by the end product. High-performance applications demand premium-grade ferroalloys, justifying higher material costs due to their specialized properties.
- Steel Production:This application involves adding noble ferroalloys to molten steel for specific mechanical and chemical properties. Steel production dominates consumption for specialized alloy steel grades used in demanding environments like heavy machinery.
- Alloy Steel:Noble ferroalloys are crucial for manufacturing specialized alloy steels, offering superior strength, corrosion, and heat resistance. Demand accelerates in aerospace and renewable energy, where material performance impacts operational efficiency.
- Castings:Noble ferroalloys improve the strength and wear resistance of cast iron and steel components for industrial machinery.
- Welding Electrodes:These alloys enhance mechanical properties and corrosion resistance of weld metal, crucial for structural integrity.
- Chemical Manufacturing:Noble ferroalloys serve as catalysts or alloying agents in various chemical processes, particularly for high-temperature environments.
Steel Production leads in volume; Alloy Steel drives innovation.
End User Industry:
The application patterns for noble ferroalloys vary across end-user industries, dictated by specific material performance requirements. Industries with high-stress or extreme-environment applications exhibit greater reliance on advanced alloy compositions.
- Construction:The construction sector utilizes noble ferroalloys in high-strength steels for infrastructure projects, including bridges and pipelines. Large-scale public works programs in North America and China bolster demand for master alloys.
- Heavy Machinery:This industry requires noble ferroalloys for producing durable components that withstand extreme wear and stress. China's extensive heavy machinery sector drives significant demand for specialized alloy steels.
- Foundries:Foundries incorporate noble ferroalloys to enhance cast metal properties, producing components with improved strength and durability.
- Shipbuilding:Noble ferroalloys contribute to the strength and corrosion resistance of marine-grade steels for vessel hulls.
- Electrical Equipment:These alloys are used in specialized electrical components requiring high conductivity, heat resistance, and magnetic properties.
Construction consumes most volume, with Heavy Machinery showing robust expansion.
Form:
The volume of noble ferroalloys traded in different forms correlates with their intended processing methods and end-use applications. Bulk forms cater to traditional smelting operations, while finer, specialized forms serve advanced manufacturing techniques.
- Powder:Fine spherical ferroalloy powders are engineered for additive manufacturing and specialized coating applications. Aerospace and medical implant industries are early adopters, leveraging these materials for 3D printing.
- Lumps:Noble ferroalloys in lump form are the traditional input for large-scale steelmaking and foundry operations, added directly to molten metal. This form remains widely used in basic oxygen and electric arc furnaces.
- Granules:Granular forms offer improved dissolution rates in molten metal, favored for precise alloying additions.
- Briquettes:Briquettes are compacted forms of ferroalloys, reducing dust and improving handling efficiency in metallurgical processes.
- Pellets:Pellets provide a uniform and consistent material input, optimizing furnace operations and alloy recovery.
Lumps dominate traditional consumption, while Powder exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global environmental policies, such as the EU Green Deal, are driving investment in sustainable material production and advanced alloy development worldwide. These regulatory frameworks incentivize the adoption of high-performance noble ferroalloys for critical infrastructure and green energy projects. This push influences market dynamics across key industrial nations.
China
Demand from heavy machinery and construction sectors remains robust in China. The Ministry of Ecology and Environment (MEE) enforces strict emissions standards on smelters, promoting cleaner production technologies. Industrial clusters in the Yangtze River Delta actively integrate specialized alloy steels into advanced manufacturing operations.
United States
Infrastructure investment programs and aerospace defense needs bolster demand for advanced noble ferroalloys in the United States. OSHA standards mandate stringent workplace safety for heavy metal handling, influencing operational costs for producers. The Gulf Coast region sees significant demand for corrosion-resistant alloys in petrochemical and energy infrastructure.
Germany
High-performance steel requirements from the automotive and specialized machinery industries drive ferroalloy consumption in Germany. The EU's REACH framework and CBAM policies shape material procurement and carbon-intensive import tariffs. The Ruhr Area, a historical industrial heartland, continues to be a hub for advanced metallurgical research and alloy production.
India
Infrastructure development projects and an expanding manufacturing base increase demand for noble ferroalloys in India. The PLI scheme supports domestic manufacturing, including steel production, creating consistent demand for alloying elements. Major industrial corridors like the Delhi-Mumbai Industrial Corridor are seeing new investments in steel and heavy engineering.
Chile
Mining sector expansion and renewable energy projects contribute to noble ferroalloy demand in Chile. Environmental regulations by the Ministry of Environment influence raw material extraction and processing, particularly for molybdenum. The Antofagasta region, a major mining hub, focuses on supplying high-grade copper and associated alloy inputs for global markets.
Global Noble Ferroalloys Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, combining large integrated mining and processing conglomerates with specialized niche producers. Archetypes include global commodity suppliers focusing on high-volume output, technology-driven specialists developing advanced alloys for demanding applications, and regional players serving specific industrial clusters. Dominant competitive moves involve strategic partnerships for securing stable raw material supplies and capacity expansion to meet escalating demand from heavy industry sectors.
AMG Advanced Metallurgical Group N.V. exemplifies a technology-driven specialist, leveraging expertise in specialty metals for high-value alloy projects across diverse industrial applications. Essel Mining & Industries Limited (EMIL) represents an integrated producer, sustaining its market position through large-scale mining and comprehensive production capabilities for various ferroalloy types. Shanghai Shenjia Ferroalloys Co. Ltd., based in China, occupies a position among regional suppliers, focusing on fulfilling domestic demand for various ferroalloy grades within the country's extensive industrial base and construction sector.
| Leading Market Players |
|---|
| Shanghai Shenjia Ferroalloys Co. Ltd. |
| FE Mottram Ltd |
| Essel Mining & Industries Limited (EMIL) |
| Nortech Ferro Alloys Pvt. Ltd. |
| Global Titanium Inc. |
| D S Alloyd Pvt Ltd |
| LekonGermess Ltd |
| Team Ferroalloys Pvt. Ltd. |
| AMG Advanced Metallurgical Group N.V. |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for vanadium and molybdenum ores directly influences noble ferroalloy pricing tiers and shapes long-term supply agreements. Geopolitical instability in key producing nations also dictates supply chain resilience and material costs.
Pricing Analysis
Certification level (e.g., aerospace-grade, medical implant-grade) creates the primary spread in noble ferroalloy pricing. Contract-based long-term offtake agreements dominate for high-volume purchases. Quality grade and after-sales technical support drive significant price differentiation. Pricing softness in standard grades stems from increased competition from regional suppliers. Construction and heavy machinery sectors exhibit higher price sensitivity compared to aerospace and medical device manufacturers.
Supply Chain Analysis
Geographic concentration of raw material extraction in China, Chile, and South Africa creates inherent supply chain risks. The market depends on stable supplies of vanadium, molybdenum, and nickel ores. Geopolitical instability in producing regions poses a structural risk to material availability. Distribution primarily runs through specialized metallurgical distributors and direct long-term contracts with large steelmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The noble ferroalloys market represents a high-growth disruption, driven by the imperative to decarbonize production and the technological inflection of additive manufacturing. New material requirements for green energy infrastructure further amplify this transformation.
For Market Incumbents: Build technological moats through advanced hydrometallurgical processes for secondary material recovery. Invest in furnace upgrades to meet stringent EU Emissions Trading System standards and secure long-term raw material offtake agreements. This defends against margin pressure from rising compliance costs and volatile input prices. Capacity additions in regions with stable energy costs and robust ESG certifications strengthen market position.
For New Entrants and Emerging Players: Establish a beachhead in additive manufacturing powders for aerospace and medical implants. Target specialized alloy steel grades for hydrogen infrastructure materials, leveraging advanced gas atomization techniques. The powder form segment represents the most penetrable area due to its high-value niche and lower volume requirements. Partner with specialized 3D printing service bureaus to accelerate market entry and product validation.
For Investors and Strategic Acquirers: The market sits at a transformative phase that favors technology-driven specialists with strong intellectual property in advanced metallurgy. Long-term viability over a 5-10 year window remains strong due to persistent demand for high-performance materials in critical infrastructure. Target companies with proven capabilities in circular economy integration and emissions control technologies. Watch for increased adoption of EU CBAM-compliant production methods as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Investing in cleaner production technologies mitigates regulatory risks from the EU Green Deal and China's MEE. |
| Long-term Supply Agreement | Securing stable raw material access counters price volatility and geopolitical supply disruptions for critical elements. |
| Capacity Expansion | Increasing production capacity for high-performance ferrovanadium meets growing demand from aerospace and defense. |
| Joint Venture | Collaborating on hydrometallurgical recovery technologies establishes secondary, sustainable supply streams for valuable elements. |
| Product Launch | Introducing specialized ferroalloy powders for additive manufacturing captures high-value niches in medical and aerospace. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory reports, corporate filings, and industry association publications. Interviews included metallurgical engineers, procurement managers from steel mills, supply chain directors, and environmental compliance officers. Data sources comprised EU REACH documents, China MEE reports, US OSHA guidelines, and trade statistics. A bottom-up approach to market sizing was triangulated with top-down validation using macroeconomic indicators.
Forecast inputs considered include projected steel production volumes, infrastructure spending, and renewable energy deployment rates. The analytical framework modeled market dynamics across the projection horizon. Segmentation dimensions included product type, application, end-user industry, form, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and anticipated technological advancements. Specific forecast inputs involved projected demand for HSLA steels and additive manufacturing adoption rates.
Stress conditions across raw material price volatility and regulatory enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding geopolitical stability and consistent technological adoption trajectories. Significant shifts in global trade policies or unforeseen material substitutions could revise these projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Ultra High Strength Steel Market