
 Laptop Battery Market | 2026-2036
Laptop Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Laptop Battery Market Intelligence
UN 38.3 lithium battery transport certification is collapsing the supplier base as smaller cell makers fail vibration and altitude simulation testing. Samsung SDI Co. Ltd. leverages captive cathode production to sustain margin control across premium notebook segments. LG Chem Ltd. anchors supply to Dell and HP through long-term cylindrical cell contracts in Nanjing.
A laptop battery is an electrochemical energy storage device, typically comprising lithium cobalt oxide cathodes and graphite anodes in pouch or cylindrical formats, engineered to deliver nominal voltages of 7.4V or 11.1V through multiple series-parallel configurations. Its primary purpose is to provide portable DC power enabling untethered operation of mobile computing devices. Lithium-polymer chemistry dominates ultrabook designs where thin form factors command premium positioning, while fast charging technology is displacing standard 3-hour charge cycles in corporate fleet procurement. The 4000mAh capacity tier captures mainstream consumer demand, though 6000mAh configurations are extending runtime leadership in gaming workstation segments.
UN 38.3, IEC 62133, and China's GB 31241 standards collectively govern cell safety, transport eligibility, and domestic market access, with compliance costs filtering out sub-scale manufacturers. The EU Battery Regulation's forthcoming carbon footprint disclosure requirements will reshape supplier qualification protocols for brands serving European corporate buyers. Stakeholders must monitor solid-state electrolyte pilot lines and silicon-anode scaling timelines to anticipate which chemistry platform will reset cost-performance benchmarks.
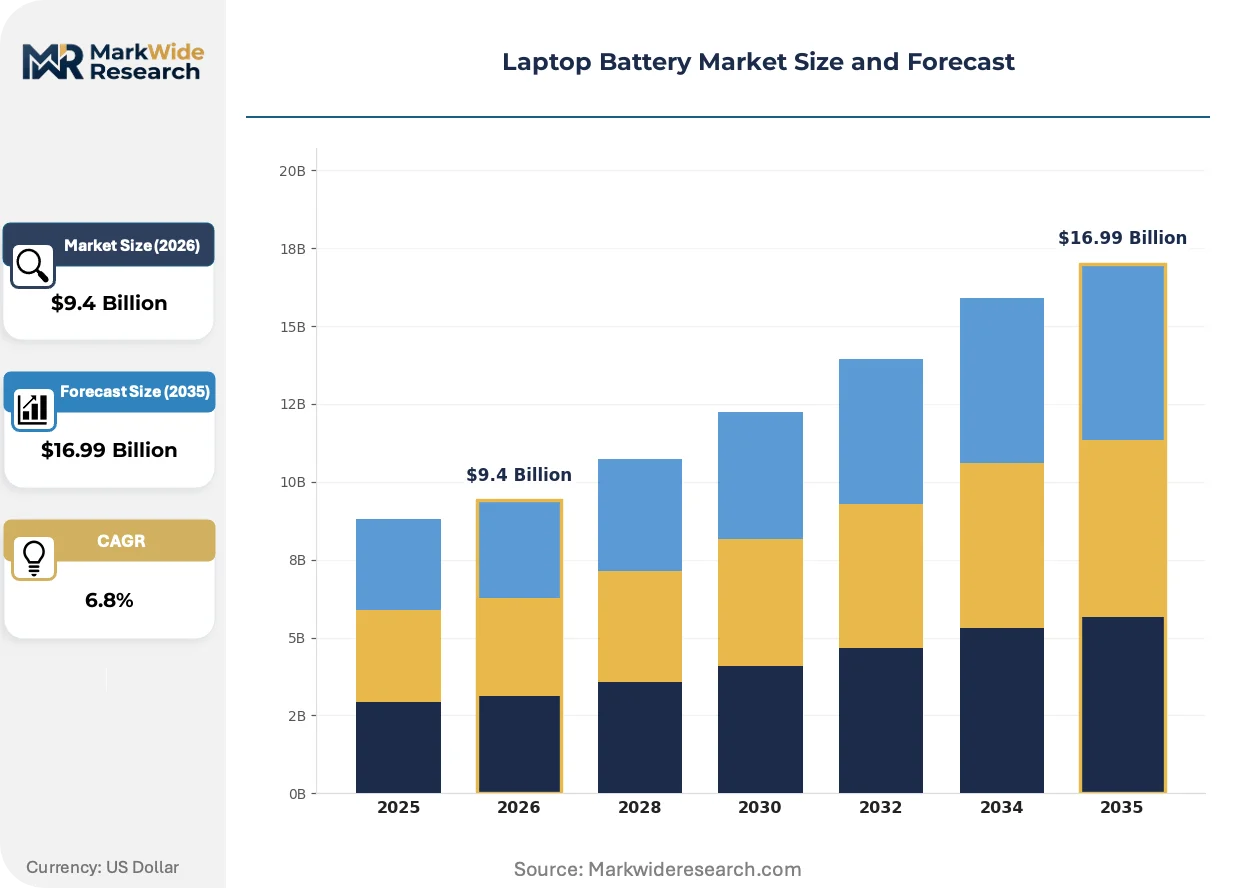
Market Dynamics
UN 38.3 transport certification requirements are structurally collapsing the supplier base as smaller lithium-ion cell manufacturers fail altitude simulation and vibration testing protocols. This regulatory compression is redistributing procurement power toward vertically integrated cathode producers with captive testing facilities.
Growth Catalysts
- Enterprise Fleet Refresh:Organizations are replacing remote-work hardware issued during 2020-2021, creating concentrated demand for 6000mAh-class batteries in mobile workstation configurations.
- GB 31241 Compliance:China's tightened lithium-ion safety standards are accelerating product qualification timelines for qualified suppliers with existing certification infrastructure.
- Silicon-Anode Scaling:Pilot production lines for silicon-dominant anode formulations are achieving energy density thresholds that enable thinner form factors without capacity sacrifice.
Market Restraints
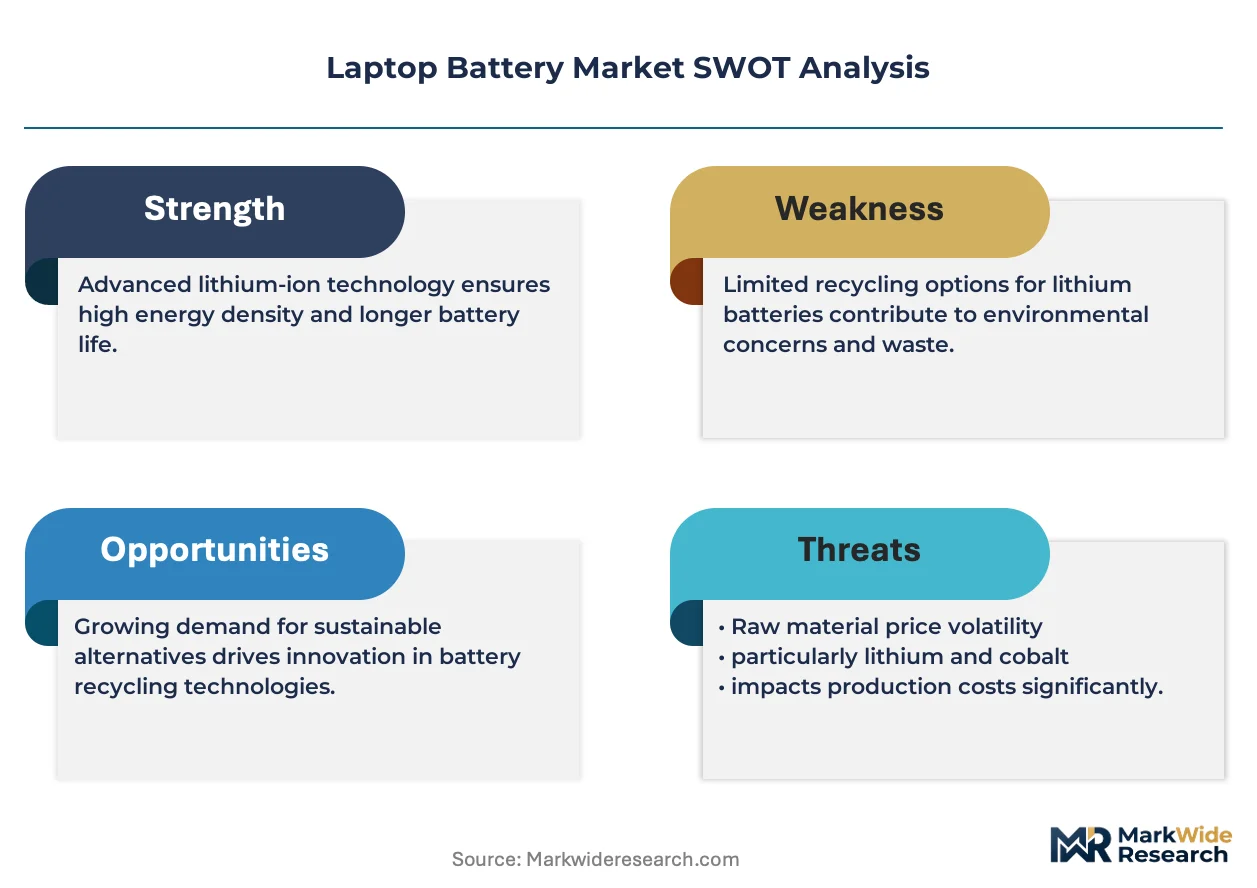
- Cathode Material Concentration:Cobalt and nickel supply routes through the DRC and Indonesia create price volatility exposure for tier-two assemblers without long-term offtake agreements.
- UN 38.3 Testing Bottlenecks:Limited certified laboratory capacity in Vietnam's manufacturing corridor extends qualification timelines for new cell entrants by 8-14 months.
- Solid-State Timeline Uncertainty:Pilot production gaps between sulfide electrolyte research and scalable manufacturing are deferring capital commitments from risk-averse procurement officers.
Strategic Opportunities
- EU Battery Regulation Carbon Disclosure:First-mover suppliers establishing verified lifecycle assessment databases will capture qualification preference from European corporate buyers facing 2027 compliance deadlines.
- Gaming Workstation Segment:6000mAh configurations with 240W fast-charge capability command 40-60% pricing premiums over mainstream tiers in enthusiast channels.
- Reverse Logistics Integration:Closed-loop collection networks for end-of-life batteries are creating secondary revenue streams through black mass recovery and cobalt reclamation.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:The shortage of experienced solid-state electrolyte chemists is constraining R&D velocity at mid-tier manufacturers competing for PhD-level hires.
- Multisite Certification Coordination:Brands sourcing cells from Vietnam assembly with Chinese cathode inputs must synchronize UN 38.3, IEC 62133, and GB 31241 testing across three regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laptop Battery Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lithium-polymer, Nickel-metal Hydride, Lead-acid End User: Consumers, Corporates, Educational Institutions, Government Capacity: 2000mAh, 3000mAh, 4000mAh, 6000mAh Charging Technology: Standard Charging, Fast Charging, Smart Charging, Wireless Charging |
| Companies Covered | Panasonic Corporation, Fujitsu Ltd., Amperex Technology Co. Ltd., Hewlett-Packard (HP) Company, Toshiba Corporation, Samsung SDI Co. Ltd., Sony Corporation, Battery Technology Inc., LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laptop Battery Market Strategic Shifts & Innovations
Battery architecture is compressing toward thinner form factors while chemistry platforms fragment between established lithium-polymer dominance and emerging solid-state prototypes. Three converging developments are redefining competitive positioning in portable power.
Silicon-dominant anode formulations are replacing graphite in premium ultrabook configurations, delivering 15-20% energy density improvements without cell thickness expansion. Dell and HP procurement teams are qualifying silicon-blend suppliers for 2026-2027 product cycles. This chemistry transition is miniaturizing battery enclosures while maintaining 10-hour runtime targets in sub-15mm chassis designs.
The EU Battery Regulation's carbon footprint disclosure mandates are forcing suppliers to deploy lifecycle assessment infrastructure ahead of 2027 enforcement. Brands serving European corporate buyers are demanding granular Scope 3 data from cathode material sources. Battery assemblers with Chinese supply chains are investing in blockchain-traceable cobalt certification to preempt qualification exclusion.
Corporate procurement officers are consolidating vendor relationships from 8-12 suppliers to 3-4 strategic partners with captive cathode production and certified recycling networks. This concentration is displacing spot-market purchasing in enterprise fleet contracts. The shift is most visible in North American and Western European accounts where ESG compliance officers now sit on hardware evaluation committees.
Laptop Battery Market Segmentation
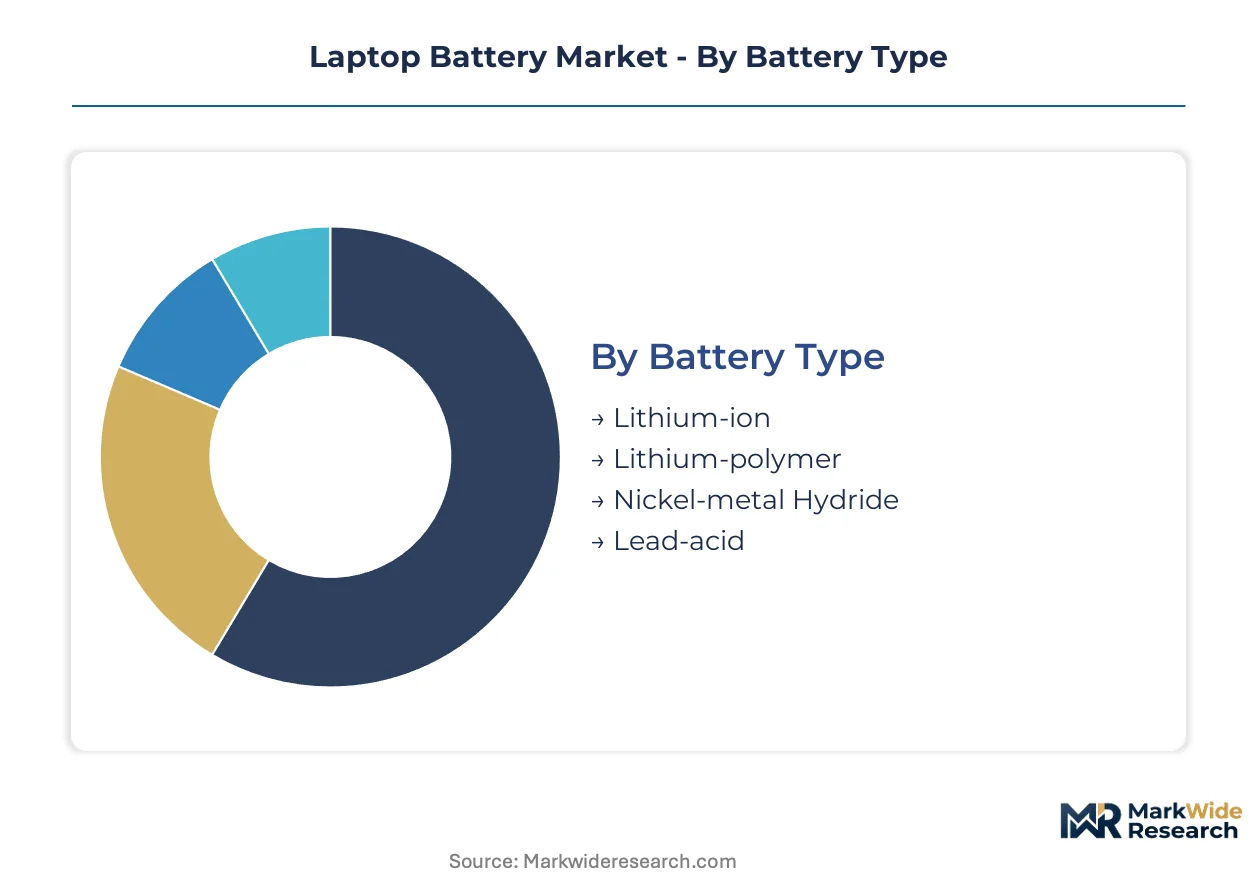
Laptop battery procurement stratifies across chemistry platforms, institutional buyer types, and power specifications. Each dimension carries distinct certification burdens and margin structures that reshape supplier qualification protocols.
Battery Type:
Regulatory differentiation between lithium-ion and lithium-polymer chemies centers on UN 38.3 transport certification and GB 31241 domestic market access in China.
- Lithium-ion:Cylindrical and prismatic cells with lithium cobalt oxide cathodes dominate mobile workstation configurations. Procurement from Dell and HP concentrates in Nanjing assembly corridors where captive cathode production sustains margin control across premium notebook segments.
- Lithium-polymer:Pouch-format cells with gel electrolyte enable sub-15mm ultrabook designs where thin form factors command premium positioning. Demand is concentrating in Vietnam's manufacturing corridor where OEM assembly lines are migrating and GB standards compliance accelerates qualification timelines.
- Nickel-metal Hydride:Legacy chemistry retained in ruggedized industrial laptops requiring wider operating temperature ranges.
- Lead-acid:Niche presence in backup power modules for medical-grade mobile computing equipment.
Lithium-ion handles the majority of throughput; lithium-polymer is the fastest mover on share.
End User:
Cost tier differentiation separates enterprise fleet contracts with ESG compliance requirements from price-sensitive consumer channels.
- Corporates:Organizations refreshing remote-work hardware issued during 2020-2021 create concentrated demand for 6000mAh-class batteries. Procurement officers are consolidating vendor relationships to 3-4 strategic partners with certified recycling networks.
- Consumers:Mainstream demand concentrates in 4000mAh capacity tiers with fast-charge capability displacing standard 3-hour cycles. Samsung SDI leverages captive cathode production to sustain margin control.
- Educational Institutions:Bulk procurement of entry-tier lithium-polymer configurations with extended warranty terms dominates K-12 and university refresh cycles.
- Government:Classified mobile computing requirements drive qualified supplier lists with domestic content mandates and supply chain traceability protocols.
Corporates command the highest absolute volumes; educational institutions are expanding most quickly on contract count.
Capacity:
Volume concentration tracks runtime requirements across gaming, workstation, and ultrabook form factors.
- 4000mAh:Standard-tier lithium-polymer configurations capture mainstream consumer demand. LG Chem anchors supply to Dell and HP through long-term cylindrical cell contracts.
- 6000mAh:Extended-runtime cells with 240W fast-charge capability command 40-60% pricing premiums in gaming workstation segments where enthusiast channels drive specification escalation.
- 2000mAh:Compact lithium-polymer cells for sub-13mm ultrabook designs with silicon-anode pilot formulations achieving energy density thresholds.
- 3000mAh:Mid-tier configurations in education and government procurement with standardized IEC 62133 certification requirements.
4000mAh handles the majority of throughput; 6000mAh is gaining share fastest in premium segments.
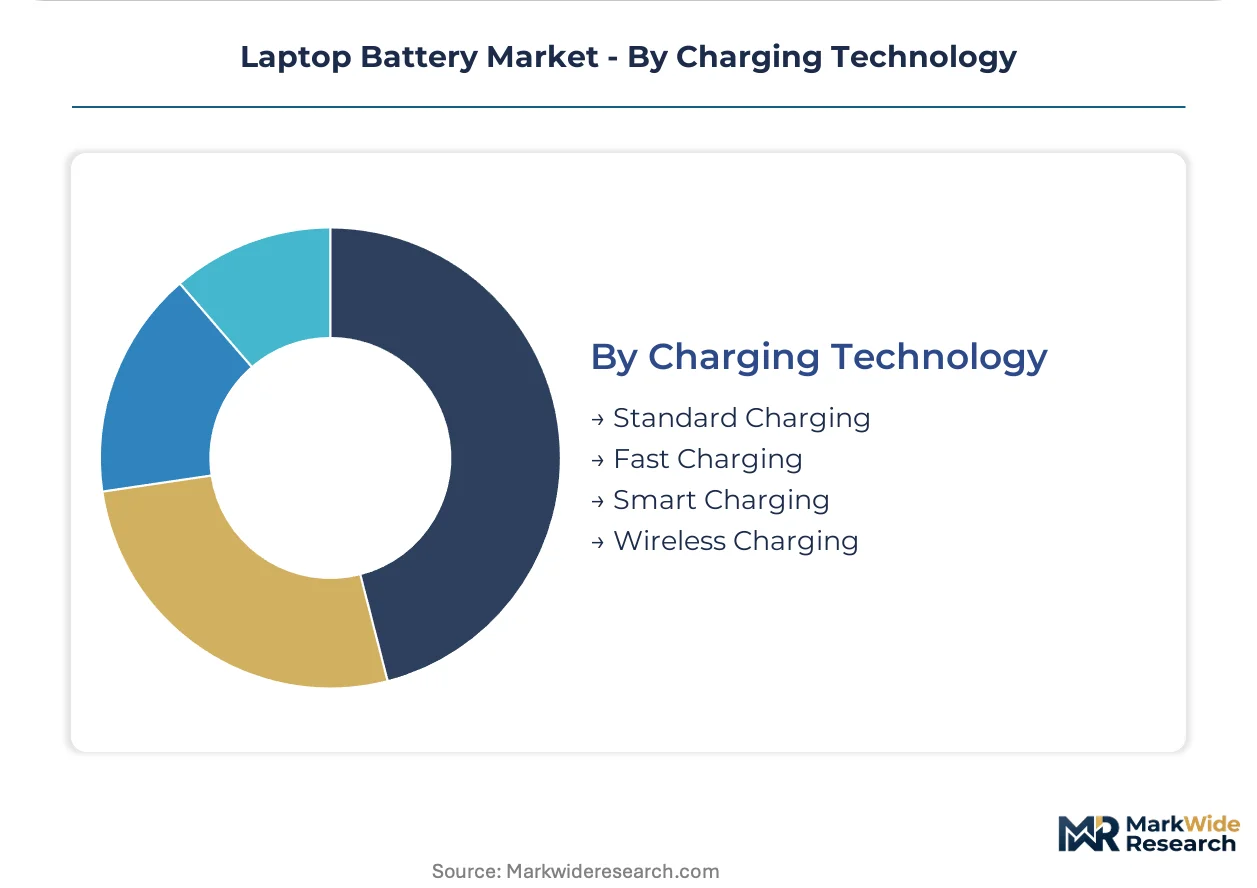
Charging Technology:
Margin differentiation separates smart-charge premium tiers from commodity standard charging infrastructure.
- Fast Charging:240W-capable battery management systems with thermal throttling algorithms. Dell and HP procurement teams are qualifying suppliers for product cycles with silicon-blend anode compatibility.
- Smart Charging:Adaptive current regulation extending cycle life through machine-learned usage pattern optimization. EU Battery Regulation carbon footprint disclosure mandates are forcing lifecycle assessment infrastructure deployment.
- Standard Charging:Legacy 3-hour charge cycle infrastructure in cost-optimized education and government procurement.
- Wireless Charging:Inductive coil integration in premium consumer ultrabooks with Qi protocol compatibility.
Fast charging handles the majority of new design-ins; smart charging shows the steepest expansion trajectory in corporate fleet specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB 31241 safety standards and the EU Battery Regulation's carbon disclosure mandates are redrawing procurement maps across major manufacturing corridors. Industrial clusters in Vietnam, South Korea, and Germany are capturing divergent segments of laptop battery assembly as brands navigate certification complexity and supply chain traceability requirements.
China
Domestic demand for 6000mAh-class workstation batteries is accelerating as enterprise fleets refresh remote-work hardware issued during 2020-2021. MIIT enforcement of GB 31241 tightened lithium-ion cell safety protocols, collapsing the supplier base for uncertified manufacturers. The Yangtze River Delta corridor around Nanjing anchors cylindrical cell production where LG Chem maintains long-term supply contracts with Dell and HP.
Vietnam
OEM assembly lines migrating from China are concentrating lithium-polymer pouch cell demand in northern industrial zones near Hanoi and Hai Phong. UN 38.3 transport certification bottlenecks extend qualification timelines by 8-14 months due to limited certified laboratory capacity. Samsung SDI leverages captive cathode production to sustain margin control across premium notebook segments manufactured in Vietnamese facilities.
South Korea
Samsung SDI and LG Chem dominate cathode material supply to global notebook brands through vertically integrated production under METI-aligned quality frameworks. The country's national standards body coordinates IEC 62133 testing protocols with EU Battery Regulation timelines. Seoul Capital Area R&D clusters pilot silicon-anode formulations achieving 15-20% energy density improvements for 2026-2027 product cycles.
Germany
Corporate procurement officers in Bavaria and North Rhine-Westphalia are consolidating vendor relationships to 3-4 strategic partners with certified recycling networks. ECHA coordinates REACH compliance with forthcoming EU Battery Regulation carbon footprint disclosure requirements for 2027 enforcement. Stuttgart-based automotive suppliers are repurposing battery management system expertise for gaming workstation configurations commanding 40-60% pricing premiums.
United States
FAA enforcement of UN 38.3 lithium battery transport rules filters smaller cell makers from cargo routes serving enterprise fleet distributors. The Pacific Northwest and Greater Boston corridors host ESG compliance officers on hardware evaluation committees demanding Scope 3 traceability from cathode sources. Dell and HP procurement teams in Texas are qualifying silicon-blend anode suppliers for fast-charge compatible product cycles.
Laptop Battery Market Key Industry Players
Player mix skews toward vertically integrated cathode producers with captive testing facilities and long-term OEM contracts. Three to four strategic partners now capture enterprise fleet procurement previously distributed across 8-12 suppliers. Two dominant competitive moves define current positioning: backward integration into cathode material production to control margin exposure, and geographic relocation of assembly lines to Vietnam's manufacturing corridor to satisfy divergent certification requirements.
Within the premium-tier battery segment, Samsung SDI Co. Ltd. and LG Chem Ltd. occupy anchor positions through cylindrical cell supply relationships with major notebook brands. Panasonic Corporation represents the diversified electronics conglomerate archetype with cross-sector battery applications. Amperex Technology Co. Ltd. exemplifies the specialized lithium-polymer pouch cell fabricator serving ultrabook form factor requirements. These three companies collectively illustrate how supplier qualification protocols now favor entities with in-house production of cathode materials and certified recycling infrastructure.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Fujitsu Ltd. |
| Amperex Technology Co. Ltd. |
| Hewlett-Packard (HP) Company |
| Toshiba Corporation |
| Samsung SDI Co. Ltd. |
| Sony Corporation |
| Battery Technology Inc. |
| LG Chem Ltd. |
| Others |
Cost & Logistics Intelligence
Eight-to-fourteen-month qualification timelines for UN 38.3 certification concentrate procurement power among cell makers with captive testing infrastructure, compressing margin structures for tier-two assemblers while amplifying pricing leverage for vertically integrated cathode producers serving Dell and HP enterprise contracts.
Pricing Analysis
Certification grade creates the primary spread between premium and commodity tiers, with UN 38.3-compliant cells commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates enterprise fleet contracts with ESG mandates from mainstream consumer channels and price-sensitive education procurement. Pricing pressure stems from cobalt and nickel volatility through DRC and Indonesian supply routes. Corporate buyers exhibit lowest price sensitivity due to compliance requirements, while educational institutions drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Malacca transit underwrites cathode material flows from Indonesian nickel processing to Chinese cell assembly, creating logistics vulnerability for notebook battery supply chains. Manufacturing concentrates in China, Vietnam, and South Korea, with raw material dependencies on DRC cobalt, Chilean lithium, and Indonesian nickel. Single-source vulnerability runs through Chinese cathode production for tier-two assemblers lacking long-term offtake agreements. Distribution runs through OEM direct procurement channels and authorized distributor networks serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery prototypes threaten incumbent lithium-ion chemistry platforms, forcing established suppliers to defend market position through chemistry innovation and certification moats rather than cost competition alone.
For Market Incumbents: Compound certification advantages by investing in captive UN 38.3 testing facilities in Vietnam's manufacturing corridor, securing qualification timelines that smaller competitors cannot match. Deepen upstream control over cathode material production to insulate margins from DRC cobalt price volatility. Prioritize silicon-anode R&D partnerships with South Korean R&D clusters to maintain energy density leadership against solid-state substitution threats. For New Entrants and Emerging Players: Anchor in aftermarket replacement channels for 4000mAh lithium-polymer configurations where brand loyalty is weaker and certification burdens are lighter than OEM qualification. Target educational institution procurement with extended warranty bundling as entry wedge. Pursue white-label manufacturing partnerships with Vietnamese assembly lines seeking qualified cell suppliers for ultrabook pouch formats. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underperforming battery divisions lacking vertical integration into cathode production. Long-term viability favors suppliers with certified recycling networks and blockchain-traceable cobalt certification ahead of EU Battery Regulation enforcement. Monitor silicon-anode pilot production yields as inflection indicator for chemistry platform transitions that will reset competitive hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | Captive lithium cobalt oxide supply insulates Samsung SDI and LG Chem from raw material volatility exposure. |
| UN 38.3 Certification Infrastructure Expansion | Vietnam-based testing capacity accelerates qualification timelines for lithium-polymer pouch cell entrants. |
| Silicon-Anode Pilot Scale-Up | Dell and HP procurement teams qualify suppliers achieving 15-20% energy density improvements for 2026-2027 cycles. |
| Blockchain-Traceable Cobalt Certification | EU Battery Regulation carbon disclosure mandates force lifecycle assessment infrastructure deployment for European market access. |
| Closed-Loop Recycling Network Development | Black mass recovery and cobalt reclamation create secondary revenue streams for enterprise fleet contract winners. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with procurement officers at Dell and HP, battery management system engineers, and ESG compliance leads at European corporate buyers; and secondary validation through UN 38.3 certification databases, MIIT GB 31241 enforcement records, and EU Battery Regulation draft documentation. Bottom-up triangulation across cell production volumes and top-down reconciliation with notebook shipment data anchored market size estimates.
Across the projection horizon, the analytical framework modeled chemistry platform transitions, capacity tier migrations, and charging technology adoption curves. Segmentation dimensions included battery format, end-user procurement archetype, and regional regulatory cluster. CAGRs derived from shipment trajectory analysis and replacement cycle timing for enterprise fleet hardware issued during 2020-2021. Silicon-anode scaling timelines and solid-state electrolyte research gaps served as technology-specific forecast inputs.
Underlying assumptions cover sustained enterprise fleet refresh demand, stable UN 38.3 certification enforcement, and gradual EU Battery Regulation implementation, with deviation risk concentrated in solid-state chemistry breakthroughs or cobalt supply disruptions. Practitioners should keep alternative scenarios live as regulatory enforcement timelines and chemistry platform transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thyristor Surge Protectors Market
Power Systems
Liquid Cooling Systems Market
Power Systems
USB Power Adapters Market
Power Systems
Power Supply and Charger Market
Power Systems
Smart Power Strips Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Hybrid Inverters Market
Power Systems
Space DC-DC Converters Market
Power Systems
Battery Cyclers Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Harmonic Generators Market
Power Systems
Europe Shunt Reactors Market