
 Gan-Powered Chargers Market | 2026-2036
Gan-Powered Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Gan-Powered Chargers Market Foresight
Chinese power semiconductor foundries is shifting toward GaN-on-Si wafer volumes as consumer electronics brands demand higher switching frequencies. Anker Innovations Technology Co., Ltd. leverages vertical integration from chip sourcing to retail packaging, sustaining margin control across multiple voltage tiers. Samsung Electronics Co., Ltd. anchors premium smartphone bundling strategies, while Xiaomi Corporation competes aggressively on cost-engineered fast-charging adapters for mass-market distribution.
Gallium nitride-powered chargers employ wide-bandgap semiconductors that switch at frequencies exceeding 100 kHz, enabling smaller magnetics and higher power density than silicon-based equivalents. Wall chargers and fast chargers lead volume shipments due to smartphone and laptop refresh cycles, while GaN HEMT technology captures expanding share in applications above 65W where thermal efficiency becomes critical. Automotive electronics represents the fastest-growing application segment as EV cabin electronics and onboard power conversion adopt GaN topologies for weight reduction.
FCC Part 15 emissions standards in the United States, CE marking requirements under EU Ecodesign regulations, and China's GB 4943.1 safety standards collectively shape product certification timelines and regional market access protocols. The EU AI Act and emerging cybersecurity labeling frameworks for connected power devices add compliance layers beyond traditional electrical safety. Stakeholders must monitor whether regional efficiency mandates expand minimum load requirements that could disqualify lower-tier GaN implementations from European and North American distribution channels.
Market Dynamics
The GaN-powered charger market is being fundamentally restructured by the EU's USB-C harmonization mandate, which forces universal interoperability across consumer electronics and eliminates proprietary charging ecosystems.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency standards are accelerating silicon-to-GaN transitions in wall adapters sold across European retail channels.
- EV cabin electronics:Automotive OEMs are adopting GaN topologies for onboard DC-DC conversion to reduce weight in electric vehicle power distribution systems.
- Shenzhen semiconductor clusters:Concentrated GaN-on-Si wafer fabrication capacity in China's Pearl River Delta is compressing device costs for finished charger production.
Market Restraints
- Gallium substrate volatility:Limited high-purity gallium refining capacity creates input cost exposure for GaN epitaxial wafer manufacturers.
- Single-region device fabrication:Overwhelming concentration of GaN HEMT production in Chinese foundries generates geopolitical supply risk for non-Chinese OEMs.
- Thermal management thresholds:GaN devices above 100W require advanced packaging solutions that silicon carbide alternatives already address more maturely.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting GaN charger assembly investments outside China.
- Wireless power convergence:Integration of GaN switching with resonant inductive coils is opening premium multi-device charging pad segments.
- EU cybersecurity labeling:Emerging frameworks for connected power devices create first-mover advantage for GaN chargers with embedded authentication chipsets.
Industry Challenges
- Power electronics talent scarcity:Shortage of RF and high-frequency magnetics engineers is extending GaN adapter design cycles beyond traditional silicon development timelines.
- Multi-jurisdiction certification stacking:Simultaneous FCC Part 15, CE marking, and GB 4943.1 approvals are creating six-to-nine month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan-Powered Chargers Market |
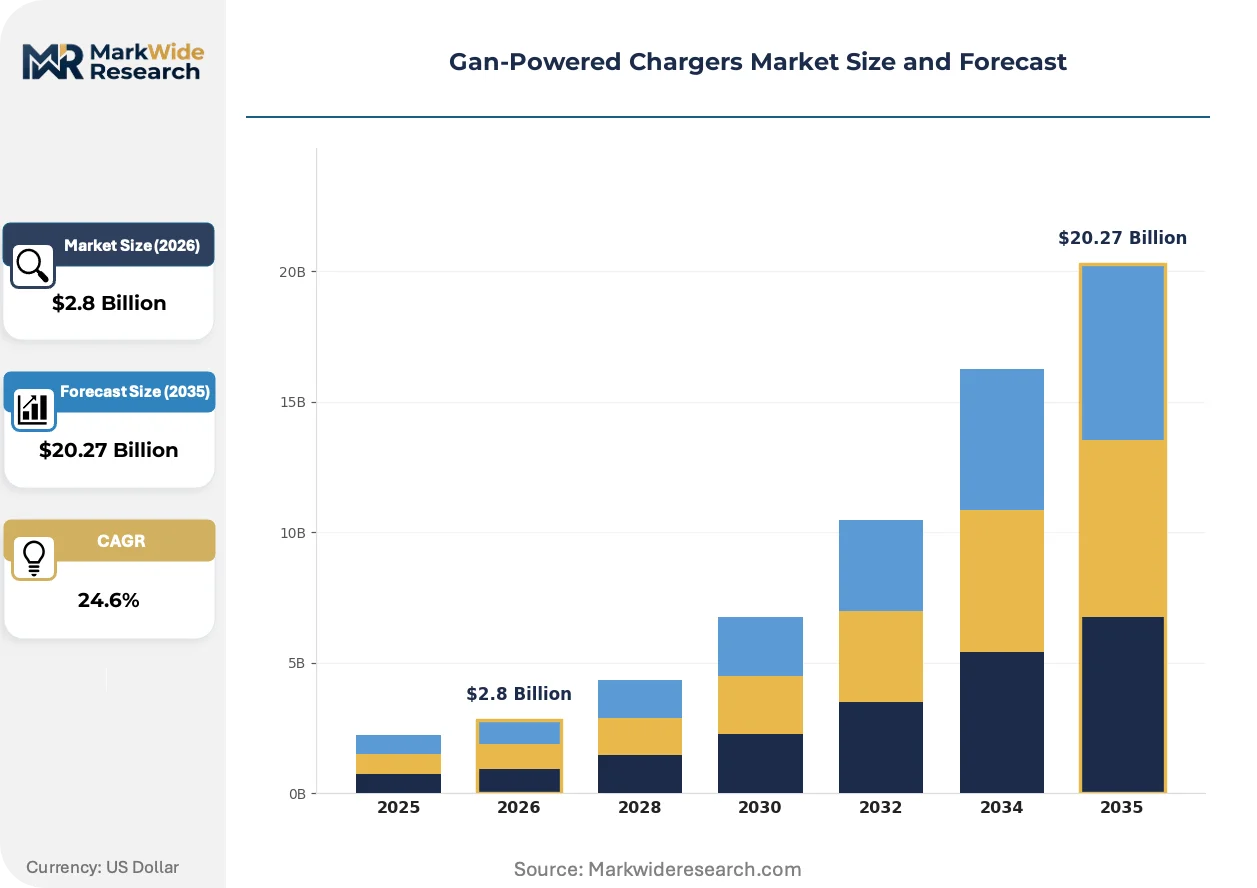
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Car Chargers, Portable Chargers, Desktop Chargers, Fast Chargers Technology: GaN FET, GaN HEMT, Hybrid GaN, Multi-Stage GaN Application: Consumer Electronics, Industrial Equipment, Automotive Electronics, Aerospace Systems, Telecommunications End User: Device Manufacturers, Equipment Integrators, System Providers, Technology Distributors |
| Companies Covered | Anker Innovations Technology Co., Ltd., Belkin International, Inc., Baseus Technology, AUKEY Technology Co., Ltd., RAVPower, Xiaomi Corporation, Samsung Electronics Co., Ltd., Apple Inc., Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan-Powered Chargers Market Shifts & Advancements
Active developments across three vectors are compressing product lifecycles and redrawing competitive boundaries in power adapter markets.
GaN-on-SiC hybrid architectures are rewriting thermal performance benchmarks for adapters above 150W. Gaming laptop OEMs and workstation manufacturers are qualifying these devices for mobile power brick applications. The technology is rewriting the traditional tradeoff between power density and thermal stability that constrained silicon-based designs.
China's GB 4943.1 safety standard revisions are mandating stricter isolation requirements for fast-charging adapters. Domestic OEMs are redesigning transformer architectures to meet creepage distance specifications. The regulation is most affecting Shenzhen-based exporters targeting European and North American distribution channels.
Enterprise procurement of universal docking stations is displacing bundled single-device chargers in corporate refresh cycles. IT departments are standardizing on multi-port GaN hubs to reduce cable clutter and support hybrid work arrangements. This pattern is most visible in North American and Western European technology procurement budgets.
Gan-Powered Chargers Market Segmentation
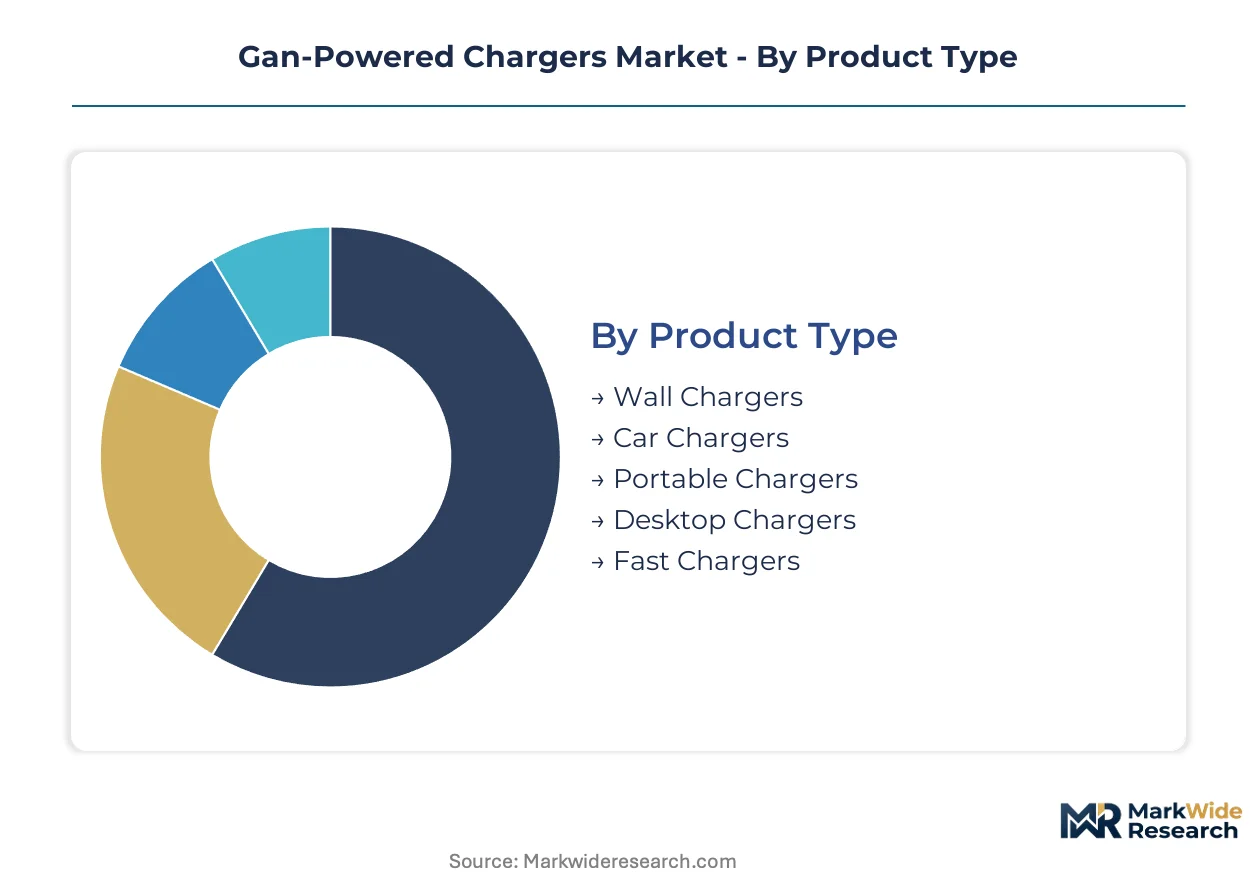
GaN-powered chargers fragment across four structural dimensions that determine pricing power, certification burden, and channel access. Product form factors and semiconductor architectures create distinct margin tiers, while application verticals impose divergent thermal and reliability specifications.
Product Type:
Standalone wall adapters dominate unit economics, but embedded automotive modules command premium pricing through qualification rigor.
- Wall Chargers:Single-port and multi-port adapters for residential and office environments. Volume concentrates in Shenzhen export manufacturing serving European USB-C harmonization mandates; FCC Part 15 emissions compliance adds certification overhead for North American distribution.
- Fast Chargers:Adapters exceeding 65W output with active cooling or advanced thermal packaging. Smartphone OEM bundling programs in China and South Korea drive procurement scale; thermal management thresholds above 100W create qualification barriers for second-tier suppliers.
- Car Chargers:Cigarette-lighter and USB-PD adapters for vehicle cabin power.
- Portable Chargers:Battery-integrated power banks with GaN input/output stages.
- Desktop Chargers:Multi-port hubs for workstation and enterprise docking applications.
Volume placements concentrate in Wall Chargers; the faster expansion belongs to Fast Chargers.
Technology:
Device architecture determines switching frequency capability, thermal dissipation requirements, and foundry sourcing flexibility.
- GaN HEMT:High-electron-mobility transistors optimized for power conversion above 100 kHz. Automotive electronics OEMs in Germany and Japan are qualifying these for onboard DC-DC conversion; MEE dual carbon goals in China accelerate domestic HEMT wafer capacity expansion.
- GaN FET:Field-effect transistor structures for lower-frequency consumer applications. Wall charger producers in India leverage PLI scheme incentives to localize FET-based adapter assembly; cost compression from Shenzhen wafer imports sustains margin pressure.
- Hybrid GaN:Architectures combining GaN switching with silicon driver integration.
- Multi-Stage GaN:Cascaded topologies for ultra-high-density applications above 150W.
GaN FET captures current volume leadership; GaN HEMT posts the steepest expansion trajectory.
Application:
End-use verticals impose divergent operating temperature ranges, shock resistance, and electromagnetic compatibility standards.
- Consumer Electronics:Smartphones, laptops, tablets, and wearables. EU Ecodesign Directive efficiency mandates are eliminating silicon-based adapters from European retail channels; OEMs in China and South Korea are consolidating procurement around 65W-140W GaN SKUs.
- Automotive Electronics:EV cabin electronics, onboard chargers, and DC-DC converters. German and Japanese automotive OEMs specify GaN topologies for weight reduction in electric vehicle power distribution; AEC-Q101 qualification timelines extend product development cycles.
- Industrial Equipment:Factory automation, robotics, and process control systems.
- Telecommunications:Base station power supplies and network infrastructure.
- Aerospace Systems:Avionics and satellite power conversion with radiation-hardened requirements.
Consumer Electronics anchors present volume; Automotive Electronics is climbing the fastest.
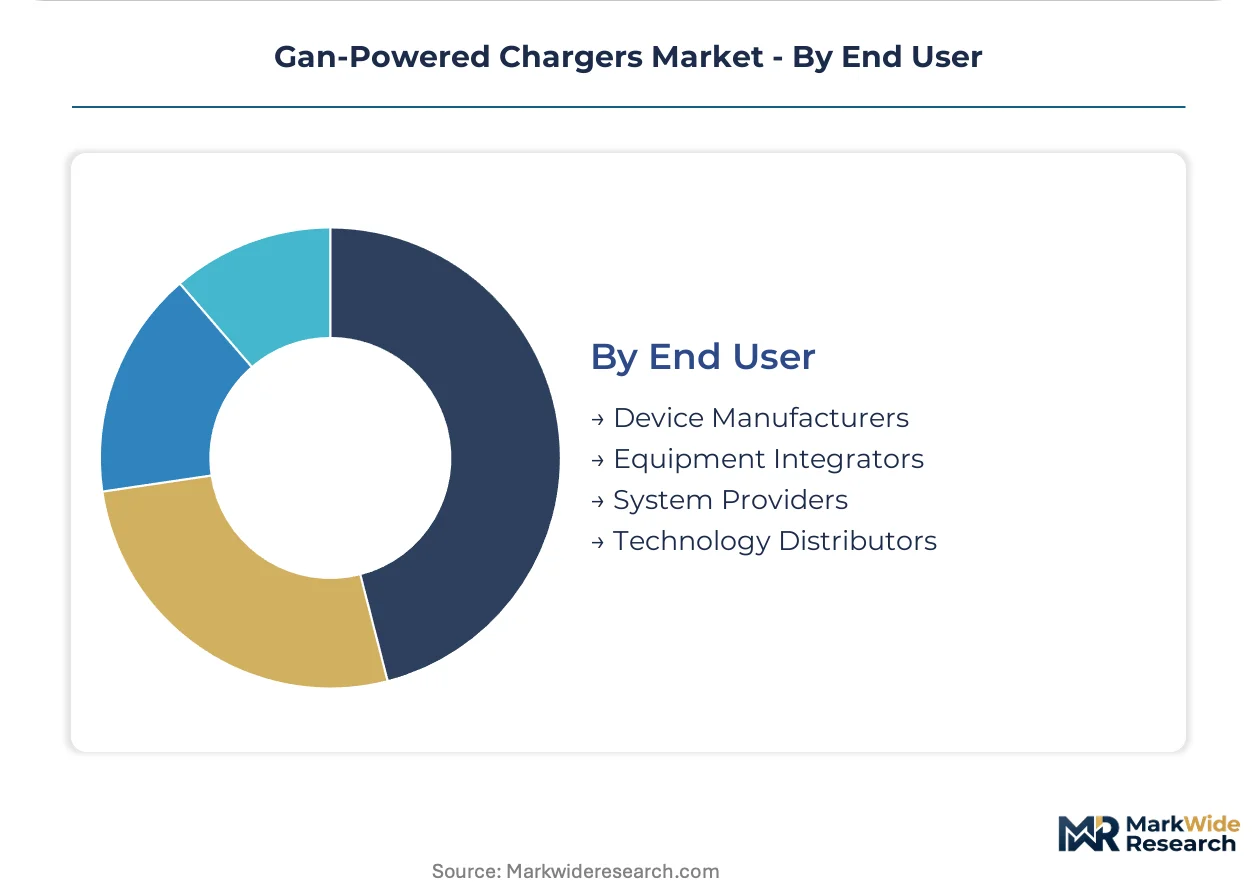
End User:
Procurement authority sits with distinct organizational functions that prioritize cost, certification, or supply security differently.
- Device Manufacturers:Consumer electronics OEMs bundling chargers with finished products. Samsung Electronics and Xiaomi Corporation operate captive procurement organizations in China; EU AI Act cybersecurity labeling requirements are adding chipset authentication specifications to sourcing criteria.
- Equipment Integrators:Industrial and automotive tier suppliers embedding GaN modules into larger systems. German automotive suppliers qualify GaN HEMT devices through KBA-type approval pathways; thermal management thresholds favor multi-source qualification strategies.
- System Providers:Data center and telecommunications infrastructure operators.
- Technology Distributors:Channel intermediaries stocking retail and enterprise SKUs.
Device Manufacturers command dominant procurement volume; Equipment Integrators are gaining share fastest through automotive qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity gallium refining capacity concentrates in Chinese industrial zones, creating geographic dependency for GaN epitaxial wafer feedstock. Shenzhen's Pearl River Delta semiconductor clusters dominate device fabrication and finished charger assembly. Regulatory divergence across major economies is fragmenting certification timelines and channel access protocols.
United States
FCC Part 15 emissions standards govern RF interference limits for GaN chargers entering North American retail channels. The Inflation Reduction Act's domestic content provisions are pressuring electronics OEMs to evaluate onshore assembly alternatives. California's energy efficiency regulations under Title 20 extend beyond federal minimums, creating a bifurcated compliance landscape for multi-state distributors.
China
MEE dual carbon goals accelerate domestic GaN HEMT wafer capacity expansion for power electronics applications. GB 4943.1 safety standard revisions mandate stricter isolation requirements for fast-charging adapters targeting export markets. Shenzhen-based ODM clusters compress device costs through concentrated GaN-on-Si fabrication and finished goods assembly integration.
Germany
KBA-type approval pathways govern GaN module qualification for automotive DC-DC conversion in electric vehicle power distribution systems. The EU Ecodesign Directive's mandatory efficiency standards are eliminating silicon-based adapters from German retail channels. Bavarian automotive suppliers qualify GaN HEMT devices through extended thermal management protocols.
India
PLI scheme production-linked incentives attract GaN charger assembly investments outside Chinese supply chains. BIS certification requirements for electronics imports create domestic manufacturing pull for finished adapter production. Tamil Nadu and Karnataka electronics manufacturing clusters host emerging GaN FET-based assembly operations serving regional consumer demand.
South Korea
MFDS-equivalent safety frameworks for power electronics align with international IEC standards for fast-charging adapter certification. Samsung Electronics and domestic smartphone OEMs consolidate procurement around 65W-140W GaN SKUs for premium device bundling. Seoul Capital Area semiconductor design houses specialize in high-frequency magnetics integration for compact adapter form factors.
Gan-Powered Chargers Market Competitive Landscape
Global majors compete with regional champions across certification expertise and foundry access, producing a tiered structure where scale-driven electronics conglomerates share space with specialized power adapter houses. The vendor base stratifies across captive semiconductor fabrication, fabless design, and pure-play assembly tiers. Three archetypes dominate: vertically integrated consumer electronics OEMs with captive chip sourcing, Shenzhen-based ODMs with compressed cost structures, and premium accessory specialists with retail brand equity. Dominant competitive moves include backward integration into GaN wafer supply and geographic diversification of assembly capacity to mitigate single-region exposure.
Among Shenzhen-based fabricators, Anker Innovations Technology Co., Ltd. exemplifies vertical control from chip sourcing through retail packaging, while Baseus Technology occupies a position in the cost-optimized fast-charging tier. Samsung Electronics Co., Ltd. anchors premium smartphone bundling strategies, representing the captive procurement archetype where device manufacturers internalize charger supply. These three companies illustrate divergent margin control strategies across voltage tiers and geographic markets.
| Leading Market Players |
|---|
| Anker Innovations Technology Co., Ltd. |
| Belkin International, Inc. |
| Baseus Technology |
| AUKEY Technology Co., Ltd. |
| RAVPower |
| Xiaomi Corporation |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Huawei Technologies Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU Ecodesign Directive efficiency mandates are forcing silicon-to-GaN transitions across European retail channels, compelling suppliers to absorb certification costs while buyers demand 65W-140W performance tiers at silicon-equivalent price points. This procurement pressure concentrates margin compression on Shenzhen-based ODMs and Indian PLI-scheme assemblers competing for volume placements.
Pricing Analysis
Warranty and after-sales service bundling separates premium GaN charger tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects AEC-Q101 automotive qualification, CE/FCC dual certification, and Shenzhen export manufacturing scale. Price differentiation hinges on thermal packaging sophistication and multi-jurisdiction approval stacks. Cost compression in 65W-100W fast chargers is intensifying because Shenzhen wafer imports sustain margin pressure. Enterprise procurement teams demonstrate lowest price sensitivity; mass-market distributors face highest.
Supply Chain Analysis
Single-source vulnerability sits with high-purity gallium refining concentrated in Chinese industrial zones. GaN HEMT fabrication draws from Shenzhen, Taiwan, and South Korean foundry capacity; high-purity gallium, sapphire substrates, and copper magnetics anchor input dependencies. Tariff exposure on Chinese semiconductor imports generates geopolitical supply risk for non-Chinese OEMs. Distribution runs through Shenzhen ODM clusters, German automotive tier suppliers, and North American enterprise technology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated players with captive GaN wafer access, as EU cybersecurity labeling and multi-jurisdiction certification stacks force sub-scale competitors into acquisition or exit.
For Market Incumbents: Anticipate margin erosion from Indian PLI-scheme assemblers by securing multi-source GaN HEMT qualification through Taiwanese and South Korean foundries. Invest in embedded authentication chipsets to capture EU AI Act cybersecurity labeling first-mover advantage. Channel control through enterprise docking station procurement contracts offers defensive positioning against Shenzhen cost leaders. For New Entrants and Emerging Players: GaN-on-SiC hybrid architectures above 150W offer technology-first wedge into gaming laptop and workstation power brick segments underserved by incumbent silicon carbide alternatives. India's Tamil Nadu and Karnataka electronics clusters present the most penetrable geography for GaN FET-based assembly outside Chinese supply chains. Direct enterprise sales to IT procurement departments bypass retail channel saturation. For Investors and Strategic Acquirers: The window for entry favors fabless GaN design houses with AEC-Q101 automotive qualification pipelines. Long-term viability rests on backward integration into gallium refining or captive foundry partnerships. Watch German KBA-type approval timelines for EV cabin electronics as the inflection indicator for automotive segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Wafer Supply | Captive sourcing from Shenzhen or Taiwanese foundries insulates margins from gallium price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FCC Part 15, CE marking, and GB 4943.1 approval stacks accelerate product launch velocity. |
| Enterprise Docking Station Partnership | Direct procurement contracts with North American IT departments displace bundled single-device chargers. |
| Automotive AEC-Q101 Qualification | German KBA-type approval pathways open EV cabin electronics and onboard DC-DC conversion segments. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Karnataka assembly operations diversify supply chain exposure beyond Chinese clusters. |
Research Methodology
SEC 10-K filings, EU Ecodesign regulatory databases, and customs trade records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with GaN device engineering leads, consumer electronics procurement managers, automotive tier supplier qualification officers, and Shenzhen ODM operations directors validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled wafer capacity data with finished charger shipment volumes.
Bottom-up modeling segmented the market by product type, semiconductor architecture, application vertical, and end-user procurement authority across the analysis window. GaN HEMT versus GaN FET technology splits, 65W/100W/150W power tier penetrations, and regional certification requirement stacks anchored forecast inputs. CAGRs derived from shipment volume trajectories and average selling price compression curves.
Several conditions sit outside the modeled scope, including gallium substrate price volatility, geopolitical trade restriction escalations, and wireless power convergence disruption. Forecasts reflect assumptions about EU regulatory harmonization and Chinese dual carbon policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Power Discrete and Modules Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Telecom Power Systems Market
Power Systems
Japan Surge Protector Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
AC Voltage Transducer Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Embedded Power Generation Market
Power Systems
Global Frequency Converter Market
Power Systems
Solid State Power Controller Market
Power Systems
Laptop Battery Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Synchrophasors Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Shunt Voltage References Market