
 Thyristor Surge Protectors Market | 2026-2036
Thyristor Surge Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Thyristor Surge Protectors Market Analytics
Industrial facilities are unwinding legacy reliance on residential surge protection as data centers command larger procurement volumes. Littelfuse leverages vertical integration in silicon-controlled rectifier fabrication to secure raw material pipelines. STMicroelectronics anchors European supply through specialized foundry capacity in France and Italy. Bourns competes via automotive-qualified thyristor portfolios that cross-apply to industrial surge applications.
Thyristor surge protectors are semiconductor devices employing silicon-controlled rectifier structures with precise breakover voltages between 50V and 600V, designed to clamp transient overvoltages within nanoseconds across power distribution networks. AC surge protectors lead unit shipments due to universal grid connectivity requirements, while modular surge protectors represent the fastest-growing configuration as facility operators prioritize field-replaceable units over hardwired installations. Thyristor-based designs command premium positioning against metal oxide varistor alternatives where response time and endurance cycles determine specification wins.
IEC 61643-11, UL 1449, and GB/T 18802 standards define clamping voltage tolerances and endurance testing protocols that determine product certification and market access across Europe, North America, and China. The EU Green Deal and China's dual carbon goals accelerate replacement of legacy protection systems with energy-efficient thyristor alternatives in grid infrastructure. Stakeholders must monitor evolving certification harmonization between IEC and national Chinese standards to anticipate qualification barriers in the largest demand concentration.
Market Dynamics
Data center operators are forcing a specification upgrade across surge protection procurement, prioritizing nanosecond response times and endurance cycles that legacy metal oxide varistor designs cannot satisfy.
Growth Catalysts
- Grid Modernization Mandates:China's dual carbon goals and State Grid infrastructure buildouts are mandating replacement of electromechanical protection with solid-state thyristor alternatives in substation automation systems.
- 5G Base Station Rollouts:Telecom infrastructure deployment concentrates procurement volumes for compact, high-reliability surge protection modules in outdoor cabinet installations.
- IEC 61643-11 Harmonization:The tightening of clamping voltage tolerances and endurance testing protocols across Europe is disqualifying non-compliant legacy products from certified installations.
Market Restraints
- Silicon Wafer Supply Concentration:Foundry capacity for specialized silicon-controlled rectifier fabrication clusters in France, Italy, and Taiwan, creating single-source vulnerability for European device vendors.
- Metal Oxide Varistor Cost Advantage:Zinc oxide disc production achieves economies of scale that thyristor wafer processing cannot match for residential and light commercial applications.
- UL 1449 Certification Friction:The updated surge current testing requirements and let-through voltage verification protocols extend qualification timelines for new product introductions in North American markets.
Strategic Opportunities
- Modular Field-Replaceable Architectures:Facility operators in Germany and the Netherlands are specifying pluggable surge protection modules to minimize maintenance downtime in critical power distribution nodes.
- Automotive-Industrial Crossover:Electric vehicle charging infrastructure standards are converging with industrial surge protection specifications, opening qualification pathways for automotive-qualified component portfolios.
- EU Green Deal Retrofit Cycles:Energy efficiency mandates for grid infrastructure are accelerating replacement schedules for electromechanical protection systems with semiconductor-based alternatives.
Industry Challenges
- Power Semiconductor Design Talent Scarcity:Expertise in silicon-controlled rectifier breakover voltage engineering and thermal management is concentrated among aging specialists in European and Japanese device houses.
- Multi-Standard Certification Burden:Simultaneous qualification against IEC 61643-11, UL 1449, and GB/T 18802 protocols strains engineering resources and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyristor Surge Protectors Market |
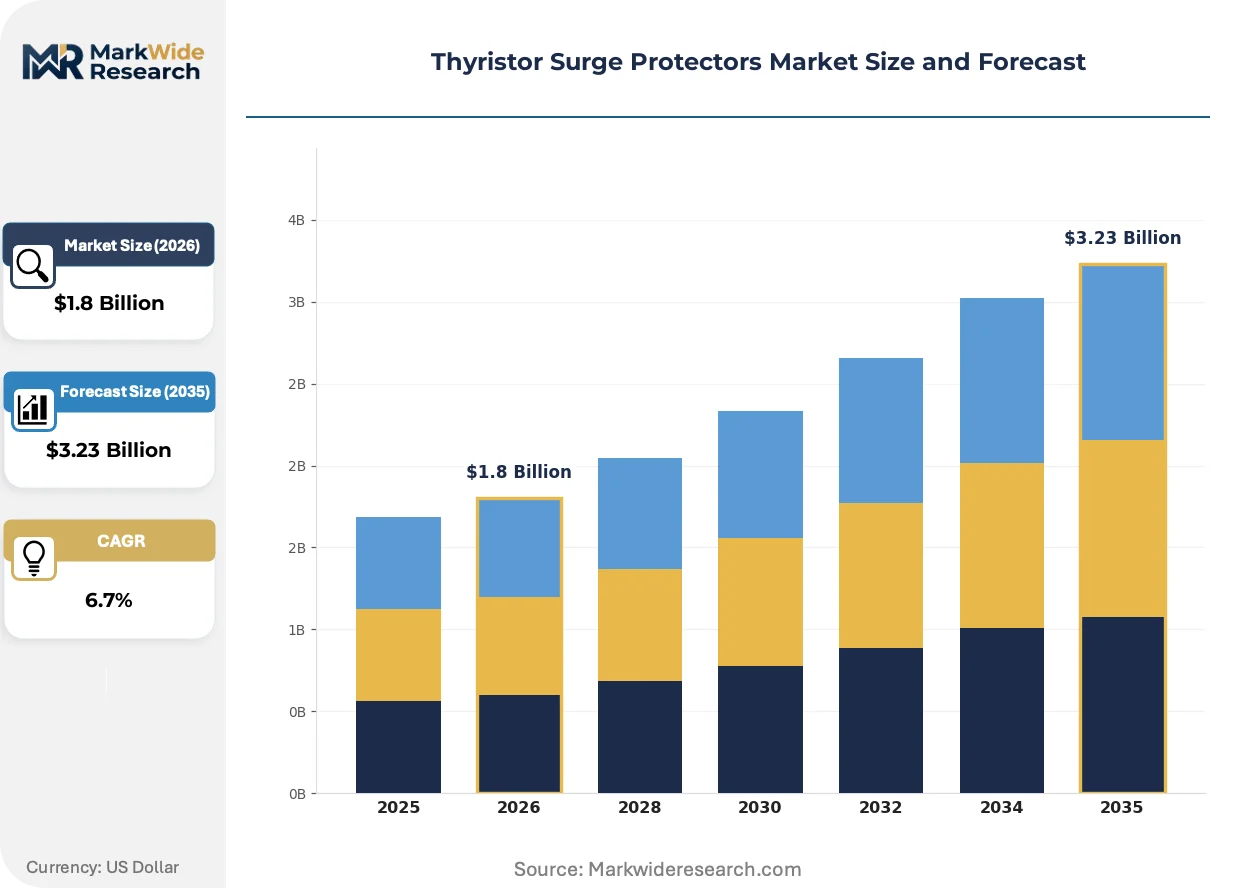
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Surge Protectors, DC Surge Protectors, Modular Surge Protectors, Integrated Surge Protectors End User: Residential Users, Commercial Establishments, Industrial Facilities, Data Centers Installation Type: Panel-Mounted, Inline, Wall-Mounted, Portable Technology: Metal Oxide Varistors, Gas Discharge Tubes, Thyristor-Based Designs, Others |
| Companies Covered | Unictron Technologies Corporation, Diodes Incorporated, STMicroelectronics, Littelfuse, ON Semiconductor, ProTek Devices, TE Connectivity, Bourns, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyristor Surge Protectors Market Evolving Landscape
Semiconductor process advances and procurement specification upgrades are splitting the surge protection market into performance-tiered segments that reward response-time superiority over cost minimization.
Silicon-controlled rectifier structures with precise breakover voltages between 50V and 600V are displacing legacy protection technologies in mission-critical power distribution applications. Data center operators and telecom infrastructure deployers are specifying these devices for primary protection layers where downtime costs dwarf component price premiums. The technology is bifurcating the market into specification-driven premium tiers and commodity metal oxide varistor alternatives.
The EU Green Deal and China's dual carbon goals are accelerating replacement of electromechanical protection systems with energy-efficient thyristor alternatives in grid infrastructure. These mandates compress payback period calculations for utilities evaluating solid-state protection upgrades. European transmission system operators and Chinese provincial grid companies are prioritizing semiconductor-based solutions in retrofit procurement specifications.
Facility operators are specifying modular surge protector configurations over hardwired installations to enable field replacement without service interruption. Industrial maintenance departments and critical facility managers are driving this preference shift toward pluggable units with standardized footprints. Germany and the Netherlands exhibit the strongest concentration of this procurement pattern in European data center and manufacturing facility buildouts.
Thyristor Surge Protectors Market Segmentation
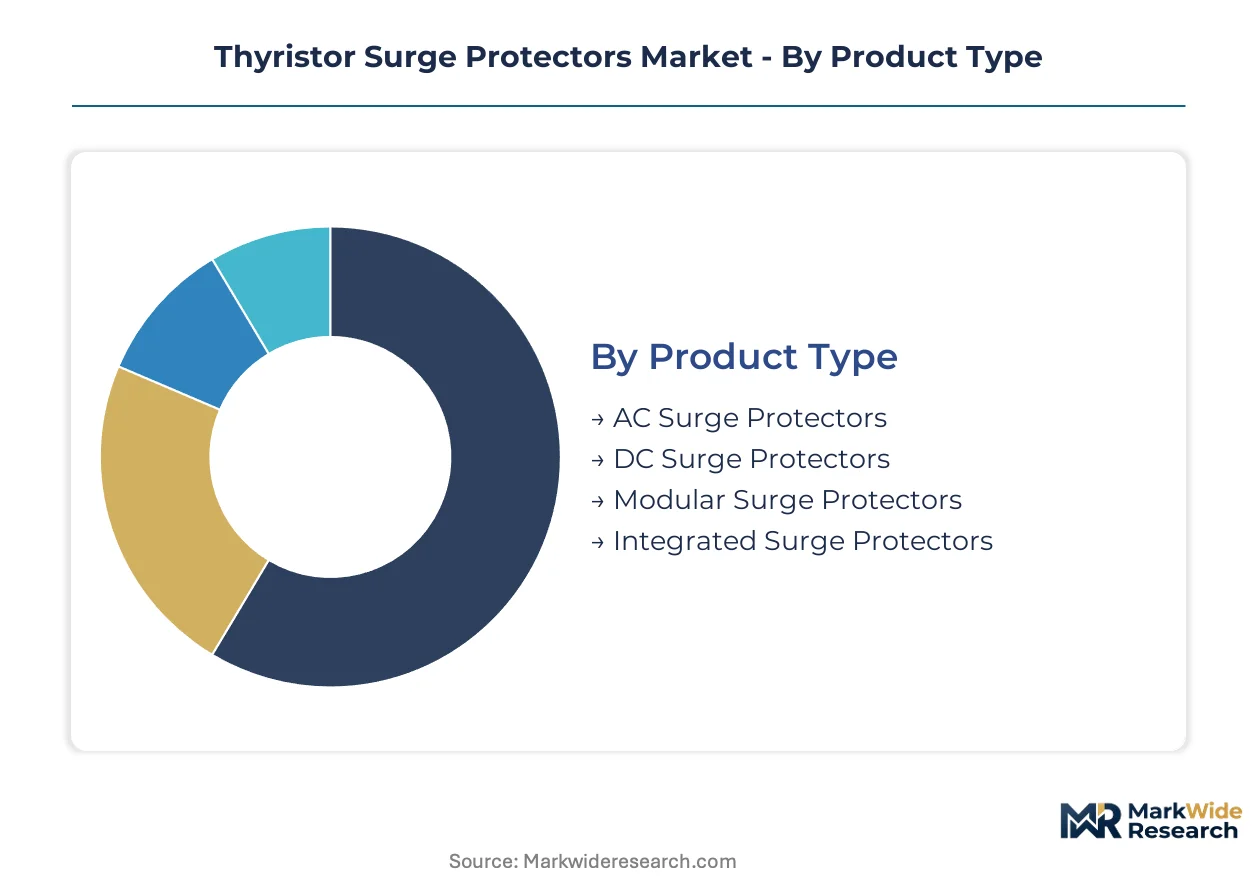
Thyristor surge protector procurement splits across performance tiers where response-time specifications determine substitution vulnerability. Segment boundaries harden around certification thresholds that disqualify legacy technologies from mission-critical installations.
Product Type:
Metal oxide varistor alternatives exert substitution pressure most acutely in segments where nanosecond response thresholds remain unspecified.
- AC Surge Protectors:Silicon-controlled rectifier structures rated for 50V-600V breakover clamp grid-side transients in distribution networks. Universal grid connectivity requirements concentrate procurement in Chinese provincial utilities and European transmission system operators modernizing substation automation.
- Modular Surge Protectors:Field-replaceable pluggable units with standardized footprints eliminate service interruption during maintenance cycles. German and Dutch facility operators specify these configurations for critical power distribution nodes in data center and manufacturing buildouts.
- DC Surge Protectors:Specialized breakover engineering addresses photovoltaic inverter and battery storage protection requirements.
- Integrated Surge Protectors:Multi-stage protection combining thyristor primary clamping with secondary suppression elements.
AC Surge Protectors retain volume leadership; Modular Surge Protectors hold the steepest expansion curve.
End User:
Cost-tier stratification separates specification-driven premium procurement from price-sensitive residential replacement cycles.
- Data Centers:Hyperscale operators mandate nanosecond response times and endurance cycles beyond metal oxide varistor capabilities. Procurement volumes concentrate in Virginia, Frankfurt, and Singapore facility clusters where downtime costs dwarf component premiums.
- Industrial Facilities:Manufacturing plants and process industries specify thyristor-based primary protection layers. Chinese State Grid infrastructure buildouts and EU Green Deal retrofit mandates accelerate solid-state replacement of electromechanical systems.
- Commercial Establishments:Office complexes and retail infrastructure balance performance requirements against installed cost constraints.
- Residential Users:Price sensitivity sustains metal oxide varistor dominance in single-family and multi-unit dwelling applications.
Data Centers command the specification upgrade momentum; Industrial Facilities anchor replacement volume in grid modernization programs.
Installation Type:
Maintenance accessibility requirements reshape preferences toward configurations minimizing technician dispatch and service interruption.
- Panel-Mounted:Hardwired integration into electrical distribution panels dominates legacy infrastructure. Industrial facilities in established manufacturing regions retain this architecture where retrofit economics favor complete panel replacement over modular upgrade.
- Inline:Series-connected protection for dedicated equipment feeds in telecom and renewable energy applications. 5G base station outdoor cabinet installations specify compact inline modules for space-constrained deployments.
- Wall-Mounted:Surface-mounted units for secondary protection layers in commercial and light industrial settings.
- Portable:Temporary protection for construction sites and emergency response applications.
Panel-Mounted installations retain installed base dominance; Inline configurations gain share fastest in telecom infrastructure deployment.
Technology:
Response-time performance hierarchies determine competitive displacement dynamics across protection technology classes.
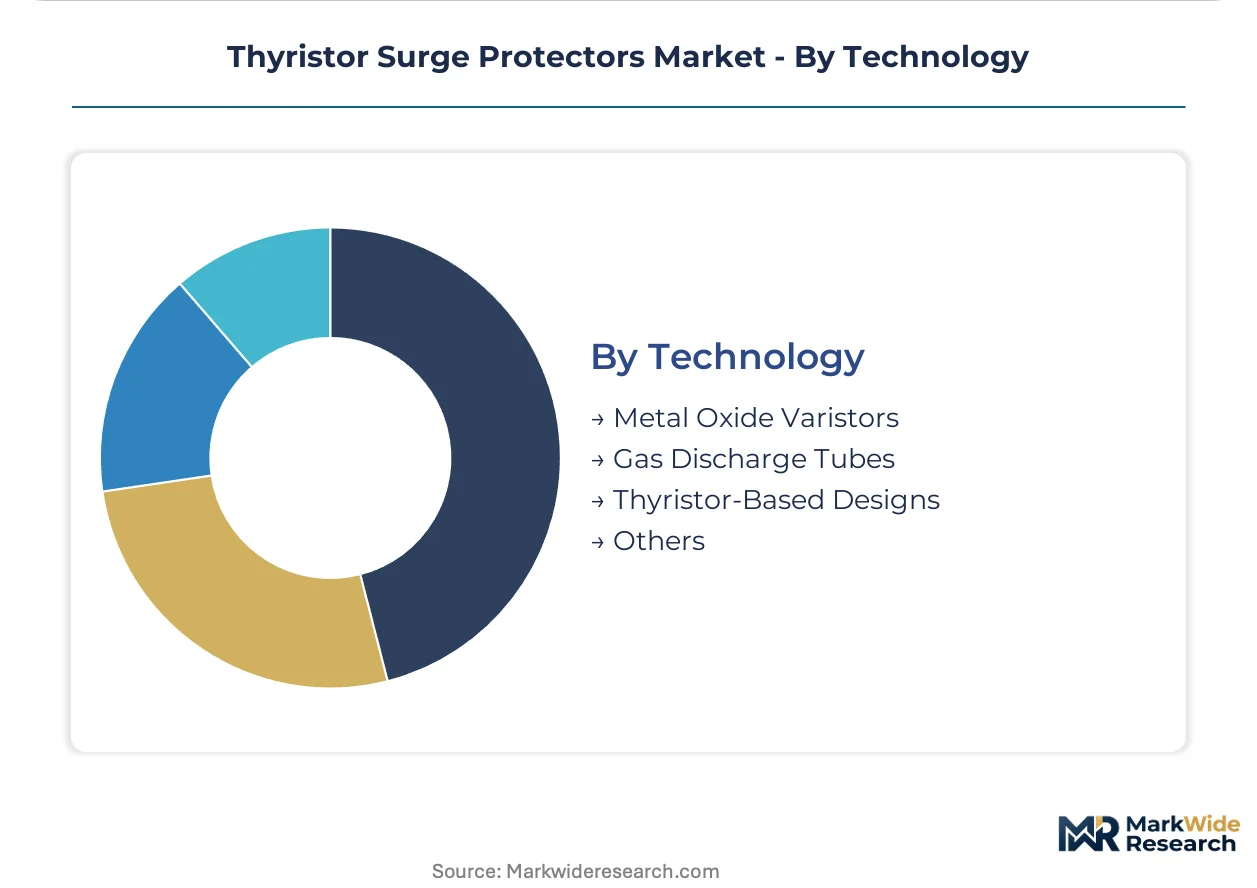
- Thyristor-Based Designs:Precise breakover voltage engineering delivers nanosecond clamping for mission-critical applications. IEC 61643-11 and UL 1449 tightening of performance thresholds expands addressable market against legacy alternatives.
- Metal Oxide Varistors:Zinc oxide disc production achieves cost structures thyristor wafer processing cannot match. Residential and light commercial applications retain this technology where response-time specifications remain unenforced.
- Gas Discharge Tubes:High-energy handling for primary lightning protection stages in outdoor telecommunications infrastructure.
- Others:Hybrid and emerging semiconductor protection architectures.
Metal Oxide Varistors retain volume leadership in cost-sensitive tiers; Thyristor-Based Designs climb the fastest as certification standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export thyristor surge protection modules to European data center operators and North American telecom infrastructure deployers, creating a trade corridor that concentrates procurement volumes in Frankfurt, Virginia, and Singapore facility clusters.
China
State Grid infrastructure buildouts and 5G base station rollouts drive procurement volumes for solid-state protection devices. The dual carbon goals mandate replacement of electromechanical systems with semiconductor alternatives in provincial substations. Yangtze River Delta and Pearl River Delta manufacturing hubs supply compact modules for outdoor telecom cabinets.
Germany
Data center operators in Frankfurt and manufacturing facilities across Baden-Württemberg specify modular field-replaceable configurations. The EU Green Deal accelerates retrofit schedules for electromechanical protection in transmission infrastructure. Bavarian industrial automation clusters prioritize nanosecond response specifications in primary protection layers.
United States
Hyperscale data centers in Northern Virginia and Texas command premium-tier procurement with endurance requirements beyond metal oxide varistor capabilities. UL 1449 updated testing protocols extend qualification timelines for new product introductions. Pacific Northwest renewable energy installations drive DC surge protector demand for battery storage integration.
Japan
Automotive-industrial crossover applications emerge as electric vehicle charging infrastructure standards converge with industrial protection specifications. METI efficiency mandates compress payback calculations for solid-state grid upgrades. Kanto region semiconductor device houses concentrate expertise in silicon-controlled rectifier breakover engineering.
Netherlands
Randstad data center operators specify pluggable surge protection modules to minimize maintenance downtime in critical power nodes. REACH and RoHS compliance requirements shape component selection for European distribution networks. Eindhoven region facility managers lead procurement preference shifts toward standardized footprint configurations.
Thyristor Surge Protectors Market Competitive Landscape
Listed leaders compete with private specialists across certification capacity and foundry access. The vendor base splits between diversified semiconductor conglomerates with captive silicon processing and focused protection device houses reliant on external foundry partnerships. Three archetypes dominate: integrated device manufacturers with backward wafer control, fabless designers leveraging specialized foundry relationships, and automotive-qualified component suppliers cross-applying industrial portfolios. Capacity expansion in European silicon-controlled rectifier fabrication and strategic partnerships for Chinese market access represent the dominant competitive vectors.
Among diversified semiconductor conglomerates, STMicroelectronics anchors European supply through specialized foundry capacity in France and Italy, while Littelfuse occupies a position exemplifying backward integration into silicon-controlled rectifier fabrication to secure raw material pipelines. Bourns represents the automotive-industrial crossover archetype, with automotive-qualified portfolios that translate into industrial surge applications.
| Leading Market Players |
|---|
| Unictron Technologies Corporation |
| Diodes Incorporated |
| STMicroelectronics |
| Littelfuse |
| ON Semiconductor |
| ProTek Devices |
| TE Connectivity |
| Bourns |
| Infineon Technologies |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between European data center operators and specialized silicon-controlled rectifier foundries lock in wafer supply access while anchoring price visibility across multi-year procurement cycles. These contracts insulate qualified vendors from spot-market silicon price volatility while binding buyers to volume commitments that sustain foundry utilization rates.
Pricing Analysis
Next-generation thyristor designs with sub-nanosecond response specifications command 40-60% premiums over prior-generation metal oxide varistor alternatives, while current-generation silicon-controlled rectifier structures occupy a mid-tier position. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61643-11 certified modules from UL 1449 qualified units and uncertified commodity alternatives. Cost compression in the economy tier is intensifying because zinc oxide disc production achieves scale economies that specialized wafer processing cannot match. Data center operators exhibit the lowest price sensitivity, while residential distributors remain highly responsive to unit cost differentials.
Supply Chain Analysis
Inventory buffers for specialized silicon wafers extend lead times to 16-20 weeks during foundry capacity constraints, compressing procurement flexibility for European device vendors. Foundry capacity clusters in France, Italy, and Taiwan, with raw material supply drawing from polysilicon producers in Germany and metallurgical-grade silicon refiners in Norway. Single-source vulnerability concentrates in European silicon-controlled rectifier fabrication, where aging specialist expertise limits rapid capacity expansion. Distribution runs through authorized distributors serving industrial automation and telecom infrastructure verticals, with direct OEM relationships dominating data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators and Chinese State Grid procurement consortia, fragmenting the vendor landscape into performance-tiered supply tiers that reward certification depth over cost minimization.
For Market Incumbents: Shield market position by deepening captive silicon-controlled rectifier fabrication capacity in France and Italy before foundry bottlenecks harden. Prioritize simultaneous IEC 61643-11, UL 1449, and GB/T 18802 qualification investments to disqualify emerging competitors from certified installation pipelines. Metal oxide varistor cost advantages in residential tiers threaten volume retention.
For New Entrants and Emerging Players: GB/T 18802 fast-track certification in China opens access to the largest provincial utility procurement volumes before harmonization with IEC standards raises qualification barriers. Target modular field-replaceable configurations in German and Dutch data center buildouts where maintenance accessibility specifications remain undersupplied. Partner with automotive-qualified component houses to leverage existing industrial crossover portfolios.
For Investors and Strategic Acquirers: Automotive-industrial crossover specialists with captive silicon-controlled rectifier design expertise represent the most defensible acquisition targets in a consolidating vendor landscape. Long-term viability hinges on backward integration into wafer supply or exclusive foundry partnerships that outlast the current capacity expansion cycle. Monitor IEC-GB harmonization announcements as the critical inflection signal for qualification barrier timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Wafer Supply | Captive polysilicon sourcing from German refiners insulates against Taiwan foundry bottlenecks. |
| Multi-Standard Certification Investment | Simultaneous IEC 61643-11, UL 1449, and GB/T 18802 qualification expands addressable market access. |
| Modular Field-Replaceable Product Launch | Pluggable configurations align with German and Dutch facility operator maintenance specifications. |
| Automotive-Industrial Crossover Partnership | Electric vehicle charging infrastructure standards convergence opens qualification pathways for industrial surge applications. |
| EU Green Deal Retrofit Program Engagement | Energy efficiency mandates accelerate replacement schedules for electromechanical protection in transmission infrastructure. |
Research Methodology
A spread of perspectives from data center infrastructure directors, State Grid procurement officers, semiconductor foundry operations managers, and industrial automation maintenance heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against IEC certification databases, UL product directories, and Chinese GB standard registration filings. Bottom-up unit shipment estimates triangulated with top-down value projections derived from foundry capacity utilization disclosures and hyperscaler capex allocations.
Segmentation dimensions modeled span product type, end-user vertical, installation configuration, and technology class across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capacity expansion announcements. Thyristor breakover voltage specifications and endurance cycle testing protocols served as industry-specific forecast inputs, with modular surge protector adoption curves calibrated against German and Dutch facility buildout timelines.
Underlying assumptions cover sustained State Grid infrastructure investment, continued IEC-GB standard harmonization, and stable silicon wafer supply from European foundries, with deviation risk concentrated in foundry capacity constraints and certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Amplifier Modules Market
Power Systems
Central Battery Systems Market
Power Systems
Voltage Regulators Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Power Supply and Charger Market
Power Systems
Global Synchronous Motor Market
Power Systems
Hybrid Inverters Market
Power Systems
Japan Surge Protector Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
USB Power Adapters Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Traction Inverter Market
Power Systems
Digital Inverter Market