
 Electrical and Automation System Market | 2026-2036
Electrical and Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical and Automation System Market Intelligence
IEC 61850 communication protocol compliance is bifurcating the competitive landscape into premium-certified and standard-tier suppliers. ABB Ltd leverages its substation automation heritage to dominate high-voltage integration projects. Siemens anchors its position through deep vertical integration in digital twin software and hardware bundles. Schneider Electric differentiates via energy management specialization across commercial building portfolios.
Electrical and automation systems encompass power distribution infrastructure paired with control architectures that govern motor drives, process loops, and safety interlocks using IEC 61131-3 programming environments and real-time industrial Ethernet protocols. Their primary purpose is to synchronize energy delivery with mechanical motion and process variables across continuous and discrete manufacturing operations. Programmable Logic Controllers constitute the mature revenue core, while Industrial Internet of Things platforms capture the fastest expansion as edge-to-cloud data pipelines become standard. Building Automation applications concentrate margin pools where long-term service contracts and software subscriptions overlay hardware deployments.
FDA 21 CFR Part 11 shapes validation protocols for pharmaceutical automation installations, while EU machinery directives and CE marking govern safety integrity levels for European equipment suppliers. OSHA electrical standards and NFPA 70E arc-flash requirements drive protective relay and switchgear upgrades across US industrial facilities. Stakeholders must weigh functional safety certification depth against total cost of ownership when specifying automation architectures for brownfield retrofits versus greenfield installations.
Market Dynamics
Digital twin integration is compressing commissioning cycles and forcing hardware suppliers to bundle software capabilities or cede margin to pure-play analytics vendors.
Growth Catalysts
- EU machinery directive compliance mandates:CE marking requirements for safety integrity levels are compelling brownfield facility upgrades across German automotive stamping plants and French food processing lines.
- Edge computing architectures:Real-time inference at the device level is eliminating latency penalties for predictive maintenance in US Gulf Coast petrochemical operations.
- China's eastern manufacturing belt:Provincial industrial upgrading programs in Jiangsu and Zhejiang are subsidizing PLC replacements with integrated motion-control systems.
Market Restraints
- Copper and rare-earth magnet volatility:Motor drive manufacturing faces input cost swings that erode quoted project margins before installation completion.
- Semiconductor foundry concentration:Industrial chip supply remains tethered to Taiwan and South Korean fabrication capacity with limited geographic diversification.
- IEC 61508 certification timelines:Functional safety validation for SIL 3 applications extends product development cycles by 14-18 months.
Strategic Opportunities
- India's PLI scheme for manufacturing:Automation equipment imports face tariff incentives that favor local assembly partnerships in Gujarat and Tamil Nadu industrial corridors.
- Digital thread convergence:Integration of CAD, simulation, and shop-floor execution software creates attach-rate expansion for vendors with cross-domain platforms.
- Carbon accounting mandates:CSRD reporting requirements in Europe are generating demand for energy management dashboards that overlay building automation systems.
Industry Challenges
- IEC 61850 interoperability gaps:Multi-vendor substation projects suffer integration failures when proprietary protocol extensions block seamless device communication.
- Arc-flash engineering talent scarcity:NFPA 70E compliance studies require certified specialists whose training pipelines lag project award velocity in US industrial construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical and Automation System Market |
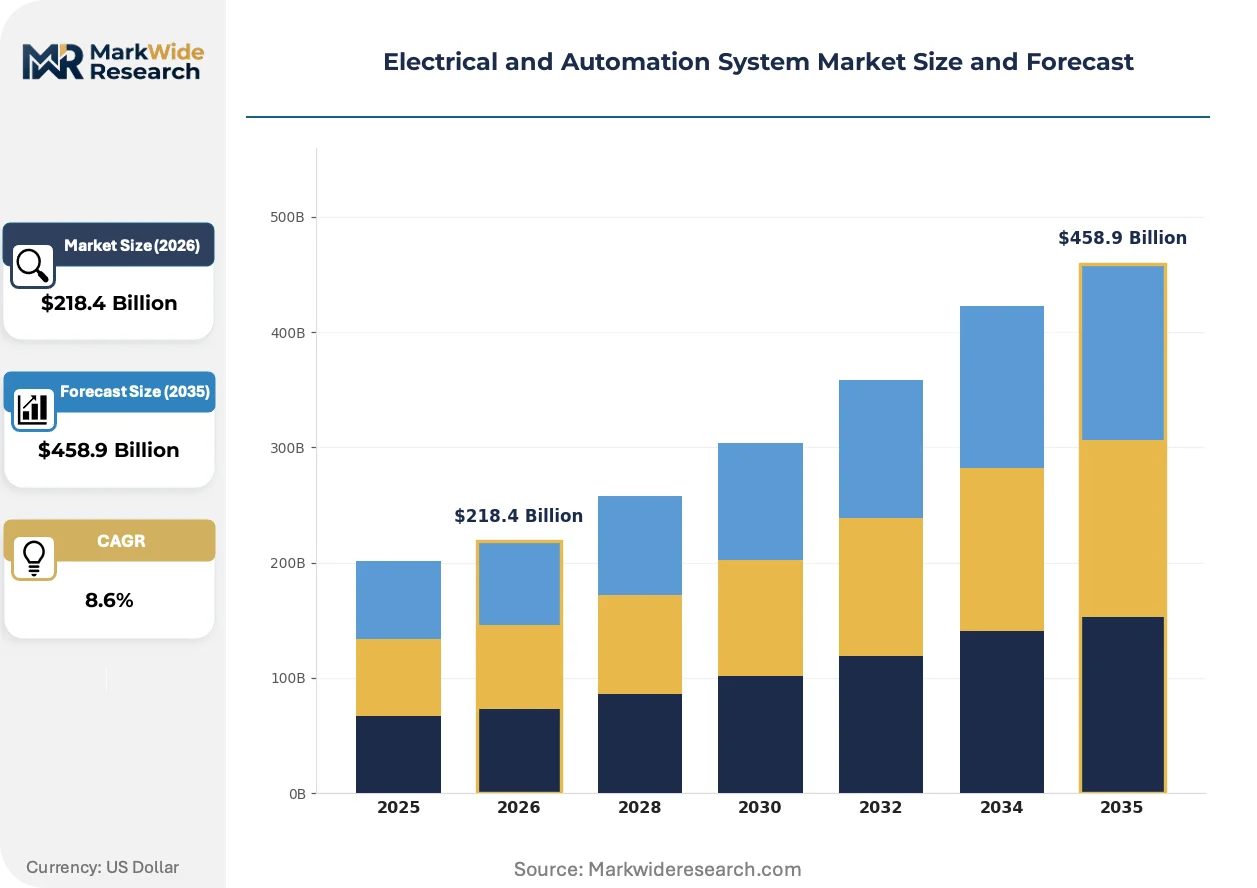
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $458.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Sensors, Human-Machine Interfaces, Switchgear Technology: Industrial Internet of Things, Machine Learning, Cloud Computing, Robotics Application: Manufacturing, Energy Management, Transportation, Building Automation End User: Oil & Gas, Pharmaceuticals, Automotive OEMs, Food & Beverage |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric, Rockwell Automation, Emerson Electric, Honeywell International, OMRON Corporation, Mitsubishi Electric Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical and Automation System Market Strategic Shifts & Innovations
Intelligent edge devices are collapsing the traditional separation between control hardware and analytics software, rewiring how automation architectures get specified and procured.
Silicon carbide power semiconductors are replacing insulated-gate bipolar transistors in motor drive applications. Automotive battery gigafactories in Germany and Hungary are adopting these devices for their switching efficiency advantages. The technology is miniaturizing drive enclosure footprints while reducing cooling infrastructure requirements.
REACH restrictions on per- and polyfluoroalkyl substances are phasing out fluoropolymer cable insulation in European industrial installations. Equipment suppliers must qualify alternative materials without degrading flame resistance or flex life ratings. German machine builders are accelerating validation programs to maintain CE marking continuity ahead of enforcement deadlines.
Buyer preference for subscription-based software licensing is displacing perpetual license models in building automation. Facility managers in US commercial real estate portfolios now prioritize vendors offering predictive analytics as a service rather than capital expenditure hardware. This compresses upfront project costs while extending vendor revenue visibility through multi-year service agreements.
Electrical and Automation System Market Segmentation
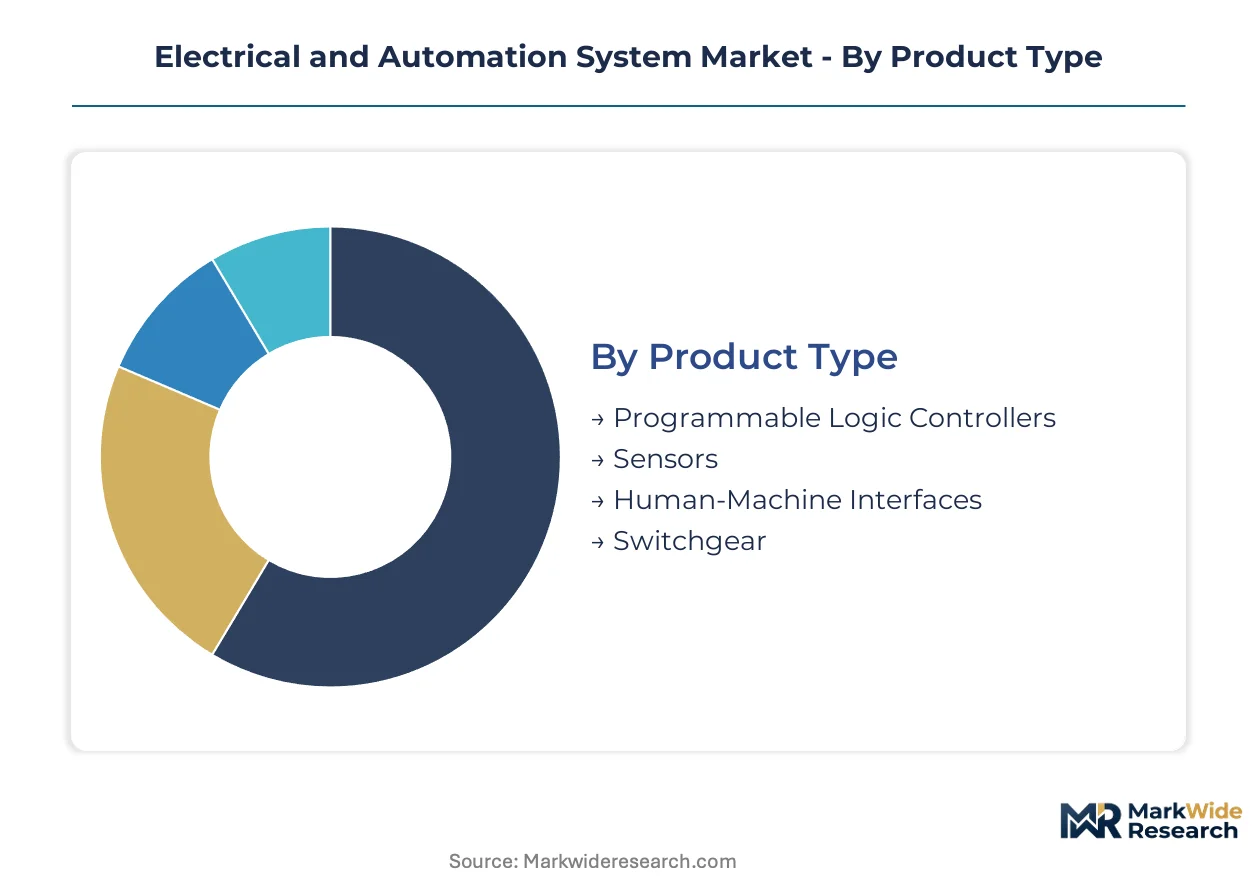
Segmentation in electrical and automation systems reveals how certification depth, protocol compatibility, and vertical specialization determine procurement patterns across industrial buyers. Regulatory divergence between IEC 61508 SIL tiers and FDA validation requirements fragments specification standards.
Product Type:
Regulatory differentiation separates safety-certified hardware from standard industrial equipment, with SIL ratings and arc-flash compliance dictating supplier qualification tiers.
- Programmable Logic Controllers:Ruggedized controllers execute ladder logic and structured text under IEC 61131-3 environments with deterministic cycle times. German automotive stamping plants and US Gulf Coast petrochemical facilities drive replacement demand as legacy systems face EU machinery directive recertification deadlines.
- Switchgear:Metal-enclosed assemblies integrate circuit breakers, bus structures, and protective relays rated for fault current interruption. Arc-flash mitigation requirements under NFPA 70E are accelerating upgrade cycles across US industrial construction, though certified engineering talent scarcity extends project timelines.
- Sensors:Industrial transducers convert physical variables to digital signals via IO-Link and HART protocols.
- Human-Machine Interfaces:Touch panels and industrial PCs provide visualization layers for SCADA and distributed control systems.
Programmable Logic Controllers handle the majority of throughput; Switchgear is expanding most quickly on share as safety retrofits accelerate.
Technology:
Cost tier stratification separates capital-intensive edge infrastructure from subscription-based analytics platforms, reshaping vendor revenue models.
- Industrial Internet of Things:Edge-to-cloud pipelines aggregate sensor streams through MQTT and OPC-UA protocols for predictive maintenance applications. China's Jiangsu and Zhejiang provincial upgrading programs subsidize integrated motion-control replacements that bundle IIoT connectivity.
- Machine Learning:Inference engines deployed at the edge eliminate latency for anomaly detection in rotating equipment. US Gulf Coast petrochemical operators prioritize real-time failure prediction over cloud-dependent batch analytics.
- Cloud Computing:SaaS platforms host digital twin simulations and remote monitoring dashboards.
- Robotics:Collaborative and industrial arms integrate servo drives with safety-rated control architectures.
Industrial Internet of Things dominates capital deployment; Machine Learning is gaining share fastest as inference shifts to edge devices.
Application:
Margin concentration varies by contract structure, with long-term service agreements and software subscriptions overlaying hardware in commercial building portfolios.
- Building Automation:Integrated systems govern HVAC, lighting, and access control through BACnet and Modbus networks. CSRD carbon accounting mandates in Europe are generating attach-rate opportunities for energy management dashboards.
- Manufacturing:Discrete and process automation synchronizes mechanical motion with process variables across PLC and DCS architectures. Automotive OEM smart factory expansions in Germany and Hungary compress commissioning cycles through digital twin integration.
- Energy Management:Power monitoring and demand response systems optimize consumption patterns.
- Transportation:Traction power and signaling automation serves rail and electric vehicle infrastructure.
Manufacturing absorbs the largest equipment volume; Building Automation is climbing the fastest as facility managers shift to subscription pricing models.
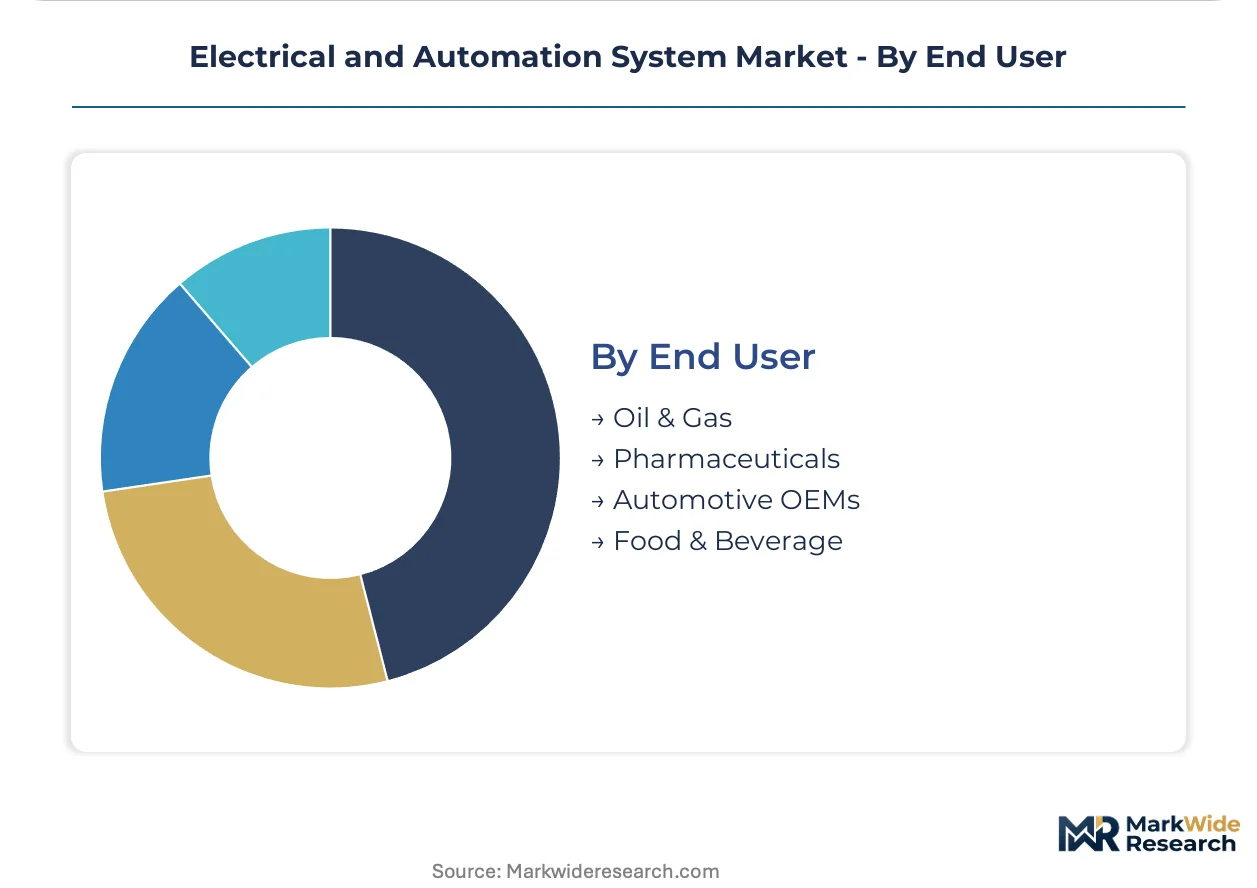
End User:
Customer type determines validation protocol complexity, with pharmaceutical and food processing facing the most stringent documentation requirements.
- Pharmaceuticals:Batch control systems require FDA 21 CFR Part 11 validation for electronic records and signatures. Serialization and track-and-trace mandates compound automation complexity for European and North American drug manufacturing.
- Oil & Gas:Explosion-proof enclosures and SIL-rated safety instrumented systems govern upstream and downstream automation. US Gulf Coast brownfield upgrades face compressed schedules as operators reconcile IEC 61508 certification timelines with production targets.
- Automotive OEMs:Battery gigafactories in Germany and Hungary adopt silicon carbide power semiconductors for drive efficiency.
- Food & Beverage:Hygienic design standards and washdown-rated enclosures comply with EU machinery directives.
Automotive OEMs command the largest project scale; Pharmaceuticals is expanding most quickly on share as biologics manufacturing capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal sharp asymmetries across major economies. Germany and China maintain substantial automation equipment trade surpluses, while India and Brazil remain net importers dependent on foreign PLC and switchgear suppliers.
Germany
Automotive battery gigafactories in Lower Saxony and Baden-Württemberg drive demand for silicon carbide motor drives and digital twin integration. CE marking requirements under EU machinery directives compress supplier qualification timelines. The industrial corridor spanning Stuttgart, Munich, and Wolfsburg concentrates smart factory retrofit investments.
China
Provincial upgrading programs in Jiangsu and Zhejiang subsidize integrated motion-control replacements with bundled IIoT connectivity. MIIT dual carbon goals accelerate energy management dashboard deployments. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou leads PLC-to-integrated system transitions.
United States
OSHA electrical standards and NFPA 70E arc-flash requirements trigger protective relay upgrades across Gulf Coast petrochemical complexes. FERC grid modernization incentives support substation automation investments. The Texas-Louisiana industrial corridor concentrates brownfield safety instrumented system retrofits.
India
PLI scheme tariff incentives favor local assembly partnerships for automation equipment in Gujarat and Tamil Nadu industrial corridors. BIS certification requirements extend product qualification cycles for imported switchgear. The Mumbai-Pune and Chennai-Bengaluru manufacturing belts anchor foreign OEM joint ventures.
Japan
METI industrial competitiveness programs fund edge computing architectures for predictive maintenance in automotive stamping plants. JIS standards govern interoperability specifications for multi-vendor substation projects. The Chubu region around Nagoya and the Kansai industrial zone concentrate servo drive and robotics integration demand.
Electrical and Automation System Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and certification depth. The market structure tilts toward consolidated premium tiers where functional safety credentials and vertical software integration determine supplier selection. Three archetypes dominate: diversified industrial conglomerates with substation heritage, pure-play automation specialists with deep PLC portfolios, and building-centric energy managers with service contract expertise. Competitive moves center on digital twin software bundling and strategic partnerships for edge-to-cloud platform completion.
Among European-based industrial conglomerates, ABB Ltd and Siemens AG exemplify the diversified archetype with heritage positions in high-voltage integration and digital twin software. Schneider Electric occupies a distinct tier as a building automation and energy management specialist. These three listed entities anchor the premium certification segment where IEC 61508 SIL ratings and IEC 61850 protocol compliance determine procurement eligibility for German automotive and US petrochemical projects.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric |
| Rockwell Automation |
| Emerson Electric |
| Honeywell International |
| OMRON Corporation |
| Mitsubishi Electric Corporation |
| Yokogawa Electric Corporation |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-month IEC 61508 certification timelines compress supplier margins and concentrate pricing power among pre-certified incumbents, while copper and rare-earth magnet volatility forces project-based quoting with material escalation clauses. Inventory buffers for silicon carbide semiconductors rarely exceed sixty days, tethering downstream pricing to Taiwanese foundry utilization rates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium-certified, standard-compliant, and economy-tier equipment levels. Certification depth under IEC 61508 SIL ratings and IEC 61850 protocol compliance drives the primary price differentiation, with German automotive and US petrochemical purchasers absorbing premiums for validated safety architectures. Cost compression in economy-tier PLCs intensifies because Chinese provincial upgrading programs flood Jiangsu and Zhejiang with subsidized integrated motion-control replacements. Automotive OEMs exhibit the least price sensitivity given digital twin integration mandates, while small-to-mid manufacturing facilities in India's PLI corridors negotiate aggressively on upfront hardware costs.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes industrial semiconductor supply to single-source concentration, with limited geographic diversification beyond South Korean memory fabrication and Japanese power discrete production. Motor drive manufacturing draws from copper winding stock, neodymium permanent magnets, and silicon carbide wafers as critical inputs. Tariff exposure escalates for EU-bound equipment as REACH fluoropolymer cable insulation restrictions force German machine builders into accelerated material requalification cycles. Distribution runs through authorized system integrator networks that bundle commissioning services with hardware procurement, particularly across US Gulf Coast petrochemical and German automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through automotive OEM smart factory consolidation and pharmaceutical serialization mandates, squeezing mid-tier automation suppliers between premium-certified incumbents and subsidized Chinese competitors.
For Market Incumbents: Secure functional safety certification depth as the primary defensive moat against emerging edge-native competitors. Invest captive supply relationships for silicon carbide semiconductors to insulate margins from Taiwanese foundry volatility. Deepen backward integration into digital twin software to prevent margin capture by pure-play analytics vendors. For New Entrants and Emerging Players: Lead with subscription-based energy management dashboards targeting US commercial real estate portfolios where facility managers prioritize operational expenditure models over capital hardware. India's Gujarat and Tamil Nadu industrial corridors offer the most penetrable geography given PLI scheme tariff incentives favoring local assembly partnerships. Pursue system integrator co-development agreements to bypass direct OEM procurement barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core automation divisions lacking vertical software integration. Long-term viability hinges on edge-to-cloud platform completion and IIoT attach-rate expansion rather than hardware shipment volumes. Watch for inflection when CSRD carbon accounting mandates in Europe accelerate building automation retrofit velocity beyond current service contract coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Software Bundling | Compresses commissioning cycles for German automotive battery gigafactories while locking in recurring revenue streams. |
| Silicon Carbide Supply Agreement | Secures switching efficiency advantages for motor drives serving Hungary and Lower Saxony manufacturing clusters. |
| Local Assembly Partnership | Navigates BIS certification requirements and PLI tariff incentives across India's Mumbai-Pune industrial belt. |
| Edge Computing Architecture Deployment | Eliminates latency penalties for predictive maintenance in US Gulf Coast petrochemical safety instrumented systems. |
| REACH-Compliant Material Validation | Maintains CE marking continuity for German machine builders ahead of fluoropolymer cable insulation enforcement deadlines. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation against SEC 10-K filings, customs and trade data, IEC certification registries, and provincial industrial upgrading program disclosures. Bottom-up equipment shipment tracking and top-down end-use demand estimation were triangulated to constrain forecast variance.
Sensitivity analysis tested forecast robustness across copper price volatility bands, semiconductor foundry utilization scenarios, and certification timeline compression assumptions. Segmentation modeling spanned product type, technology tier, application vertical, and end-user industry across the projection horizon. CAGRs were derived from installed base replacement cycles, brownfield retrofit velocity, and greenfield capital expenditure patterns. Edge-to-cloud platform adoption curves and digital twin penetration rates served as industry-specific demand modifiers.
The analysis sits within stated boundaries; outcomes outside sustained industrial capital expenditure levels, stable regulatory certification timelines, and intact semiconductor supply chains would require recalibration. Forecasts reflect documented assumptions regarding EU machinery directive enforcement consistency, MIIT dual carbon goal implementation pacing, and NFPA 70E arc-flash upgrade compliance velocity. Revision becomes warranted when rare-earth magnet supply concentration or Taiwan Strait logistics disruption crosses material availability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
AC DC Power Adapter Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Series Reactor Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Solid State Power Controller Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Global Synchronous Motor Market
Power Systems
Power Supply and Charger Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Hybrid Inverters Market
Power Systems
Buck-Boost Controller Market
Power Systems
South America Battery Management System Market