
 AC DC Power Adapter Market | 2026-2036
AC DC Power Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
AC DC Power Adapter Market Analysis
OEM direct sourcing is tilting away from traditional distributor networks toward contracted manufacturing partnerships in Asia. Delta Electronics leverages captive semiconductor sourcing to sustain margin stability across high-volume notebook adapter programs. MEAN WELL anchors its position in industrial open-frame adapters through dedicated R&D facilities in Taiwan. Chicony Power dominates the wall-mount segment for consumer electronics brands, competing primarily on manufacturing scale rather than proprietary technology.
An AC DC power adapter converts alternating current from mains electricity into regulated direct current through transformer isolation, rectification, and switching circuitry, typically achieving efficiencies above 85% under active-load conditions in modern designs. The device serves as the essential power interface for consumer electronics, telecommunications equipment, medical devices, and industrial automation systems where internal AC conversion remains impractical. Wall-mount adapters occupy the highest volume tier due to proliferation of portable electronics, while open-frame units command premium positioning in embedded industrial applications where thermal management and form-factor constraints dominate procurement criteria. Desktop variants retain stable demand in workstation and medical-grade deployments where detachable cabling and enhanced surge protection justify incremental unit costs.
The US Department of Energy enforces minimum efficiency standards under external power supply regulations, compelling manufacturers to redesign transformer architectures and adopt active power-factor correction. The EU Ecodesign Directive and CE marking requirements under the Low Voltage Directive shape market access for imported adapters, with REACH compliance adding material disclosure obligations for cable assemblies and housings. China's GB standards and compulsory certification through the country's national quality regulator enforce domestic efficiency benchmarks that increasingly align with international norms. Stakeholders must monitor evolving efficiency tiers and regional certification divergence to avoid stranded inventory in cross-border fulfillment channels.
Market Dynamics
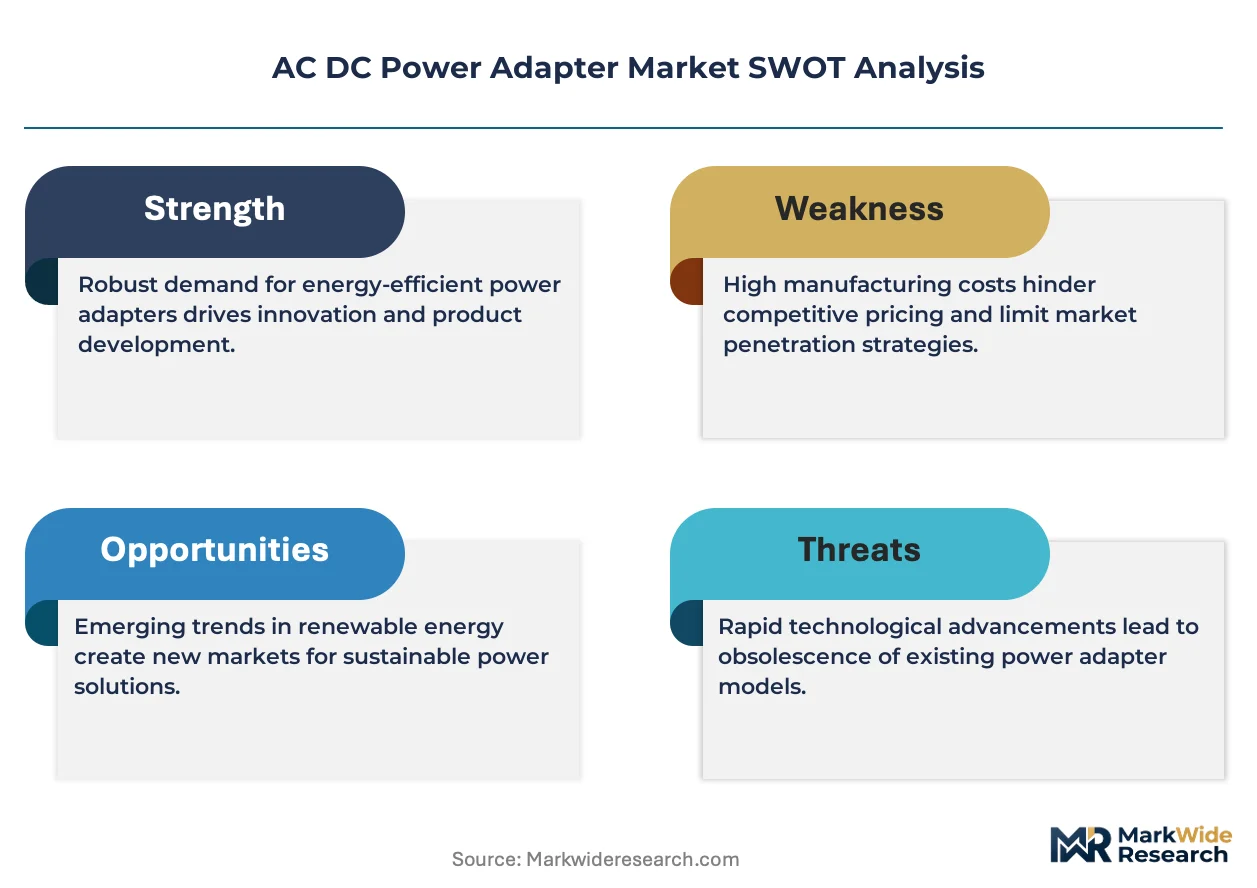
External power supply efficiency mandates are compressing legacy transformer architectures while simultaneously elevating active power-factor correction circuitry to baseline requirements, forcing wholesale redesign of adapter platforms across all volume tiers.
Growth Catalysts
- EU Ecodesign Directive:Tiered no-load power consumption limits below 0.5W are compelling adapter redesigns that favor higher-efficiency switching topologies across consumer electronics supply chains.
- Portable computing refresh cycles:Notebook and tablet manufacturers are expanding adapter procurement to match device shipment volumes, particularly for USB-C PD-compatible platforms.
- Shenzhen-Dongguan production cluster:Concentrated manufacturing capacity in China's Pearl River Delta enables rapid scale-up for high-volume consumer electronics programs.
Market Restraints
- Magnetics cost volatility:Ferrite core and copper winding materials face input price swings that compress margins on transformer-dependent adapter designs.
- Single-region supply concentration:Over 70% of global adapter assembly capacity resides in Guangdong Province, creating geographic risk exposure for procurement continuity.
- GaN substitution ceiling:Gallium nitride power semiconductors remain cost-prohibitive for sub-65W adapters, limiting efficiency gains in the highest-volume product tier.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for domestic adapter production create localized supply alternatives to China-centric sourcing.
- Medical-grade open-frame adapters:IEC 60601-1 4th Edition compliance requirements are expanding addressable market for isolation-rated industrial designs.
- GaN-SiC hybrid topologies:Converging wide-bandgap semiconductors with silicon controllers enables 94%+ efficiency in compact form factors for premium notebook segments.
Industry Challenges
- EMC pre-compliance testing backlog:FCC Part 15 and CISPR 32 certification queues are extending product launch timelines for new adapter platforms.
- Multi-jurisdiction efficiency alignment:Divergent US DoE Level VI, EU Code of Conduct Tier 2, and China GB 20943 requirements force SKUs proliferation across regional variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC DC Power Adapter Market |
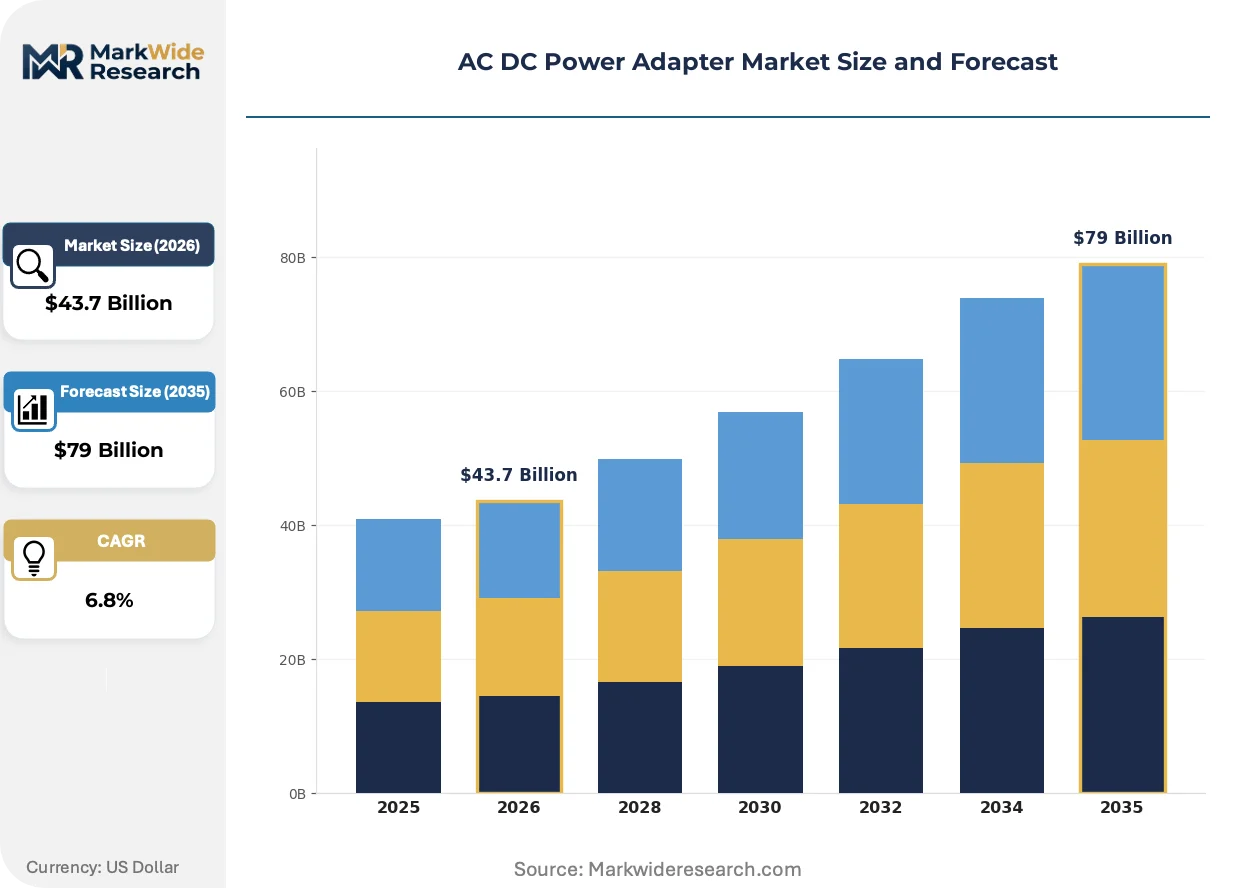
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mount, Desktop, Open Frame, Embedded Power Rating: 5W, 12W, 24W, 36W Input Voltage: 100-240V, 100-120V, 220-240V, 12-24V Connectivity: USB, Barrel Connector, Terminal Block, Others |
| Companies Covered | Delta Electronics Inc, MEAN WELL Enterprises Co Ltd, TDK-Lambda Corporation, Huawei Technologies Co Ltd, Chicony Power Technology Co Ltd, Ametek Inc, Keysight Technologies Inc, Advanced Energy Industries Inc, Murata Manufacturing Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC DC Power Adapter Market Emerging Trajectories
Adapter architectures are converging around universal USB-C PD delivery while magnetic component miniaturization and wide-bandgap semiconductor integration compress physical footprints without sacrificing thermal performance.
GaN-based active-clamp flyback topologies are hybridizing with traditional silicon controller platforms to bridge cost-performance gaps in mid-wattage adapters. Gaming laptop and workstation OEMs are adopting these hybrid designs fastest, prioritizing thermal density over unit cost. The technology is hybridizing procurement specifications, forcing tier-1 suppliers to maintain dual-qualified component lines.
US Department of Energy Level VII efficiency standards are tightening active-mode loss allowances for external power supplies above 49W. Manufacturers must redesign magnetic components and add synchronous rectification to maintain compliance. Industrial open-frame adapters face the steepest redesign burden due to legacy transformer platforms.
Direct contracting with Asian ODMs is displacing traditional electronics distributor networks for volume adapter procurement. Consumer electronics brands are consolidating supplier panels to capture scale pricing and dedicated capacity. This channel compression is most pronounced among US and EU notebook OEMs with annual adapter demand exceeding 10 million units.
AC DC Power Adapter Market Segmentation
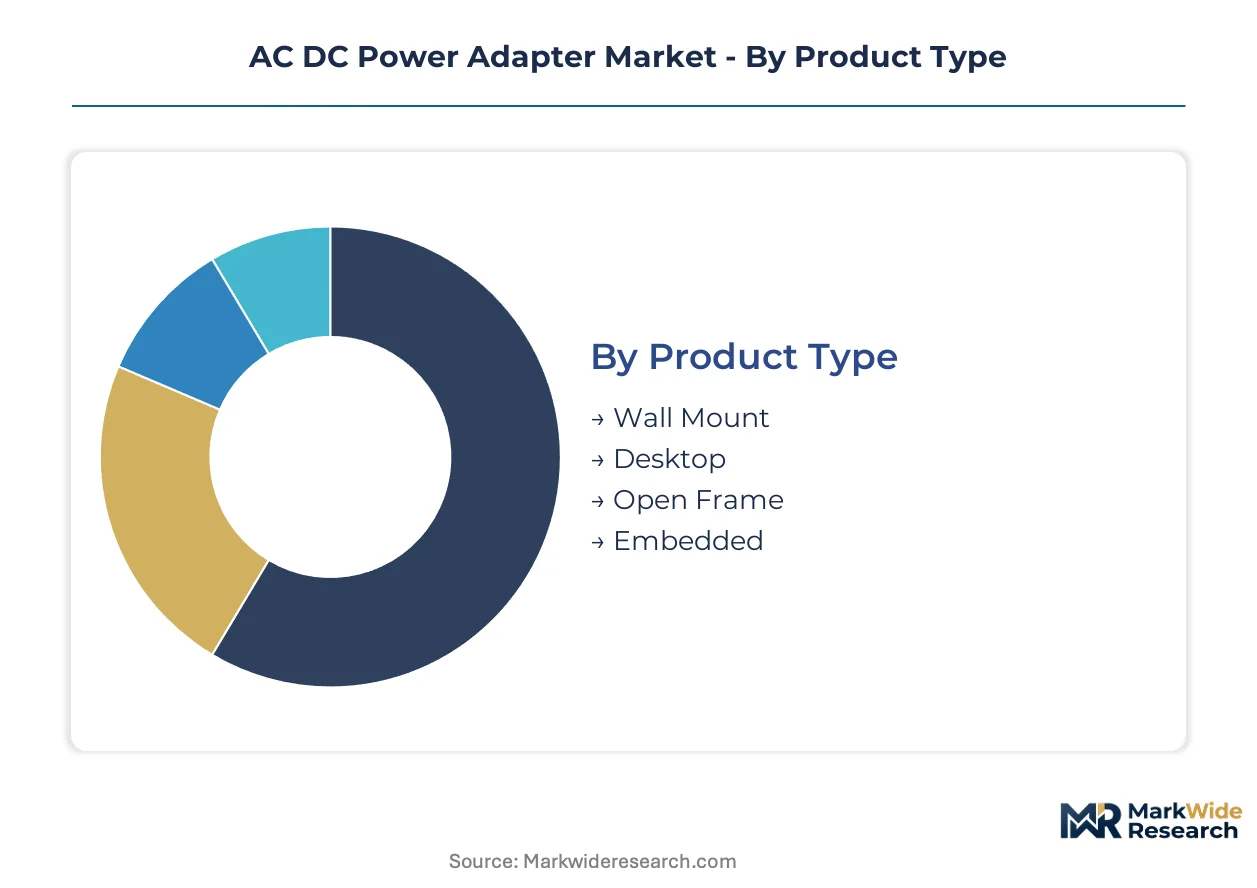
Adapter procurement decisions hinge on form-factor constraints, power delivery specifications, and regional voltage standards. Manufacturers configure product portfolios across these dimensions to match end-use thermal budgets, safety certifications, and connector interoperability requirements.
Product Type:
Mature wall-mount designs dominate consumer electronics volumes while emerging embedded configurations address IoT integration demands.
- Wall Mount:Self-contained units with integrated AC prongs and thermal enclosures serve portable electronics where space constraints prohibit internal power conversion. Notebook and smartphone OEMs in China's Pearl River Delta concentrate procurement here, driven by USB-C PD standardization and efficiency mandates from the US Department of Energy.
- Desktop:Detachable-cable adapters with enhanced surge protection and medical-grade isolation target workstation and healthcare deployments. Demand clusters in Germany and Japan where IEC 60601-1 compliance and extended cable reach justify premium positioning over wall-mount alternatives.
- Open Frame:Exposed PCB assemblies for industrial equipment ventilation.
- Embedded:Board-mounted modules integrating directly into host device chassis.
Wall Mount handles the majority of throughput; Embedded is the fastest mover on share.
Power Rating:
Cost tier stratification separates commodity consumer adapters from precision industrial units.
- 5W:Low-wattage designs for IoT sensors and standby power applications.
- 12W:Entry-level smartphone and peripheral charging platforms.
- 24W:Mid-range tablet and compact notebook power delivery.
- 36W:Higher-output configurations for gaming peripherals and medical monitors requiring sustained thermal performance under continuous load.
12W maintains the largest installed base; 36W is climbing the fastest as power budgets rise.
Input Voltage:
Application geography determines voltage range requirements with universal designs commanding manufacturing priority.
- 100-240V:Universal input architectures accommodate North American, European, and Asian mains standards in single SKUs, reducing inventory fragmentation for multinational electronics brands sourcing from Shenzhen contract manufacturers.
- 100-120V:Japan and North America-specific designs optimize magnetic component sizing for lower voltage operation.
- 220-240V:European and Chinese domestic market configurations.
- 12-24V:DC-input adapters for automotive and solar-powered installations.
100-240V carries the volume weight; 12-24V is gaining share fastest in off-grid applications.
Connectivity:
Customer type fragmentation separates consumer retail channels from industrial procurement specifications.
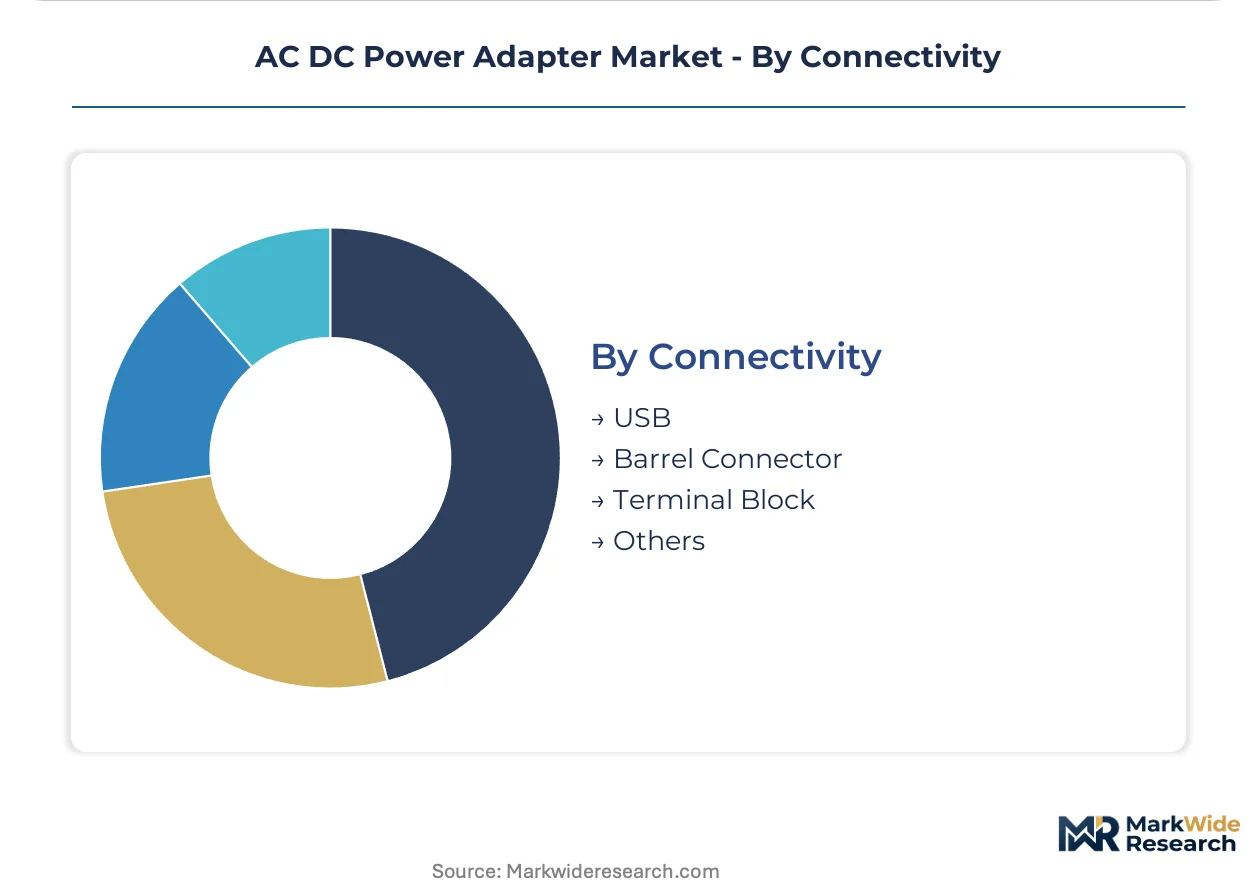
- USB:Standardized Type-C connectors with Power Delivery negotiation dominate notebook and mobile device ecosystems, with procurement consolidating around USB-IF certification requirements for interoperability across Apple, Samsung, and Dell product lines.
- Barrel Connector:Cylindrical DC plugs retain stable demand in legacy industrial equipment and medical devices where connector retention force and pin configuration standardization outweigh USB transition costs.
- Terminal Block:Screw-down connections for industrial automation and LED lighting installations.
- Others:Proprietary and application-specific connector formats.
USB commands the broadest throughput; Terminal Block is expanding most quickly in factory automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta's container throughput infrastructure underwrites China's dominance in adapter assembly, while the US Department of Energy's efficiency mandates reshape procurement specifications across import-dependent markets.
China
Shenzhen and Dongguan concentrate over seventy percent of global adapter assembly capacity, serving notebook and smartphone OEM procurement programs. GB standards enforced by SAMR align domestic efficiency benchmarks with international norms, compelling redesigns of legacy transformer platforms. The Pearl River Delta manufacturing cluster enables rapid scale-up for USB-C PD-compatible adapter volumes.
United States
Notebook OEMs and medical device manufacturers drive adapter procurement through direct contracting with Asian ODMs. US Department of Energy Level VII efficiency standards tighten active-mode loss allowances above 49W, forcing magnetic component redesigns. FCC Part 15 EMC certification queues extend product launch timelines for new platform introductions.
Germany
Industrial automation and medical equipment sectors sustain demand for open-frame and desktop adapter configurations. EU Ecodesign Directive Tier 2 no-load limits below 0.5W compel switching topology upgrades across imported consumer electronics. Bavaria's precision engineering base supports specialized procurement for IEC 60601-1 compliant medical-grade power supplies.
Japan
Workstation OEMs and telecommunications equipment manufacturers anchor demand for high-reliability adapter platforms. METI efficiency guidelines shape domestic procurement specifications for external power supplies. The Kanto region's electronics manufacturing base concentrates sourcing for 100-120V optimized magnetic designs.
India
Domestic electronics assembly expansion under the PLI scheme is redirecting adapter procurement toward localized production alternatives. BIS certification requirements enforce compliance with converging efficiency standards for imported and locally manufactured units. Gujarat and Tamil Nadu emerging electronics manufacturing clusters are attracting contract assembly investments from multinational OEMs.
AC DC Power Adapter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly. The market structures around a consolidated tier of high-volume contract manufacturers and a fragmented base of specialized industrial suppliers. Three archetypes dominate: captive semiconductor integrators, scale-driven consumer electronics contractors, and precision industrial specialists. Competitive moves concentrate on backward integration into magnetic components and dedicated capacity contracting with multinational OEMs.
Among Taiwan-based platform specialists, Delta Electronics Inc and Chicony Power Technology Co Ltd exemplify the high-volume contract manufacturing archetype, while MEAN WELL Enterprises Co Ltd represents the precision industrial tier. These three occupy positions spanning consumer electronics procurement and specialized industrial applications, with their geographic concentration reflecting the Pearl River Delta and Taiwan manufacturing corridor's dominance in global adapter supply.
| Leading Market Players |
|---|
| Delta Electronics Inc |
| MEAN WELL Enterprises Co Ltd |
| TDK-Lambda Corporation |
| Huawei Technologies Co Ltd |
| Chicony Power Technology Co Ltd |
| Ametek Inc |
| Keysight Technologies Inc |
| Advanced Energy Industries Inc |
| Murata Manufacturing Co Ltd |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Guangdong Province's transformer winding facilities is compressing spot pricing for ferrite cores and copper windings while simultaneously eroding supplier leverage in annual contract negotiations with notebook OEMs.
Pricing Analysis
Volume-discount tiering structures separate multinational OEMs procuring ten-million-unit annual programs from mid-tier consumer electronics brands sourcing below one million units. Pricing stratifies across medical-grade isolation, industrial open-frame, and consumer wall-mount tiers, with IEC 60601-1 certification adding substantial premiums over standard efficiency variants. Cost compression in sub-65W consumer adapters is intensifying because gallium nitride power semiconductors remain cost-prohibitive at mass-market volumes. Mid-tier brands exhibit the highest price sensitivity, while medical device manufacturers prioritize isolation reliability over unit cost.
Supply Chain Analysis
Export-control regime restrictions on wide-bandgap semiconductor deposition equipment are limiting gallium nitride foundry capacity expansion outside China and Taiwan. Adapter assembly draws from concentrated manufacturing in China, Taiwan, and emerging facilities in India under PLI scheme incentives. Ferrite core magnetics, copper windings, and power semiconductors constitute critical input dependencies. Single-region supply concentration in Guangdong Province creates tariff exposure vulnerability for US-bound shipments. Distribution runs through direct contracting with Asian ODMs rather than traditional electronics distributor networks for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified magnetic design engineers capable of optimizing active-clamp flyback architectures for 94% efficiency targets remain scarce relative to procurement demand from gaming laptop and workstation OEMs.
For Market Incumbents: Entrench market position through backward integration into ferrite core manufacturing and dedicated capacity contracting with Shenzhen-based winding facilities. GaN-SiC hybrid topology adoption threatens legacy silicon-controller platforms, necessitating R&D investment in synchronous rectification and active power-factor correction circuitry. Certification investment in IEC 60601-1 4th Edition compliance expands addressable medical-grade revenue pools. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized adapter assembly corridor before capacity absorption accelerates. Medical-grade open-frame adapters for industrial automation present the most penetrable white space, with Bavaria and Japan-based precision engineering clusters offering anchor demand. Pursue USB-C PD certification as the primary go-to-market credential for notebook OEM supplier qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gallium nitride power semiconductor integration programs as deposition equipment costs escalate. Long-term viability hinges on captive magnetic component supply and qualified EMC pre-compliance testing infrastructure. Acquisition targets should demonstrate dual-qualified component lines for hybrid silicon-GaN platforms. The signal to watch is FCC Part 15 and CISPR 32 certification queue lengths as a leading indicator of product launch friction and working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-SiC Hybrid Topology Adoption | Enables 94% efficiency in compact notebook adapters for gaming OEMs. |
| Backward Integration into Magnetics | Captures ferrite core margin stability amid copper winding price volatility. |
| IEC 60601-1 4th Edition Certification | Unlocks medical-grade open-frame adapter demand in Germany and Japan. |
| India PLI Manufacturing Footprint | Diversifies geographic supply concentration beyond Guangdong Province. |
| USB-C PD Universal Platform Standardization | Consolidates procurement specifications across Apple, Samsung, and Dell ecosystems. |
Methodological Framework
The analysis maps wall-mount, desktop, open-frame, and embedded adapter configurations, each validated through procurement directors at notebook OEMs, magnetic component engineers at transformer suppliers, EMC testing laboratory managers, and contract manufacturing executives in the Pearl River Delta. Primary interview findings were cross-referenced with US Department of Energy efficiency regulation filings, EU Ecodesign Directive tier documentation, China GB standard updates, SEC 10-K disclosures from listed power supply manufacturers, and customs trade data for ferrite core imports. Bottom-up unit shipment estimates by power rating and form factor were triangulated against top-down market value reconstructions.
Assumptions regarding gallium nitride cost curves, USB-C PD adoption velocity, and efficiency mandate enforcement timelines were held fixed across baseline scenarios while regional production shift speeds and medical-grade certification demand were varied in sensitivity testing. Segmentation dimensions modeled include product type, power rating tier, input voltage architecture, and connectivity standard across the projection horizon. CAGRs were derived from regression analysis of historical shipment correlations with portable computing refresh cycles and industrial automation capital expenditure patterns. Forecast inputs incorporated SAMR enforcement intensity for China GB standards and METI guideline revisions for Japanese domestic procurement.
Stress conditions across ferrite core price volatility, Guangdong logistics disruption, and gallium nitride substitution ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including EMC certification queue extensions and multi-jurisdiction efficiency standard divergence. Material shifts in US Department of Energy Level VII implementation timing or EU Ecodesign Directive Tier 3 proposals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Digital Inverter Market
Power Systems
Global Data Center Transformer Market
Power Systems
Global Flexible Batteries Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Modular Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Liquid Cooling Systems Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Vehicle Inverter Market
Power Systems
Global Excitation Systems Market
Power Systems
USB Power Adapters Market