
 Automatic Laser PCB Depaneling Machines Market | 2026-2036
Automatic Laser PCB Depaneling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Laser PCB Depaneling Machines Market Insights
Multi-source procurement for laser depaneling subsystems is shifting toward captive integration among top-tier equipment builders. LPKF Laser & Electronics anchors its position through in-house beam source development. ASYS Group competes via modular platform architectures that span multiple laser technologies. Hans Laser leverages cost-optimized fiber laser configurations to serve high-volume PCB assemblers in Asia.
Automatic laser PCB depaneling machines cut populated circuit boards using focused laser beams that vaporize substrate material along programmed paths, typically achieving kerf widths below 20 micrometers with positional accuracy of ±10 micrometers. Fiber laser systems dominate installed capacity due to lower maintenance cycles and superior cutting speed on FR-4 and polyimide substrates, while UV laser configurations command premium placement in medical device and flex-rigid applications where thermal damage must be minimized. Contract manufacturers represent the fastest-growing end-user category as outsourcing of PCB singulation accelerates among OEMs seeking to avoid capital intensity.
FDA device manufacturing regulations and ISO 13485 quality management standards shape demand specifications in medical device applications, where depaneling residue and particulate controls are validated as part of process qualification. EPA air emission guidelines and OSHA laser safety classifications further constrain equipment design, particularly for CO2 laser systems generating volatile organic compounds during ablation. Stakeholders must weigh wavelength selection against evolving substrate portfolios as halogen-free and ceramic-filled laminates gain share in automotive and telecom boards.
Market Dynamics
PCB miniaturization is compressing mechanical tolerance windows below 25 micrometers, forcing depaneling equipment buyers to abandon routing and punching methods in favor of laser systems that eliminate mechanical stress on populated boards.
Growth Catalysts
- REACH and RoHS compliance tightening:European electronics manufacturers face material purity mandates that laser depaneling satisfies through non-contact, contamination-free singulation processes.
- Flex-rigid substrate proliferation:Medical device and wearable electronics producers require thermal-damage-free cutting that UV laser configurations uniquely deliver.
- Automotive electronics clusters:Precision manufacturing hubs in Germany concentrate demand as advanced driver-assistance systems multiply board counts per vehicle.
Market Restraints
- Fiber laser source concentration:High-power beam generation components concentrate among specialized photonics suppliers, creating single-source vulnerability for equipment builders.
- Capital intensity barrier:UV laser depaneling systems require 2-3x the upfront investment of mechanical alternatives, excluding smaller contract manufacturers.
- Substrate material volatility:Ceramic-filled and halogen-free laminate prices fluctuate with rare earth and copper supply disruptions, destabilizing processing cost models.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and PCB assembly create virgin installed base demand as domestic production scales.
- AI-driven process optimization:Machine vision integration with real-time kerf monitoring enables predictive maintenance and yield improvement for high-mix producers.
- Service unbundling models:Equipment-as-a-service contracts with per-panel pricing lower barriers for mid-volume assemblers in Southeast Asia.
Industry Challenges
- Laser safety engineering talent scarcity:OSHA Class 4 laser system design and installation certification requires specialized photonics expertise that outpaces vocational training output.
- Legacy mechanical equipment stranding:Depreciation schedules and operator retraining costs delay replacement cycles at established PCB houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Laser PCB Depaneling Machines Market |
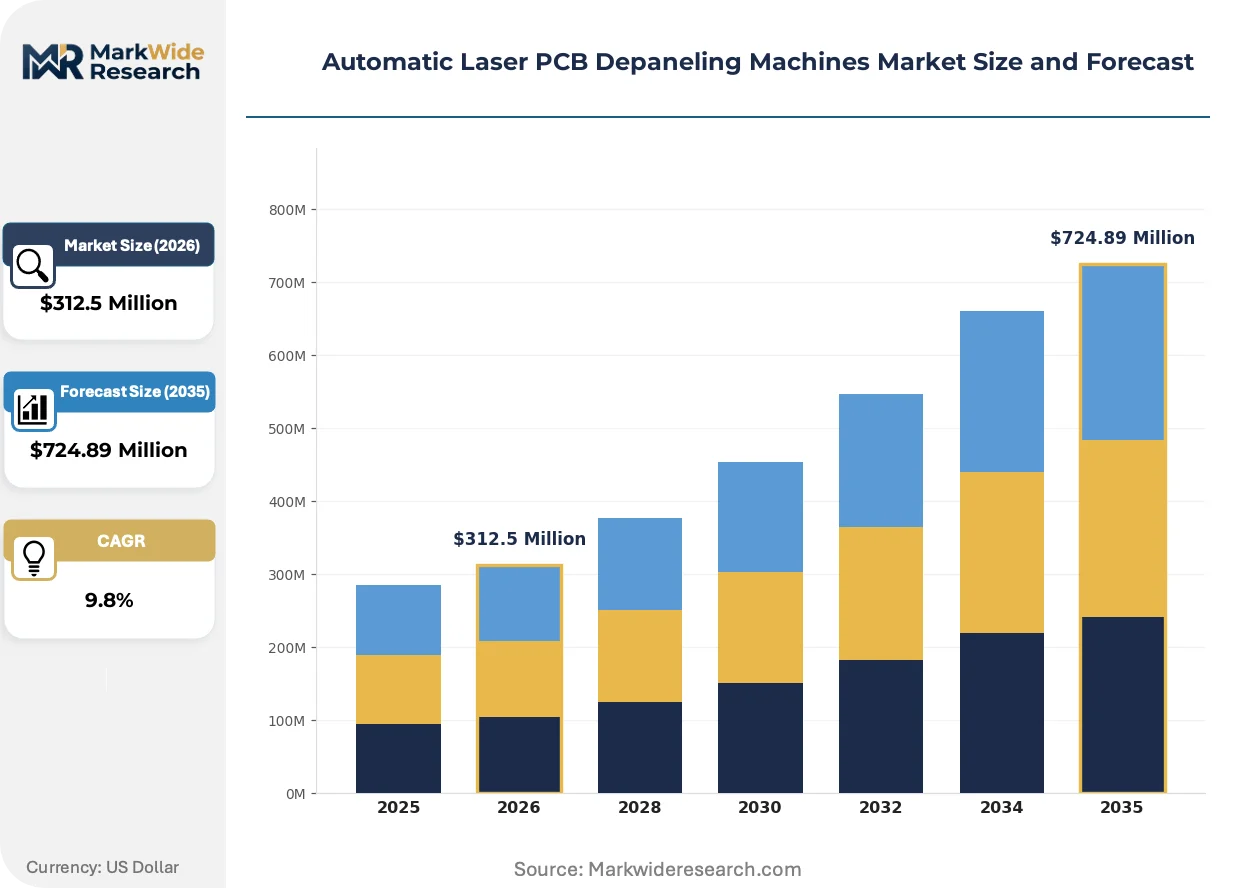
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $724.89 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CO2 Laser, Fiber Laser, UV Laser, Green Laser Application: Consumer Electronics, Automotive Components, Medical Devices, Telecommunication End User: Original Equipment Manufacturers, Contract Manufacturers, PCB Assemblers, Electronics Manufacturers Service Type: Maintenance, Installation, Consulting, Training |
| Companies Covered | LPKF Laser & Electronics, ASYS Group, Cencorp Automation, MSTECH, Aurotek Corporation, SAYAKA, Control Micro Systems, Hans Laser, Coherent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Laser PCB Depaneling Machines Market Trends and Innovations
Beam delivery architectures and process control software are undergoing simultaneous transformation as equipment builders compete on total cost of ownership rather than throughput metrics alone.
Ultrafast picosecond laser sources are converging with galvo-scanning beam steering to enable cold ablation of polyimide and LCP substrates without carbonization. Medical device manufacturers in Switzerland and Massachusetts are piloting these systems for implantable electronics. The technology is converging with cleanroom automation requirements, compressing equipment qualification timelines from 18 months to under 9 months.
EU MDR medical device regulations now mandate validated particulate controls during PCB singulation, extending process qualification documentation requirements. FDA has aligned inspection protocols with ISO 13485 traceability standards for laser-processed boards. Flex-rigid medical device producers in Bavaria and Minnesota are restructuring production lines to segregate laser depaneling into ISO 7 cleanroom zones.
Contract manufacturers are consolidating equipment procurement decisions at regional hub levels rather than individual facility autonomy. EMS giants now mandate laser depaneling compatibility across their qualified supplier networks. This concentration is most visible in Taiwan and Guadalajara, where top-tier assemblers enforce standardized machine interfaces and data logging protocols.
Automatic Laser PCB Depaneling Machines Market Segmentation
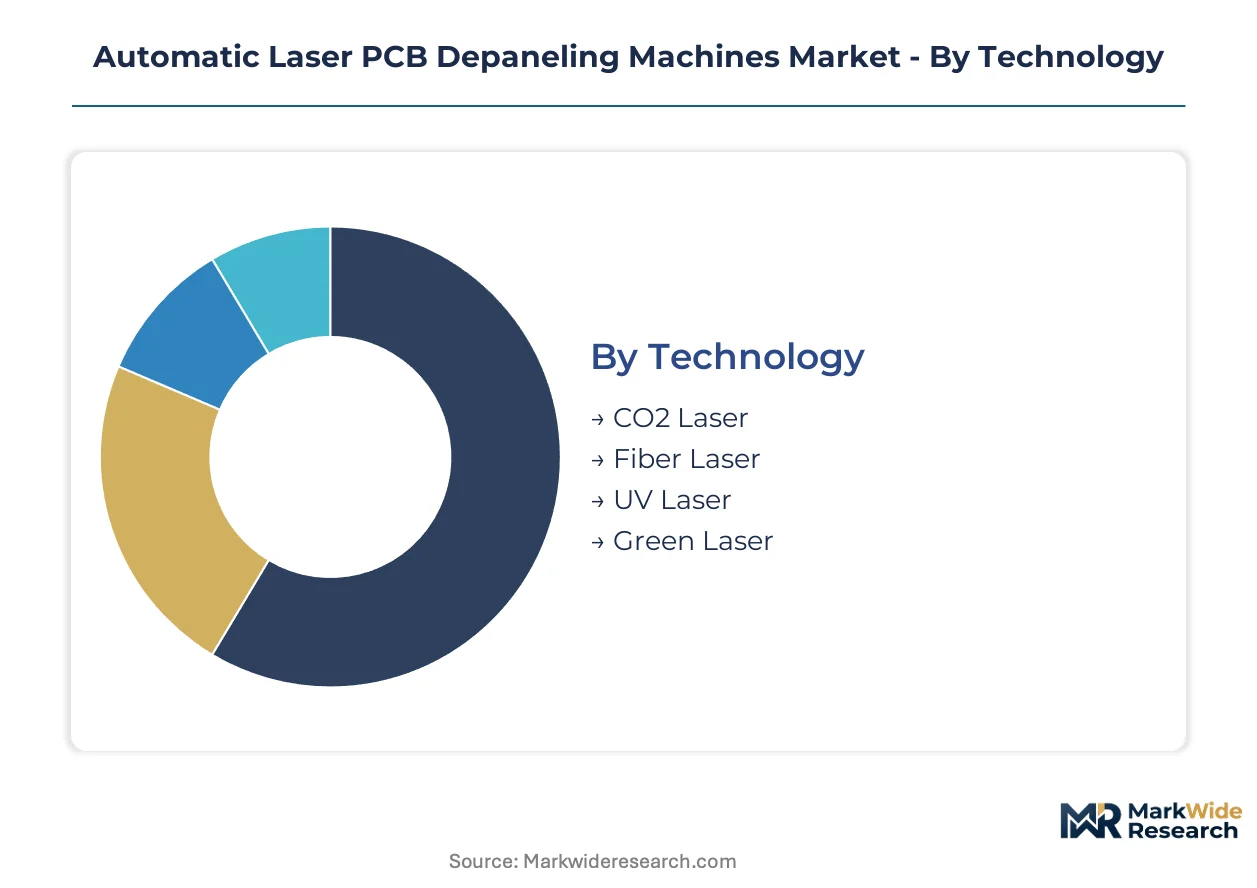
Laser PCB depaneling equipment buyers prioritize different performance attributes based on substrate portfolios, volume profiles, and regulatory exposure. Segmentation reveals where technology premiums command pricing power versus where cost optimization drives procurement.
Technology:
Buyers in this category differentiate primarily by thermal damage tolerance and maintenance burden tolerance.
- Fiber Laser:Solid-state sources operating at 1064nm wavelength deliver cutting speeds exceeding mechanical alternatives on FR-4 substrates. Demand concentrates among high-volume PCB assemblers in China seeking minimal downtime and reduced consumable costs.
- UV Laser:355nm wavelength systems enable cold ablation of polyimide and LCP with kerf widths below 15 micrometers. Medical device manufacturers in Switzerland and Massachusetts specify UV configurations for implantable electronics where carbonization risks disqualify longer wavelengths.
- CO2 Laser:Gas-based 10600nm systems process thicker substrates and ceramic-filled laminates at lower capital cost. Automotive electronics producers in Germany retain CO2 installations for non-critical board singulation.
- Green Laser:532nm wavelength bridges fiber and UV performance for mid-range precision requirements on flexible substrates. Wearables manufacturers pilot green laser systems for cost-sensitive flex-rigid applications.
Volume sits with fiber laser systems; growth tilts toward UV laser configurations.
Application:
End-use sectors separate by cleanliness requirements, traceability mandates, and batch size economics.
- Medical Devices:Implantable and diagnostic electronics demand validated particulate controls per EU MDR and FDA ISO 13485 alignment. Bavaria and Minnesota producers segregate laser depaneling into ISO 7 cleanroom zones with 9-month qualification timelines.
- Automotive Components:Advanced driver-assistance systems multiply board counts per vehicle, concentrating demand in German precision manufacturing hubs. REACH and RoHS compliance mandates favor non-contact laser methods over mechanical stress-inducing alternatives.
- Consumer Electronics:High-mix, high-volume production of smartphones and wearables dominates installed capacity. Contract manufacturers in Taiwan and Guadalajara enforce standardized machine interfaces across qualified supplier networks.
- Telecommunication:Base station and optical module PCBs require processing of halogen-free laminates with tight impedance control. Rare earth supply volatility destabilizes processing cost models for ceramic-filled substrates in this segment.
Consumer electronics anchors current installed base; medical devices demonstrate the steepest expansion trajectory.
End User:
Procurement authority and capital access distinguish buyer types in this category.
- Contract Manufacturers:EMS giants consolidate equipment decisions at regional hub levels, mandating laser depaneling compatibility across supplier networks. Outsourcing acceleration among OEMs seeking capital avoidance drives fastest segment expansion.
- Original Equipment Manufacturers:Vertically integrated electronics producers in automotive and medical verticals retain direct control over singulation processes. FDA and EPA compliance documentation requirements favor captive equipment ownership.
- PCB Assemblers:Mid-volume specialists balance fiber laser throughput against UV laser flexibility for mixed substrate portfolios. Southeast Asian assemblers increasingly adopt equipment-as-a-service contracts with per-panel pricing.
- Electronics Manufacturers:Broad-category producers serving industrial and instrumentation markets prioritize total cost of ownership over cutting speed metrics. India's PLI scheme incentives create virgin installed base demand as domestic production scales.
Contract manufacturers capture volume leadership; PCB assemblers gain share fastest through service unbundling models.
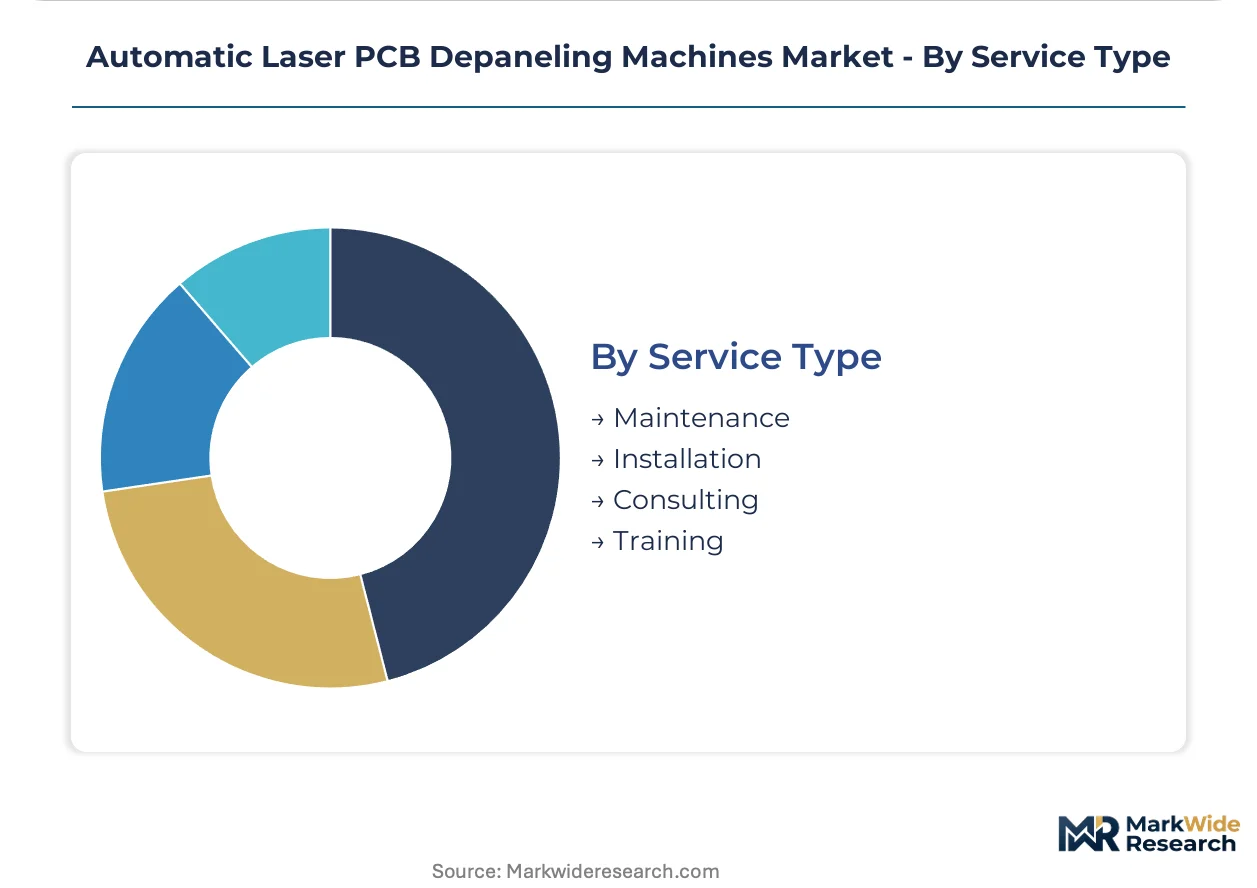
Service Type:
Post-sale revenue streams differentiate by customer technical capability and uptime sensitivity.
- Maintenance:Predictive service contracts with real-time kerf monitoring command premium pricing from high-mix producers. Machine vision integration enables yield improvement and downtime reduction.
- Installation:OSHA Class 4 laser safety certification requirements create specialized photonics expertise bottlenecks. Installation timelines extend where vocational training output lags demand.
- Consulting:Process qualification support for FDA and EU MDR compliance generates recurring engagement with medical device producers. Documentation requirements now span 18-month validation cycles.
- Training:Operator retraining costs delay replacement cycles at established PCB houses with legacy mechanical equipment. Equipment builders bundle training with platform migrations to accelerate conversion.
Maintenance commands the largest service revenue pool; consulting expands most quickly on regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision electronics manufacturing clusters anchor European laser depaneling demand, while Asian contract manufacturing hubs in Taiwan and Guadalajara concentrate procurement authority for high-volume consumer electronics.
Germany
Automotive electronics producers in Bavaria and Baden-Württemberg drive fiber laser adoption for advanced driver-assistance systems. REACH and RoHS compliance mandates from ECHA tighten material purity requirements, favoring non-contact singulation methods. Stuttgart and Munich manufacturing corridors host precision automation suppliers serving Mercedes-Benz and Bosch electronics divisions.
China
High-volume PCB assemblers in the Pearl River Delta and Yangtze River Delta prioritize fiber laser throughput for smartphone and wearable production. MIIT industrial upgrading policies incentivize laser equipment replacement of mechanical depaneling lines. Shenzhen and Suzhou electronics parks concentrate contract manufacturer demand for cost-optimized configurations.
United States
Medical device manufacturers in Massachusetts and Minnesota specify UV laser systems for implantable electronics under FDA ISO 13485 alignment. EPA air emission guidelines constrain CO2 laser system designs for volatile organic compound control. Minneapolis-Saint Paul and Greater Boston medical technology clusters validate particulate controls in ISO 7 cleanroom zones.
Switzerland
Implantable electronics producers in the Lake Geneva region pilot ultrafast picosecond laser sources for cold ablation of polyimide substrates. Swissmedic medical device regulations mandate validated process documentation extending qualification timelines. Basel and Zurich precision manufacturing corridors integrate laser depaneling with cleanroom automation requirements.
India
Domestic PCB assembly scaling under the PLI scheme creates virgin installed base demand for mid-volume fiber laser systems. BIS standards for electronics manufacturing equipment shape procurement specifications for emerging assemblers. Karnataka and Tamil Nadu electronics manufacturing clusters attract contract manufacturers establishing regional hub operations.
Automatic Laser PCB Depaneling Machines Market Competitive Landscape
Global majors compete with regional champions across technology specialization and geographic proximity to end-user clusters. The vendor base stratifies into three tiers: integrated beam source developers, modular platform architects, and cost-optimized volume suppliers. Strategic archetypes include captive photonics integration specialists, multi-technology platform builders, and Asia-centric scale operators. Competitive moves center on backward integration into beam source production and regional service network densification.
Among German-integrated equipment builders, LPKF Laser & Electronics AG exemplifies the captive beam source development archetype through in-house photonics capabilities. ASYS Group GmbH occupies a position as modular platform architect spanning multiple laser technologies across standardized machine interfaces. Hans Laser Technology Industry Group Co., Ltd. represents the Asia-centric scale operator archetype serving high-volume contract manufacturers with cost-optimized configurations. These three anchors illustrate divergent strategic postures: vertical control over core components, flexibility across technology modalities, and geographic cost positioning.
| Leading Market Players |
|---|
| LPKF Laser & Electronics |
| ASYS Group |
| Cencorp Automation |
| MSTECH |
| Aurotek Corporation |
| SAYAKA |
| Control Micro Systems |
| Hans Laser |
| Coherent |
| Others |
Pricing and Supply Chain Analysis
Family-owned German photonics specialists and PE-rolled automation equipment builders anchor supply discipline, translating captive beam-source production into pricing power for UV laser configurations while cost-optimized fiber laser systems face margin compression from Asian contract manufacturer procurement consolidation.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium UV laser depaneling systems from unbundled economy-tier fiber laser alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA-validated medical device configurations command substantial premiums over industrial-grade alternatives. Cost compression in fiber laser tiers is intensifying because Hans Laser and Chinese competitors prioritize volume share over margin retention. Mid-volume PCB assemblers in Southeast Asia exhibit highest price sensitivity, while Swiss implantable electronics producers demonstrate lowest elasticity due to EU MDR compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with high-power fiber laser beam generation components concentrated among specialized photonics suppliers in Germany, the United States, and Japan. Equipment builders draw from rare earth-doped fiber preforms, precision galvo-scanning optics, and ceramic-filled laminate substrates. Tariff exposure on Chinese-sourced laser diodes creates procurement risk for cost-optimized configurations. Distribution runs through regional equipment integrators serving contract manufacturer hub operations in Taiwan, Guadalajara, and Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
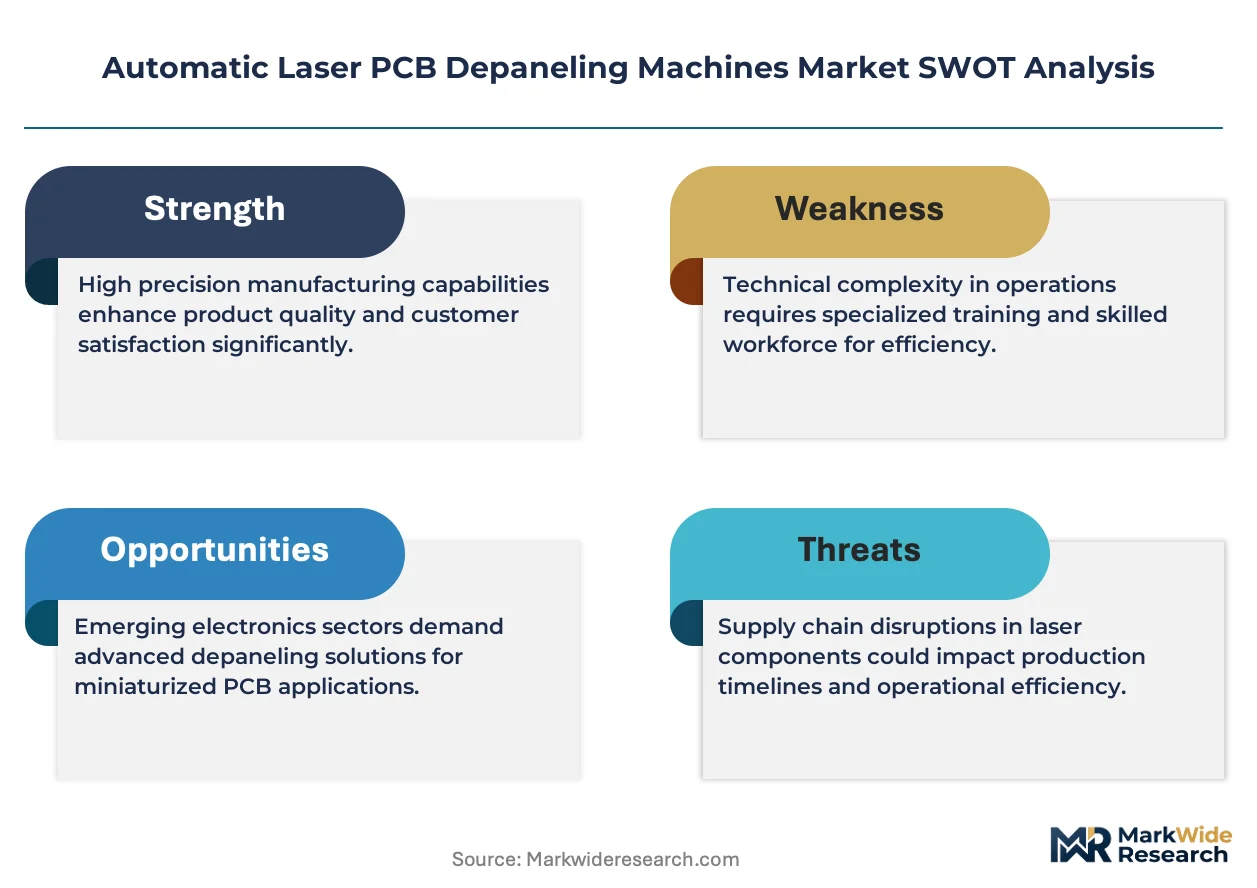
The automatic laser PCB depaneling machines market sits in a technology-transition phase where fiber laser systems displace mechanical routing and punching methods as PCB miniaturization compresses tolerance windows below 25 micrometers.
For Market Incumbents: Lock in beam-source supply agreements with IPG Photonics and nLight to defend against substitution pressure from Chinese fiber laser cost leaders. Deepen captive photonics integration into UV laser architectures to capture medical device premium pricing as EU MDR documentation requirements extend qualification timelines. Consolidate regional service networks in Taiwan and Guadalajara to match EMS procurement centralization.
For New Entrants and Emerging Players: The 2-3x price-point gap between premium UV medical-grade systems and economy fiber laser configurations creates entry space for mid-range green laser platforms targeting wearables manufacturers. India's PLI scheme incentives for domestic PCB assembly represent the most penetrable geography for virgin installed base capture. Equipment-as-a-service contracts with per-panel pricing lower capital barriers for Southeast Asian mid-volume assemblers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular platform architects with multi-technology flexibility in German precision manufacturing corridors. Long-term viability hinges on backward integration into beam-source production or exclusive distribution control over Asian contract manufacturer networks. Watch for FDA 510(k) clearance acceleration for picosecond laser medical device applications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beam Source Production | LPKF's in-house photonics capabilities reduce supplier dependency for UV laser medical systems. |
| Equipment-as-a-Service Launch | Per-panel pricing models lower barriers for Indian PCB assemblers scaling under PLI incentives. |
| Cleanroom Automation Partnership | Swiss and Bavarian medical device producers compress ISO 7 qualification timelines to 9 months. |
| AI-Driven Process Optimization Platform | Machine vision integration with real-time kerf monitoring enables predictive maintenance for high-mix producers. |
| Regional Service Network Densification | Taiwan and Guadalajara hub operations match EMS procurement centralization requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with equipment procurement directors at EMS giants, photonics R&D leads, cleanroom automation engineers, and aftermarket service heads combined with FDA 510(k) databases, ECHA REACH registration dossiers, and MIIT industrial equipment certification records. Bottom-up triangulation across technology segments and top-down validation against contract manufacturer capex disclosures ensured cross-verification.
Segment-level granularity modeled technology type, application vertical, end-user category, and service type across the projection horizon. CAGRs derived from installed base replacement cycles, substrate portfolio shifts, and regulatory compliance timeline compression. Forecast inputs incorporated rare earth supply volatility indices, PLI scheme disbursement schedules, and EU MDR implementation phase transitions.
Underlying measurement precision varies by segment; fiber laser consumer electronics applications carry tighter precision than emerging picosecond laser medical device pilots. Forecasts reflect assumptions on substrate material substitution rates, OSHA Class 4 certification training output, and EMS outsourcing acceleration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market