
 Telecom Battery Market | 2026-2036
Telecom Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Battery Market Analysis
Data center and edge computing deployments are broadening the addressable base for telecom battery suppliers beyond traditional macro cell sites. CATL leverages its manufacturing scale to dominate lithium-ion supply for Chinese tower operators. EnerSys anchors its position in North America through deep channel relationships with rural telecom cooperatives. Samsung SDI differentiates via advanced nickel-rich cathode formulations that extend cycle life in tropical climates.
Telecom batteries are electrochemical storage systems engineered to deliver uninterrupted DC power during grid failures, typically operating at 48V with cycle depths calibrated to telecom load profiles. Lead acid retains share in price-sensitive emerging markets, yet lithium-ion captures margin pools as tower operators prioritize energy density and remote monitoring compatibility. The application split shows base stations consuming the largest volume, while solar-hybrid installations represent the fastest-growing deployment model as off-grid sites multiply.
FCC rules in the United States mandate minimum backup durations for 911-capable infrastructure, while the EU Green Deal and CE marking frameworks shape battery chemistry and recyclability requirements across Europe. India's BIS certification and CEA grid codes enforce thermal safety standards for telecom installations. Stakeholders must weigh chemistry transitions against existing lead acid asset bases and regional regulatory phase-in timelines when committing capital to next-generation backup systems.
Market Dynamics
The transition from lead acid to lithium-ion chemistry is compressing replacement cycles and forcing suppliers to rebuild service networks around remote monitoring capabilities rather than physical maintenance schedules.
Growth Catalysts
- 5G Network Densification:Tower operators in India and Brazil are doubling backup power capacity per site to support higher radio power draws from massive MIMO antenna arrays.
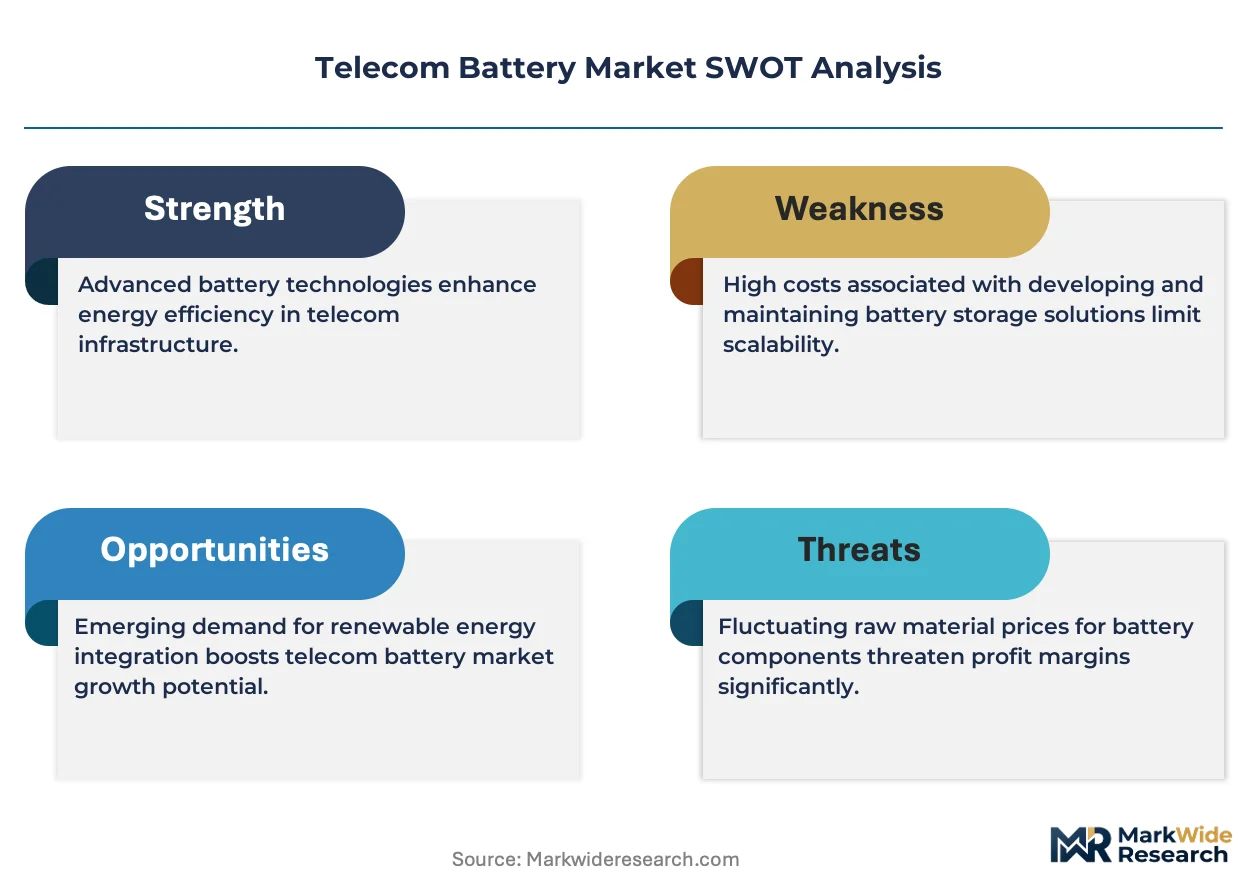
- F-Gas Regulation:The European Union's phasedown of high-global-warming-potential refrigerants is accelerating tower operator migration toward solid-state battery cooling systems that eliminate compressor-based thermal management.
- Solar-Hybrid Mandates:Off-grid base stations across sub-Saharan Africa are integrating photovoltaic generation with lithium storage to displace diesel gensets in markets where fuel logistics consume 40% of opex.
Market Restraints
- Cobalt Supply Concentration:Cathode material sourcing remains tethered to Central African mining operations, exposing cell manufacturers to ESG audit failures and forced labor disclosure requirements under the EU Corporate Sustainability Due Diligence Directive.
- Lead Acid Stranded Assets:Rural telecom cooperatives in the United States face write-down pressure from FCC-mandated backup duration upgrades that favor lithium-ion chemistry incompatible with existing rectifier infrastructure.
- Thermal Runaway Certification:UL 9540A test protocol compliance adds 18-24 months to product qualification timelines, freezing out smaller pack assemblers from tier-one tower operator approved vendor lists.
Strategic Opportunities
- Edge Computing Micro-Data Centers:Telecom tower real estate is repurposing for distributed compute workloads that require 4-8 hour battery autonomy rather than 2-hour telecom standards, expanding addressable capacity per site.
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting module packagers to Gujarat and Tamil Nadu industrial corridors with 25% capital expenditure subsidies.
- Second-Life Automotive Packs:Degraded electric vehicle battery modules with 70-80% remaining capacity are reconfiguring into 48V telecom racks, cutting material costs for price-sensitive African and Southeast Asian operators.
Industry Challenges
- Battery Management System Integration:Tower operators lack in-house firmware engineering to reconcile proprietary BMS protocols with existing SCADA architectures, forcing reliance on vendor-locked service contracts.
- Fire Suppression Retrofit Costs:Indoor equipment shelters originally engineered for lead acid thermal profiles require sprinkler system upgrades and gas-based suppression installation to accommodate lithium-ion fire characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Battery Market |
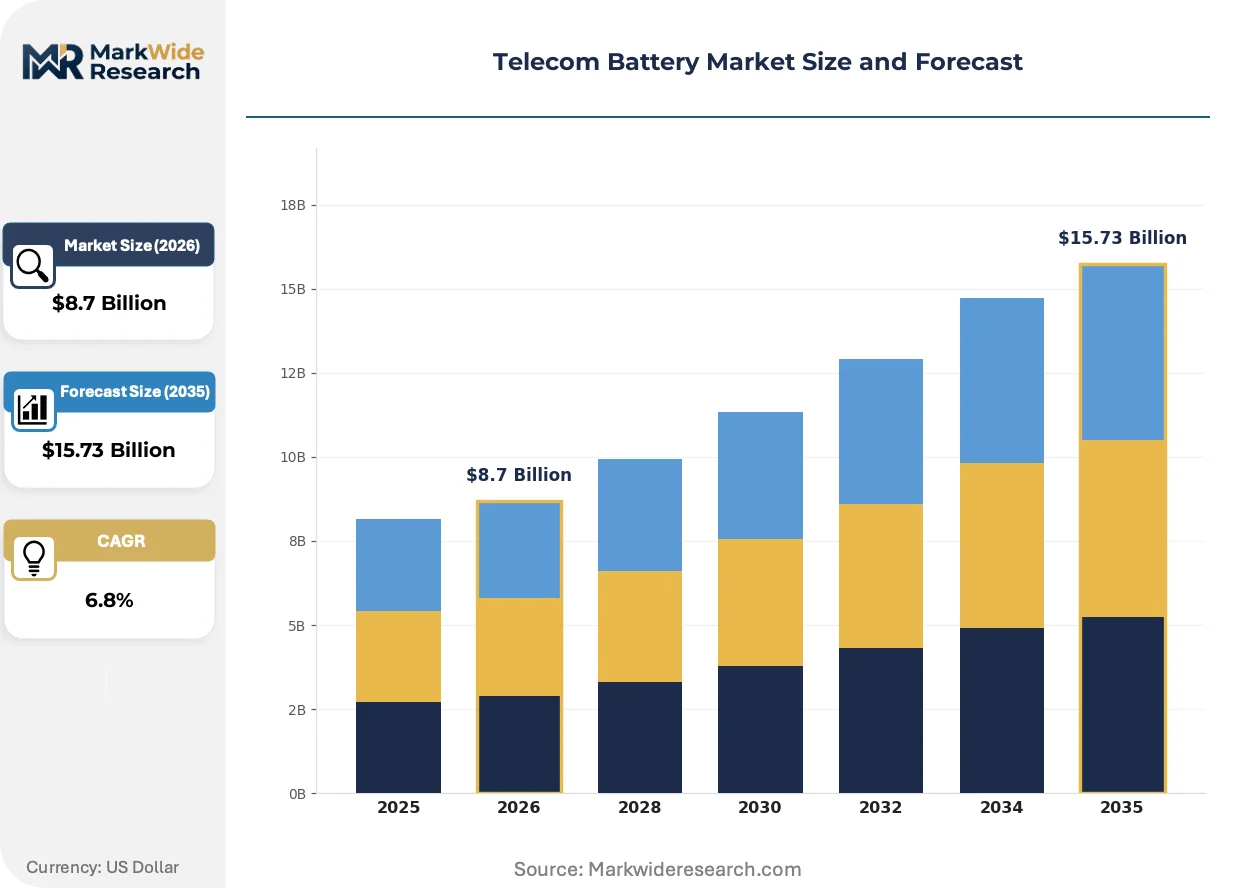
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Cadmium, Nickel Metal Hydride Application: Base Stations, Network Routers, Power Backup, Solar Systems End User: Telecommunication Companies, Enterprises, Government, Utilities Technology: Smart Grid, Renewable Energy, Energy Storage, Hybrid Solutions |
| Companies Covered | Panasonic Energy, SK On, CATL, EnerSys, Tianjin Lishen Battery, BYD, Samsung SDI, Tesla, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Battery Market Emerging Trajectories
Electrochemical storage architectures are fragmenting into application-specific configurations as tower operators abandon universal battery platforms in favor of workload-matched energy density and cycle life specifications.
Sodium-ion cell chemistry is modularizing into 48V rack systems for tropical climate deployments where nickel-rich lithium-ion degradation rates exceed economic thresholds. Indian tower operators are piloting 100Ah sodium modules with Prussian white cathodes in Kerala and Tamil Nadu coastal humidity zones. The technology is modularizing supplier ecosystems by enabling non-cobalt supply chains and compressing cathode material cost structures against lithium iron phosphate benchmarks.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in battery thermal management systems from 2030, forcing European tower operators toward phase-change material cooling or ambient air designs. This industrial consequence is accelerating R&D investment in passive thermal architectures that eliminate compressor maintenance. Nordic operators in Sweden and Finland are deploying these systems most aggressively, leveraging sub-20°C annual mean temperatures to minimize active cooling duty cycles.
Leasing models for battery-as-a-service are displacing capital purchase contracts among African tower operators where currency volatility and limited project finance access constrain upfront investment. Energy service companies now retain asset ownership and charge per available kilowatt-hour, transferring performance risk from Mobile Network Operators to specialized storage providers. This shift is most visible in Nigeria and Kenya, where tower portfolios managed by American Tower and IHS Holdings are transitioning 60% of new deployments to opex-based structures.
Telecom Battery Market Segmentation
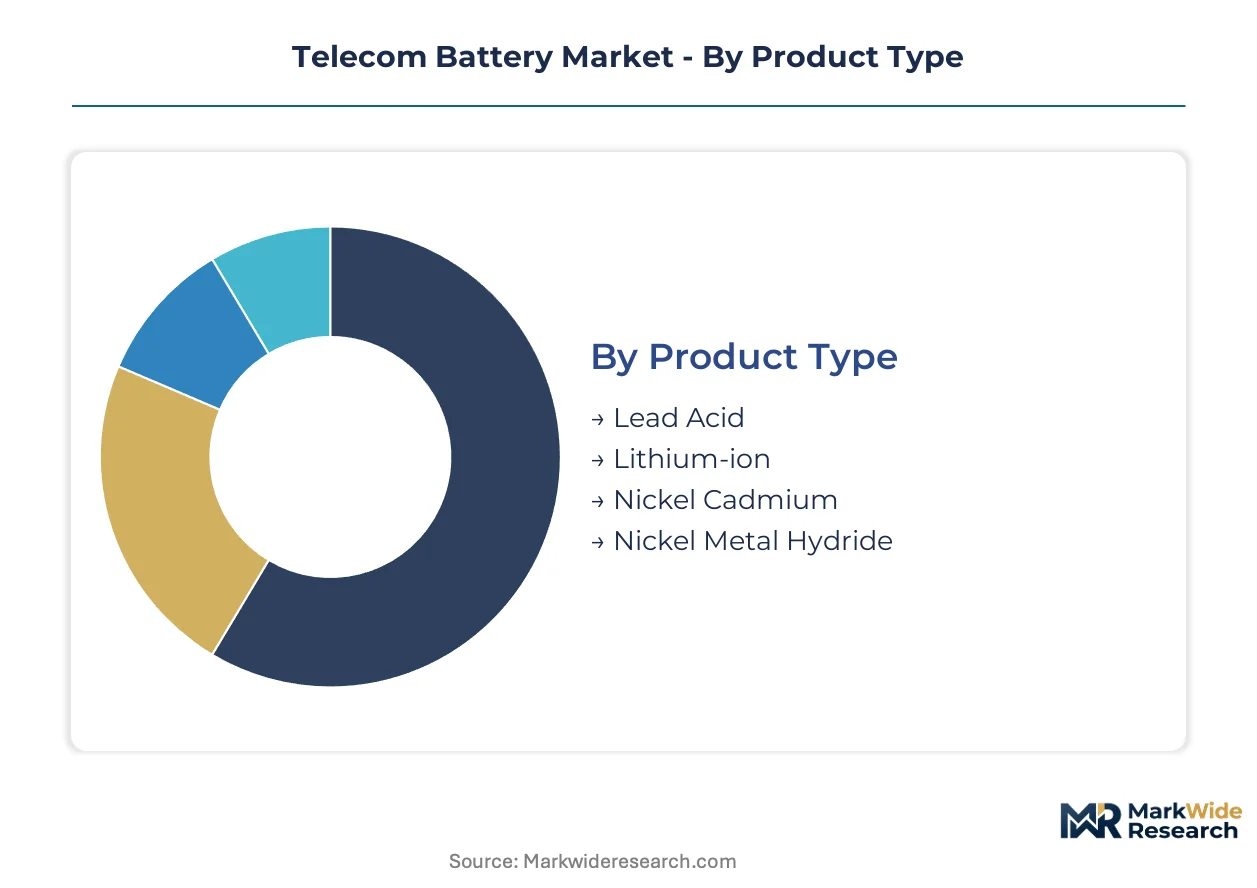
Telecom battery procurement diverges sharply across chemistry types and deployment contexts. Certification requirements from BIS, FCC, and EU F-Gas Regulation fragment vendor qualification pathways. Tower operators segment their sourcing strategies by thermal profile, cycle depth, and remote monitoring compatibility.
Product Type:
UL 9540A thermal runaway certification creates divergent approval timelines across chemistries, freezing out smaller pack assemblers from tier-one operator vendor lists. BIS certification in India and CE marking in Europe impose additional chemistry-specific safety testing.
- Lead Acid:Flooded and valve-regulated designs dominate price-sensitive rural installations in India and sub-Saharan Africa. Stranded asset risk mounts as FCC-mandated backup duration upgrades in the United States favor lithium-ion replacements incompatible with existing rectifier infrastructure.
- Lithium-ion:Nickel-rich cathode formulations from Korean suppliers extend cycle life in tropical humidity zones. CATL manufacturing scale anchors supply for Chinese tower operators migrating from lead acid toward energy-dense 48V rack systems with embedded BMS telemetry.
- Nickel Cadmium:Sintered plate construction tolerates extreme temperature swings in Middle Eastern desert installations. Limited new demand concentrates in retrofit markets where existing charging infrastructure cannot accommodate voltage profiles of newer chemistries.
- Nickel Metal Hydride:Rare earth content from Chinese separation facilities constrains cost competitiveness. Niche applications persist in Japanese telecom infrastructure where METI safety standards grandfather legacy chemistry approvals.
Lithium-ion sits at the top of the volume ranking, with sodium-ion pilot deployments climbing the fastest in Kerala and Tamil Nadu coastal zones.
Application:
Load profile differentiation drives battery specification divergence across deployment contexts. Autonomy requirements stretch from two-hour telecom standards toward four-to-eight hour edge computing specifications.
- Base Stations:Macro cell sites consume the largest installed capacity globally. Indian tower operators under TRAI uptime mandates are doubling backup power density per site to support massive MIMO antenna arrays in 5G rollouts.
- Network Routers:Edge computing micro-data centers repurposing telecom tower real estate require extended autonomy windows. American Tower and IHS Holdings portfolios in Nigeria and Kenya are transitioning router backup specifications toward opex-based battery-as-a-service contracts.
- Power Backup:Indoor equipment shelters originally engineered for lead acid thermal profiles require fire suppression retrofits to accommodate lithium-ion fire characteristics. Sprinkler upgrades and gas-based suppression installation add capital burden to chemistry transitions.
- Solar Systems:Photovoltaic-battery hybrid installations displace diesel gensets across sub-Saharan Africa. Fuel logistics consuming forty percent of opex in remote markets make solar-hybrid economics compelling for off-grid base stations.
Base Stations dominate current procurement volumes, with Solar Systems expanding most quickly as currency volatility drives African operators toward leased asset structures.
End User:
Capital deployment capacity and technical integration capabilities fragment procurement patterns across customer categories. Government and utility segments carry distinct compliance burdens.
- Telecommunication Companies:Mobile network operators in Brazil and India anchor volume demand. Tower operators prioritize remote monitoring compatibility to reduce physical maintenance schedules in dispersed site portfolios.
- Enterprises:Private 5G campus networks drive specialized backup specifications. Manufacturing and logistics facilities require guaranteed uptime for automated systems beyond standard telecom reliability thresholds.
- Government:Emergency communications infrastructure in the United States faces FCC-mandated minimum backup durations for 911-capable systems. Procurement cycles stretch longer due to budget appropriation timelines and public tender requirements.
- Utilities:Smart grid integration projects specify batteries with bidirectional power flow capabilities. Frequency regulation and peak shaving applications demand cycle depths calibrated to utility load profiles rather than telecom standards.
Telecommunication Companies sit at the top of the volume ranking, with Utilities climbing the fastest as grid-edge storage convergence accelerates.
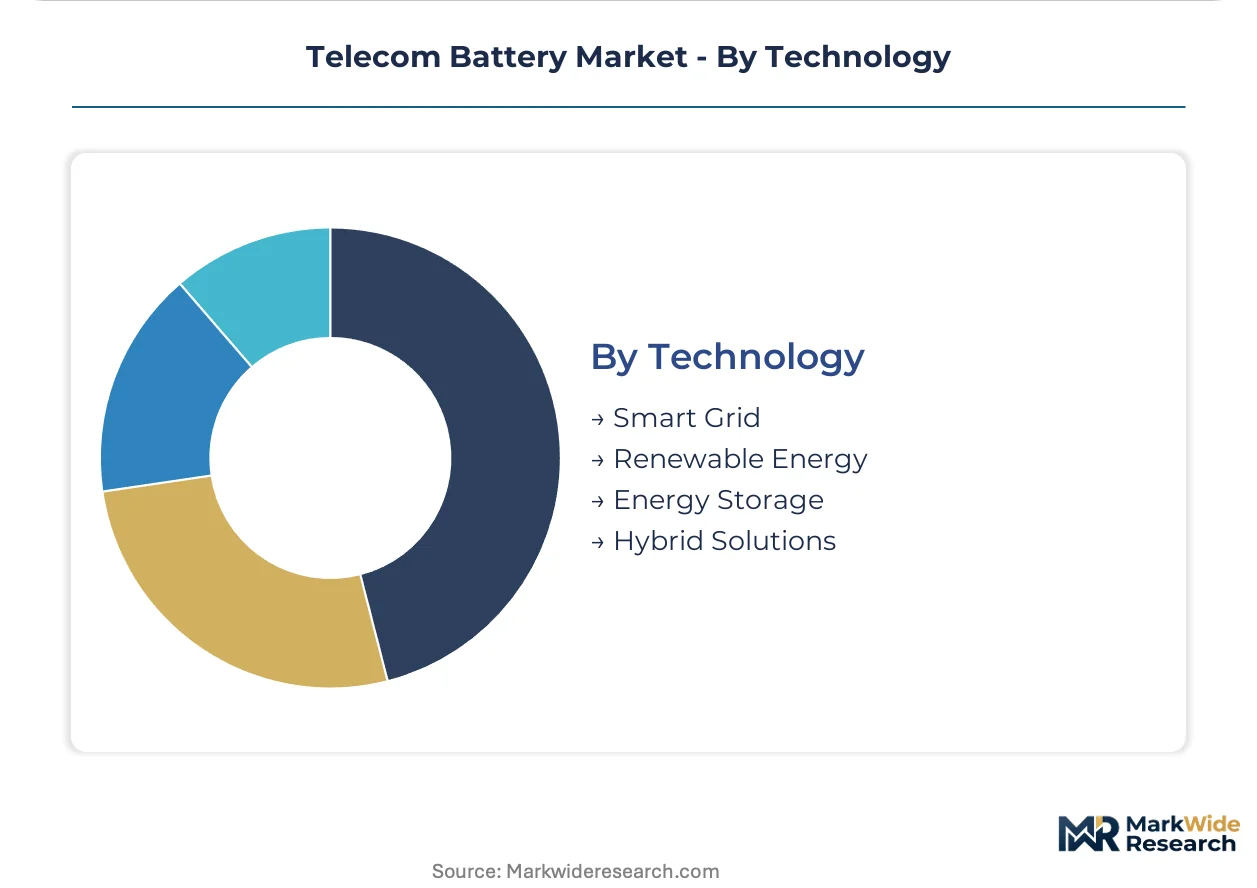
Technology:
System architecture choices determine thermal management complexity and vendor lock-in risk. Passive cooling designs gain traction where refrigerant-based systems face regulatory phaseout.
- Smart Grid:Bidirectional communication protocols enable demand response participation. Battery assets provide ancillary services to grid operators while maintaining telecom backup readiness.
- Renewable Energy:Solar-hybrid mandates from regulators in sub-Saharan markets displace diesel dependency. Photovoltaic generation paired with lithium storage eliminates fuel logistics in remote installations.
- Energy Storage:Standalone battery systems without generation coupling serve grid-connected sites with unreliable utility supply. Cycle life optimization focuses on shallow discharge patterns typical of telecom load profiles.
- Hybrid Solutions:Multi-technology architectures combine diesel, solar, and battery assets under unified control systems. IHS Holdings and American Tower deployments in Kenya and Nigeria lead this operational model.
Energy Storage sits at the top of the volume ranking, with Hybrid Solutions climbing the fastest as currency volatility constrains upfront capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage is driving battery pack assembly toward jurisdictions with subsidized cell manufacturing and lighter environmental compliance burdens. Module packagers are relocating to industrial corridors offering capital expenditure offsets and streamlined certification pathways. This migration pattern concentrates capacity in regions where domestic demand growth intersects with export-oriented manufacturing incentives.
China
CATL and BYD anchor domestic supply for tower operators migrating from lead acid toward energy-dense 48V rack systems. MIIT dual carbon goals accelerate factory electrification and renewable-powered production lines. Yangtze River Delta clusters around Ningde and Shenzhen dominate cell-to-pack integration for both domestic consumption and Southeast Asian export markets.
India
TRAI uptime mandates for rural base stations are doubling backup power density per site as 5G massive MIMO rollouts accelerate. PLI scheme subsidies for advanced chemistry cell manufacturing attract module packagers to Gujarat and Tamil Nadu industrial corridors. Kerala and Tamil Nadu coastal humidity zones host sodium-ion pilot deployments with Prussian white cathodes targeting tropical degradation resistance.
United States
FCC backup duration requirements for 911-capable infrastructure favor lithium-ion chemistry incompatible with legacy lead acid rectifier systems. Rural telecom cooperatives face stranded asset write-downs during mandated infrastructure upgrades. Southeast manufacturing corridors in Georgia and South Carolina attract Korean cell suppliers seeking IRA-compliant domestic content qualification.
Germany
EU F-Gas Regulation phaseout of hydrofluorocarbon refrigerants forces tower operators toward passive thermal management architectures. ECHA REACH compliance and CSRD disclosure requirements elevate due diligence burdens for cobalt-containing supply chains. Bavarian industrial zones around Munich concentrate battery system engineering for Nordic ambient-air cooling exports.
Brazil
Tower operators in São Paulo and Rio de Janeiro states are doubling backup capacity per site to support higher radio power draws from 5G antenna arrays. ANVISA-equivalent telecom regulator mandates intersect with state-level renewable integration incentives for solar-hybrid base stations. Minas Gerais mining corridors supply nickel feedstock for regional cathode material processing.
Telecom Battery Market Vendor Landscape
Capacity expansion dominates the current landscape as cell manufacturers scale gigafactory output to capture tower operator procurement contracts. The vendor base stratifies into three tiers: integrated cell-to-pack suppliers with captive cathode material streams, regional pack assemblers dependent on merchant cell markets, and second-life automotive battery reconfigurers serving price-sensitive African and Southeast Asian operators. Strategic archetypes include scale-driven Chinese manufacturers, Korean chemistry specialists, and North American channel-anchored service providers. M&A activity concentrates on BMS firmware capabilities and thermal management engineering talent, while geographic expansion through joint ventures secures local certification and tariff-advantaged production.
Within the integrated manufacturing tier, CATL represents scale-driven vertical control over cell-to-system production, while Samsung SDI exemplifies advanced cathode formulation specialization. EnerSys occupies a position among North American channel-anchured service providers with deep relationships in rural telecom cooperative markets. These three anchors illustrate divergent competitive vectors: manufacturing scale, materials science differentiation, and distribution infrastructure depth.
| Leading Market Players |
|---|
| Panasonic Energy |
| SK On |
| CATL |
| EnerSys |
| Tianjin Lishen Battery |
| BYD |
| Samsung SDI |
| Tesla |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between UL 9540A-qualified systems and uncertified pack assemblies splits pricing power and procurement pathways across tower operator vendor lists. This bifurcation concentrates margin capture among integrated cell-to-pack suppliers while compressing assembler margins and reshaping upstream cathode material contracting toward long-term offtake structures.
Pricing Analysis
Distributor margins for telecom rack systems compress against direct-to-tower-operator contracts that Korean and Chinese cell manufacturers negotiate at volume scale. Pricing stratifies across premium nickel-rich cathode systems, standard lithium iron phosphate benchmarks, and economy lead acid replacements, with differentiation driven by cycle life certification and embedded BMS telemetry depth. Cost compression in standard lithium tiers intensifies as sodium-ion pilots in India establish alternative chemistry floors. Rural telecom cooperatives in the United States exhibit highest price sensitivity due to stranded asset write-down exposure, while Nordic operators absorbing F-Gas compliance costs show lowest sensitivity.
Supply Chain Analysis
Cathode active material supply rests on Chinese nickel sulfate refining, Korean precursor synthesis, and Japanese specialty chemical coating operations. Cell production draws from concentrated electrode calendaring equipment and separator membrane feedstocks, with logistics chokepoints at Rotterdam and Singapore transshipment hubs. Distribution runs through regional pack assemblers in India and Southeast Asia who integrate cells into 48V rack systems for tower operator deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in telecom batteries hinges on sodium-ion chemistry maturation compressing cathode material costs below lithium iron phosphate benchmarks while premium nickel-rich systems capture tropical climate premiums.
For Market Incumbents: Anticipate sodium-ion module standardization eroding lithium iron phosphate volume in Indian coastal zones by securing Prussian white cathode supply agreements and pre-empting BIS certification for 100Ah rack configurations. Reinforce service network density in rural telecom cooperative territories before FCC-mandated backup duration upgrades accelerate lithium-ion replacement cycles. For New Entrants and Emerging Players: Capture second-life automotive pack reconfiguration opportunities in Nigerian and Kenyan markets where American Tower and IHS Holdings portfolios shift sixty percent of new deployments toward opex-based battery-as-a-service structures. Target solar-hybrid base station specifications in sub-Saharan Africa with leased asset models that transfer performance risk from currency-constrained mobile network operators. For Investors and Strategic Acquirers: Consolidation pressure builds where BMS firmware capabilities and thermal management engineering talent concentrate among mid-tier pack assemblers frozen out of UL 9540A approval timelines. Long-term viability favors acquirers of sodium-ion pilot operators in Kerala and Tamil Nadu industrial corridors. Watch TRAI mandate enforcement velocity in rural Indian base stations as inflection indicator for backup power density procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Ion Chemistry Scale-Up | Prussian white cathode production in Gujarat and Tamil Nadu corridors disrupts lithium cost structures for tropical deployments. |
| UL 9540A Certification Investment | Thermal runaway test protocol compliance secures tier-one tower operator vendor list placement against uncertified competitors. |
| Battery-as-a-Service Leasing Model | Opex-based contracts transfer currency volatility risk from Nigerian and Kenyan mobile network operators to storage providers. |
| Second-Life Automotive Pack Reconfiguration | Degraded EV modules with seventy to eighty percent remaining capacity cut material costs for price-sensitive African operators. |
| Passive Thermal Architecture R&D | F-Gas Regulation phaseout of hydrofluorocarbon refrigerants forces Nordic ambient-air cooling system deployment across European tower portfolios. |
Methodological Framework
Bottom-up tower operator procurement modeling reconciled against top-down cell manufacturer capacity tracking forms the analytical core of this study. Primary interviews with tower engineering directors, mobile network operator procurement leads, battery system integrators, and thermal management specialists combined with secondary validation against BIS certification databases, TRAI mandate filings, FCC backup duration rules, and EU F-Gas Regulation implementation guidance. Trade data from Indian DGFT, Chinese customs, and Korean export statistics anchored supply-side triangulation.
Historical deployment trendlines across lead acid, lithium-ion, and emerging sodium-ion chemistries established baseline penetration curves extended through the projection horizon. Segmentation modeling captured chemistry type, application context, end-user category, and technology architecture dimensions with CAGRs derived from fitted growth curves calibrated to regulatory mandate phase-in schedules and tower operator capital commitment patterns. Solar-hybrid deployment velocity in sub-Saharan Africa and edge computing micro-data center autonomy extensions provided industry-specific forecast inputs.
Regulatory mandate delays, cobalt supply disruption from Central African mining operations, and sodium-ion cycle life validation failures in tropical humidity zones are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions about PLI scheme disbursement timelines and IRA domestic content qualification pathways. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
String Inverter Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Global Flexible Batteries Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Telecom Power Systems Market
Power Systems
Voltage Regulators Market
Power Systems
Global Data Center Transformer Market
Power Systems
Batteries for Semiconductor Market
Power Systems
Power Inverter Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Battery Electronic Control Unit Market