
 Electrolyzer Test System Market | 2026-2036
Electrolyzer Test System Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyzer Test System Market Insights
Automotive-grade validation protocols are redrawing competitive boundaries in electrolyzer testing. Siemens Energy leverages its power-electronics heritage to anchor high-current test bench architectures. Nel Hydrogen sustains Nordic technology leadership through specialized PEM validation systems. Green Light Innovation competes on modular test skids designed for rapid deployment in distributed hydrogen hubs.
An electrolyzer test system is precision instrumentation that subjects electrolysis cells to controlled electrical load, thermal cycling, and pressure profiles to verify efficiency degradation curves and gas purity outputs; its commercial purpose is to certify stack performance before scale-up to production megawatt arrays. PEM test rigs command premium positioning due to membrane durability testing complexity, while alkaline systems occupy mature volume tiers with standardized protocols. Research institutions represent the fastest-growing end-user segment as national hydrogen strategies fund university-led stack innovation.
FDA oversight of hydrogen purity for medical-grade applications and EPA emissions frameworks for industrial hydrogen sourcing shape product specification tiers in the United States. EU Green Deal hydrogen bank criteria and CE marking for electrical safety determine market access thresholds for European deployments. Stakeholders must monitor how evolving ISO 22734 electrolyzer performance standards recalibrate test system certification requirements across jurisdictions.
Market Dynamics
PEM technology maturation is compressing validation timelines and forcing test system vendors to differentiate on throughput rather than specification breadth alone.
Growth Catalysts
- EU Green Deal hydrogen bank:German electrolyzer OEMs are expanding test capacity ahead of 2030 production targets, pulling demand for high-current validation benches.
- China's hydrogen valleys:State-backed industrial clusters in Shandong and Inner Mongolia mandate localized test infrastructure, creating captive demand for modular skid systems.
- Automotive-grade protocols:Fuel cell vehicle manufacturers are imposing automotive validation standards on electrolyzer suppliers, elevating test rig complexity and replacement frequency.
Market Restraints
- Platinum group metal volatility:PEM membrane catalyst costs fluctuate with South African mining output, squeezing test cell consumable budgets and extending payback periods.
- Specialized power electronics concentration:High-precision DC power supply manufacturing concentrates in German and Japanese industrial corridors, exposing buyers to single-source lead times.
- Alkaline protocol standardization:Mature testing standards for alkaline stacks limit premium pricing power, compressing margins for vendors without PEM differentiation.
Strategic Opportunities
- India's National Hydrogen Mission:Electrolyzer manufacturing incentives under the PLI scheme will require localized test infrastructure as domestic stack production scales.
- SOEC-AEM convergence:Solid oxide and anion exchange membrane technology maturation creates demand for hybrid test platforms capable of multi-technology validation.
- Research institution channel:University-led stack innovation programs funded by national hydrogen strategies represent an underdeveloped direct sales channel bypassing OEM intermediaries.
Industry Challenges
- ISO 22734 compliance timelines:Evolving electrolyzer performance standards require continuous test system recertification, consuming engineering resources and delaying product releases.
- Multiphysics simulation integration:Coupling physical test rigs with computational fluid dynamics and electrochemical modeling demands scarce cross-functional talent in electrochemistry and software engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyzer Test System Market |
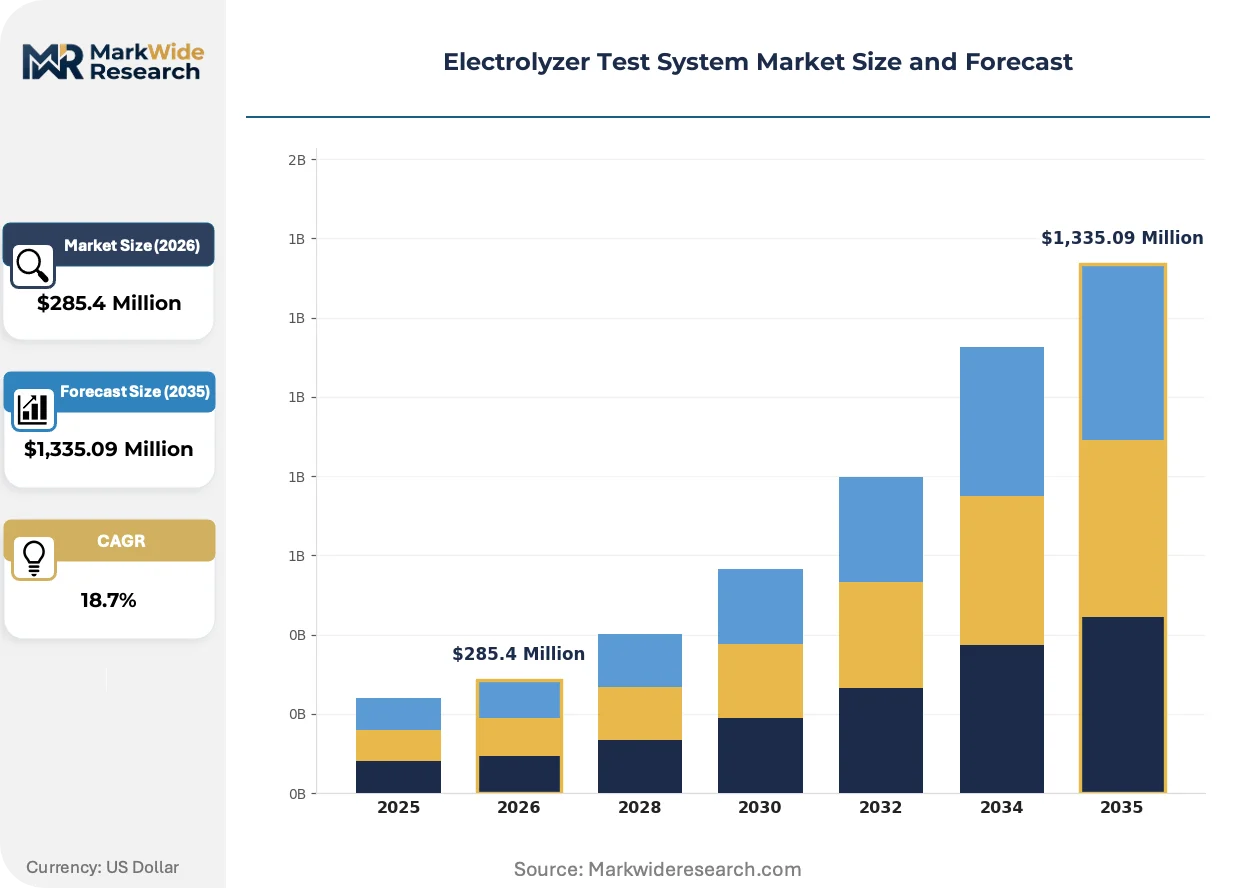
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Alkaline, PEM, Solid Oxide, Anion Exchange Membrane Scale: Small-Scale, Medium-Scale, Large-Scale, Modular End User: Utilities, Industrial Producers, Research Institutions, Energy Companies Application: Green Hydrogen Production, Renewable Energy Storage, Fuel Cell Applications, Water Treatment |
| Companies Covered | Siemens Energy, Nel Hydrogen, ITM Power, Thyssenkrupp, McPhy Energy, Green Light Innovation, HORIBA FuelCon, Scribner, AVL List GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyzer Test System Market Trends and Innovations
Test system architectures are fragmenting between centralized megawatt validation facilities and distributed rapid-deployment skids serving hydrogen hub construction timelines.
Digital twin integration is bifurcating test system value propositions. Virtual stack modeling reduces physical test cycles for established PEM designs. Nel Hydrogen and Siemens Energy are embedding simulation layers into hardware platforms. This convergence is compressing R&D timelines while elevating software competency requirements for test bench vendors.
CE marking revisions under the EU Machinery Directive are tightening electrical safety documentation for high-current test installations. German TÜV certification bodies are expanding hydrogen-specific audit capacity. European electrolyzer OEMs are front-loading compliance spending to avoid installation delays at hydrogen valley sites.
Validation service unbundling is disrupting traditional equipment-only contracts. Chinese industrial cluster developers now procure test capacity as operational expenditure through third-party validation houses. This preference shift pressures European and North American vendors to build local service partnerships or risk exclusion from state-backed procurement frameworks.
Electrolyzer Test System Market Segmentation
Electrolyzer test system procurement channels diverge sharply by segment, with OEMs favoring direct vendor relationships for high-current benches while research institutions increasingly source through specialized distributors. Understanding these channel dynamics illuminates where pricing power concentrates and where modular suppliers can bypass incumbent lock-in.
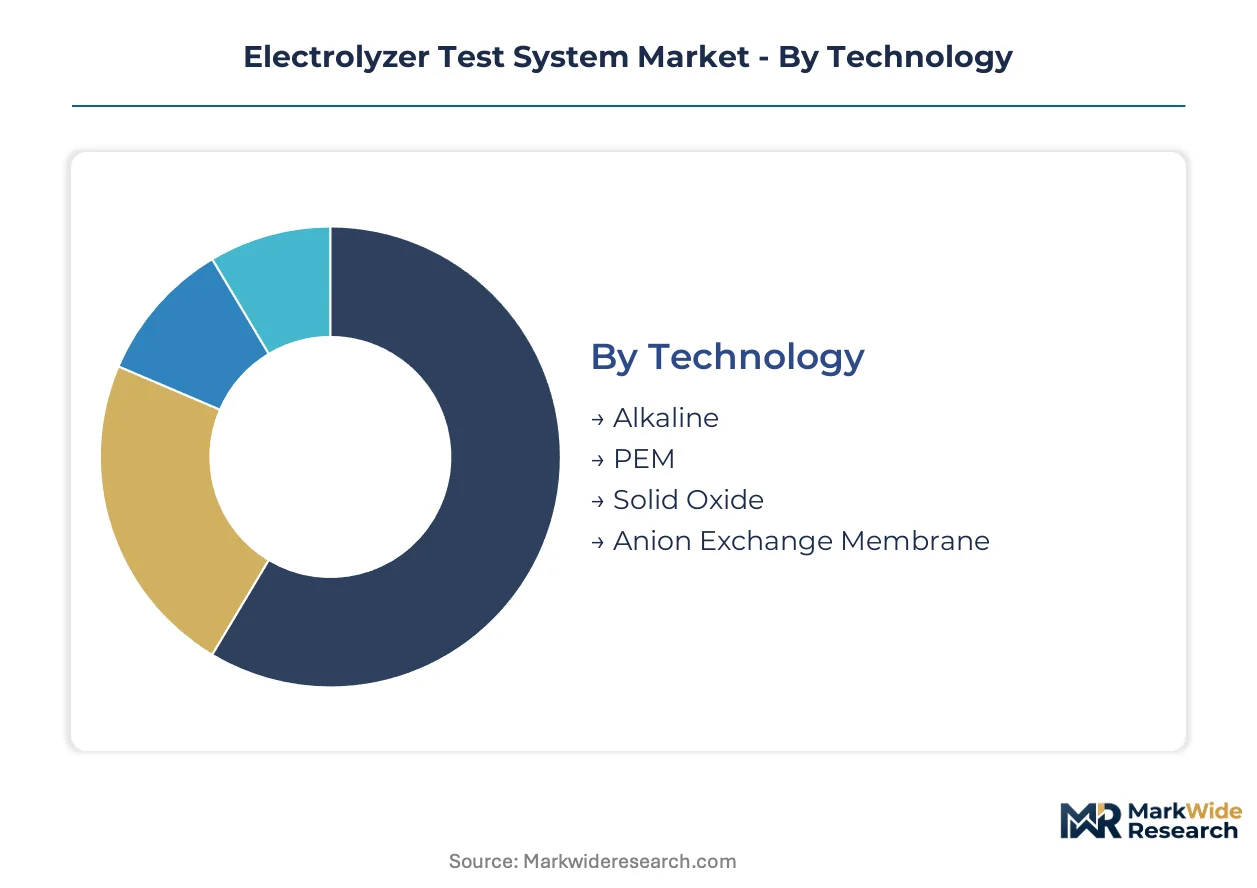
Technology:
Channel mix varies dramatically across electrolyzer chemistries, with PEM systems commanding premium direct sales while alkaline platforms flow through established industrial equipment distributors.
- PEM:Membrane durability testing complexity demands precision power electronics and thermal cycling rigs that OEMs source directly from Siemens Energy, Nel Hydrogen, and specialized German suppliers. German electrolyzer manufacturers expanding test capacity ahead of EU Green Deal targets are pulling disproportionate demand for these high-specification systems.
- Alkaline:Mature validation protocols and standardized test sequences allow procurement through broad-line industrial distributors serving China's hydrogen valleys in Shandong and Inner Mongolia. State-backed cluster developers favor turnkey alkaline test skids with localized service support.
- Solid Oxide:High-temperature operation requirements (700-900°C) restrict vendor base to specialized ceramics and thermal engineering houses in Japan and Germany.
- Anion Exchange Membrane:Emerging technology status drives direct collaboration between stack startups and university-affiliated test labs, bypassing traditional equipment channels.
By volume, alkaline leads. By growth pace, PEM is ahead.
Scale:
Cost tier segmentation separates capital-intensive megawatt facilities from rapidly deployable skids serving distributed hydrogen hub construction timelines.
- Large-Scale:Megawatt-class validation benches require dedicated electrical infrastructure and civil works, anchoring centralized test facilities in Germany's hydrogen valleys and China's industrial clusters. These installations command seven-figure capital commitments with decade-long depreciation schedules.
- Modular:Containerized or skid-mounted systems enable rapid deployment across multiple distributed production sites, aligning with India's National Hydrogen Mission timeline pressures and European hydrogen bank project milestones. Procurement often shifts to operational expenditure through third-party validation service contracts.
- Medium-Scale:Mid-range systems serve stack manufacturers transitioning from pilot to commercial production, typically sourced through regional system integrators.
- Small-Scale:Laboratory-scale rigs for materials research and membrane development flow through academic procurement channels with extended evaluation cycles.
Large-scale captures dominant revenue share. Modular configurations are climbing the fastest as distributed hydrogen infrastructure accelerates.
End User:
Customer type determines specification complexity, with utilities and industrial producers driving standardization while research institutions demand customization flexibility.
- Research Institutions:University-led stack innovation programs funded by national hydrogen strategies require adaptable test platforms supporting multiple electrolyzer chemistries and experimental protocols. These buyers prioritize software openness and sensor configurability over throughput metrics.
- Industrial Producers:Chemical and steel sector hydrogen offtakers need production-line validation systems with automotive-grade reliability standards, reflecting fuel cell vehicle manufacturer supplier requirements.
- Utilities:Power sector players integrating electrolyzers with renewable generation prioritize grid-synchronization testing and dynamic load response validation.
- Energy Companies:Oil and gas majors transitioning to hydrogen production seek vendor-managed test capacity rather than in-house equipment ownership.
Industrial producers dominate current procurement volume. Research institutions are expanding most quickly as government R&D funding redirects toward domestic stack development.
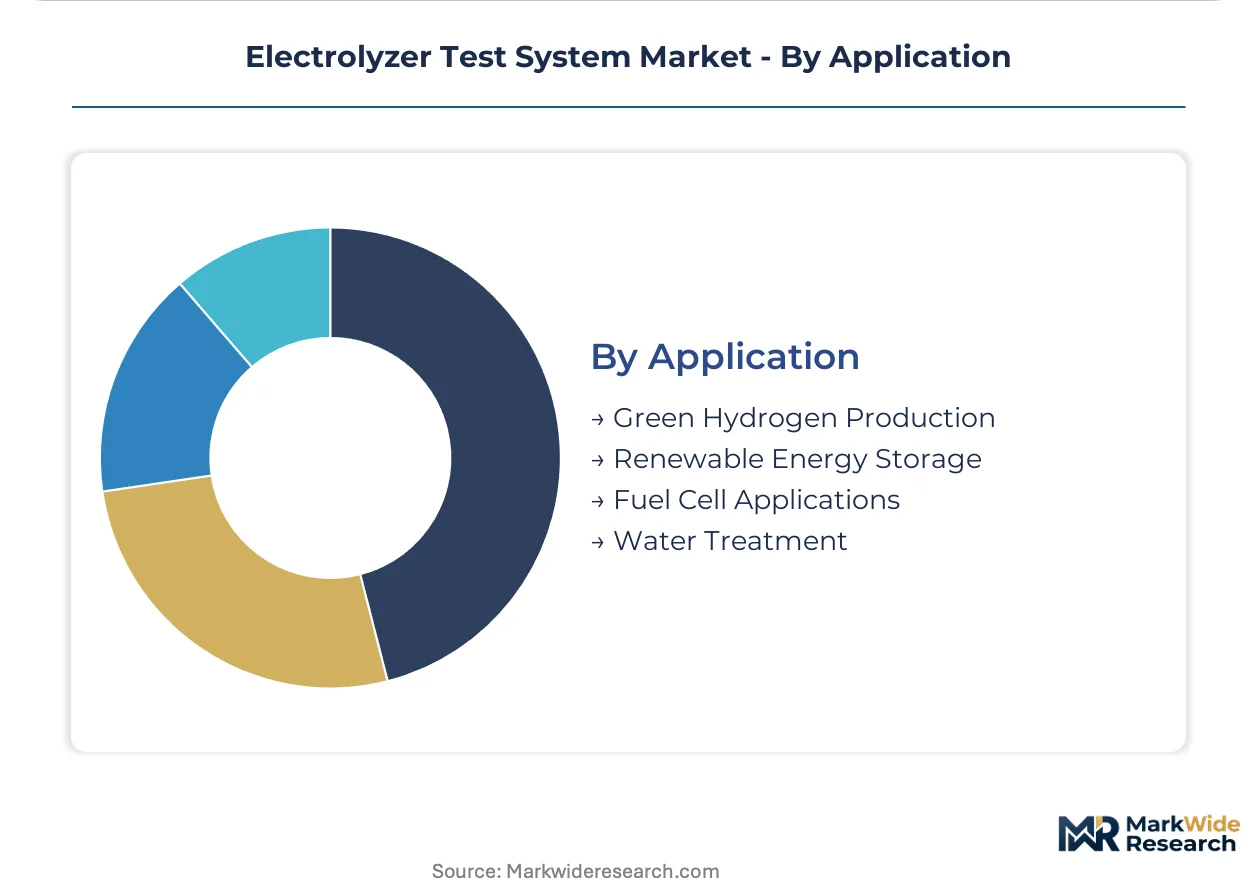
Application:
Application focus shapes geographic demand concentration, with green hydrogen production anchoring European and Chinese investment while fuel cell applications drive Japanese and Korean test system specifications.
- Green Hydrogen Production:Renewable-powered electrolysis validation requires integrated power electronics testing, thermal management verification, and gas purity certification under ISO 22734 frameworks. EU Green Deal hydrogen bank criteria and China's dual carbon goals are synchronizing demand for production-scale test infrastructure.
- Renewable Energy Storage:Power-to-gas applications demand dynamic response testing simulating wind and solar intermittency, with German TÜV certification bodies expanding audit protocols for grid-connected installations.
- Fuel Cell Applications:Automotive-grade validation standards imposed by fuel cell vehicle manufacturers elevate test rig complexity for hydrogen quality and pressure cycling verification.
- Water Treatment:Niche application for specialized industrial electrolyzers with distinct membrane and electrode testing requirements.
Green hydrogen production anchors the largest installed base. Renewable energy storage applications are gaining share fastest as grid-balancing economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test system trade flows favor manufacturing economies with deep power-electronics supply chains. Germany and China run structural export surpluses in high-current validation benches, while hydrogen-importing markets in India and the Middle East absorb inbound equipment shipments.
Germany
Siemens Energy and Nel Hydrogen anchor domestic production of PEM validation systems for EU Green Deal hydrogen bank projects. TÜV certification bodies under the EU Machinery Directive enforce electrical safety documentation for megawatt-class installations. Industrial clusters in North Rhine-Westphalia host centralized test facilities serving electrolyzer OEMs scaling toward 2030 production targets.
China
State-backed hydrogen valleys in Shandong and Inner Mongolia mandate localized test infrastructure procurement under dual carbon implementation frameworks. MIIT industrial policy directs domestic equipment sourcing for electrolyzer manufacturing lines. Pearl River Delta system integrators supply modular skid configurations to industrial cluster developers preferring operational expenditure contracts over capital purchases.
United States
FDA oversight of hydrogen purity for medical-grade applications and EPA emissions frameworks shape specification tiers for domestic test system deployments. Fuel cell vehicle manufacturers impose automotive-grade validation standards on electrolyzer suppliers, elevating test rig complexity. Texas and California hydrogen hub awards under the IRA are pulling demand for rapid-deployment validation capacity.
India
PLI scheme incentives for electrolyzer manufacturing are creating captive demand for localized test infrastructure as domestic stack production scales. BIS standards development for hydrogen equipment lags equipment deployment timelines, creating certification uncertainty. Gujarat and Maharashtra industrial corridors are emerging as concentration points for validation facility construction ahead of National Hydrogen Mission deadlines.
Japan
METI hydrogen roadmap targets are sustaining investment in solid oxide electrolyzer test platforms requiring high-temperature thermal cycling capabilities. JIS standards for fuel cell applications extend to electrolyzer quality verification protocols. Kansai region ceramics specialists supply thermal engineering components for SOEC validation rigs serving domestic and export markets.
Electrolyzer Test System Market Competitive Landscape
Listed leaders compete with private specialists across capital access and technology agility dimensions. Siemens Energy and Thyssenkrupp leverage public market financing for megawatt facility expansion, while Green Light Innovation and Scribner maneuver faster on modular product iterations. Three archetypes dominate: diversified industrial conglomerates with power-electronics heritage, pure-play hydrogen equipment specialists, and precision instrumentation houses pivoting from fuel cell testing. Competitive moves concentrate on strategic partnerships for localized service networks and technology licensing for hybrid test platforms spanning multiple electrolyzer chemistries.
Within the conglomerate tier, Siemens Energy and Thyssenkrupp exemplify European industrial diversification into hydrogen validation infrastructure. Nel Hydrogen occupies the pure-play specialist position, representing Nordic technology concentration in PEM system architecture. Green Light Innovation anchors the modular rapid-deployment segment, sitting within a competitive space where Chinese industrial cluster procurement preferences are reshaping contract structures toward operational expenditure models. AVL List GmbH and HORIBA FuelCon exemplify instrumentation specialists extending automotive testing expertise into electrolyzer validation protocols.
| Leading Market Players |
|---|
| Siemens Energy |
| Nel Hydrogen |
| ITM Power |
| Thyssenkrupp |
| McPhy Energy |
| Green Light Innovation |
| HORIBA FuelCon |
| Scribner |
| AVL List GmbH |
| Others |
Pricing and Supply Chain Analysis
Sixteen-to-twenty-week lead times for high-precision DC power supplies from German and Japanese corridors compress pricing power for PEM validation benches while amplifying cost pass-through leverage for incumbent vendors serving EU hydrogen bank projects.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture membrane durability testing complexity with ISO 22734 certification requirements, while standardized alkaline protocols compress margins at the economy tier. Pricing pressure stems from platinum group metal volatility squeezing test cell consumable budgets. Research institutions exhibit highest price sensitivity due to extended academic procurement cycles, whereas automotive-grade validation buyers prioritize specification compliance over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for ceramic thermal components sourced from Japanese Kansai region suppliers. Manufacturing concentrates in Germany, China, and Japan for power electronics, thermal cycling rigs, and precision instrumentation respectively. The supply chain draws from platinum catalysts, proton exchange membranes, and high-temperature ceramics as critical inputs. Single-source vulnerability concentrates in specialized DC power supply manufacturing. Distribution runs through direct vendor relationships for PEM systems and broad-line industrial distributors for alkaline platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrolyzer test system market sits in early-cycle recovery as national hydrogen strategies fund capacity buildouts ahead of production scale-up deadlines.
For Market Incumbents: Fortify service network localization in China's hydrogen valleys and India's industrial corridors to defend against state-backed procurement preferences shifting toward operational expenditure contracts. Deepen backward integration into power electronics manufacturing to reduce exposure to sixteen-to-twenty-week lead times from German and Japanese suppliers. Prioritize CE marking documentation investments under EU Machinery Directive revisions to preempt installation delays at European hydrogen valley sites. For New Entrants and Emerging Players: Differentiate on hybrid test platforms capable of multi-technology validation spanning SOEC-AEM convergence trends. Target India's National Hydrogen Mission timeline pressures as the most penetrable geography, where BIS standards lag equipment deployment and create certification uncertainty windows. Pursue university-led stack innovation programs as a direct sales channel bypassing OEM intermediaries, emphasizing software openness and sensor configurability over throughput metrics. For Investors and Strategic Acquirers: Long-term, this sits as a capital-goods cyclical play because electrolyzer manufacturing capacity waves drive lumpy test system procurement tied to policy milestone deadlines. Acquisition targets should emphasize precision instrumentation houses with automotive testing heritage pivoting into electrolyzer validation protocols. Watch ISO 22734 recertification timelines as the signal indicating vendor engineering resource strain and product release delays.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for Hybrid Platforms | Enables multi-chemistry validation capability as SOEC-AEM convergence accelerates stack innovation cycles. |
| Localized Service Partnership Buildout | Secures access to Chinese state-backed procurement frameworks favoring operational expenditure contract structures. |
| Digital Twin Integration Investment | Compresses R&D timelines for PEM designs while elevating software competency barriers against modular competitors. |
| CE Marking Pre-Compliance Spending | Avoids TÜV audit delays at German hydrogen valley megawatt installation sites under Machinery Directive revisions. |
| University Channel Direct Sales Development | Bypasses OEM intermediaries in fastest-growing research institution segment funded by national hydrogen strategies. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrolyzer OEM procurement directors, university research lab managers, TÜV certification auditors, and hydrogen valley project developers; and secondary validation against SEC filings from listed industrial conglomerates, MIIT policy directives, EU Green Deal hydrogen bank criteria documentation, and customs trade data for power electronics imports. Bottom-up stack manufacturer demand estimates triangulated against top-down national hydrogen strategy funding allocations.
Across the analysis window, the forecasting framework modeled volume and value outputs by technology chemistry, system scale tier, end-user category, and application focus. CAGRs derived from electrolyzer manufacturing capacity buildout schedules, policy milestone deadlines, and validation cycle compression trends. Industry-specific inputs included platinum group metal price volatility bands and ISO 22734 standard evolution timelines.
The analysis sits within stated boundaries; outcomes outside sustained policy funding for hydrogen infrastructure, stable platinum catalyst supply from South African mining output, or continued PEM technology maturation would require recalibration. Forecasts reflect documented assumptions regarding electrolyzer OEM production scale-up trajectories and state-backed cluster development timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Calibration Services Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market