
 South America DC Distribution Network Market | 2026-2036
South America DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
South America DC Distribution Network Market Analytics
Utility procurement fragmentation across Brazil's distributed generation cooperatives is recalibrating vendor engagement models. ABB Ltd leverages its transformer manufacturing footprint to anchor large-scale industrial contracts. Siemens Energy AG competes through integrated switchgear solutions for data center clients. Schneider Electric SE controls channel access via established electrical distributor partnerships across the Southern Cone.
A DC distribution network transmits electrical power using direct current rather than alternating current, typically operating at voltages from 380V to 1500V depending on application scale and employing solid-state circuit breakers for fault isolation. The architecture eliminates AC-DC conversion stages, reducing energy losses in facilities with high native DC loads such as solar PV arrays, battery storage systems, and LED lighting infrastructure. Panel boards and switchgear dominate product type revenue due to recurring replacement cycles in aging Brazilian industrial parks. Data centers represent the fastest-growing end user segment as cloud providers retrofit facilities for 48V rack-level distribution. Commercial applications remain mature across Argentine retail chains with limited expansion appetite.
Brazil's ANEEL governs grid interconnection standards for distributed generation assets, while Argentina's ENRE oversees transmission access tariffs that influence DC microgrid economics. Chile's SEC mandates electrical safety certifications that shape product compliance costs for imported switchgear. Stakeholders must monitor regulatory divergence across Mercosur members when standardizing procurement specifications.
Market Dynamics
ANEEL's net metering reforms are compressing payback periods for distributed generation assets, forcing industrial buyers to reconfigure power architectures around native DC loads from solar PV and battery storage systems.
Growth Catalysts
- ANEEL net metering reforms:Brazil's regulatory framework now permits full energy credit rollover for commercial DC microgrid operators, eliminating prior monthly expiration penalties that discouraged capital deployment.
- Data center rack-level conversion:Cloud providers across São Paulo's industrial corridor are retrofitting facilities for 48V DC distribution, eliminating AC-DC conversion losses at server level.
- Lithium-ion storage cost curves:Falling battery pack prices are enabling hybrid DC architectures that buffer renewable intermittency without grid-scale transmission upgrades.
Market Restraints
- Copper price volatility:Busbar and conductor raw material costs swing with commodity markets, compressing margins for panel board manufacturers serving Brazilian industrial parks.
- Import dependency for solid-state breakers:Domestic production capacity for DC-rated switching equipment concentrates in East Asian supply chains, exposing buyers to extended lead times.
- AC infrastructure lock-in:Existing transformer substations and distribution networks create path dependency that slows full DC conversion timelines for legacy manufacturing facilities.
Strategic Opportunities
- Chilean mining electrification:Copper and lithium extraction operations in the Atacama Desert require resilient off-grid power architectures where DC microgrids eliminate transmission losses from remote renewable sites.
- Argentina's distributed generation cooperatives:ENRE tariff structures are creating procurement fragmentation that rewards vendors with localized assembly capabilities and cooperative financing relationships.
- LED lighting retrofits:Commercial building efficiency mandates are driving demand for 380V DC distribution that eliminates redundant conversion stages between solar arrays and native DC loads.
Industry Challenges
- DC safety certification gaps:Chile's SEC mandates electrical safety testing protocols that lack harmonization with Brazilian INMETRO standards, forcing manufacturers to maintain dual compliance documentation.
- Specialized commissioning expertise:Solid-state breaker configuration and DC arc fault detection require field engineers with training that outpaces vocational program curricula across Mercosur member states.
- Legacy AC protection coordination:Industrial facilities must engineer complex interface logic between new DC microgrids and existing AC protective relaying schemes, extending project commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America DC Distribution Network Market |
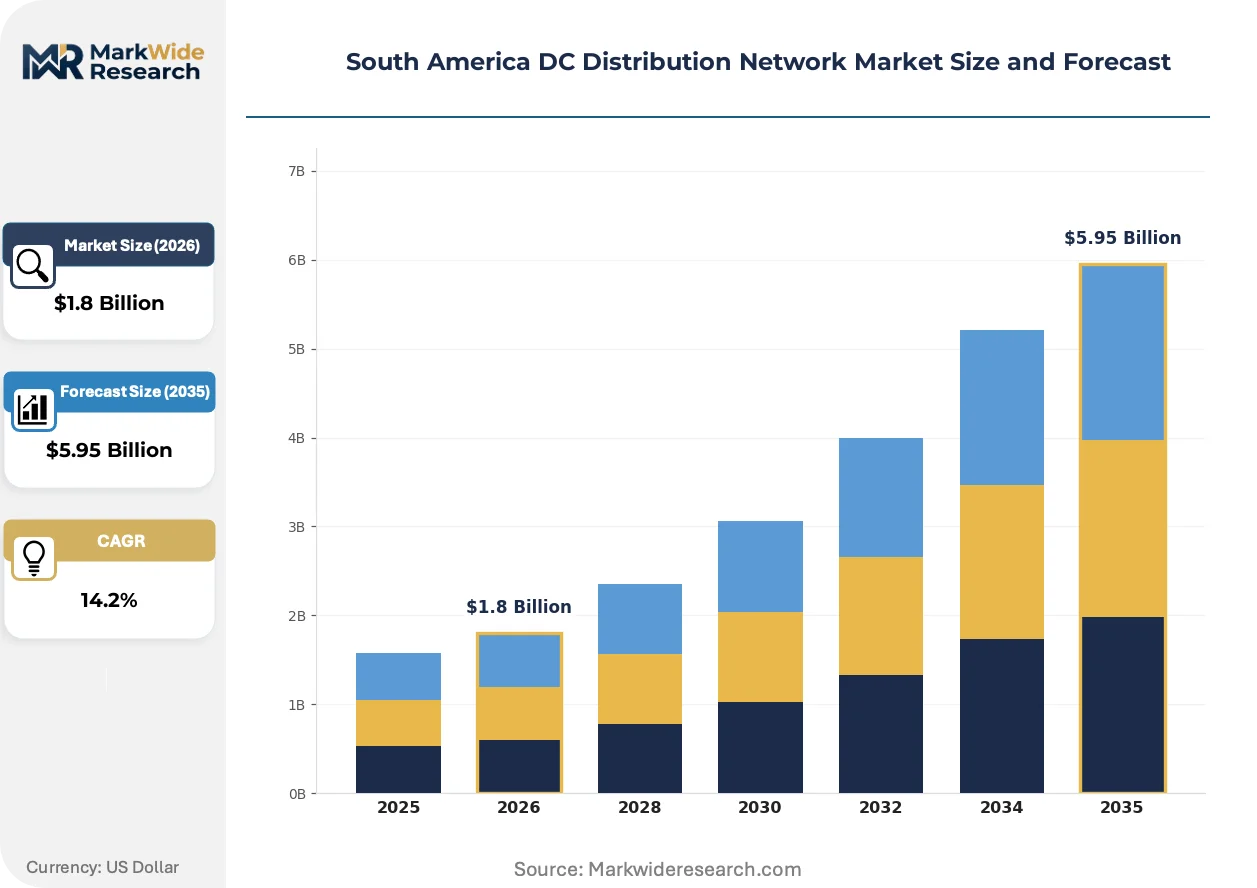
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Circuit Breakers, Switchgear, Panel Boards Application: Commercial, Industrial, Residential, Utility End User: Retailers, Manufacturers, Energy Providers, Data Centers Installation Type: New Construction, Retrofits, Upgrades, Maintenance |
| Companies Covered | Vertiv Group Corp, Sécheron SA, ABB Ltd, Nextek Power Systems Inc, Alpha Technologies Inc, Siemens Energy AG, Eaton Corporation PLC, Hitachi Energy, Schneider Electric SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America DC Distribution Network Market Evolving Landscape
Silicon carbide power electronics and modular DC switchgear architectures are compressing system footprints while enabling higher voltage operation, reshaping how industrial buyers evaluate total installed cost against operational efficiency gains.
Solid-state circuit breakers employing silicon carbide MOSFETs are replacing mechanical contactors in high-current DC applications. Data center operators in São Paulo's industrial corridor are specifying these devices for 1500V bus protection. This semiconductor transition is electrifying fault isolation response times from milliseconds to microseconds, enabling denser power distribution architectures.
ANEEL's regulatory revisions for distributed generation interconnection standards are mandating bidirectional metering infrastructure. Industrial facilities must now install certified power quality monitoring equipment to qualify for net metering credits. Brazilian panel board manufacturers are responding by integrating revenue-grade metering into pre-wired distribution assemblies.
Cloud providers are unbundling power infrastructure procurement from general electrical contracting, establishing direct vendor relationships with DC switchgear specialists. This disintermediation bypasses traditional electrical distributor markups in Chile's data center construction market. The shift is most visible in Santiago's emerging hyperscale cluster, where owner-operators specify equipment directly to optimize for 48V rack-level efficiency targets.
South America DC Distribution Network Market Segmentation
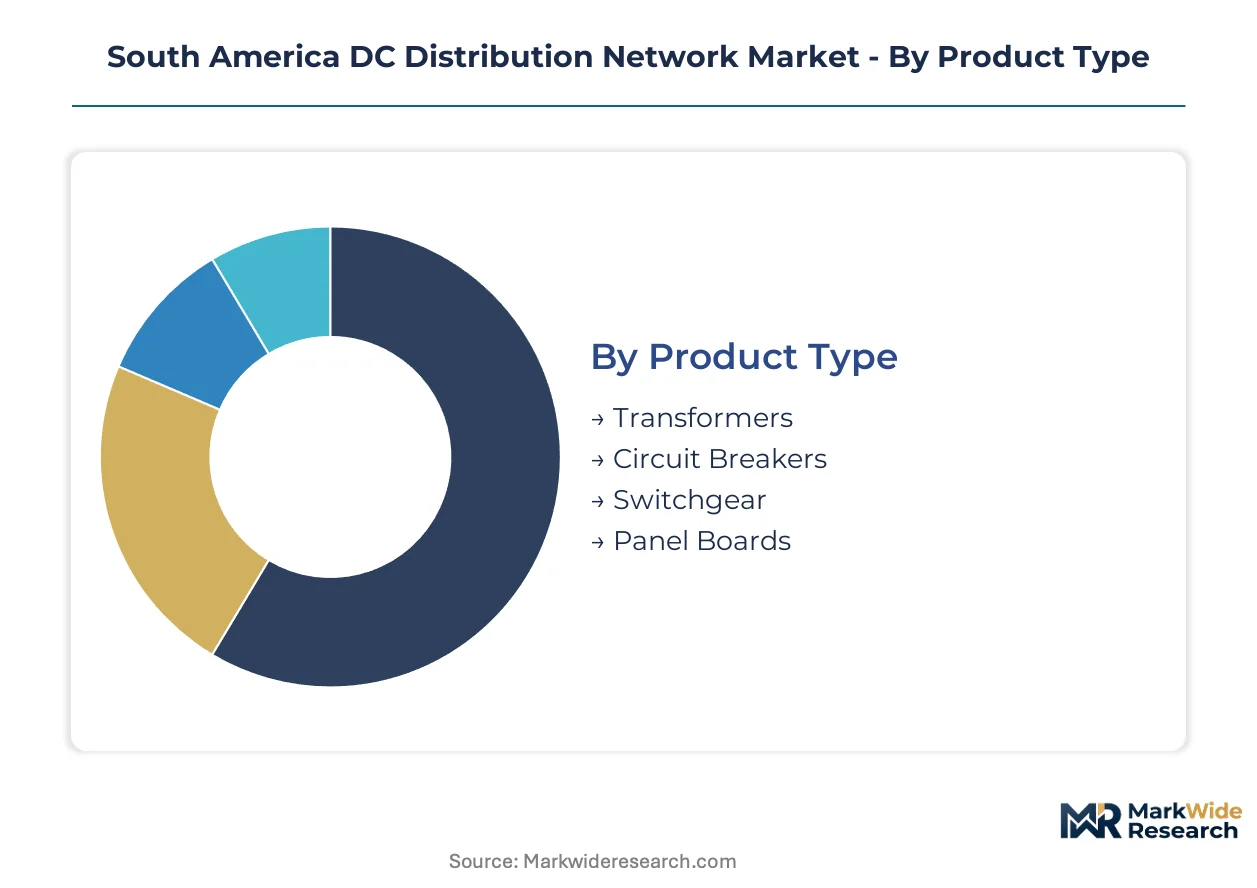
DC distribution architectures in South America fragment across voltage classes and deployment contexts. Equipment specifications diverge sharply between legacy industrial retrofits and hyperscale data center greenfield projects. Procurement patterns in Brazil's regulated utility sector contrast with Chile's unregulated mining electrification market.
Product Type:
Panel boards and switchgear dominate revenue due to recurring replacement cycles, while transformers and circuit breakers split between premium efficiency tiers and standard commodity specifications.
- Panel Boards:Pre-wired distribution assemblies integrate revenue-grade metering mandated by ANEEL's bidirectional interconnection standards. Demand concentrates in São Paulo's aging industrial parks where manufacturers face compressed payback timelines for solar PV integration.
- Switchgear:Modular DC architectures employing silicon carbide MOSFETs enable 1500V bus protection with microsecond fault isolation. Santiago's hyperscale data center cluster drives specification of solid-state configurations that eliminate mechanical contactor maintenance.
- Circuit Breakers:DC-rated solid-state breakers rely on East Asian supply chains, exposing Brazilian buyers to extended lead times.
- Transformers:ABB leverages manufacturing footprints to anchor large-scale industrial contracts across the Southern Cone.
Mature deployment sits with Panel Boards. Newer deployment is concentrated in Switchgear.
Application:
Industrial buyers prioritize resilient architectures for renewable buffering, while commercial and utility applications diverge across regulatory jurisdictions.
- Industrial:Manufacturers in São Paulo's corridor reconfigure power architectures around native DC loads from solar PV and lithium-ion storage. ANEEL net metering reforms eliminate monthly credit expiration penalties that previously discouraged capital deployment.
- Data Center:Cloud providers retrofit facilities for 48V rack-level distribution, eliminating AC-DC conversion losses at server level. This segment climbs the fastest as owner-operators disintermediate traditional electrical distributors.
- Commercial:Argentine retail chains exhibit limited expansion appetite for LED lighting retrofits despite efficiency mandates.
- Utility:Brazilian distributed generation cooperatives create procurement fragmentation that rewards vendors with localized assembly capabilities.
Revenue concentration tilts toward Industrial. Technology innovation centers on Data Center.
End User:
Energy providers and manufacturers anchor current procurement volumes, while data centers and retailers occupy opposite ends of the technology adoption curve.
- Data Centers:Hyperscale operators in Santiago and São Paulo specify equipment directly to optimize for 48V rack-level efficiency targets, bypassing distributor markups.
- Manufacturers:Industrial facilities engineer complex interface logic between new DC microgrids and existing AC protective relaying schemes, extending commissioning timelines.
- Energy Providers:Chilean copper and lithium extraction operations in the Atacama Desert require off-grid DC microgrids that eliminate transmission losses from remote renewable sites.
- Retailers:Argentine retail chains maintain mature AC infrastructure with minimal DC conversion appetite.
Procurement sophistication is highest with Data Centers. Legacy lock-in persists with Retailers.
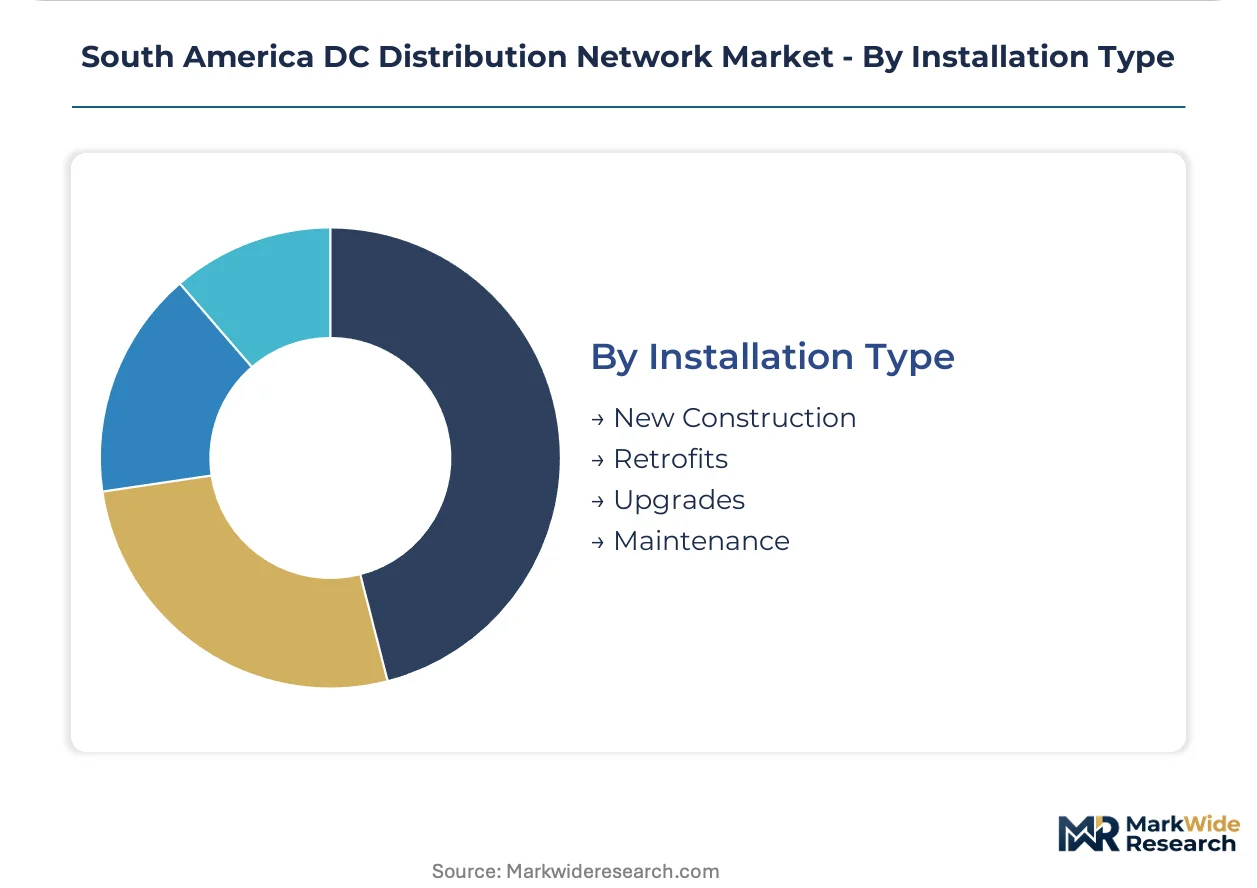
Installation Type:
New construction commands premium pricing for integrated DC-native designs, while retrofits and upgrades navigate path dependency constraints.
- New Construction:Greenfield data center projects in Santiago's emerging cluster specify 1500V DC distribution from foundation, avoiding AC infrastructure lock-in entirely.
- Retrofits:Brazilian industrial facilities must coordinate DC microgrid commissioning with existing transformer substations, slowing full conversion timelines.
- Upgrades:Panel board replacements in aging São Paulo industrial parks drive recurring revenue for manufacturers with established distributor partnerships.
- Maintenance:Solid-state breaker configuration requires field engineers with training that outpaces vocational program curricula across Mercosur member states.
Technical flexibility is greatest with New Construction. Operational complexity concentrates in Retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for DC distribution infrastructure clusters in Brazil's industrial corridor, with São Paulo manufacturers driving procurement volumes for solar-buffered microgrids. Chile's mining sector and Argentina's cooperative utilities anchor secondary growth nodes across the Southern Cone.
Brazil
São Paulo's manufacturing belt dominates equipment procurement as factories reconfigure around native DC loads from lithium-ion storage systems. ANEEL's net metering reforms now permit full energy credit rollover for commercial operators, eliminating prior monthly expiration penalties. Panel board demand concentrates in aging industrial parks where replacement cycles intersect with solar PV integration timelines.
Chile
Copper and lithium extraction operations in the Atacama Desert require resilient off-grid architectures that eliminate transmission losses from remote renewable sites. SEC mandates electrical safety certifications for imported switchgear, shaping product compliance costs and vendor selection criteria. Santiago's emerging hyperscale data center cluster drives specification of 1500V DC distribution systems with solid-state protection.
Argentina
ENRE tariff structures for distributed generation cooperatives create procurement fragmentation that rewards vendors with localized assembly capabilities. Commercial LED lighting retrofits face limited expansion appetite among retail chains despite building efficiency mandates. Buenos Aires industrial zones exhibit slower DC conversion timelines due to legacy AC infrastructure lock-in and protective relaying complexity.
Colombia
Andean mining electrification projects are evaluating DC microgrids for remote extraction sites with unreliable grid access. The national mining regulator is developing technical guidelines for off-grid power architectures in environmentally sensitive extraction zones. Antioquia's industrial corridor represents the primary concentration of early-stage pilot deployments for hybrid renewable-buffered systems.
South America DC Distribution Network Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular silicon carbide architectures and direct data center procurement relationships. The vendor base stratifies between transformer manufacturers anchoring large-scale industrial contracts and switchgear specialists capturing hyperscale facility retrofits. Two strategic archetypes dominate: integrated electrical conglomerates leveraging distributor networks, and power electronics specialists disintermediating traditional channels. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through cooperative financing structures.
Among Swiss-based specialists, Sécheron SA occupies a position within the high-voltage DC protection tier. ABB Ltd exemplifies the integrated conglomerate archetype with manufacturing footprints spanning the Southern Cone. Schneider Electric SE anchors the distributor-centric model through established electrical channel partnerships across Brazil and Chile. Siemens Energy AG represents the integrated solutions vector competing for data center switchgear specifications.
| Leading Market Players |
|---|
| Vertiv Group Corp |
| Sécheron SA |
| ABB Ltd |
| Nextek Power Systems Inc |
| Alpha Technologies Inc |
| Siemens Energy AG |
| Eaton Corporation PLC |
| Hitachi Energy |
| Schneider Electric SE |
| Others |
Value Network & Pricing Analysis
Chile's SEC electrical safety certifications gate qualified supply access and premium-tier pricing for DC distribution equipment across the Southern Cone, compressing margins for non-compliant manufacturers while rewarding certified vendors with pricing power in Santiago's hyperscale data center cluster.
Pricing Analysis
Volume concentrates in standard-grade panel boards for Brazilian industrial retrofits, while margins accrue to silicon carbide switchgear for 1500V data center applications. Pricing stratifies across premium certified tiers, standard efficiency grades, and economy commodity specifications, with SEC and INMETRO dual compliance driving differentiation. Cost compression in standard busbar assemblies intensifies because copper price volatility squeezes manufacturer margins. Municipal utilities and cooperative distributors exhibit highest price sensitivity, whereas hyperscale cloud operators prioritize efficiency metrics over unit cost.
Supply Chain Analysis
Solid-state breaker production rests on East Asian semiconductor foundries, with Taiwan, South Korea, and Japan anchoring DC-rated switching equipment capacity. Copper busbar and lithium-ion battery pack inputs draw from Chilean mining operations and Chinese cell manufacturing respectively. Single-source vulnerability for silicon carbide MOSFETs exposes Brazilian panel board assemblers to extended procurement cycles. Distribution runs through established electrical distributor partnerships across Brazil and Chile, though data center operators increasingly disintermediate traditional channels for direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Chile's SEC certification mandates create a barrier-to-entry moat for switchgear vendors with dual-standard documentation capabilities.
For Market Incumbents: Lock in distributor channel control across Brazil's ANEEL-regulated utility sector to defend against modular silicon carbide specialists disintermediating traditional procurement. Deepen backward integration into semiconductor sourcing for solid-state breaker production to reduce East Asian supply dependency. Prioritize certification investment for dual SEC-INMETRO compliance to maintain premium-tier pricing access in cross-border Mercosur contracts. For New Entrants and Emerging Players: ANEEL's net metering reforms in Brazil open a window for cooperative financing relationships with distributed generation utilities seeking localized assembly capabilities. Target Argentina's ENRE-fragmentated procurement environment where incumbent distributor relationships remain underdeveloped. Pursue direct owner-operator sales channels in Santiago's emerging hyperscale data center cluster, bypassing traditional electrical distributor markups through 48V rack-level efficiency specialization. For Investors and Strategic Acquirers: Cloud provider disintermediation of general electrical contractors is the leading indicator that procurement sophistication is concentrating in hyperscale facility specifications. Frame long-term viability around vendors with captive silicon carbide semiconductor sourcing and dual-jurisdiction certification capabilities. Monitor solid-state breaker lead time compression as the signal for supply chain localization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Semiconductor Sourcing | Captive supply of silicon carbide MOSFETs insulates Brazilian panel board manufacturers from East Asian lead time volatility. |
| Dual Certification Investment for SEC and INMETRO Standards | Dual compliance documentation unlocks premium pricing tiers in cross-border Chilean-Brazilian utility contracts. |
| Direct Procurement Relationship with Hyperscale Data Centers | Bypassing electrical distributor markups captures margin in Santiago's 1500V DC specification market. |
| Cooperative Financing Partnership with Argentine Utilities | Localized assembly capabilities align with ENRE tariff structures favoring distributed generation cooperatives. |
| Revenue-Grade Metering Integration in Pre-Wired Assemblies | ANEEL's bidirectional interconnection mandate creates replacement cycle demand in São Paulo's aging industrial parks. |
Research Methodology
Independent corroboration across primary interviews with data center infrastructure directors, utility planning officers at Brazilian cooperatives, EPC contractors specializing in mining electrification, and solid-state breaker procurement leads underwrites the qualitative findings. Secondary validation drew from ANEEL distributed generation interconnection filings, SEC electrical safety certification databases, Chilean mining project development registries, and customs records for DC switchgear imports. Bottom-up equipment procurement surveys triangulate against top-down market sizing from regulatory capacity announcements.
Historical reference periods spanning pre-reform and post-reform regulatory environments anchored the forecast window, with growth trajectories calibrated to policy implementation timelines. Segmentation modeling incorporated voltage class, application context, end-user procurement sophistication, and installation type across the projection horizon. CAGRs derived from equipment replacement cycle analysis, renewable integration adoption curves, and data center construction pipeline tracking. Key inputs included lithium-ion storage cost trajectories and copper commodity price volatility assumptions.
Caveats apply where ANEEL regulatory revision timelines, SEC certification harmonization negotiations, or East Asian semiconductor supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding net metering credit rollover permanence and hyperscale data center buildout commitment durability. A small set of named triggers including solid-state breaker localization progress and copper price regime shifts warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Automotive Inverters Market
Power Systems
Thyristor Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Japan Surge Protector Market
Power Systems
Power Semiconductor Market
Power Systems
Battery Racks Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Traction Inverter Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Global Data Center Transformer Market
Power Systems
Central Battery Systems Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Medium Voltage Drives Market
Power Systems
Battery Electronic Control Unit Market