
 Global Data Center Transformer Market | 2026-2036
Global Data Center Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Transformer Market Foresight
Power systems engineering talent scarcity is bifurcating the competitive landscape into firms with captive design depth and those dependent on outsourced specification. ABB Ltd. leverages its transformer and grid automation integration to capture early-stage hyperscale engineering engagement. Siemens Energy AG anchors European supply through regional manufacturing and IEC standard pre-certification. Hitachi Energy Ltd. competes on liquid-filled and dry-type platforms for high-density AI training facilities.
Data center transformers are electromagnetic devices that convert medium-voltage utility feed to low-voltage distribution suitable for server rack power supplies, typically operating at 50/60 Hz with insulation classes rated for continuous thermal stress in enclosed environments. Step-down configurations dominate product type demand as hyperscale and colocation facilities require voltage reduction from 11-33 kV to 400-480 V. Dry-type technology leads technology adoption in indoor data halls where fire codes prohibit oil-immersed units, while liquid-filled designs occupy edge and research facilities with outdoor pad-mount configurations. Cloud service providers represent the fastest-growing application segment as Microsoft Azure, Amazon Web Services, and Google Cloud expand regional availability zones.
EPA efficiency mandates and EU Ecodesign regulations under the EU Green Deal are tightening loss-factor requirements for distribution transformers installed in new data center builds. IEC 60076 and IEEE C57 standards govern thermal performance and short-circuit withstand, creating compliance barriers for non-certified manufacturers seeking access to North American or European projects. Stakeholders must monitor how NERC reliability standards and emerging grid-interconnection queues reshape procurement timelines for multi-hundred-megawatt campus developments.
Market Dynamics
Hyperscale cloud operators are compressing transformer procurement timelines as AI training clusters demand multi-hundred-megawatt interconnections faster than utility infrastructure can deploy, forcing manufacturers to front-load engineering engagement before site selection finalizes.
Growth Catalysts
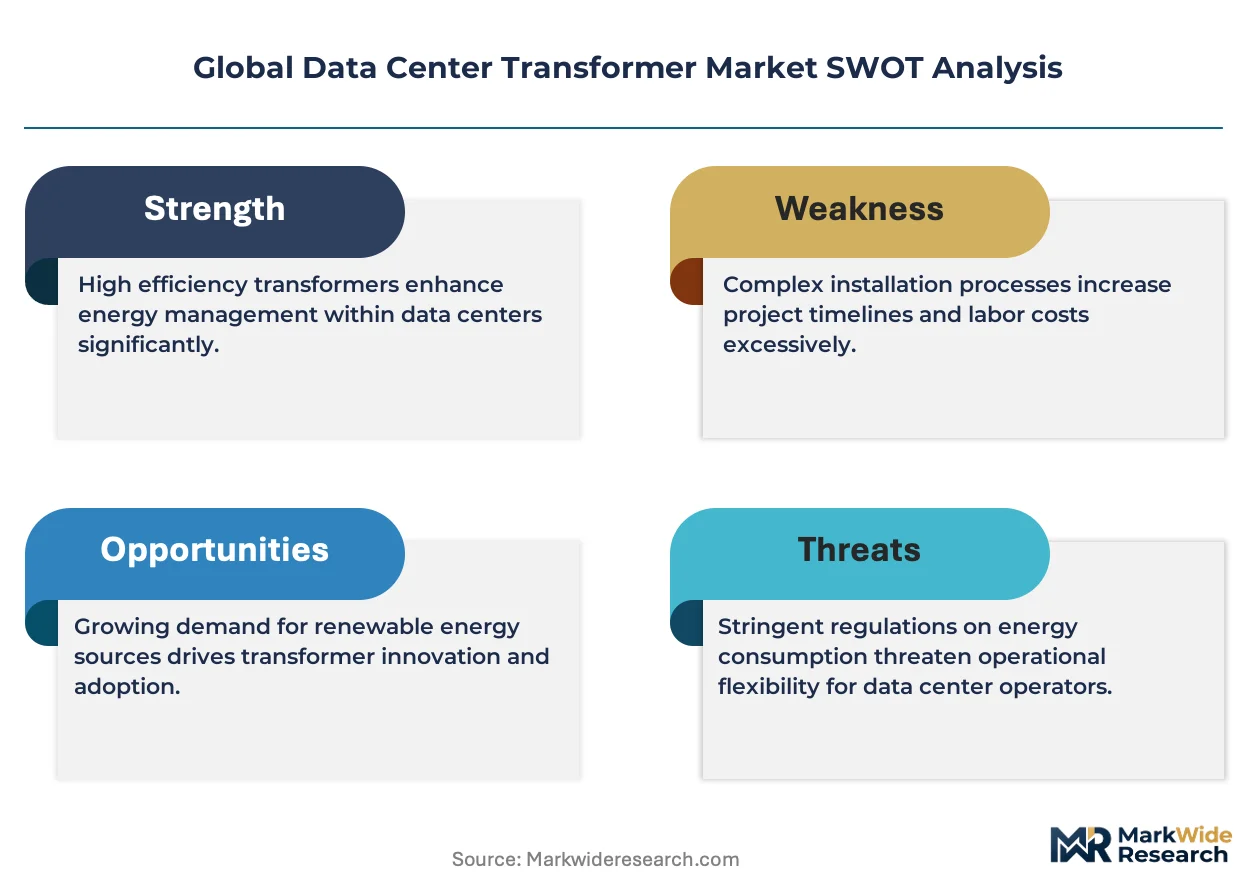
- EU Ecodesign loss-factor mandates:Tighter efficiency requirements under the EU Green Deal are accelerating replacement cycles for legacy oil-immersed units in European data hall builds.
- Dry-type insulation adoption:Indoor hyperscale facilities in fire-code-restricted jurisdictions are specifying cast-resin transformers to eliminate oil containment infrastructure.
- India sovereign cloud expansion:Government-mandated data localization is driving domestic transformer demand for state-approved cloud regions.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of core lamination material concentrates among a limited set of specialty steel producers, exposing lead times to commodity volatility.
- IEC 60076 certification bottlenecks:Third-party testing capacity for thermal performance validation creates queue delays for non-captive manufacturers.
- Utility interconnection timelines:Grid connection queues for 100+ MW campuses extend 24-36 months, misaligning with facility construction schedules.
Strategic Opportunities
- Edge computing micro-grids:Distributed AI inference nodes in secondary German cities require pad-mount liquid-filled units below traditional hyperscale scale thresholds.
- Digital twin integration:Convergence of transformer monitoring systems with building management platforms opens recurring software attach revenue.
- US Inflation Reduction Act domestic content incentives:Tax credits for domestically manufactured electrical equipment are reshaping sourcing strategies for US-based cloud campuses.
Industry Challenges
- Power systems engineering scarcity:Specialized magnetics design talent pools have not expanded with facility build rates, forcing reliance on aging practitioner networks.
- Multi-standard compliance complexity:Simultaneous IEEE C57 and IEC 60076 certification requirements for multinational operators duplicate testing expenditure.
- Legacy oil-immersed retrofit coordination:Brownfield data center electrical upgrades must sequence transformer replacement without disrupting live compute loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Transformer Market |
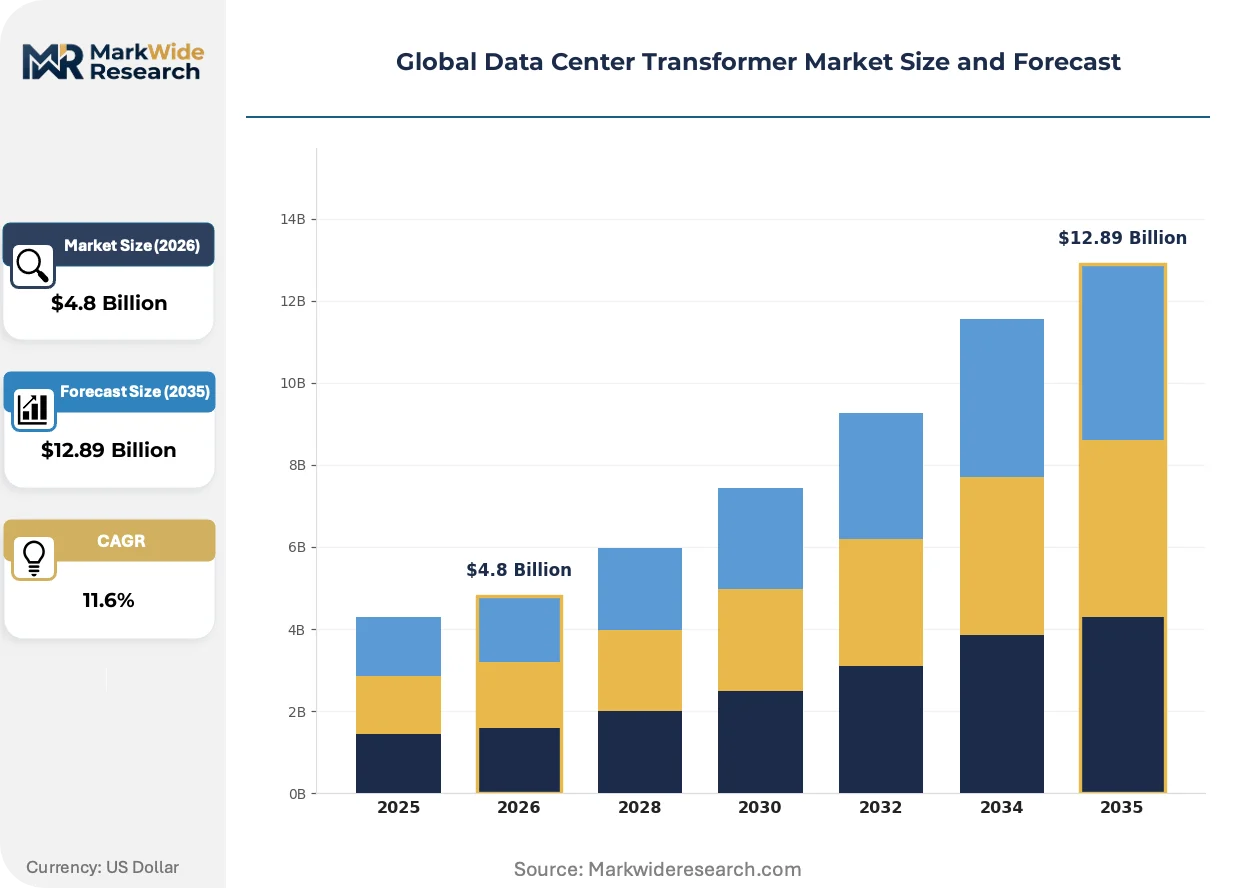
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Down Transformer, Step-Up Transformer, Isolation Transformer, Autotransformer, Instrument Transformer Technology: Dry-Type, Oil-Immersed, Cast Resin, Amorphous Core, Liquid-Filled Application: Hyperscale Data Centers, Edge Data Centers, Colocation Facilities, Cloud Service Providers, Research Facilities End User: IT Infrastructure Providers, Telecom Operators, Financial Institutions, Government Agencies, Educational Institutions |
| Companies Covered | Mitsubishi Electric Corporation, ABB Ltd., Hitachi Energy Ltd., Toshiba Corporation, Eaton Corporation plc, General Electric Company, Siemens Energy AG, Fuji Electric Co. Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Transformer Market Shifts & Advancements
Transformer architecture is compressing physical footprints while integrating intelligence layers, as facility density requirements outpace legacy electromagnetic design conventions.
Cast-resin dry-type technology is miniaturizing core-and-coil assemblies through advanced vacuum-pressure impregnation techniques that reduce insulation clearances without degrading thermal class ratings. Hyperscale operators in Singapore and the Netherlands are specifying these compact units for high-rise urban data halls where floor loading limits restrict traditional transformer mass. The structural consequence is a shift toward manufacturer-integrated skid packages that pre-wire switchgear and cooling, collapsing on-site installation schedules.
EPA efficiency mandates for distribution transformers are tightening no-load loss thresholds for units above 10 MVA, forcing core material upgrades from conventional grain-oriented steel to domain-refined and laser-scribed grades. US-based colocation providers face compliance deadlines that predate typical equipment refresh cycles, accelerating capital deployment. The segment most affected is multi-tenant facilities in Virginia and Texas, where operators are pre-ordering certified units to secure manufacturing slots.
Specification authority is migrating from general contractors to cloud operator engineering teams, who now issue binding technical requirements before site award. Traditional electrical distributors are losing bid participation rights as direct manufacturer relationships capture early-stage design influence. This pattern is most visible in US hyperscale developments, where Amazon Web Services and Microsoft Azure procurement teams issue standardized transformer specifications across multiple simultaneous projects.
Global Data Center Transformer Market Segmentation
Transformer specification varies sharply across facility types, with voltage conversion requirements and fire-safety codes dictating product selection. Procurement patterns diverge between hyperscale operators who standardize globally and edge deployers who prioritize local availability over technical optimization.
Product Type:
Step-down configurations face minimal substitution threat as voltage reduction from medium-voltage utility feeds remains non-negotiable for server rack power supplies, while isolation and instrument variants compete with integrated power electronics in low-voltage distribution zones.
- Step-Down Transformer:Core electromagnetic assemblies reduce incoming 11-33 kV utility distribution to 400-480 V suitable for rack-level power distribution units. Hyperscale campuses in Virginia and Texas specify these units in multi-megawatt blocks to match compressed construction timelines.
- Isolation Transformer:Galvanic separation layers protect sensitive compute loads from ground reference disturbances and harmonic propagation. Research facilities in Germany and the Netherlands deploy these for precision workloads where power quality directly affects experimental outcomes.
- Step-Up Transformer:Deployed in on-site generation integration scenarios where low-voltage renewable sources require elevation to match distribution bus voltages.
- Autotransformer:Compact variable-ratio designs serve voltage-matching applications where isolation is not required, common in retrofit expansions with limited floor loading capacity.
- Instrument Transformer:Current and potential sensing elements feed protection relays and metering systems, increasingly integrated into digital substation architectures.
Step-down transformers anchor the volume base while isolation transformers gain share at the steepest rate as power quality sensitivity climbs in AI training clusters.
Technology:
Cost tiers separate legacy oil-immersed designs facing replacement pressure from premium dry-type and cast-resin alternatives that eliminate fire-suppression infrastructure.
- Dry-Type:Air-cooled core-and-coil assemblies with cast-resin or vacuum-pressure impregnated insulation suit indoor data halls where fire codes prohibit liquid dielectrics. Singapore and Netherlands operators specify these for high-rise urban facilities with strict containment requirements.
- Liquid-Filled:Mineral oil or synthetic ester dielectrics provide superior thermal conductivity for high-density outdoor pad-mount installations. Edge computing nodes in secondary German cities favor these units for distributed AI inference below hyperscale scale thresholds.
- Oil-Immersed:Traditional tank-and-radiator designs face accelerated replacement cycles under EPA efficiency mandates and EU Ecodesign loss-factor regulations.
- Cast Resin:Epoxy-encapsulated windings offer moisture resistance and reduced fire risk for coastal and subterranean deployments.
- Amorphous Core:Non-crystalline metal laminations cut no-load losses by 60-70 percent versus conventional grain-oriented steel, specified where 24/7 operation justifies material premium.
Dry-type technology commands the premium tier while liquid-filled designs retain cost-sensitive edge applications.
Application:
Volume concentration tracks facility scale, with hyperscale and cloud deployments driving procurement standardization while smaller segments fragment across regional specifications.
- Hyperscale Data Centers:Single-tenant campuses exceeding 50 MW demand transformer banks in synchronized blocks with unified protection schemes. Microsoft Azure and Amazon Web Services issue binding technical specifications before site award, collapsing distributor participation.
- Cloud Service Providers:Multi-tenant infrastructure operators require flexible capacity scaling with standardized electrical interfaces across regional availability zones.
- Edge Data Centers:Distributed 1-10 MW facilities in secondary cities prioritize rapid deployment over thermal optimization, accepting liquid-filled pad-mount units.
- Colocation Facilities:Multi-tenant providers in Virginia and Texas face EPA compliance deadlines that accelerate capital deployment ahead of typical refresh cycles.
- Research Facilities:National laboratories and university compute centers specify precision-grade units with extended thermal monitoring for experimental reproducibility.
Hyperscale data centers dominate absolute volume while cloud service providers expand most quickly as regional availability zones multiply.
End User:
Customer type determines specification authority, with IT infrastructure providers and telecom operators driving standardization while institutional buyers prioritize compliance documentation.
- IT Infrastructure Providers:Specialized data center developers consolidate electrical specifications across multiple simultaneous projects, capturing volume pricing and accelerating delivery.
- Telecom Operators:5G core network densification drives transformer demand for edge compute co-location at cellular baseband aggregation points.
- Financial Institutions:Trading floor and risk analytics facilities mandate dual-source transformer configurations with automatic transfer schemes.
- Government Agencies:Sovereign cloud mandates in India require domestic manufacturing certification and local content verification.
- Educational Institutions:University research computing centers balance capital constraints against power quality requirements for simulation workloads.
IT infrastructure providers set the procurement template while government agencies reshape fastest as data localization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA efficiency mandates and IRA domestic content incentives are reshaping procurement patterns across the United States, while EU Ecodesign regulations and India's sovereign cloud mandates create parallel compliance architectures in their respective markets.
United States
Virginia and Texas hyperscale clusters are compressing transformer delivery timelines as Microsoft Azure and Amazon Web Services front-load specifications before site selection finalizes. EPA loss-factor mandates for units above 10 MVA are accelerating capital deployment ahead of typical refresh cycles. Northern Virginia's Loudoun County maintains the densest concentration of multi-hundred-megawatt campuses under active construction.
Germany
Edge computing nodes in secondary cities like Leipzig and Nuremberg are driving demand for pad-mount liquid-filled units below traditional hyperscale scale thresholds. EU Ecodesign regulations under the EU Green Deal are tightening efficiency requirements and accelerating replacement cycles for legacy oil-immersed designs. Frankfurt's Rhine-Main region anchors continental cloud infrastructure expansion with strict fire-code enforcement favoring dry-type alternatives.
India
Government-mandated data localization is propelling domestic transformer demand for state-approved cloud regions operated by global and local providers. CEA certification requirements and PLI scheme incentives are reshaping sourcing strategies toward domestically manufactured equipment. Mumbai and Bengaluru clusters are absorbing the majority of sovereign cloud capacity deployment.
Singapore
High-rise urban data halls with strict floor loading limits are specifying compact cast-resin dry-type units with advanced vacuum-pressure impregnation. Local building authorities enforce fire-safety codes that prohibit liquid dielectrics in enclosed environments. The Jurong Lake District and Changi North are concentrating next-generation facility development.
Netherlands
Research facilities and precision computing centers in Eindhoven and Amsterdam are specifying isolation transformers for experimental workloads where power quality affects reproducibility. REACH compliance and national building codes are eliminating oil-immersed options from new indoor builds. The Amsterdam Metropolitan Area remains the primary hub for European cloud availability zone expansion.
Global Data Center Transformer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure where design depth commands premium positioning and manufacturing scale captures volume segments. The vendor base spans integrated electrical conglomerates, specialized magnetics manufacturers, and regional fabrication specialists serving localized compliance requirements. Two strategic archetypes dominate: firms with captive power systems engineering talent securing early-stage hyperscale engagement, and manufacturers leveraging regional certification pre-approval to compress delivery timelines. Competitive moves center on direct procurement relationships with cloud operator engineering teams and manufacturer-integrated skid packages that collapse on-site installation schedules.
Among diversified industrial conglomerates, ABB Ltd. and Siemens Energy AG exemplify archetypes combining transformer manufacturing with grid automation integration, while Hitachi Energy Ltd. occupies a position bridging liquid-filled and dry-type platform specialization. These three entities represent distinct geographic anchoring strategies—Swiss-Swedish, German, and Japanese respectively—reflecting how regional manufacturing presence and standards pre-certification shape competitive access to multi-jurisdictional hyperscale developments.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Hitachi Energy Ltd. |
| Toshiba Corporation |
| Eaton Corporation plc |
| General Electric Company |
| Siemens Energy AG |
| Fuji Electric Co. Ltd. |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Domain-refined grain-oriented electrical steel displacing conventional core lamination grades is redrawing procurement geography toward Japan and South Korea while compressing margin structures for mid-tier transformer assemblers dependent on spot-market steel purchases.
Pricing Analysis
Price spreads between European and Asian supply origins exceed transport cost differentials, reflecting IEC 60076 pre-certification premiums that German and Swiss manufacturers command from hyperscale operators. Three-tier pricing structure across amorphous-core premium, laser-scribed standard, and conventional-grain-economy levels tracks core material technology tiers. Cost compression in the economy tier is intensifying because Indian and Southeast Asian fabricators are absorbing steel price volatility to capture volume share. Cloud service providers exhibit lowest price sensitivity, prioritizing delivery certainty over unit cost, while regional colocation operators in secondary US markets remain most cost-constrained.
Supply Chain Analysis
Inventory buffers for grain-oriented electrical steel have compressed to twelve-week coverage versus historical eighteen-week norms, exposing transformer lead times to specialty steel mill scheduling. Manufacturing concentrates in Germany, Japan, and India, with each hub serving distinct regulatory certification clusters. Core lamination draws from Nippon Steel, Posco, and ThyssenKrupp facilities, while copper winding supply rests on Chilean and Zambian cathode flows. Single-source vulnerability concentrates in high-permeability steel grades required for EPA-compliant efficiency thresholds. Distribution runs through direct manufacturer relationships with cloud operator engineering teams, bypassing traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the transformer supply base as hyperscale procurement centralization creates tier-two demand pockets that regional specialists can capture without competing on global scale.
For Market Incumbents: Secure captive magnetics engineering talent pools through acquisition of specialized design consultancies in Germany and the United States, insulating against power systems practitioner scarcity. Deepen backward integration into domain-refined steel sourcing through long-term offtake agreements with Japanese mills, defending margin position against commodity volatility. Pre-position IEC 60076 and IEEE C57 dual-certification capabilities to capture multinational hyperscale specifications that duplicate testing requirements currently fragmenting competitor access. For New Entrants and Emerging Players: Anchor in India's sovereign cloud buildout where CEA certification requirements and PLI scheme incentives create protected demand arcs for domestically manufactured equipment. Target edge computing micro-grid deployments in secondary German cities, where sub-10 MW scale thresholds fall below incumbent priority focus. Pursue skid-package integration partnerships with European switchgear specialists to collapse on-site installation schedules without carrying full manufacturing overhead. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive certification capabilities and regional manufacturing footprints. Long-term viability centers on transformer-as-a-service revenue models where digital twin integration generates recurring software attach. Target acquisition archetype: mid-cap European manufacturers with IEC pre-certification and unexploited capacity in Poland or Romania. Signal to watch: utility interconnection queue relief measures that would decompress hyperscale procurement timelines and shift buyer power toward manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Simultaneous IEEE C57 and IEC 60076 pre-approval unlocks multinational hyperscale procurement pools. |
| Steel Supply Agreement | Long-term domain-refined grain-oriented steel offtake secures core material access against commodity volatility. |
| Digital Twin Integration | Transformer monitoring convergence with building management platforms opens recurring software revenue streams. |
| Regional Manufacturing Footprint | Domestic production presence in India satisfies CEA certification and PLI scheme localization requirements. |
| Skid-Package Pre-Integration | Manufacturer-integrated switchgear and cooling assemblies collapse hyperscale site installation schedules. |
Research Methodology
A standing panel of hyperscale facility engineering directors, utility interconnection planners, transformer manufacturing operations heads, and power systems design consultants provided ongoing calibration against market developments across the analysis window. Primary fieldwork combined structured interviews with secondary validation against EPA efficiency mandate filings, EU Ecodesign regulatory updates, CEA certification databases, and hyperscaler capital expenditure disclosures. Bottom-up unit economics triangulated against top-down utility interconnection queue data and regional construction permit flows.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled transformer demand by product type, insulation technology, facility scale tier, and regional regulatory cluster. CAGRs derived from segment-level build-up analysis incorporating utility interconnection timelines, sovereign cloud mandate implementation schedules, and efficiency regulation compliance deadlines. Industry-specific inputs included grain-oriented steel price indices, IEC certification queue lengths, and hyperscale procurement standardization patterns.
Material uncertainties — utility interconnection queue reform, specialty steel trade policy shifts, and sovereign cloud mandate scope revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and hyperscale facility buildout continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Battery Voltage Supervisor Market
Power Systems
South America Battery Management System Market
Power Systems
Global Excitation Systems Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
HVDC Converters Market
Power Systems
Space DC-DC Converters Market