
 Global Fault Current Limiter Market | 2026-2036
Global Fault Current Limiter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fault Current Limiter Market Foresight
Multi-sourcing of superconducting tape and cryogenic cooling subsystems is broadening as OEMs reduce dependency on single Japanese suppliers. ABB Ltd. leverages its integrated power-grid portfolio to bundle fault current limiters with digital substation packages. Siemens AG anchors European utility tenders through its superconducting device joint ventures. Nexans competes on specialized cryogenic cable expertise that supports hybrid limiter architectures.
A fault current limiter is a power-system protection device that restricts prospective short-circuit current to safe levels within milliseconds, typically employing superconducting elements that quench from near-zero resistance to high resistance above critical current thresholds. Its primary purpose is to prevent thermal and mechanical damage to transformers, busbars, and switchgear while avoiding service interruption. Superconducting technology leads installed value due to its near-instantaneous response, though solid-state variants are gaining traction in data center applications where footprint constraints dominate. Power grid protection remains the mature revenue pool, while renewable integration represents the fastest structural expansion as distributed solar and offshore wind strain conventional protection coordination.
FERC reliability standards in the United States, EU F-Gas Regulation affecting cryogenic cooling agents, and Japan's METI grid resilience directives collectively elevate product certification requirements and shorten replacement cycles. These frameworks force manufacturers to validate limiter performance across wider temperature bands and fault-current ranges. Stakeholders must monitor superconductor material cost curves and cooling system efficiency gains as the primary variables determining whether hybrid architectures displace fully superconducting designs at scale.
Market Dynamics
Superconducting tape supply concentration in Japan is forcing OEMs to reconfigure procurement networks while FERC reliability mandates accelerate replacement cycles for conventional protection equipment across North American utilities.
Growth Catalysts
- FERC reliability standards:US utility operators face mandatory grid hardening timelines that compress fault current limiter procurement decisions from multi-year planning cycles to 18-month execution windows.
- Urban substation densification:East Asian megacities including Tokyo, Shanghai, and Seoul require compact protection solutions where superconducting limiters replace bulky air-core reactors.
- EU Green Deal electrification:Renewable integration mandates across Germany, France, and Italy strain conventional circuit breaker coordination, creating immediate demand for faster-acting limiter architectures.
Market Restraints
- Helium supply volatility:Cryogenic cooling system costs fluctuate with Qatar and Algeria LNG-helium extraction rates, compressing margin predictability for resistive limiter manufacturers.
- Japanese tape dominance:Over 70% of high-temperature superconducting tape originates from three Japanese suppliers, creating single-source vulnerability for European and North American OEMs.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases complicate cooling agent selection for hybrid limiter designs, extending product validation timelines.
Strategic Opportunities
- India grid modernization:CEA-mandated urban distribution upgrades in Mumbai, Delhi, and Bangalore create first-mover positioning for resistive limiter suppliers before domestic manufacturing scales.
- Offshore wind protection:North Sea and Baltic Sea converter platforms require compact fault current management where superconducting limiters displace conventional switchgear arrays.
- Data center microgrids:Hyperscale facilities in Northern Virginia and Frankfurt seek solid-state limiter variants that eliminate cryogenic infrastructure while meeting footprint constraints.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in superconducting system thermal management concentrates in Japanese and German research institutions, constraining OEM hiring pipelines.
- Legacy protection coordination:Utilities in the US Midwest and German industrial zones struggle to integrate limiter response curves with electromechanical relay hierarchies installed decades prior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fault Current Limiter Market |
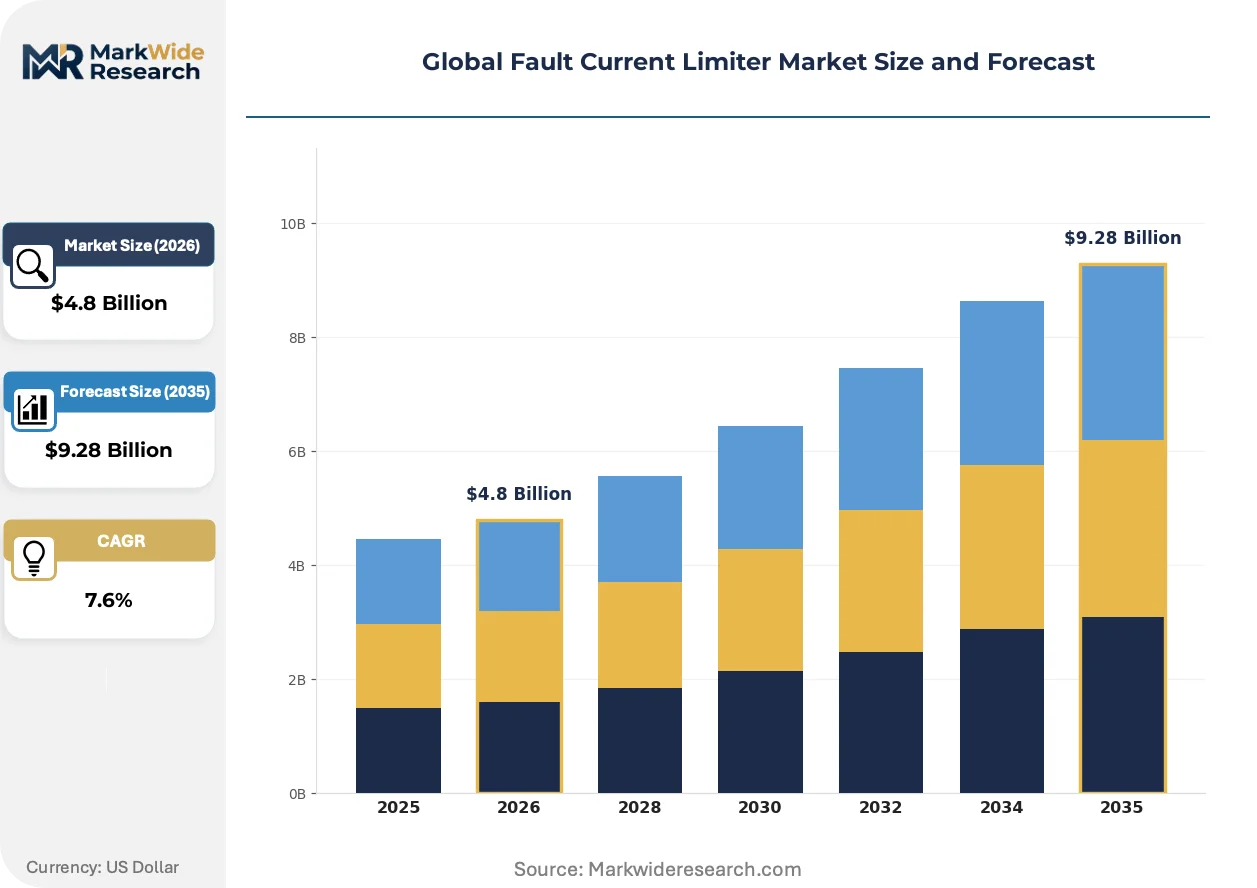
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
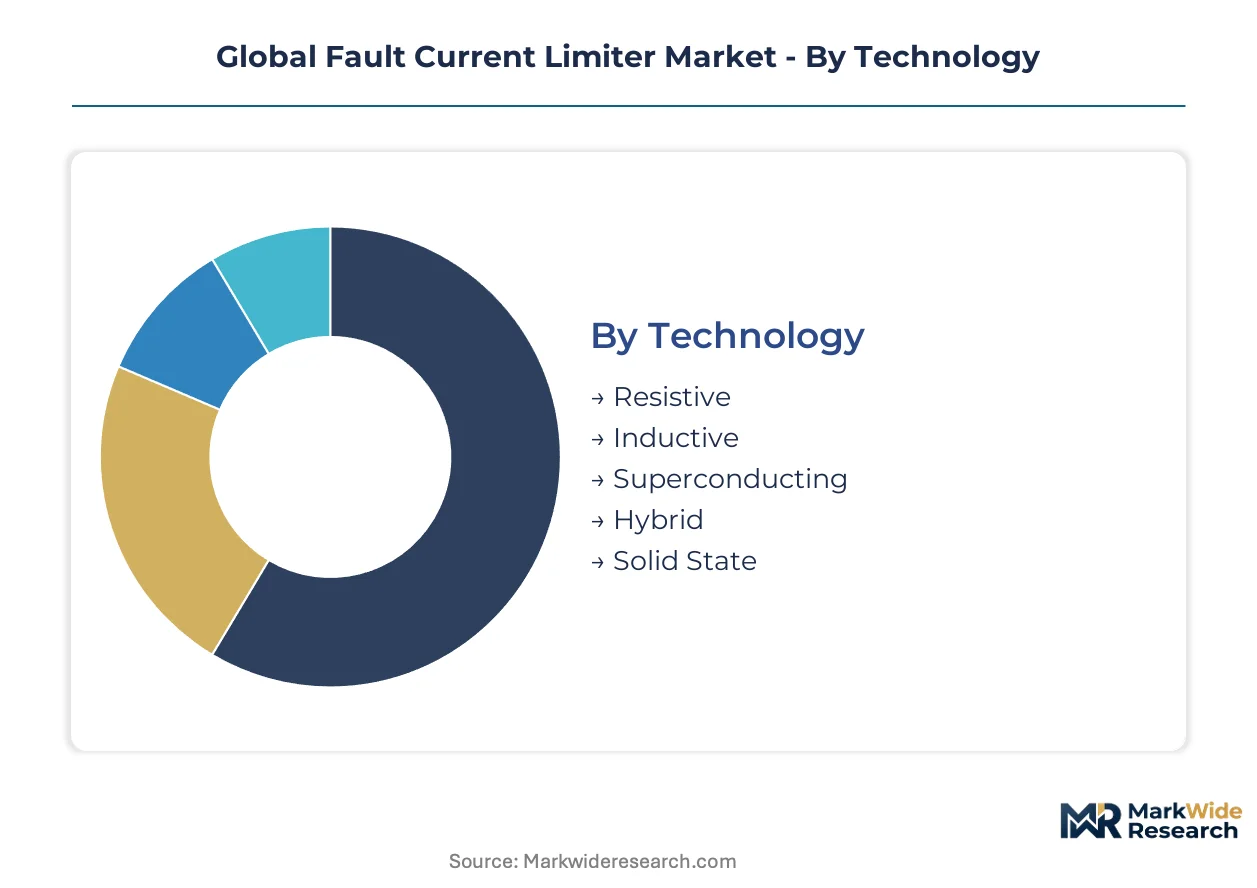
| Segmentation | Technology: Resistive, Inductive, Superconducting, Hybrid, Solid State Application: Power Grid Protection, Renewable Integration, Industrial Power Systems, Data Centers, Railways Installation Type: Indoor, Outdoor, Substation, Satellite Substation, Mobile Units End User: Utility Operators, Manufacturing Plants, Commercial Complexes, Transportation Networks, Data Facilities |
| Companies Covered | ABB Ltd., Siemens AG, American Superconductor Corporation, Rongxin Power Electronic Co. Ltd., Schneider Electric, Nexans, Alstom, Applied Materials, Superconductor Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fault Current Limiter Market Shifts & Advancements
Hybrid architectures combining superconducting elements with solid-state switches are compressing the traditional trade-off between response speed and operational simplicity that has structured this market for two decades.
Resistive-superconducting hybrid limiters are unifying the instantaneous quench response of YBCO tape with the maintenance accessibility of conventional switchgear. Data center operators in Northern Virginia and Singapore are piloting these configurations to eliminate cryogenic infrastructure while retaining sub-millisecond fault isolation. The technology is unifying previously separate procurement categories—superconducting devices and solid-state breakers—into single-vendor service contracts.
EU F-Gas Regulation amendments are compelling cooling system redesigns across German and French utility fleets. Manufacturers must validate alternative cryogenic fluids or closed-loop helium recovery systems before 2027 compliance deadlines. Offshore wind converter platforms in the North Sea face the steepest requalification burden due to salt-air corrosion testing requirements for modified cooling circuits.
Utility procurement committees now require lifecycle cost guarantees extending 25 years, displacing capital-expedient bidding practices that dominated prior tender cycles. European transmission operators including TenneT and RTE embed performance-based maintenance clauses that transfer operational risk to OEMs. This restructuring concentrates contract awards with vendors possessing captive service networks across Germany, France, and Benelux regions.
Global Fault Current Limiter Market Segmentation
Fault current limiter procurement decisions hinge on response speed requirements, cooling infrastructure availability, and legacy grid compatibility. Technology selection determines whether utilities deploy cryogenic systems or solid-state alternatives, while application context shapes voltage ratings and coordination protocols.
Technology:
Buyer decisions center on balancing instantaneous response against operational complexity and total cost of ownership across the installation lifecycle.
- Superconducting:YBCO tape elements quench from near-zero to high resistance within milliseconds, delivering unmatched fault suppression speed. Demand clusters in Japanese urban substations and German offshore wind converter platforms where space constraints eliminate conventional reactor alternatives.
- Resistive:Metallic or composite resistors provide predictable current limitation without cryogenic infrastructure, simplifying maintenance protocols. Chinese State Grid pilots and Indian CEA-mandated urban upgrades drive procurement volumes where helium supply volatility discourages superconducting architectures.
- Hybrid:Combines superconducting quench response with solid-state switch durability for intermediate applications.
- Inductive:Air-core or iron-core reactors offer mature protection coordination with existing relay systems.
- Solid State:Power electronic switches eliminate moving parts and cryogenic requirements entirely, suiting data center microgrids in Northern Virginia and Singapore where footprint constraints dominate.
Volume sits with resistive limiters; growth tilts toward hybrid architectures bridging performance and operational simplicity.
Application:
End-use environments dictate fault current magnitude, coordination speed requirements, and environmental exposure ratings that shape equipment specifications.
- Power Grid Protection:Transmission and distribution substations deploy high-voltage limiters to prevent transformer thermal damage during busbar faults. US utilities under FERC reliability mandates and EU transmission operators including TenneT accelerate replacement of aging circuit breaker arrays.
- Renewable Integration:Distributed solar inverters and offshore wind converter stations strain conventional protection coordination with bidirectional fault currents. German North Sea platforms and Chinese coastal wind clusters represent concentrated demand for compact limiter solutions.
- Industrial Power Systems:Steel mills and chemical plants require limiters capable of withstanding frequent switching operations and harsh environments.
- Data Centers:Hyperscale facilities prioritize solid-state variants eliminating cryogenic infrastructure while meeting sub-millisecond isolation requirements.
- Railways:Traction power networks utilize limiters protecting rectifier substations against catenary short circuits.
Revenue concentrates in power grid protection; renewable integration climbs the fastest as electrification targets strain legacy protection architectures.
Installation Type:
Physical deployment context determines enclosure ratings, thermal management design, and accessibility for maintenance interventions.
- Substation:Permanent installations in transmission yards house the highest voltage ratings and largest current capacities. German industrial zones and US Midwest utilities favor these configurations for centralized protection of multiple feeder lines.
- Indoor:Climate-controlled environments accommodate sensitive superconducting systems requiring stable cryogenic operating temperatures. Japanese urban substations in Tokyo and Osaka deploy these variants to maximize equipment lifespan in dense metropolitan settings.
- Outdoor:Weather-hardened enclosures serve remote renewable generation sites and rural distribution networks.
- Satellite Substation:Compact secondary substations in urban distribution networks prioritize space-efficient limiter designs.
- Mobile Units:Trailer-mounted systems provide temporary protection during grid maintenance or emergency restoration.
Deployment volume favors substation installations; satellite substation configurations gain share fastest with urban densification trends.
End User:
Procurement authority and technical sophistication vary sharply across customer categories, influencing sales cycle length and service contract structures.
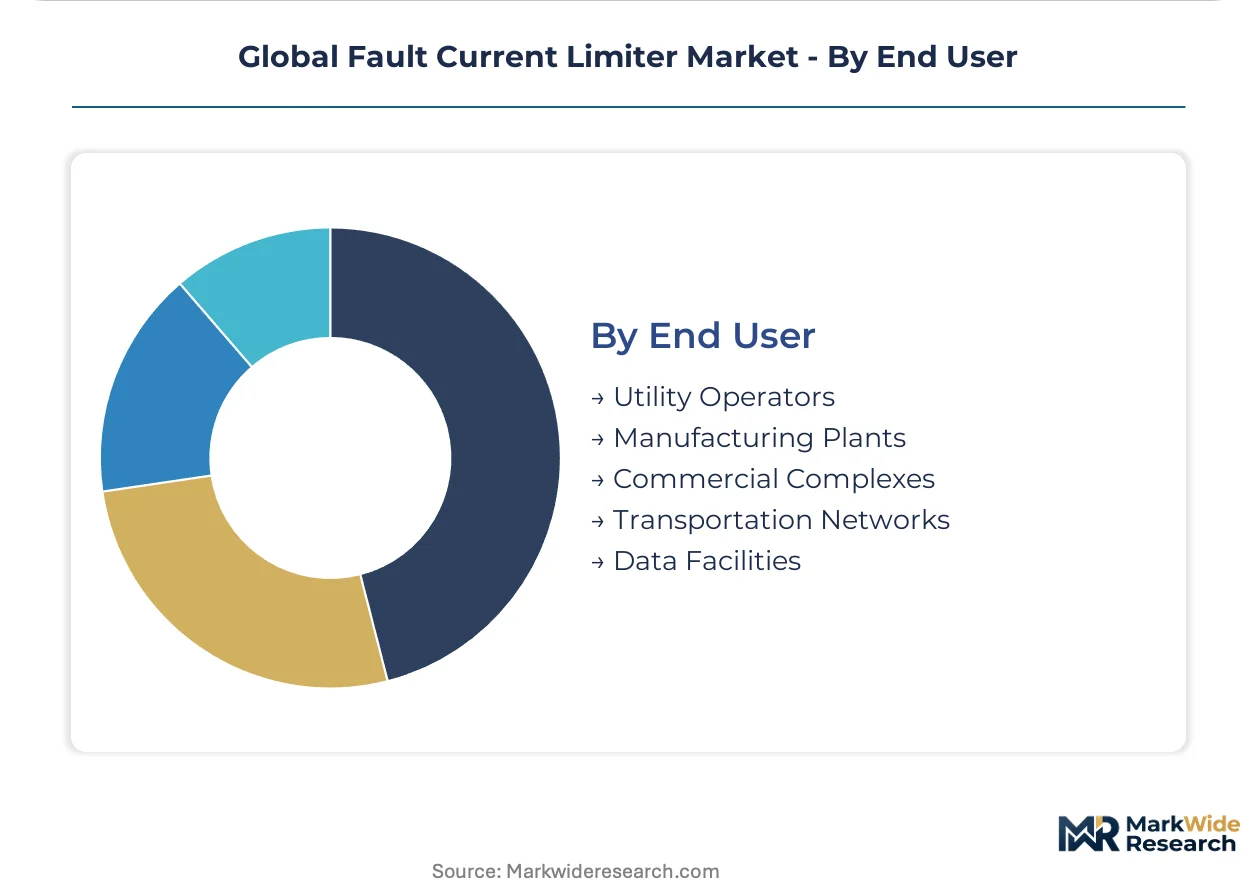
- Utility Operators:Transmission and distribution companies command the largest procurement volumes with multi-year tender cycles and lifecycle cost evaluation frameworks. European operators including RTE and TenneT embed 25-year performance guarantees and risk-transfer maintenance clauses.
- Data Facilities:Hyperscale operators in Northern Virginia and Frankfurt prioritize solid-state limiters with minimal footprint and eliminated cryogenic infrastructure, compressing procurement decisions to 6-12 month cycles.
- Manufacturing Plants:Industrial facilities seek limiters compatible with existing protection relay hierarchies and minimal operational disruption.
- Commercial Complexes:Large-scale real estate developments require limiters protecting on-site substations serving mixed-use loads.
- Transportation Networks:Railway operators and airport authorities deploy specialized limiters for traction power and critical facility protection.
Contract value concentrates with utility operators; data facilities expand most quickly with hyperscale construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese superconducting tape production anchors the upstream supply base for fault current limiter manufacturing, with fabrication clusters in Osaka and Tokyo feeding OEM assembly lines across Germany, the United States, and China.
United States
Utility operators under FERC reliability mandates compress procurement cycles from multi-year planning to 18-month execution windows. The Federal Energy Regulatory Commission enforces mandatory grid hardening timelines that accelerate replacement of aging circuit breaker arrays. Northern Virginia data center clusters pilot solid-state limiter variants that eliminate cryogenic infrastructure while meeting sub-millisecond isolation requirements.
Germany
TenneT and RTE embed 25-year performance guarantees and risk-transfer maintenance clauses in transmission tenders. The EU F-Gas Regulation compels cooling system redesigns with 2027 compliance deadlines for alternative cryogenic fluids. North Sea offshore wind converter platforms face steep requalification burdens due to salt-air corrosion testing requirements for modified cooling circuits.
Japan
METI grid resilience directives elevate product certification requirements across wider temperature bands and fault-current ranges. Urban substations in Tokyo and Osaka deploy indoor climate-controlled superconducting systems to maximize equipment lifespan in dense metropolitan settings. Over 70% of high-temperature superconducting tape originates from three domestic suppliers, creating concentrated upstream supply control.
China
State Grid pilots next-generation resistive limiters for urban substation upgrades in Shanghai and Beijing. The country's dual carbon goals strain conventional protection coordination with bidirectional fault currents from distributed solar and offshore wind integration. Coastal wind clusters in Jiangsu and Guangdong represent concentrated demand for compact limiter solutions.
India
CEA-mandated urban distribution upgrades in Mumbai, Delhi, and Bangalore create first-mover positioning for resistive limiter suppliers. The Central Electricity Authority mandates infrastructure modernization timelines that compress vendor qualification periods. Domestic manufacturing scale-up remains nascent, favoring early entrants with established service networks.
Global Fault Current Limiter Market Competitive Landscape
Global majors compete with regional champions across integrated power-grid portfolios versus specialized cryogenic cable expertise. The vendor base stratifies between full-system integrators bundling limiters with digital substation packages, superconducting device joint ventures anchoring European utility tenders, and component specialists supplying tape or cooling subsystems. Strategic moves concentrate on multi-sourcing agreements to reduce Japanese tape dependency and lifecycle cost guarantee structures transferring operational risk to OEMs.
Among European-headquartered conglomerates, ABB Ltd. and Siemens AG occupy positions as integrated power-grid portfolio providers, while Nexans sits within the specialized cryogenic cable tier. ABB Ltd. represents the full-system bundling archetype, Siemens AG exemplifies superconducting device joint venture structures, and Nexans anchors the hybrid limiter architecture specialization vector.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| American Superconductor Corporation |
| Rongxin Power Electronic Co. Ltd. |
| Schneider Electric |
| Nexans |
| Alstom |
| Applied Materials |
| Superconductor Technologies Inc. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation amendments gate qualified supply for alternative cryogenic cooling systems and reserve premium-tier pricing access to OEMs with validated closed-loop helium recovery architectures. Buyers in Germany and France face compressed vendor pools as compliance deadlines eliminate uncertified competitors from transmission tender shortlists.
Pricing Analysis
Warranty bundling now separates full-lifecycle maintenance contracts from capital-equipment-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against IEC 62271 standards and geographic service network density. Cost compression in economy-tier resistive limiters is intensifying because Chinese State Grid volume procurement exerts leverage over metallic resistor suppliers. Data facility buyers in Northern Virginia exhibit lowest price sensitivity due to footprint-constrained application requirements, while Indian CEA-mandated urban upgrades drive highest sensitivity among utility operators.
Supply Chain Analysis
Cryogenic engineering talent scarcity in Japanese and German research institutions constrains OEM hiring pipelines and limits assembly capacity expansion. Manufacturing concentrates in Japan, Germany, and China, with YBCO tape production anchored in Osaka and Tokyo, system integration clustered in Munich and Berlin, and resistive component fabrication scaling in Shanghai. Raw material dependencies center on rare-earth barium copper oxide substrates, high-purity helium reserves, and specialized cryogenic steel alloys. Single-source vulnerability from Japanese tape suppliers exceeding 70% market share creates structural risk for European and North American OEMs. Distribution runs through direct utility tender channels and EPC contractor specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese superconducting tape production capacity acts as the binding constraint propping pricing power for qualified OEMs and compressing margin available to second-tier suppliers.
For Market Incumbents: Lock in multi-sourcing agreements with emerging Korean and Chinese tape suppliers to reduce dependency on Japanese single-source exposure. Secure captive cryogenic engineering talent through German and Japanese university partnerships before competitor hiring intensifies. Vertical integration into closed-loop helium recovery system production defends margin position against Qatar and Algeria supply volatility. For New Entrants and Emerging Players: Capture first-mover positioning in Indian CEA-mandated urban distribution upgrades before domestic manufacturing scales and incumbent service networks mature. Target solid-state limiter variants for data center microgrids in Northern Virginia and Singapore where footprint constraints eliminate incumbent cryogenic advantages. Pursue OEM partnership routes rather than direct utility tender competition to bypass 25-year performance guarantee barriers. For Investors and Strategic Acquirers: METI grid resilience directive amendments accelerating Japanese certification requirements is the leading indicator that regulatory complexity will consolidate vendor tiers and elevate acquisition premiums for qualified assets. Five-to-ten-year viability favors superconducting device specialists with captive tape supply agreements over pure-play resistive manufacturers facing commodity margin compression. Watch for FERC reliability standard enforcement intensity as the signal determining North American replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sourcing Agreement | Diversifies YBCO tape supply beyond Japanese suppliers for European OEMs. |
| Cryogenic Engineering Partnership | Secures specialized thermal management talent from German research institutions. |
| Closed-Loop Helium Recovery | Validates EU F-Gas Regulation compliance for French and German utility tenders. |
| Solid-State Product Line Extension | Addresses data center microgrid demand in Northern Virginia without cryogenic infrastructure. |
| Lifecycle Service Contract | Transfers operational risk to OEMs per TenneT and RTE procurement frameworks. |
Research Methodology
SEC filings from ABB Ltd. and Siemens AG, FERC reliability standard documentation, and EU F-Gas Regulation amendment records formed the secondary backbone for market sizing validation. Primary interviews with utility planning officers at TenneT and RTE, grid operators at State Grid and Tokyo Electric, and EPC contractors specializing in offshore wind converter platforms provided demand-side calibration. Cryogenic system engineers and superconducting tape procurement leads at OEMs supplied upstream cost structure intelligence. Bottom-up unit economics triangulated against top-down transmission infrastructure investment forecasts.
Historical deployment trendlines across superconducting, resistive, hybrid, and solid-state technology categories established baseline penetration rates over the projection horizon. Segmentation modeling incorporated technology type, application environment, installation configuration, and end-user procurement authority. CAGRs derived from regression analysis against grid reliability mandate enforcement intensity and renewable integration targets. Forecast inputs included helium price volatility indices and superconducting tape production capacity announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Japanese tape supply expansion, EU F-Gas Regulation enforcement consistency, and FERC reliability standard penalty structures. Forecasts reflect documented assumptions regarding mandate timelines and technology cost curves. Material deviation in METI directive acceleration or Qatar helium export policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Central Battery Systems Market
Power Systems
Laptop Battery Market
Power Systems
Automotive Inverters Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Battery Racks Market
Power Systems
DC Power Supplies Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Power Amplifier Modules Market
Power Systems
AC Voltage Transducer Market
Power Systems
DC-DC Converter Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Three Phase Micro Inverters Market