
 Shotcrete Accelerators Market | 2026-2036
Shotcrete Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Shotcrete Accelerators Market Analysis
Alkali-free accelerator specifications is collapsing the gap between commodity-grade and performance-grade product tiers across European and Asian project portfolios. Sika AG leverages its integrated admixture technology platform to sustain specification leadership in wet-mix tunneling applications. Normet Oy anchors its competitive position through deep specialization in mining-grade rapid-setting formulations for deep-shaft operations. BASF SE competes on manufacturing scale and REACH-compliant chemistry portfolios across Alpine infrastructure corridors.
Shotcrete accelerators are chemical admixtures—typically based on aluminum sulfate, alkali silicates, or amorphous aluminum hydroxide—dosed at 3-8% by cement weight to reduce final set time below five minutes in sprayed concrete applications. Their primary industrial purpose is enabling immediate load-bearing capacity in underground excavations where water ingress and ground instability threaten structural integrity. Chemical accelerators dominate current volume flows in mature European tunnel markets where specification standards are most demanding. Synthetic accelerator formulations represent the fastest-expanding margin pool as mining operators seek reduced rebound rates and lower alkali content for worker safety compliance. Wet mix technology commands premium positioning in hydropower and transit tunnel segments where pumpability and controlled accelerator dispersion determine application success.
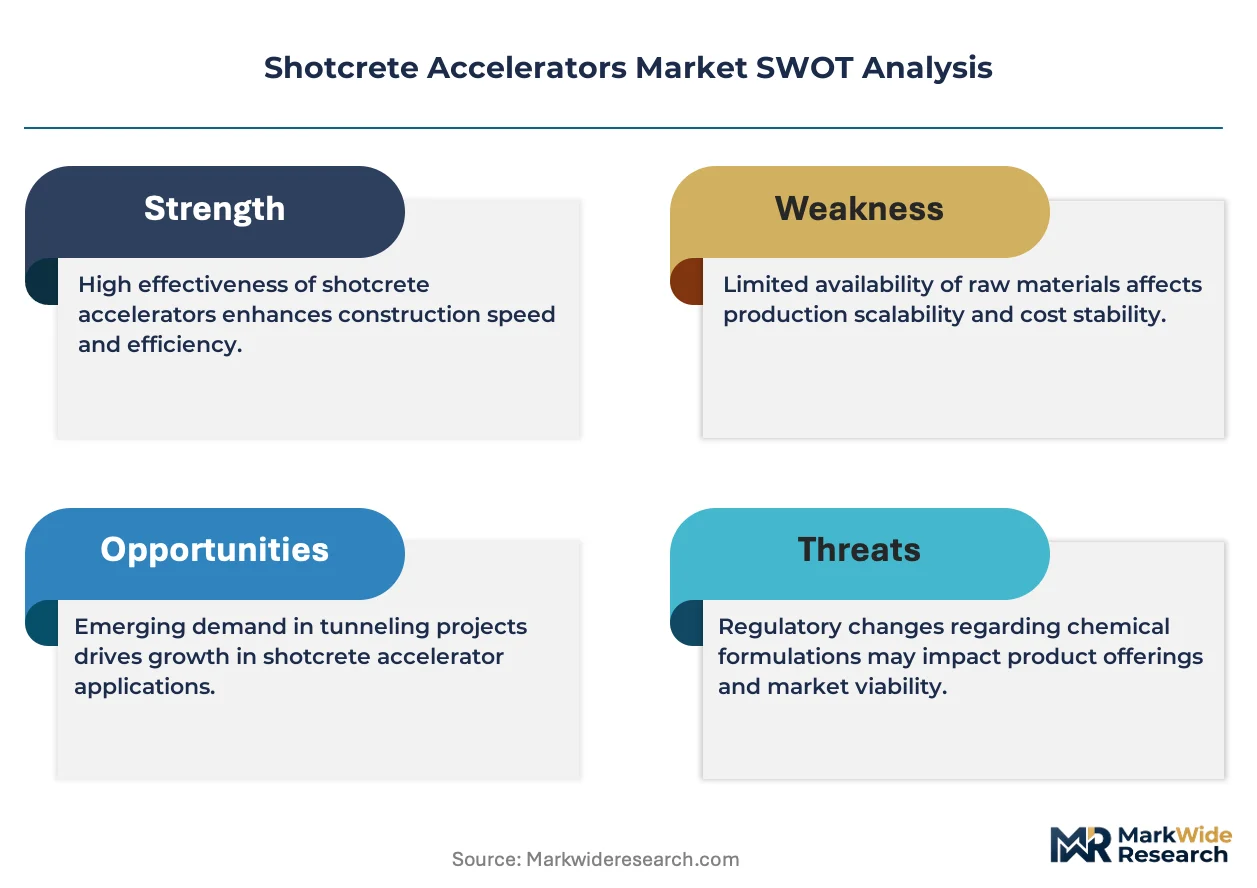
REACH registration requirements and ECHA substance evaluation protocols constrain permissible active ingredients in European accelerator formulations, directly elevating R&D costs for reformulation cycles. The EPA's National Emission Standards for Hazardous Air Pollutants and OSHA silica exposure limits shape product design and jobsite application protocols in United States underground construction. China's GB standards for tunnel engineering materials and MEE environmental compliance certifications govern import qualification and domestic production licensing. Stakeholders must monitor divergence between European chemical hazard classifications and emerging economy performance standards when configuring regional product portfolios and manufacturing footprints.
Market Dynamics
Alkali-free formulation chemistry is compressing the historical premium-commodity price spread across tunneling and mining specifications, forcing incumbent suppliers to recalibrate R&D allocation toward REACH-compliant active ingredients.
Growth Catalysts
- High-speed rail tunneling:Alpine corridor infrastructure mandates specification-grade alkali-free accelerators for hydropower caverns and transit tunnels in Germany, Switzerland, and Austria.
- REACH compliance thresholds:ECHA substance evaluation protocols elevate technical barriers for market entry, advantaging incumbents with registered chemistry portfolios.
- Wet-mix application technology:Pumpability requirements in hydropower segments drive specification for controlled accelerator dispersion systems.
Market Restraints
- Aluminum sulfate feedstock volatility:Bauxite processing capacity concentration in select geographies creates input cost instability for sulfate-based formulations.
- Deep-shaft mining grade supply concentration:Specialized rapid-setting chemistry for vertical excavation remains concentrated among Nordic suppliers with underground testing facilities.
- Alkali-silica reaction standards:Stricter European admissible chemical thresholds force reformulation cycles that extend product development timelines.
Strategic Opportunities
- Chinese GB standard tunnel engineering:MEE environmental compliance certifications create import qualification pathways for REACH-registered European suppliers.
- Synthetic accelerator convergence:Reduced rebound rate chemistry combined with worker safety compliance opens margin expansion in mechanized mining operations.
- OSHA silica exposure protocols:United States underground construction safety mandates drive specification migration toward low-dust accelerator delivery systems.
Industry Challenges
- Spray application technician certification:Wet-mix pump operation and accelerator dosing calibration require specialized training pipelines that lag demand growth.
- Legacy dry-mix equipment retrofit:Existing fleet conversion for alkali-free chemistry compatibility demands capital deployment that contractor balance sheets strain to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shotcrete Accelerators Market |
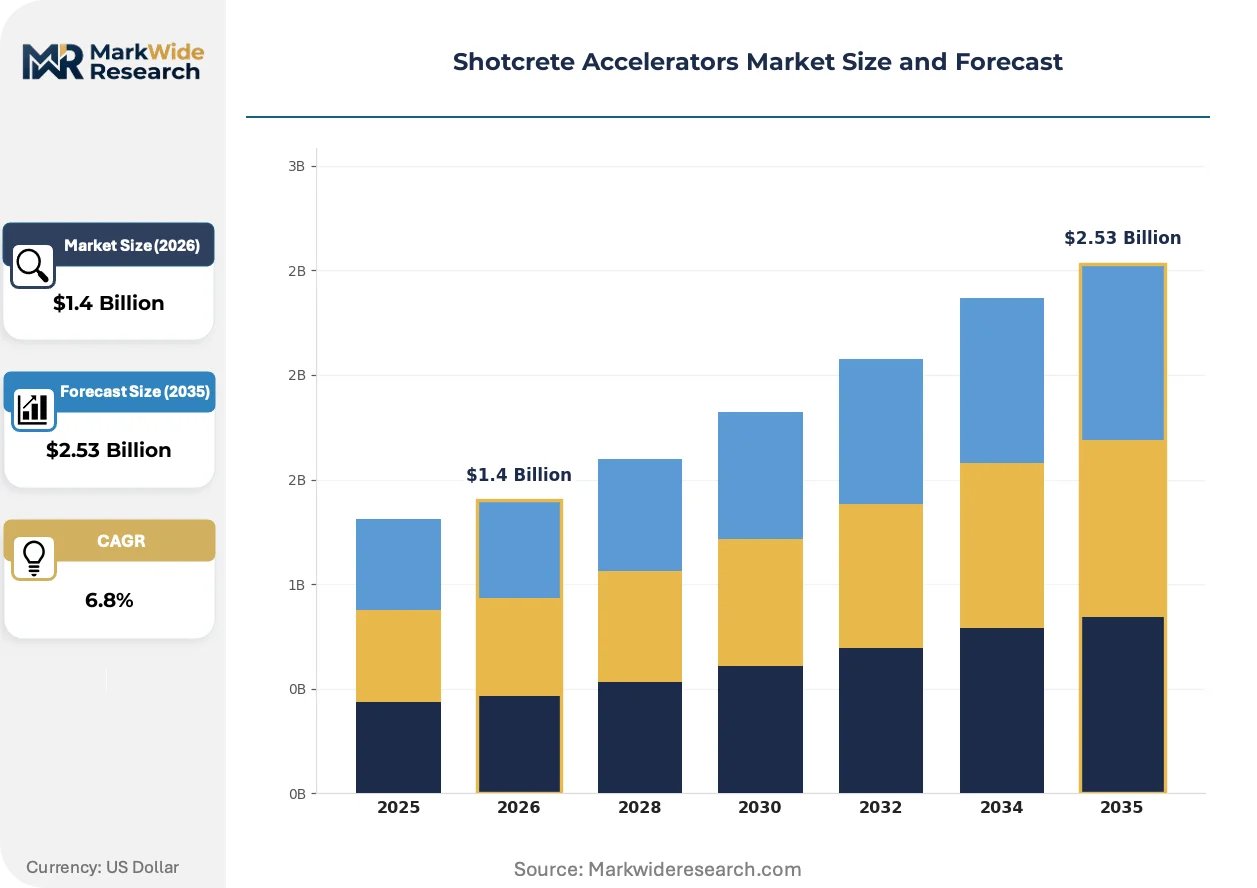
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Accelerators, Synthetic Accelerators, Mineral Accelerators, Admixtures Application: Tunnel Construction, Mining, Structural Repair, Water Proofing End User: Construction Companies, Mining Companies, Engineering Firms, Contractors Technology: Sprayed Concrete, Dry Mix, Wet Mix, High-Performance Mix |
| Companies Covered | BASF SE, Sika AG, Mapei S.p.A., GCP Applied Technologies Inc., Normet Oy, The Euclid Chemical Company, Fosroc, CEMEX S.A.B. de C.V., Denka Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shotcrete Accelerators Market Emerging Trajectories
Formulation chemistry is fragmenting into performance-optimized and cost-optimized tracks as regulatory divergence between European hazard classifications and emerging economy standards accelerates product portfolio complexity.
Amorphous aluminum hydroxide accelerator technology is bifurcating the specification landscape between premium wet-mix tunneling applications and commodity dry-mix mining operations. Hydropower contractors in the Alpine corridor specify hydroxide-based systems for controlled setting and reduced rebound. Mining operators in deep-shaft environments adopt the same chemistry for worker safety compliance, compressing the historical tier separation between performance and standard grades.
REACH registration requirements and ECHA substance evaluation protocols are constraining permissible active ingredients in European formulations. Manufacturers face elevated R&D costs for reformulation cycles to maintain compliance. Wet-mix tunneling segments absorb these costs through specification premiums, while dry-mix mining grades experience margin compression.
Buyer procurement is consolidating around certified applicator networks that guarantee specification compliance and warranty coverage. Traditional distributor channels face disintermediation as major tunneling contractors establish direct technical partnerships with admixture suppliers. This pattern concentrates most visibly in Germany and Switzerland where high-speed rail project bundling favors integrated supply arrangements over fragmented purchasing.
Shotcrete Accelerators Market Segmentation
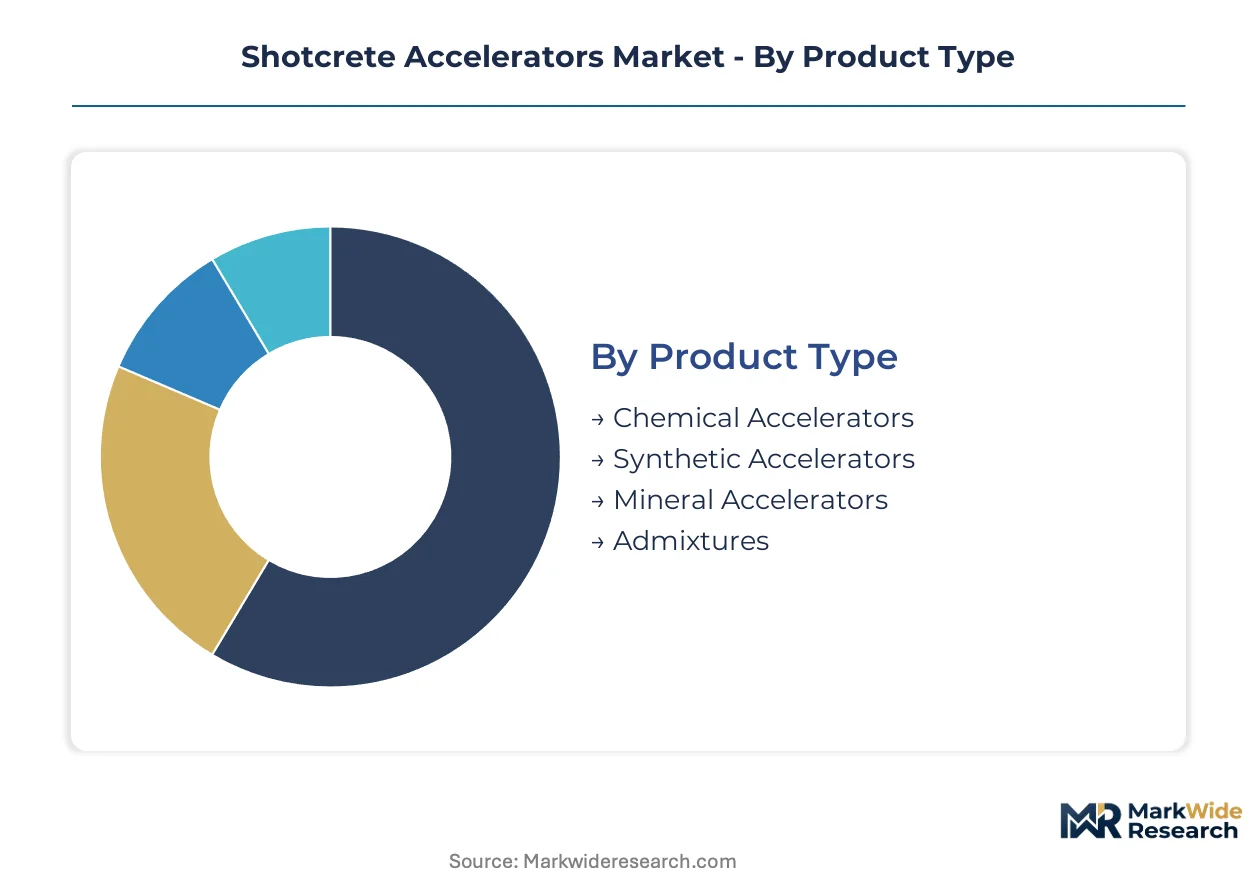
Shotcrete accelerator demand fragments across distinct performance tiers, each tied to specific regulatory thresholds and application protocols. Tunnel contractors in Germany and Switzerland specify alkali-free chemistry for hydropower caverns, while mining operators in Austria prioritize rapid-setting formulations for deep-shaft stability.
Product Type:
Domestic production concentrates chemical and mineral accelerators for European tunnel markets, while synthetic formulations flow through export channels into mechanized mining operations across Central Asia and South America.
- Chemical Accelerators:Aluminum sulfate and alkali silicate formulations dominate Alpine corridor tunnel specifications. REACH-registered chemistry from German and Swiss suppliers anchors demand for hydropower caverns where ECHA substance evaluation protocols govern admissible active ingredients.
- Synthetic Accelerators:Amorphous aluminum hydroxide systems reduce rebound rates and alkali content for worker safety compliance. Mining operators in deep-shaft environments specify these formulations where OSHA silica exposure limits and reduced dust generation determine procurement decisions.
- Mineral Accelerators:Ground granulated blast-furnace slag and silica fume blends serve cost-optimized dry-mix applications in emerging economy infrastructure.
- Admixtures:Multi-component systems integrate accelerators with plasticizers and retarders for controlled setting in complex pour sequences.
Chemical accelerators command the established base. The steepest expansion runs through synthetic formulations.
Application:
Cost tier differentiation separates specification-grade tunneling chemistry from commodity mining formulations, with premium wet-mix systems absorbing REACH compliance costs through project bundling arrangements.
- Tunnel Construction:High-speed rail and transit tunnel mandates in Germany, Switzerland, and Austria drive alkali-free accelerator consumption. Wet-mix pumpability requirements and controlled dispersion systems determine specification success in hydropower caverns.
- Mining:Deep-shaft vertical excavation demands rapid-setting chemistry with sub-five-minute final set times. Nordic suppliers with underground testing facilities anchor supply for mechanized operations where ground instability threatens structural integrity.
- Structural Repair:Bridge deck rehabilitation and seismic retrofit applications specify accelerated shotcrete for bond strength and reduced downtime.
- Water Proofing:Basement and foundation sealing employs low-dosage accelerators for spray-applied membrane compatibility.
Tunnel construction absorbs the premium tier. Mining applications are gaining share fastest in volume terms.
End User:
Customer type determines procurement channel structure, with major tunneling contractors establishing direct technical partnerships while fragmented mining operators route through certified applicator networks.
- Construction Companies:Alpine corridor infrastructure specialists bundle admixture procurement across high-speed rail project portfolios. Integrated supply arrangements with Sika AG and BASF SE disintermediate traditional distributor channels in Germany and Switzerland.
- Mining Companies:Mechanized operators in deep-shaft environments specify synthetic accelerators for reduced rebound and worker safety compliance. Procurement concentrates among Nordic suppliers with demonstrated underground performance data.
- Engineering Firms:Design consultants specify accelerator chemistry during tender preparation, influencing contractor procurement decisions.
- Contractors:Spray application technician certification requirements and wet-mix pump operation training lag demand growth, constraining qualified labor supply.
Construction companies anchor specification-grade volume. Mining companies drive the steepest chemistry transition.
Technology:
Application maturity separates established dry-mix equipment fleets from wet-mix conversion investments, with legacy retrofit costs straining contractor balance sheets.
- Wet Mix:Pumpability and controlled accelerator dispersion define specification success in hydropower and transit tunnel segments. Alpine corridor contractors absorb premium chemistry costs through project bundling that favors integrated admixture supply.
- Dry Mix:Legacy equipment dominates mining applications where dust generation and rebound rates tolerate commodity-grade formulations. Equipment conversion for alkali-free chemistry compatibility demands capital deployment.
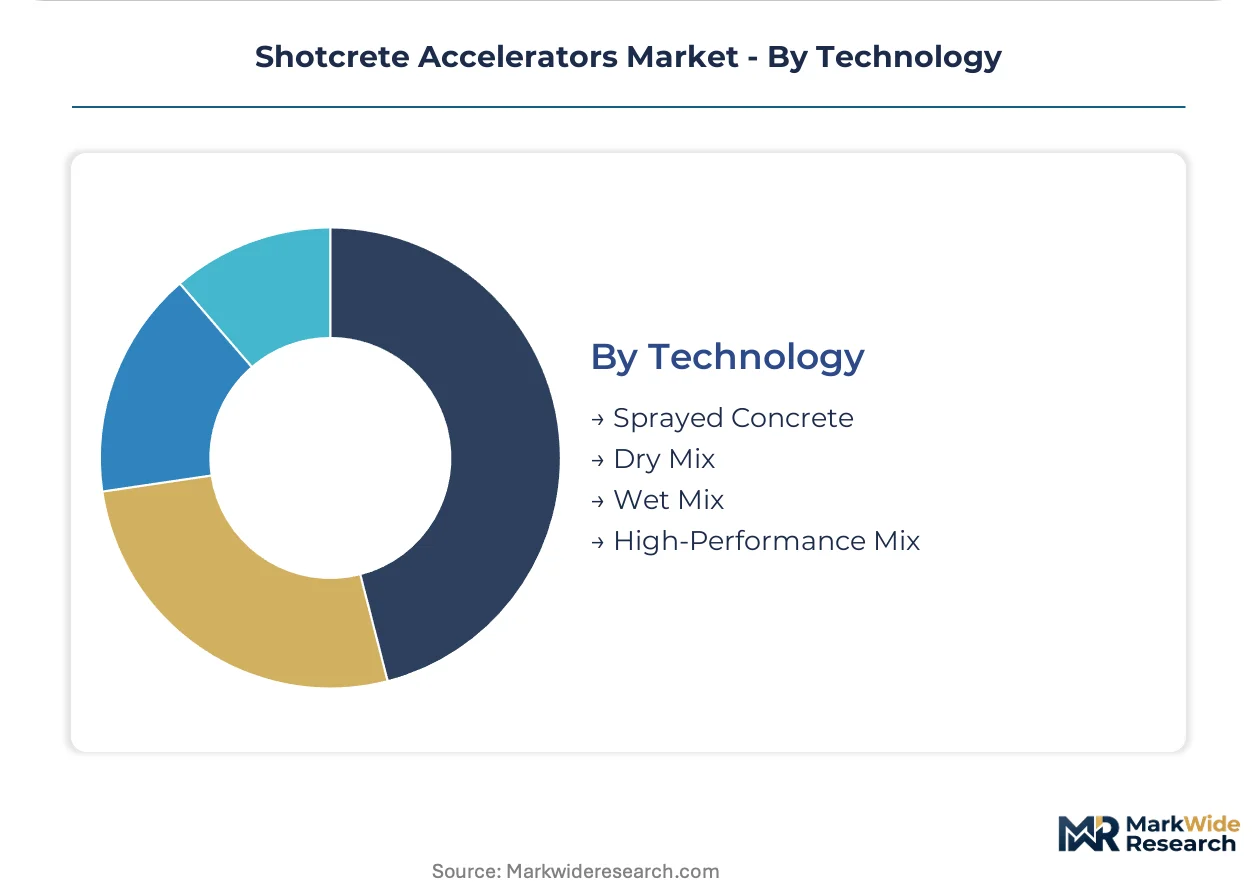
- Sprayed Concrete:Umbrella term covering both wet and dry delivery methods, with specification standards diverging by end-use.
- High-Performance Mix:Engineered formulations combining multiple admixtures for extreme environment applications including seismic zones and chemical exposure.
Dry-mix technology holds the installed base. Wet-mix systems are climbing the fastest in specification-grade penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of REACH-registered alkali-free formulations concentrate in German and Swiss manufacturing hubs, while import demand surges in Chinese tunnel engineering and Australian mining operations. Trade balances tilt toward surplus in European specialty chemistry and deficit in emerging economy infrastructure markets.
Germany
High-speed rail tunneling along the Stuttgart-Ulm and Munich-Verona corridors consumes specification-grade accelerators for hydropower caverns. ECHA substance evaluation protocols under REACH registration constrain permissible active ingredients, elevating technical barriers for domestic suppliers. The Alpine corridor construction cluster in Bavaria anchors wet-mix pumpability requirements for controlled accelerator dispersion systems.
China
GB standard tunnel engineering for high-speed rail networks drives import qualification pathways for European REACH-registered chemistry. MEE environmental compliance certifications govern domestic production licensing and foreign supplier registration. The Yangtze River Delta infrastructure belt concentrates wet-mix application technology deployment for transit tunnel segments.
Switzerland
Gotthard Base Tunnel maintenance and new Alpine transit links sustain premium alkali-free formulation demand. Swissmedic chemical hazard classifications align with ECHA protocols, streamlining cross-border supply with EU suppliers. The Ticino construction corridor exemplifies integrated admixture procurement bundling across bundled high-speed rail portfolios.
Australia
Mechanized mining operations in Western Australia's Pilbara region specify synthetic accelerators for reduced rebound and worker safety compliance. The country's national occupational health regulator enforces silica exposure limits that shape low-dust accelerator delivery system procurement. Perth-based mining contractors anchor deep-shaft vertical excavation chemistry demand for sub-five-minute final set times.
United States
OSHA silica exposure protocols drive specification migration toward low-dust accelerator delivery systems in underground transit construction. EPA National Emission Standards for Hazardous Air Pollutants shape product design and jobsite application protocols. The Pacific Northwest hydropower rehabilitation cluster concentrates structural repair applications specifying accelerated shotcrete for bond strength.
Shotcrete Accelerators Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry tiers, creating a bifurcated structure where scale-driven multinationals face focused technology boutiques. The vendor base separates into REACH-registered portfolio holders, mining-grade rapid-setting specialists, and integrated construction materials conglomerates. Three archetypes dominate: specification-grade tunneling chemistry providers, deep-shaft mining formulation experts, and diversified admixture platform operators. Capacity expansion in alkali-free manufacturing and strategic partnerships for Chinese GB standard qualification represent the dominant competitive moves.
Among European-based chemistry specialists, BASF SE, Sika AG, and Normet Oy exemplify distinct positioning archetypes. BASF SE occupies a position representing manufacturing scale and REACH-compliant portfolio breadth across Alpine infrastructure corridors. Sika AG anchors the integrated admixture technology platform tier, exemplifying specification leadership in wet-mix tunneling applications. Normet Oy sits within the mining-grade specialization archetype, representing deep expertise in rapid-setting formulations for deep-shaft operations. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning in a market where regulatory registration and application-specific performance data determine procurement decisions.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Mapei S.p.A. |
| GCP Applied Technologies Inc. |
| Normet Oy |
| The Euclid Chemical Company |
| Fosroc |
| CEMEX S.A.B. de C.V. |
| Denka Company Limited |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day raw material lead times for aluminum sulfate and amorphous aluminum hydroxide feedstocks compress pricing power for commodity-grade suppliers while REACH-registered formulation specialists in Germany and Switzerland command specification premiums through inventory scarcity and technical barriers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in shotcrete accelerator procurement. Specification-grade alkali-free formulations for Alpine corridor hydropower caverns command premium positioning driven by REACH registration costs and wet-mix pumpability certification, while commodity sulfate-based grades for dry-mix mining applications face cost compression from bauxite processing volatility. Margins are tightening in standard-tier chemical accelerators as Chinese GB standard qualification pathways open import competition. Mining contractors in mechanized operations exhibit highest price sensitivity, whereas German high-speed rail project bundling arrangements show lowest sensitivity due to integrated supply guarantees.
Supply Chain Analysis
Just-in-time inventory strategies dominate European specification-grade supply chains, while strategic stockpiling of aluminum sulfate concentrates persists among Asian dry-mix compounders exposed to bauxite processing bottlenecks. Manufacturing gravity centers on Germany, Switzerland, and China, with Nordic suppliers anchoring deep-shaft mining-grade rapid-setting chemistry. Raw material flows draw from bauxite refining corridors, alkali silicate production clusters, and synthetic hydroxide synthesis facilities. Single-source vulnerability concentrates in aluminum sulfate feedstock where processing capacity clusters in select geographies. Distribution runs through certified applicator networks that disintermediate traditional distributor channels in specification-grade tunneling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shotcrete accelerators function as a regulatory-entrenchment market where REACH registration portfolios and ECHA substance evaluation compliance create defensive moats that extend product development timelines and elevate technical barriers for unregistered competitors.
For Market Incumbents: Consolidate specification-grade positioning by deepening backward integration into amorphous aluminum hydroxide synthesis and expanding captive supply of REACH-registered active ingredients. Capacity addition in Chinese MEE-certified manufacturing addresses emerging economy import qualification pathways while defending against Nordic mining-grade specialists. Certification investment in wet-mix pumpability testing protocols reinforces technical partnership lock-in with Alpine corridor contractors. For New Entrants and Emerging Players: Anchor in Australian mechanized mining operations where silica exposure compliance mandates drive synthetic accelerator substitution and incumbent Nordic suppliers face logistics cost disadvantages. Target structural repair applications in US Pacific Northwest hydropower rehabilitation where OSHA protocols favor low-dust delivery systems and specification standards remain less entrenched than European tunneling. Go-to-market through direct technical partnerships with certified spray application training networks rather than distributor channel penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction materials conglomerates where accelerator portfolios represent non-core revenue streams with stranded REACH registration assets. Long-term viability over a multi-year horizon hinges on alkali-free chemistry transition completion and Chinese GB standard qualification achievement. Signal to monitor: divergence between European ECHA hazard classifications and Chinese MEE environmental compliance thresholds that would force dual-formulation R&D burden on single-portfolio players.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Expansion | ECHA substance evaluation protocols elevate technical barriers for unregistered competitors in Alpine corridor projects. |
| Backward Integration into Hydroxide Synthesis | Captive production of amorphous aluminum hydroxide reduces rebound rate chemistry cost exposure and secures supply. |
| Chinese GB Standard Qualification | MEE environmental compliance certification opens import pathways for European suppliers into Yangtze River Delta infrastructure. |
| Wet-Mix Application Technology Partnership | Controlled accelerator dispersion system integration locks in specification-grade procurement with German high-speed rail contractors. |
| Certified Applicator Network Development | Direct technical training pipelines disintermediate distributor channels and guarantee warranty coverage compliance. |
Methodological Framework
A spread of perspectives from tunnel construction procurement directors, mining operations managers, admixture R&D chemists, and certified spray application technicians converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through ECHA substance registration databases, SEC 10-K filings of listed admixture suppliers, customs trade flow records for aluminum sulfate and alkali silicate imports, and tunnel engineering specification documents from Alpine corridor project tenders. Bottom-up volume modeling from individual project chemistry requirements triangulated against top-down market sizing from supplier revenue disclosures.
Segmentation dimensions modeled encompass product type tier, application protocol, end-user procurement channel structure, and technology delivery method across the analysis window. CAGRs derived from regression analysis of historical specification-grade and commodity-grade volume trajectories, adjusted for regulatory compliance cost pass-through assumptions and wet-mix technology penetration curves. Industry-specific forecast inputs include high-speed rail tunnel project pipeline data from German and Swiss infrastructure authorities and mechanized mining capital expenditure plans from Australian and South American operators.
Material uncertainties — bauxite processing capacity disruptions, divergence between European and Chinese regulatory hazard classifications, and spray technician certification pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding REACH registration maintenance costs and MEE certification timeline stability. Revision becomes warranted when aluminum sulfate feedstock concentration crosses thresholds that trigger supply rationing among compound-grade manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Construction Repaint Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Composite Repair Market
Specialty Construction
Portable Walls Market
Specialty Construction
Global Fencing Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
India Anchors and Grouts Market