
 Asia-Pacific Waterproofing Solutions Market | 2026-2036
Asia-Pacific Waterproofing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Waterproofing Solutions Market Insights
China's manufacturing corridor for polymer-modified bitumen is narrowing the supply gap for high-performance sheet membranes. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. leverages domestic feedstock access to sustain cost leadership across liquid membrane formulations. Sika AG anchors its regional position through integrated supply chains serving infrastructure tunneling projects from Singapore to Sydney. Pidilite Industries Limited specializes in cementitious systems tailored to India's monsoon-exposed coastal construction.
Asia-Pacific waterproofing solutions encompass engineered barriers—polyurethane liquid membranes, bituminous sheet layers, cementitious coatings, and EPDM seals—applied to structural surfaces to prevent water ingress and chloride penetration, typically specified to withstand hydrostatic pressures exceeding 70 meters head. The technology dimension shows polyurethane liquid membranes capturing premium specification in complex geometries such as podium decks and green roofs, while bituminous sheet membranes dominate volume in Chinese infrastructure tenders where thermal-welding reliability reduces seam failure risk. Application segmentation reveals basement waterproofing as the fastest-growing margin pool, driven by deeper excavation norms across metro rail projects in India and Vietnam.
China's Ministry of Ecology and Environment (MEE) enforces GB standard compliance for VOC emissions in solvent-based waterproofing products, pushing manufacturers toward water-borne polyurethane formulations. India's BIS certification for waterproofing materials under IS 13262 creates market access barriers for uncertified imports, reinforcing domestic production incentives. Australia's National Construction Code mandates flood-resilient basement specifications in designated zones, lifting demand for dual-layer membrane systems. Stakeholders must monitor how evolving green building rating tools across the region recalibrate material eligibility criteria for public procurement.
Market Dynamics
China's GB standard enforcement on VOC emissions is forcing solvent-based waterproofing manufacturers toward water-borne polyurethane reformulation, compressing margins for legacy producers while opening specification gates for compliant domestic suppliers across tier-one infrastructure tenders.
Growth Catalysts
- India's BIS certification mandate:IS 13262 compliance requirements for coastal zone construction create captive demand for certified cementitious systems, insulating domestic producers from import competition.
- Underground rail excavation:Metro basement projects across Vietnam and India specify dual-layer membrane assemblies to withstand hydrostatic pressures exceeding 70 meters head.
- Polymer-modified bitumen sheet technology:Thermal-welding reliability in Chinese infrastructure tenders reduces seam failure risk versus conventional torch-applied methods.
Market Restraints
- Crude oil derivative volatility:Bitumen and polyurethane feedstock costs fluctuate with regional refining capacity constraints, squeezing formulation margins.
- Domestic supply concentration:China's polymer-modified bitumen manufacturing corridor narrows to Shandong and Jiangsu provinces, creating geographic single-point vulnerability.
- EPDM substitution pressure:Synthetic rubber seals compete for green roof and podium deck specifications where complex geometries favor sheet over liquid application.
Strategic Opportunities
- Vietnam's underpenetrated metro construction:Ho Chi Minh City and Hanoi rail expansions lack established membrane specification standards, opening first-mover positioning for certified suppliers.
- Australia's flood-resilient basement mandate:National Construction Code designated zones now require dual-layer systems, lifting premium membrane demand in Queensland and New South Wales.
- Water-borne polyurethane convergence with green building ratings:Regional LEED-equivalent tools recalibrate material eligibility for public procurement, advantaging low-VOC formulations.
Industry Challenges
- Certification timeline compression:BIS and GB standard testing protocols extend product validation cycles, delaying market entry for reformulated chemistries.
- Thermal welding technician scarcity:Chinese infrastructure tenders demand certified applicators for polymer-modified bitumen seams, constraining project execution capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Waterproofing Solutions Market |
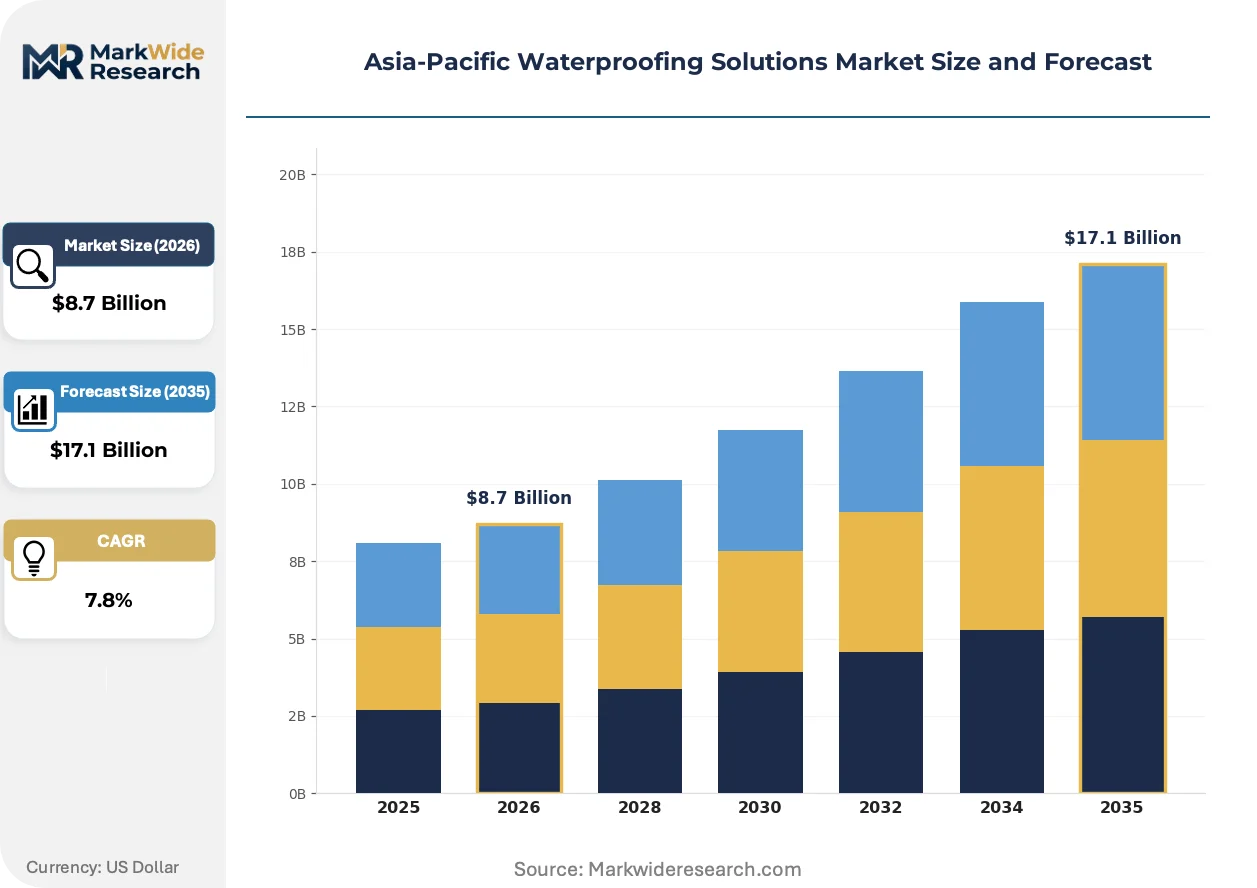
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Membranes, Sheet Membranes, Coatings, Sealants Application: Roofing, Walls, Basements, Parking Structures End User: Residential, Commercial, Industrial, Infrastructure Technology: Polyurethane, Bituminous, Cementitious, EPDM |
| Companies Covered | Beijing Oriental Yuhong Waterproof Technology Co., Ltd., Sika AG, Saint-Gobain, Ardex Group, Hongyuan Waterproof Technology Group Co., Ltd., BASF SE, Mapei S.p.A., Pidilite Industries Limited, Keshun Waterproof Technology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Waterproofing Solutions Market Trends and Innovations
Waterproofing chemistry is hybridizing across material classes as manufacturers chase performance thresholds demanded by deeper excavation norms and green building eligibility criteria.
Polyurethane liquid membrane technology is hybridizing with cementitious additives to create moisture-tolerant formulations that bond to damp concrete substrates. Singaporean commercial podium deck contractors specify these systems for accelerated construction schedules where curing time compression matters. The structural consequence is segment blurring between liquid and cementitious categories, forcing suppliers to maintain dual formulation competencies.
China's MEE enforces GB standard VOC emission limits on solvent-based waterproofing products used in enclosed underground spaces. Manufacturers respond by converting production lines to water-borne polyurethane, absorbing capital costs to retain Beijing and Shanghai infrastructure access. The policy impact concentrates on high-volume sheet membrane producers with legacy solvent-dependent processes.
Specification authority is migrating from general contractors to specialist waterproofing subcontractors in complex basement projects across India and Southeast Asia. These subcontractors demand performance warranties rather than material supply-only contracts, shifting risk allocation upstream to membrane manufacturers. The behavioral change is most visible in Mumbai and Bengaluru metro rail tenders where design-build contracts dominate.
Asia-Pacific Waterproofing Solutions Market Segmentation
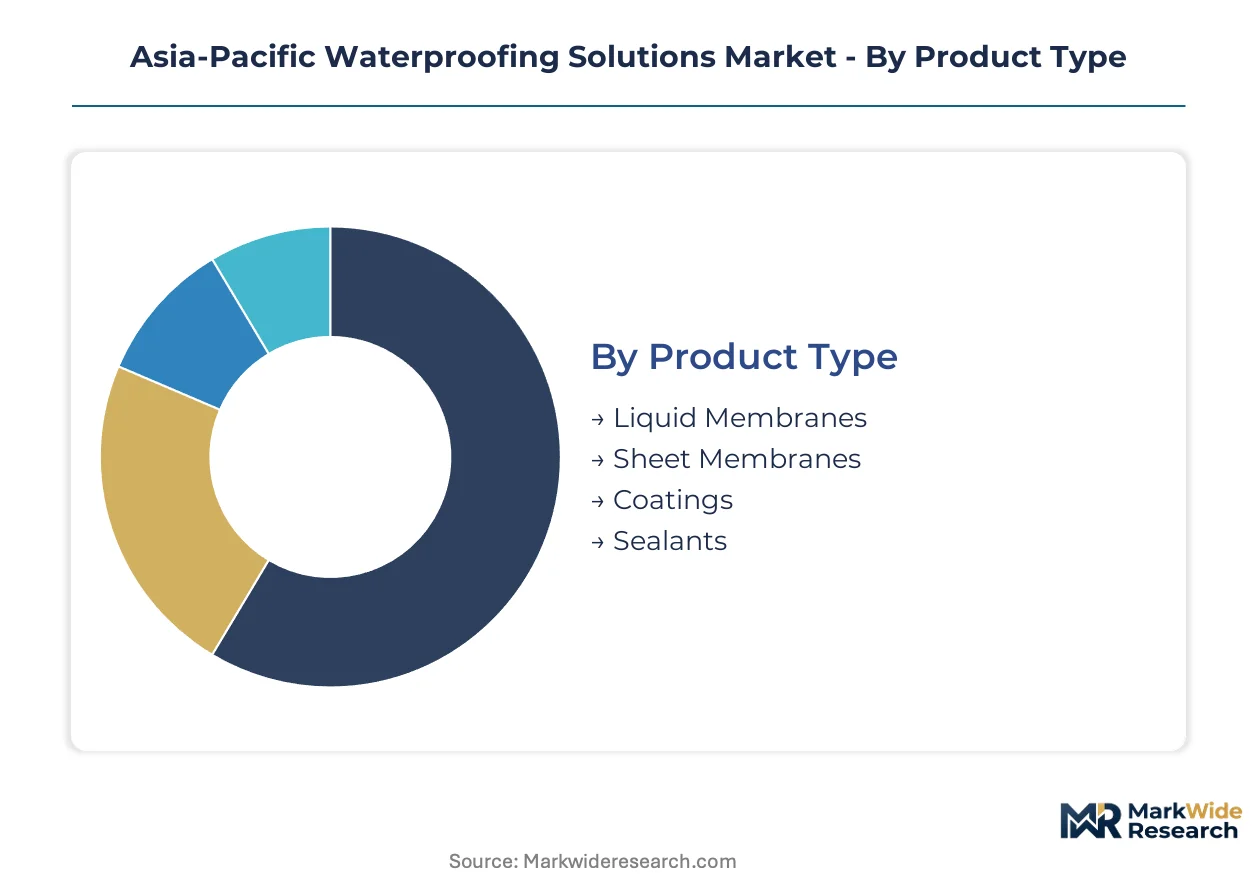
Segmentation in waterproofing solutions tracks how material chemistry, structural application, and procurement authority intersect. Specification patterns diverge sharply between infrastructure tenders with rigid thermal-welding mandates and commercial projects prioritizing curing speed.
Product Type:
Specification authority varies by project complexity — liquid systems dominate irregular geometries while sheet membranes capture volume in standardized infrastructure.
- Liquid Membranes:Polyurethane and hybrid polymer formulations cure to seamless elastomeric barriers. Podium decks and green roofs across Singapore's commercial district specify these for complex drainage geometries where sheet seaming proves impractical.
- Sheet Membranes:Polymer-modified bitumen layers with thermal-weldable seams deliver hydrostatic resistance exceeding 70 meters head. Chinese metro rail tenders in Beijing and Shanghai mandate these for basement walls where seam integrity is non-negotiable.
- Coatings:Cementitious crystalline systems penetrate concrete substrates to block capillary water migration. Indian coastal construction under BIS IS 13262 specifies these for monsoon-exposed podium slabs.
- Sealants:EPDM and polysulfide compounds fill expansion joints and penetrations. Australian flood-resilient basement codes in Queensland drive dual-layer specifications combining sealants with primary membranes.
Established volume favors Sheet Membranes; emerging adoption favors Liquid Membranes.
Application:
Excavation depth and hydrostatic pressure dictate material selection across structural planes.
- Roofing:Exposed membrane assemblies must withstand thermal cycling and UV degradation. Green roof specifications across China's tier-one cities favor root-resistant EPDM with fleece backing.
- Walls:Vertical surfaces demand spray-applied systems with sag resistance. Vietnamese commercial towers specify cementitious coatings for below-grade retaining walls where access constraints limit sheet application.
- Basements:Dual-layer assemblies combining drainage composites with primary membranes address rising water tables. India's metro rail projects in Mumbai and Bengaluru represent the steepest expansion trajectory for this segment.
- Parking Structures:Chloride-bearing de-icing salts and carbonation drive specification of crystalline coatings. Australian multi-level car parks in Sydney specify traffic-bearing membrane systems with wearing courses.
Margin concentration clusters in Basements; specification standardization advances fastest in Parking Structures.
End User:
Procurement sophistication separates infrastructure tenders with performance warranties from residential projects focused on first-cost minimization.
- Residential:Single-family and multi-family construction specify cost-optimized bituminous coatings. India's affordable housing schemes drive volume for torch-applied membrane systems in tier-two cities.
- Commercial:Podium decks, plaza areas, and building envelopes demand accelerated curing to compress construction schedules. Singaporean developers specify moisture-tolerant polyurethane for tight completion windows.
- Industrial:Chemical processing facilities and cold storage require membrane systems with thermal shock resistance. Australian food processing plants specify specialized EPDM formulations for freezer floor slabs.
- Infrastructure:Design-build contracts with 10-year waterproofing warranties shift risk to membrane manufacturers. Vietnam's Ho Chi Minh City metro expansion lacks established specification standards, creating first-mover positioning for certified suppliers.
Contract value peaks in Infrastructure; project velocity drives specification in Commercial.
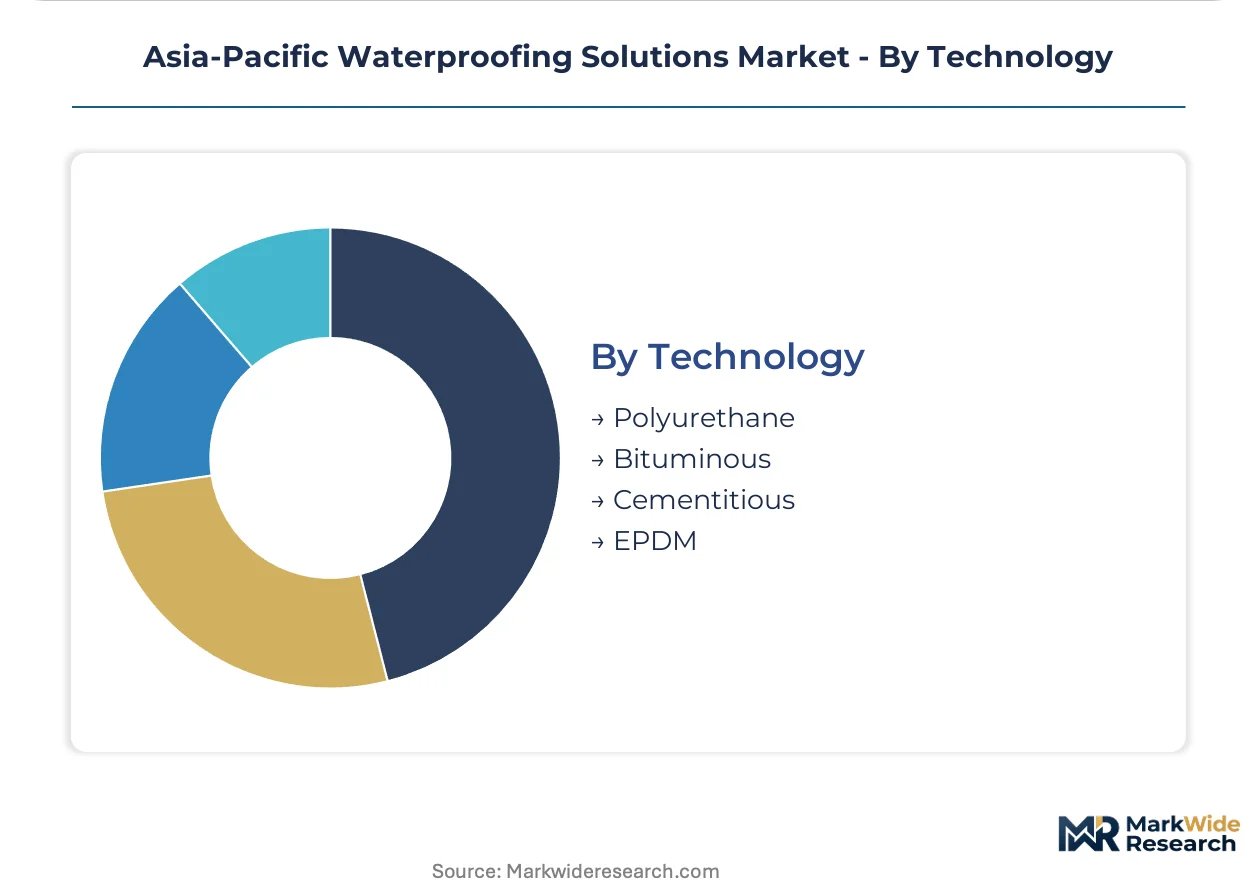
Technology:
Regulatory chemistry constraints are fragmenting competitive position between solvent-dependent legacy producers and water-borne reformulators.
- Polyurethane:Two-component elastomeric systems bond to damp concrete and accommodate structural movement. China's MEE GB standard VOC limits are forcing solvent-based manufacturers toward water-borne reformulation.
- Bituminous:Atactic polypropylene and styrene-butadiene-styrene modified bitumen deliver thermal-weld seam reliability. Shandong and Jiangsu provinces concentrate domestic manufacturing capacity for these sheet products.
- Cementitious:Crystalline and flexible polymer-modified cement systems integrate with concrete chemistry. BIS certification requirements insulate Indian domestic producers from import competition in coastal zones.
- EPDM:Ethylene propylene diene monomer sheets offer root resistance and UV stability for exposed applications. Green roof specifications across Australian LEED-equivalent projects favor these for longevity.
Volume leadership sits with Bituminous; regulatory tailwinds favor Polyurethane conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment anchors regional regulatory direction through GB standard enforcement on VOC emissions, compressing solvent-based formulation margins while accelerating water-borne polyurethane adoption across Beijing and Shanghai infrastructure tenders.
China
Polymer-modified bitumen sheet production concentrates in Shandong and Jiangsu provinces, supplying thermal-weldable membranes for metro rail basements. MEE's GB standards on solvent emissions force manufacturers toward water-borne polyurethane reformulation. Beijing and Shanghai infrastructure tenders specify dual-layer membrane assemblies for underground commercial developments.
India
Metro rail excavation in Mumbai and Bengaluru drives basement waterproofing specification with hydrostatic resistance exceeding 70 meters head. BIS mandates IS 13262 certification for coastal zone construction, insulating domestic cementitious producers from import competition. Maharashtra and Karnataka states concentrate demand for certified crystalline coating systems.
Australia
Flood-resilient basement mandates under the National Construction Code lift dual-layer membrane demand in Queensland and New South Wales. Sydney commercial developments specify traffic-bearing systems for multi-level parking structures. Melbourne and Brisbane infrastructure projects prioritize EPDM formulations for green roof longevity.
Vietnam
Ho Chi Minh City and Hanoi rail expansions lack established membrane specification standards, creating positioning opportunities for certified suppliers. Below-grade retaining walls in commercial towers specify cementitious coatings where access constraints limit sheet application. Vietnamese construction codes are evolving toward BIS-equivalent certification requirements.
Singapore
Commercial podium deck contractors specify moisture-tolerant polyurethane for accelerated construction schedules. Green building rating tools recalibrate material eligibility criteria for public procurement, advantaging low-VOC formulations. Marina Bay and Orchard Road developments concentrate premium liquid membrane specification for complex drainage geometries.
Asia-Pacific Waterproofing Solutions Market Competitive Landscape
Capability concentration sits with specialized membrane formulators; scale advantage sits with diversified construction chemical conglomerates. The competitive structure fragments across three tiers: domestic Chinese manufacturers with feedstock proximity, European multinationals with integrated regional supply chains, and Indian specialists with BIS-certified coastal formulations. Strategic moves center on water-borne polyurethane capacity conversion and BIS/GB certification acquisition to secure infrastructure tender access.
Within the domestic Chinese tier, Beijing Oriental Yuhong Waterproof Technology Co., Ltd. and Hongyuan Waterproof Technology Group Co., Ltd. occupy positions shaped by Shandong and Jiangsu manufacturing corridor proximity. Sika AG and BASF SE exemplify the multinational integrated supply chain archetype serving tunneling projects from Singapore to Sydney. Pidilite Industries Limited represents the BIS-certified domestic specialist model for monsoon-exposed coastal construction.
| Leading Market Players |
|---|
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| Sika AG |
| Saint-Gobain |
| Ardex Group |
| Hongyuan Waterproof Technology Group Co., Ltd. |
| BASF SE |
| Mapei S.p.A. |
| Pidilite Industries Limited |
| Keshun Waterproof Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
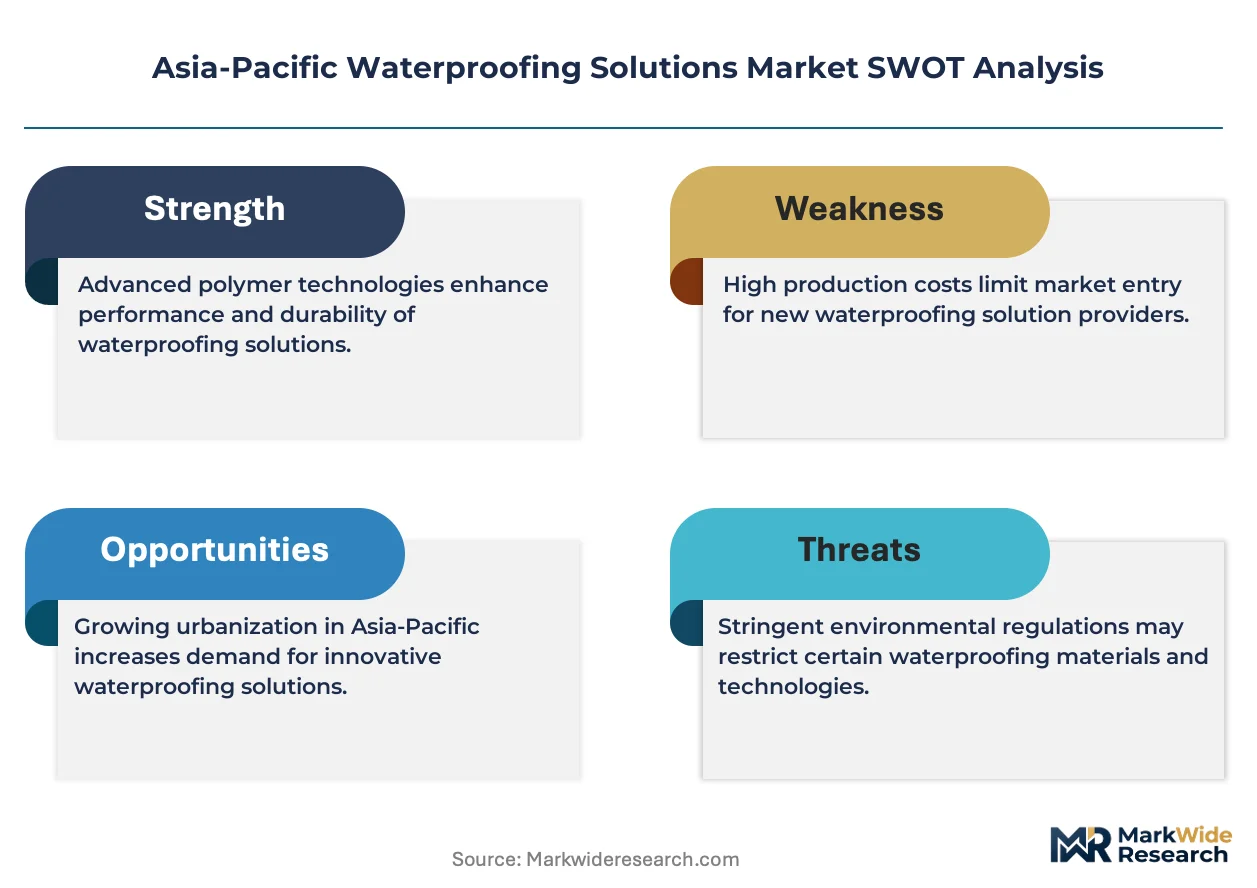
Crude oil derivative volatility in bitumen and polyurethane feedstocks compresses formulation margins while simultaneously widening price spreads between certified premium systems and commodity-grade alternatives across the Asia-Pacific waterproofing market. This input cost instability forces manufacturers to recalibrate procurement strategies and tiered positioning.
Pricing Analysis
China's Shandong and Jiangsu manufacturing corridors command 15-25% price premiums over Southeast Asian imports for polymer-modified bitumen sheets due to thermal-welding certification density. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified cementitious systems from uncertified torch-applied membranes. Pricing pressure stems from water-borne polyurethane reformulation capital absorption as China's MEE enforces GB VOC limits. Residential contractors in India's tier-two cities exhibit highest price sensitivity, while infrastructure design-build contracts in Vietnam show lowest sensitivity due to performance warranty requirements.
Supply Chain Analysis
Export-control restrictions on advanced polymer additives from European and Japanese suppliers constrain water-borne polyurethane formulation access for non-integrated manufacturers. Feedstock supply concentrates in China's Shandong and Jiangsu provinces, South Korea's petrochemical complexes, and Singapore's specialty chemical hubs. Raw material dependencies span atactic polypropylene, styrene-butadiene-styrene, and isocyanate precursors. Single-source vulnerability sits with Shandong's polymer-modified bitumen corridor. Distribution runs through regional construction chemical distributors serving specialist waterproofing subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified thermal-welding technician scarcity across metro rail projects creates a binding constraint that reshapes competitive advantage toward training-captive suppliers. This capability gap rewards early investment in applicator certification programs.
For Market Incumbents: Harden market position by acquiring BIS and GB certification pipelines before regulatory timelines compress, insulating against emerging domestic competitors in India and Vietnam. Deepen backward integration into water-borne polyurethane resin production to offset solvent-based margin compression from China's MEE enforcement. Prioritize captive applicator training networks in Ho Chi Minh City and Hanoi to preempt technician scarcity bottlenecks. For New Entrants and Emerging Players: Mid-market commercial podium decks in Southeast Asia represent the most penetrable entry point where complex geometries favor liquid membrane specification over established sheet membrane incumbents. Vietnam's underpenetrated metro construction lacks established membrane standards, creating first-mover positioning for certified suppliers. Australia's flood-resilient basement mandate in Queensland offers premium dual-layer system demand with lower certification barriers than Chinese infrastructure tenders. Lead with moisture-tolerant polyurethane formulations targeting Singaporean accelerated construction schedules. For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors BIS/GB-certified domestic specialists with captive formulation capabilities. Long-term viability hinges on water-borne chemistry conversion completion and regional certification density. Target acquisition archetypes include Indian cementitious formulators with coastal zone BIS certification and Vietnamese distributors with metro project relationships. Watch for inflection when China's MEE extends GB VOC enforcement to imported solvent-based products.| Strategic Initiative | Industry Significance |
|---|---|
| Water-borne Polyurethane Capacity Conversion | China's MEE GB standard compliance secures Beijing and Shanghai infrastructure tender access. |
| BIS/GB Certification Acquisition | IS 13262 and GB standard testing protocols create defensive moats against import competition. |
| Thermal-welding Technician Training Programs | Certified applicator scarcity in Chinese infrastructure tenders constrains project execution capacity. |
| Backward Integration into Polymer Resins | Captive feedstock supply insulates margin compression from crude oil derivative volatility. |
| Joint Venture with Regional Distributors | Vietnamese construction codes evolving toward BIS-equivalent requirements favor partnered market entry. |
Research Methodology
A spread of perspectives from waterproofing subcontractor project managers, polymer formulation chemists, infrastructure procurement officers, and regional distribution channel heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, BIS certification registries, Chinese Ministry of Ecology and Environment regulatory filings, and construction tender documentation from metro rail authorities. Bottom-up project pipeline enumeration triangulated against top-down chemical consumption estimates across the analysis window.
Demand-supply balance modeling tracked membrane specification volumes against polymer-modified bitumen and polyurethane raw material availability through the projection horizon. Segmentation dimensions spanned product chemistry class, structural application plane, end-user procurement sophistication, and technology regulatory compliance tier. CAGRs derived from weighted project pipeline flows and feedstock capacity expansion schedules. Forecast inputs incorporated excavation depth norms for metro basements and green building rating tool evolution timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, Chinese infrastructure stimulus intensity, or Indian coastal construction permit velocity would shift the trajectory. Material shifts in China's MEE enforcement scope or BIS certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Construction Repaint Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Portable Walls Market
Specialty Construction
Composite Repair Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Slab Repair Products Market