
 Roller Shutter Market | 2026-2036
Roller Shutter Market Size, Share, and Industry Trends Forecast 2026-2036
Roller Shutter Market Analysis
The capital-intensity divergence between in-house extrusion capacity and outsourced component assembly is redrawing competitive tiers among roller shutter manufacturers. Hörmann Group leverages captive aluminum rolling mills to control raw material cost volatility. ASSA ABLOY sustains premium positioning through intensive R&D spending on automated drive systems. Sanwa Holdings Corporation anchors its Asia-Pacific footprint with localized steel slat production.
A roller shutter is a retractable door or window covering comprising horizontal slats hinged together, typically manufactured from aluminum, steel, or PVC, and engineered to provide security, thermal insulation, and weather protection for commercial and industrial openings. Automated operation systems now command the fastest expansion trajectory as warehouse operators prioritize integration with building management platforms. Steel slats still dominate industrial end-use applications where impact resistance and fire ratings determine specification, while aluminum solutions capture margin pools in premium residential retrofits.
The EU F-Gas Regulation and CE marking requirements under the Construction Products Regulation shape thermal performance standards across European installations. The EPA's energy efficiency guidelines and China's GB standards for building materials influence product compliance in their respective jurisdictions. Stakeholders must monitor regulatory divergence on embodied carbon reporting as this will determine which material categories retain specification access in major construction markets.
Market Dynamics
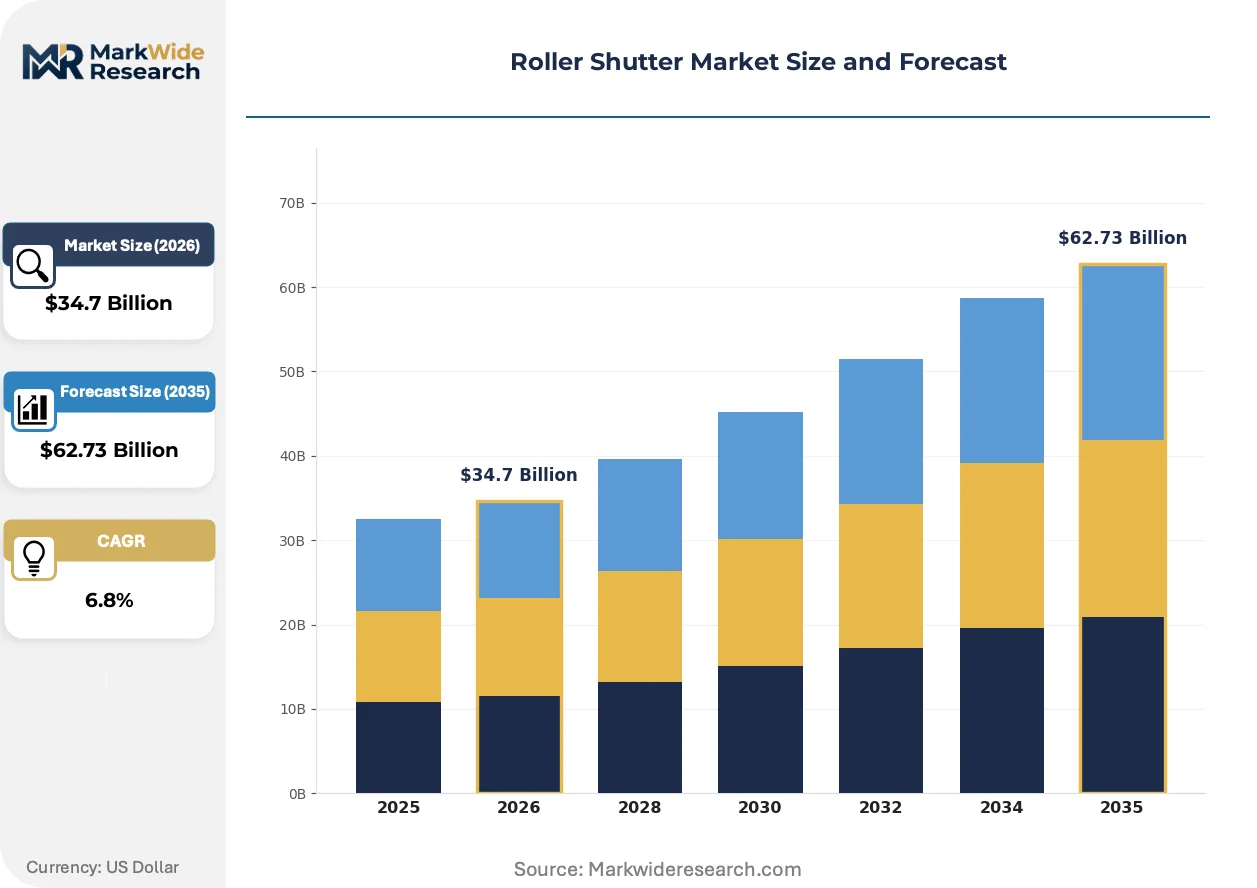
The EU F-Gas Regulation is forcing thermal performance upgrades across European installations while warehouse automation in Germany, China, and the United States pulls demand toward integrated building management systems. This dual pressure is compressing specification timelines and favoring suppliers with captive extrusion capacity.
Growth Catalysts
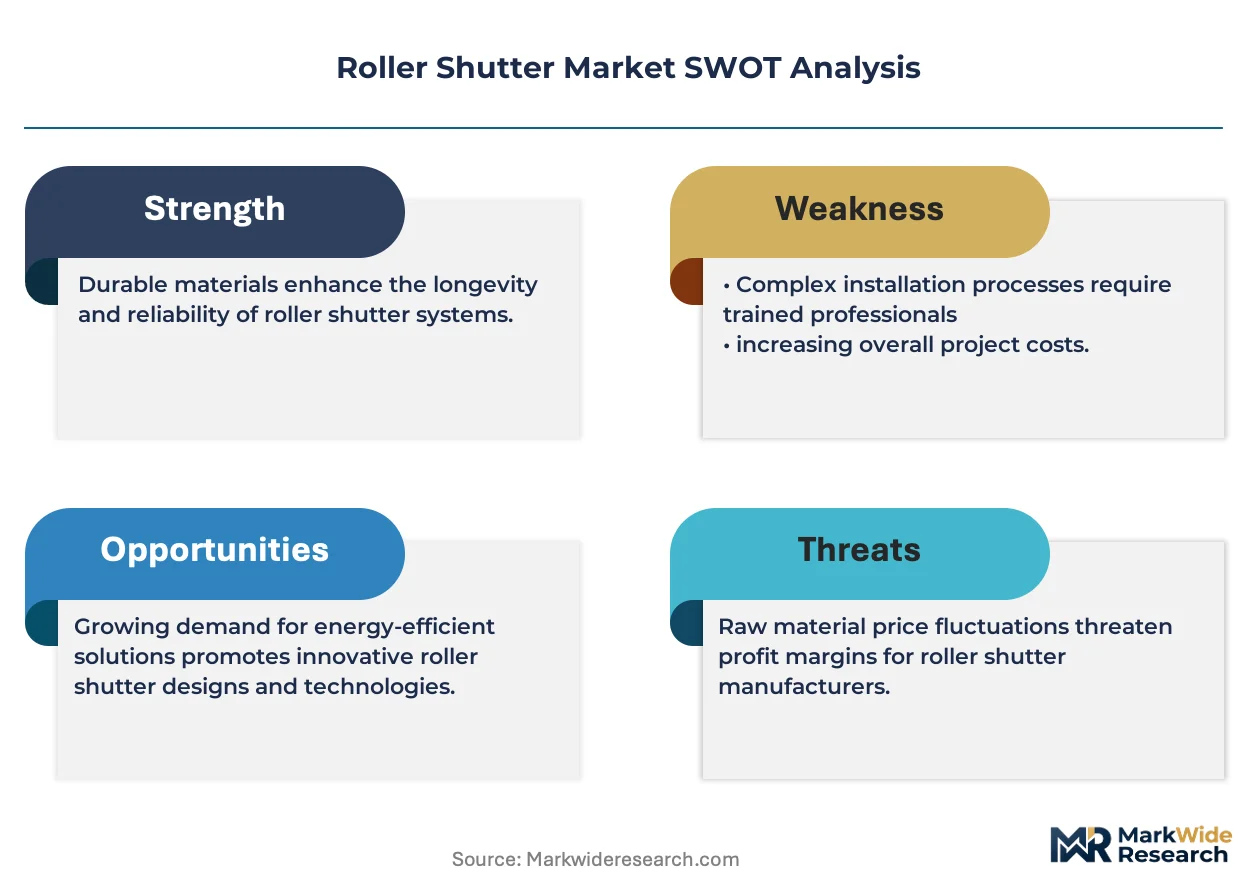
- EU F-Gas Regulation:Mandates for lower-global-warming-potential refrigerants in climate-controlled facilities are accelerating thermally insulated roller shutter adoption in cold-chain logistics.
- Warehouse automation:E-commerce fulfillment centers in Germany and the United States are specifying motorized shutters with programmable logic controller integration.
- Steel slat durability:Fire-rated steel configurations retain specification dominance in industrial applications where impact resistance and insurance underwriting requirements converge.
Market Restraints
- Aluminum price volatility:London Metal Exchange aluminum contract swings compress margin predictability for extrusion-dependent manufacturers.
- Drive motor supply concentration:Sourcing automated actuation systems from a limited supplier base in East Asia creates lead-time vulnerability.
- CE marking complexity:Construction Products Regulation conformity assessment timelines extend project completion schedules for cross-border European contracts.
Strategic Opportunities
- India warehousing expansion:PLI scheme incentives for logistics infrastructure are opening specification windows for fire-rated industrial shutter systems.
- Photovoltaic slat integration:Building-integrated photovoltaics convergence with shutter assemblies creates energy-generating facade opportunities in German retrofits.
- Direct contractor procurement:Large general contractors in the United States are bypassing traditional distribution to source aluminum systems directly from extruders.
Industry Challenges
- Building management system integration:Legacy BACnet and Modbus protocol fragmentation complicates unified control architecture deployment.
- Fire certification timelines:Extended testing protocols for multi-jurisdictional approval delay product launch cycles.
- Automation engineering talent:Scarcity of PLC programming specialists constrains after-sales service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roller Shutter Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, PVC, Fiberglass Operation Type: Manual, Electric, Remote-Controlled, Automated End User: Residential, Commercial, Industrial, Retail Installation Type: Interior, Exterior, Integrated, Custom |
| Companies Covered | Hörmann Group, ASSA ABLOY, Somfy Group, Alulux GmbH, Sanwa Holdings Corporation, SKB Shutters Corporation Berhad, Janus International Group Inc., The Stella Group, Ferco Shutters and Seating Systems Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roller Shutter Market Emerging Trajectories
Connected building infrastructure is redefining shutter specification criteria. Procurement teams now weight interoperability above standalone durability metrics. Three developments are compressing traditional competitive moats.
Polyurethane-foam-filled aluminum slats are displacing hollow extrusions in premium residential retrofits. German and French installers specify these configurations for thermal transmittance values below 1.0 W/m²K. The shift is compressing price premiums previously commanded by steel thermal-break alternatives.
REACH substance restrictions and the EU Green Deal embodied carbon reporting requirements are reshaping material selection protocols. Aluminum recyclate content thresholds now appear in French public procurement specifications. Suppliers with verified scrap-input documentation are securing municipal contract preference.
Facility managers are unbundling maintenance contracts from initial equipment purchase. German industrial end-users now source shutter systems and service agreements through separate competitive tenders. This bifurcation is compressing traditional OEM aftermarket revenue streams and opening third-party service provider entry points.
Roller Shutter Market Segmentation
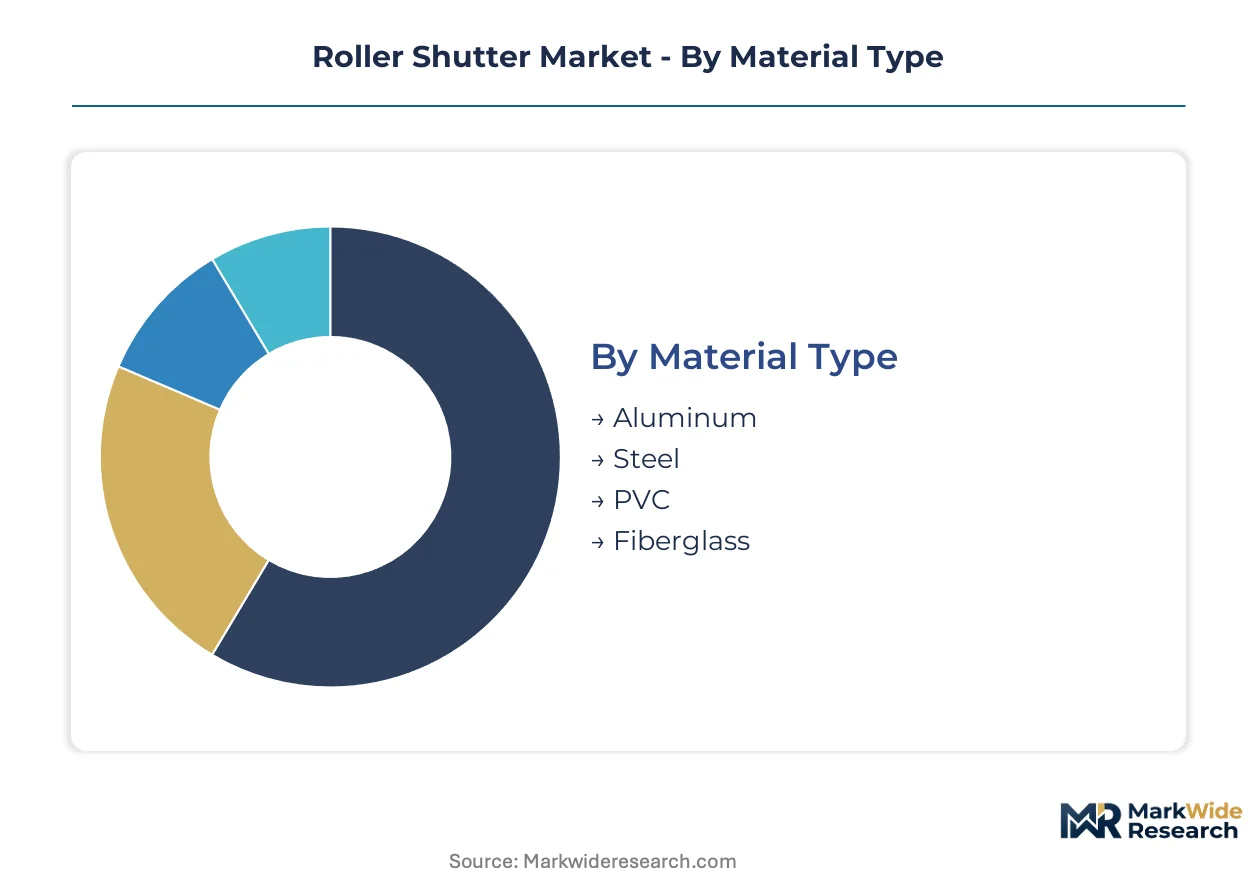
Segmentation in the roller shutter market determines specification access across divergent regulatory and performance environments. Material selection protocols vary sharply between EU thermal compliance mandates and industrial fire-rating requirements. Operation type segmentation is compressing as building management system integration becomes a baseline procurement criterion.
Material Type:
Aluminum faces intensifying substitution pressure from polyurethane-foam-filled configurations that deliver comparable thermal transmittance at lower weight penalties.
- Aluminum:Hollow and foam-filled extrusions dominate premium residential retrofits in Germany and France. REACH substance restrictions and French public procurement recyclate content thresholds favor suppliers with verified scrap-input documentation. Thermal transmittance values below 1.0 W/m²K now command specification preference over steel thermal-break alternatives.
- Steel:Fire-rated configurations retain specification dominance in industrial applications where impact resistance and insurance underwriting requirements converge. Cold-chain logistics facilities across Germany specify steel slats for combined thermal performance and structural durability under automated cycling regimes.
- PVC:Cost-sensitive residential applications in price-competitive markets specify PVC for corrosion resistance and minimal maintenance requirements.
- Fiberglass:Niche coastal and chemical-exposure environments specify fiberglass for salt-air degradation resistance and non-conductive properties.
Steel retains volume leadership in industrial end-uses; aluminum holds the steepest expansion curve in premium residential retrofits.
Operation Type:
Cost tier stratification separates basic manual systems from integrated automated platforms, with electric operation capturing the mid-market consolidation zone.
- Automated:Programmable logic controller integration with BACnet and Modbus protocols commands specification in German and United States warehouse automation projects. E-commerce fulfillment centers prioritize interoperability with building management platforms over standalone durability metrics.
- Electric:Motorized drive systems without full automation integration serve commercial retrofits where power infrastructure exists but control system upgrades are deferred.
- Remote-Controlled:Radio-frequency and infrared handheld systems retain residential preference for convenience without hardwired control infrastructure.
- Manual:Spring-loaded and crank-operated systems concentrate in cost-constrained small commercial installations and legacy residential replacement cycles.
Automated systems are gaining share fastest in logistics infrastructure; manual operation retains residual volume in replacement markets.
End User:
Application-driven specification divergence separates thermal-performance-focused commercial segments from impact-rated industrial requirements.
- Industrial:Warehouse and logistics facilities in Germany, China, and the United States specify fire-rated steel configurations with automated operation. EU F-Gas Regulation compliance for cold-chain logistics accelerates thermally insulated system adoption.
- Commercial:Office and institutional buildings specify aluminum systems with building-integrated photovoltaic convergence for energy-generating facade opportunities.
- Residential:Premium retrofits in France and Germany specify polyurethane-foam-filled aluminum slats for thermal transmittance compliance.
- Retail:Security-focused storefront applications prioritize rapid-deployment motorized systems with anti-lift locking mechanisms.
Industrial end-use retains volume leadership; commercial applications hold the most rapid expansion trajectory.
Installation Type:
Customer type stratification separates standardized exterior deployments from high-margin custom architectural integration projects.
- Exterior:Standardized facade-mounted systems dominate volume production for new construction and replacement cycles across all material categories.
- Integrated:Concealed headbox and guide rail configurations command specification in German premium residential and commercial architectural projects.
- Interior:Room-dividing and secondary security applications specify lighter-duty aluminum or PVC systems without weather exposure requirements.
- Custom:Non-standard dimensions and finish-matched architectural integration projects concentrate in high-end commercial and heritage building retrofits.
Exterior installation retains volume leadership; integrated systems are climbing the fastest in premium construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums for thermally certified systems while Chinese fabricators compete on aluminum extrusion scale. This asymmetry shapes procurement patterns across cold-chain logistics and premium residential retrofits.
Germany
Cold-chain logistics operators in Hamburg and Munich specify steel slat configurations for EU F-Gas Regulation compliance. The KBA enforces construction product standards that extend testing timelines for cross-border contracts. The Rhine-Ruhr industrial corridor concentrates automated shutter integration with warehouse management platforms.
China
E-commerce fulfillment centers in Shenzhen and Hangzhou drive motorized system demand for building management integration. GB standards for building materials establish thermal performance baselines that shape specification protocols. The Yangtze River Delta anchors aluminum extrusion capacity serving domestic and export markets.
United States
Third-party logistics providers in Dallas-Fort Worth and Chicago specify fire-rated steel configurations for insurance underwriting compliance. EPA energy efficiency guidelines influence product selection in climate-controlled facilities. The Southeast distribution corridor accelerates direct contractor procurement from extrusion specialists.
France
Premium residential retrofits in Paris and Lyon specify polyurethane-foam-filled aluminum slats for thermal transmittance below 1.0 W/m²K. Public procurement mandates recyclate content thresholds under EU Green Deal reporting frameworks. The Auvergne-Rhône-Alpes region hosts architectural integration specialists serving heritage building projects.
India
PLI scheme incentives for logistics infrastructure open specification windows for fire-rated industrial systems in Mumbai and Delhi-NCR. The Bureau of Indian Standards enforces building material certifications that extend product launch timelines. The Western Dedicated Freight Corridor drives warehousing expansion across Maharashtra and Gujarat.
Roller Shutter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across material and operation segments. The market structures around captive extrusion capacity, automated drive system integration, and regional installation density. Three archetypes dominate: vertically integrated aluminum specialists, steel-focused industrial fabricators, and automation-technology licensors. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through distribution partnerships.
Among Germany-based manufacturers, Hörmann Group and Alulux GmbH occupy positions within the premium-systems tier, exemplifying captive production capacity and thermal-performance specialization. ASSA ABLOY represents the automation-technology archetype across multiple geographies. Sanwa Holdings Corporation anchors the Asia-Pacific fabrication segment with steel slat production concentration.
| Leading Market Players |
|---|
| Hörmann Group |
| ASSA ABLOY |
| Somfy Group |
| Alulux GmbH |
| Sanwa Holdings Corporation |
| SKB Shutters Corporation Berhad |
| Janus International Group Inc. |
| The Stella Group |
| Ferco Shutters and Seating Systems Pte Ltd |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, as thermally certified systems command substantial premiums over standard configurations while excluding uncertified fabricators from cold-chain logistics procurement. Certification timelines and testing costs compress margin structures for mid-tier players while rewarding incumbents with captive laboratory capacity.
Pricing Analysis
Configured-to-order pricing spreads 40-60% above standard catalog configurations in German and French premium residential markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal transmittance certification and automation integration depth. Cost compression in economy-tier aluminum extrusions is intensifying because of London Metal Exchange volatility and recyclate documentation requirements. Small commercial contractors exhibit highest price sensitivity, while cold-chain logistics operators prioritize thermal performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate aluminum extrusion procurement, while strategic steel coil stockpiles buffer against mill lead-time volatility in fire-rated industrial segments. Manufacturing concentration centers on Germany, China, and the United States for automated drive systems and extruded slats. Raw material dependencies draw from primary aluminum smelters, galvanized steel mills, and East Asian motor suppliers. Single-source vulnerability in programmable logic controller actuation creates procurement risk. Distribution runs through specialized building envelope distributors and direct contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PLC programming talent scarcity constrains after-sales network expansion and threatens service-level agreements for automated system deployments. Engineering capability gaps separate viable competitors from specification-locked incumbents.
For Market Incumbents: Fortify captive extrusion capacity in the Rhine-Ruhr corridor to defend against aluminum price volatility and secure recyclate documentation for French public procurement. Deepen backward integration into motor assembly to reduce East Asian supplier dependency. Prioritize BACnet-Modbus protocol engineering talent acquisition before warehouse automation specifications harden around unified control architectures. For New Entrants and Emerging Players: Lead with photovoltaic-integrated slat systems for German commercial retrofits, where building-integrated photovoltaics convergence creates specification white space absent incumbent lock-in. Target India's PLI-subsidized warehousing corridors with fire-rated steel configurations. Pursue direct contractor procurement relationships in the United States Southeast distribution corridor to bypass established distributor margins. For Investors and Strategic Acquirers: EU Green Deal embodied carbon reporting requirements reshape the acquisition landscape toward suppliers with verified scrap-input documentation and lifecycle assessment capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Monitor French public procurement recyclate thresholds as the inflection signal for portfolio rebalancing toward circular-economy-certified assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Hörmann Group's captive mills insulate margin volatility from LME contract swings. |
| Photovoltaic Slat Integration | Building-integrated photovoltaics convergence opens energy-generating facade specification in German retrofits. |
| Direct Contractor Procurement Channels | United States general contractors bypass distributors to source extruded systems at volume scale. |
| PLC Protocol Engineering Talent Acquisition | BACnet-Modbus integration specialists command premium compensation in warehouse automation projects. |
| Recyclate Documentation Certification | French public procurement mandates scrap-input verification under EU Green Deal frameworks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with warehouse automation directors, building envelope procurement managers, thermal certification laboratory heads, and aftermarket service network operators; and secondary validation through customs trade databases, Construction Products Regulation filing records, KBA and BIS certification registries, and SEC filings of publicly traded building products manufacturers. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material type, operation automation level, end-use application, and installation architecture. CAGRs derived from shipment volume trajectories and average selling price movements within each segment. Forecast inputs incorporated warehouse automation capex cycles, EU F-Gas Regulation compliance deadlines, and aluminum LME forward curves.
Forecasts assume regulatory continuity in EU F-Gas and CE marking regimes; material policy shifts would require re-modeling. Revision becomes warranted when warehouse automation adoption rates or thermal certification timeline extensions cross thresholds that alter supply-demand balance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Fire Hydrants Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Composite Repair Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Global Fencing Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
India Anchors and Grouts Market